
 Asia Big Data Analytics in Education Market | 2026-2036
Asia Big Data Analytics in Education Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Big Data Analytics in Education Market Analytics
ISO/IEC 27001 certification for education data governance is collapsing the vendor landscape into a smaller set of qualified platform providers. Microsoft Corporation leverages its Azure cloud footprint to anchor multi-institutional analytics deployments across East Asian markets. IBM Corporation competes through Watson Education's specialized positioning in predictive student-risk modeling for large university systems. SAP SE differentiates via deep ERP integration that sustains long-term contracts with established higher-education clients.
Asia Big Data Analytics in Education encompasses the collection, processing, and algorithmic analysis of structured and unstructured learning data to generate actionable insights for institutional decision-making, typically operating across distributed cloud architectures with real-time dashboard latency under 500 milliseconds. Its primary commercial purpose is to reduce student attrition while optimizing resource allocation across academic programs. Personalized Learning applications now command the deepest margin pools as institutions prioritize adaptive content delivery over retrospective reporting. Cloud-Based deployment leads volume growth among EdTech Companies seeking elastic infrastructure without capital-intensive server commitments. Predictive Analytics solutions within the Learning Management Systems category are expanding fastest as K-12 Institutions in emerging Asian economies modernize legacy student information infrastructure.
China's MIIT cloud certification requirements and India's BIS data-localization standards are reshaping how foreign vendors architect their education platforms for Asian jurisdictions. The EU AI Act's extraterritorial influence on multinational EdTech providers is forcing alignment of algorithmic transparency standards even for non-European deployments. Stakeholders must monitor whether national regulators in key Asian markets impose mandatory algorithmic auditing for student-facing predictive models before committing to platform architecture decisions.
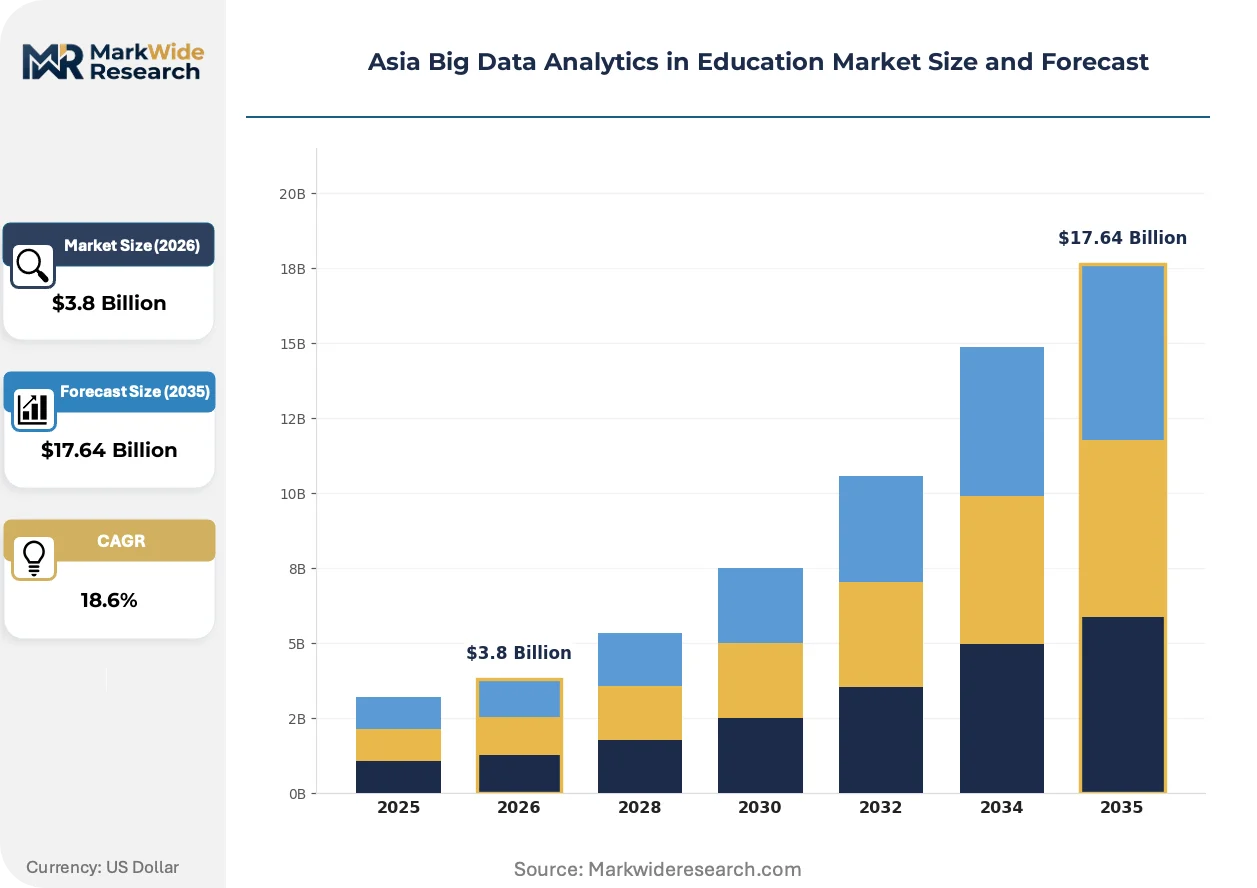
Market Dynamics
China's MIIT cloud certification requirements and India's BIS data-localization standards are compressing vendor qualification timelines and collapsing the competitive landscape into a smaller pool of certified platform providers across Asian education markets.
Growth Catalysts
- Cloud-First Procurement Mandates:National digital education frameworks in multiple Asian jurisdictions are accelerating analytics platform adoption by universities seeking elastic infrastructure without capital-intensive server commitments.
- Federal Skill-Development Directives:India's higher education segment faces mandates forcing universities to deploy data-driven enrollment and placement tracking systems, concentrating demand visibly in this vertical.
- Predictive Analytics Technology Maturation:Real-time dashboard latency under 500 milliseconds now enables algorithmic student-risk modeling that improves retention outcomes across distributed cloud architectures.
Market Restraints
- ISO/IEC 27001 Certification Barriers:Education data governance standards are structurally limiting vendor participation to qualified platform providers with established compliance infrastructure.
- Input Cost Concentration in Cloud Infrastructure:Reliance on hyperscale cloud providers for compute and storage creates supply concentration risk in East Asian data center markets.
- Algorithmic Transparency Requirements:The EU AI Act's extraterritorial influence creates regulatory friction for multinational EdTech providers deploying student-facing predictive models in Asian jurisdictions.
Strategic Opportunities
- K-12 Infrastructure Modernization:Predictive analytics solutions within Learning Management Systems categories are expanding fastest as emerging Asian economies modernize legacy student information infrastructure.
- Adaptive Content Delivery Convergence:Integration of machine learning with learning management platforms is opening margin pools in personalized learning applications prioritized over retrospective reporting.
- ERP Integration Channel Innovation:Deep enterprise resource planning integration capabilities are sustaining long-term contract opportunities with established higher-education clients seeking unified data environments.
Industry Challenges
- Algorithmic Auditing Skill Shortages:Universities face operational gaps in technical capacity to validate student-facing predictive models for bias and accuracy before deployment.
- Legacy System Integration Complexity:Higher education institutions struggle with data migration friction when connecting modern analytics platforms to decades-old student information infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Big Data Analytics in Education Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Performance Tracking, Personalized Learning, Enrollment Management, Curriculum Development End User: K-12 Institutions, Higher Education, Corporate Training, EdTech Companies Deployment: On-Premises, Cloud-Based, Hybrid, Virtual Learning Environments Solution: Learning Management Systems, Data Visualization Tools, Predictive Analytics, Student Information Systems |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, SAS Institute, Tableau Software, TIBCO Software, Alteryx, Inc., Blackboard, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Big Data Analytics in Education Market Evolving Landscape
Algorithmic transparency requirements and adaptive learning technologies are actively restructuring how education institutions procure, deploy, and validate analytics platforms across Asian markets.
Edge computing architectures for campus-level data processing are miniaturizing analytics deployment footprints. K-12 institutions in Southeast Asia are adopting these distributed systems to reduce latency for real-time learning interventions. This technology compression is enabling analytics capabilities in previously connectivity-constrained environments without full cloud dependency.
India's BIS data-localization standards are mandating sovereign storage of student records. Foreign platform vendors must rearchitect infrastructure to maintain market access. Higher education procurement teams in Indian states are prioritizing domestic data residency certifications in vendor selection criteria.
Subscription-based platform licensing is displacing perpetual software purchases across Asian university systems. Chief information officers in Chinese provincial universities favor operational expenditure models that align costs with enrollment volatility. This financial restructuring is most visible in East Asian markets where capital budget constraints intersect with cloud-migration timelines.
Asia Big Data Analytics in Education Market Segmentation
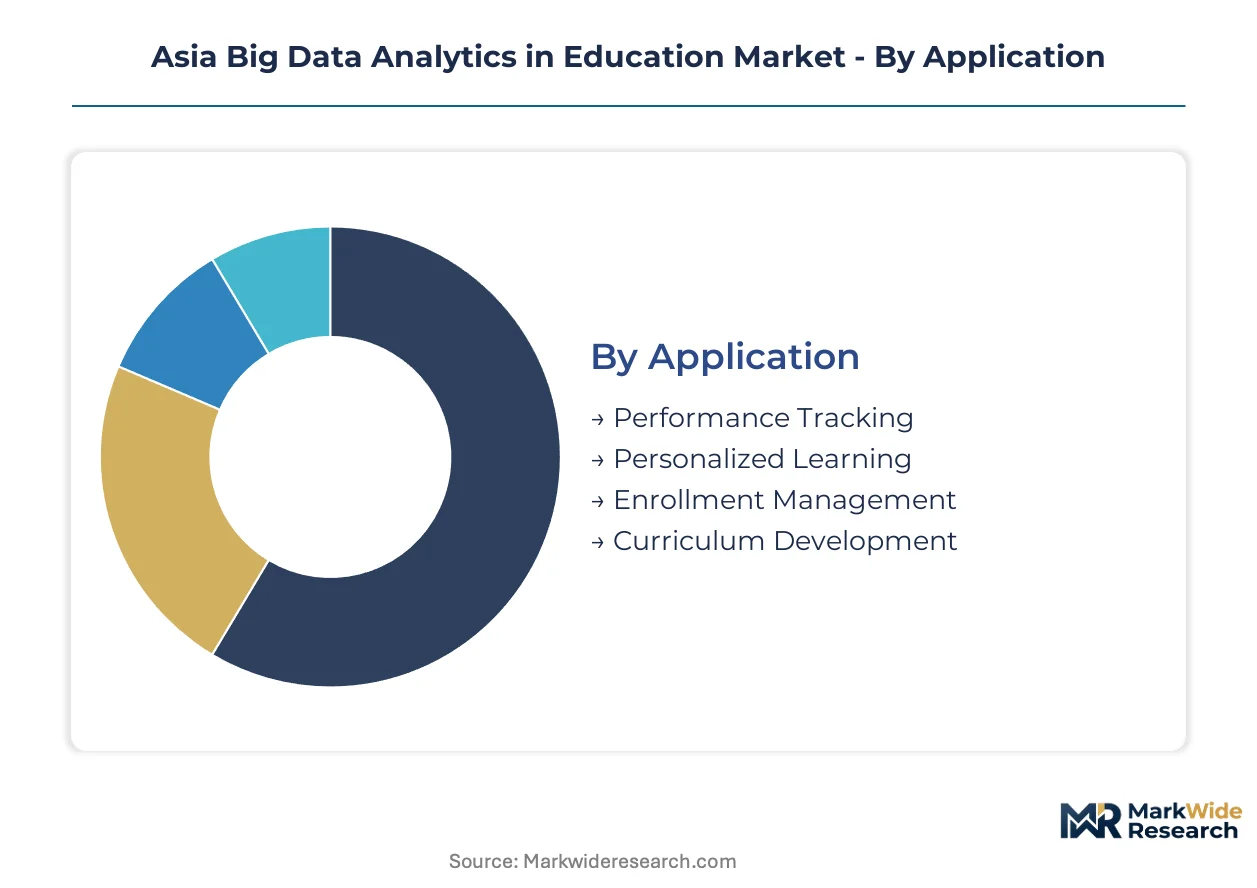
Segmentation in Asia's education analytics market reveals how procurement priorities diverge across institutional maturity levels and regulatory environments. Each dimension exposes distinct margin structures and vendor qualification requirements.
Application:
Regulatory differentiation across Asian jurisdictions is segmenting application demand by data sensitivity tiers, with student-facing predictive functions attracting stricter compliance scrutiny than administrative tools.
- Performance Tracking:Dashboards aggregate assessment metrics, attendance patterns, and learning velocity indicators into unified institutional views. Chinese provincial universities under MIIT cloud mandates concentrate procurement here, driven by federal mandates for transparent academic outcome reporting.
- Personalized Learning:Adaptive algorithms adjust content difficulty and pacing based on real-time learner interaction data. India's higher education segment concentrates visible demand as federal skill-development directives force adoption of individualized placement preparation pathways.
- Enrollment Management:Predictive models forecast applicant yield and optimize financial aid allocation.
- Curriculum Development:Text mining and outcome analysis identify skill gaps between graduate competencies and employer requirements.
Established volume favors Performance Tracking; emerging adoption favors Personalized Learning.
End User:
Customer type determines pricing elasticity and contract duration, with multi-year enterprise agreements dominating higher education while K-12 procurement cycles compress under annual budget constraints.
- K-12 Institutions:Legacy student information infrastructure modernization is driving fastest solution uptake across Southeast Asian emerging economies. BIS data-localization standards in India are forcing infrastructure rearchitecture for foreign vendors seeking access to this expanding segment.
- Higher Education:Research-intensive universities deploy comprehensive analytics stacks spanning research output tracking to alumni engagement. Chinese provincial procurement teams favor subscription licensing that aligns operational expenditure with enrollment volatility.
- Corporate Training:Workforce reskilling platforms integrate with enterprise HR systems for competency gap analysis.
- EdTech Companies:Platform providers require elastic cloud infrastructure without capital-intensive server commitments.
Revenue concentration sits with Higher Education; steepest expansion trajectory belongs to K-12 Institutions.
Deployment:
Cost tier stratification separates capital-constrained institutions from those prioritizing data sovereignty and latency performance.
- Cloud-Based:Elastic infrastructure scales compute and storage with enrollment fluctuations. EdTech Companies across East Asian markets lead volume growth here, avoiding upfront server investments while maintaining sub-500 millisecond dashboard latency through distributed architectures.
- Hybrid:Sensitive student records remain on-premises while analytics processing leverages cloud elasticity. Indian higher education procurement teams prioritize this architecture to satisfy BIS data-localization requirements without sacrificing computational flexibility.
- On-Premises:Complete institutional control over hardware and data residency.
- Virtual Learning Environments:Integrated platforms combining content delivery with embedded analytics capabilities.
Volume leadership belongs to Cloud-Based; compliance-driven substitution favors Hybrid.
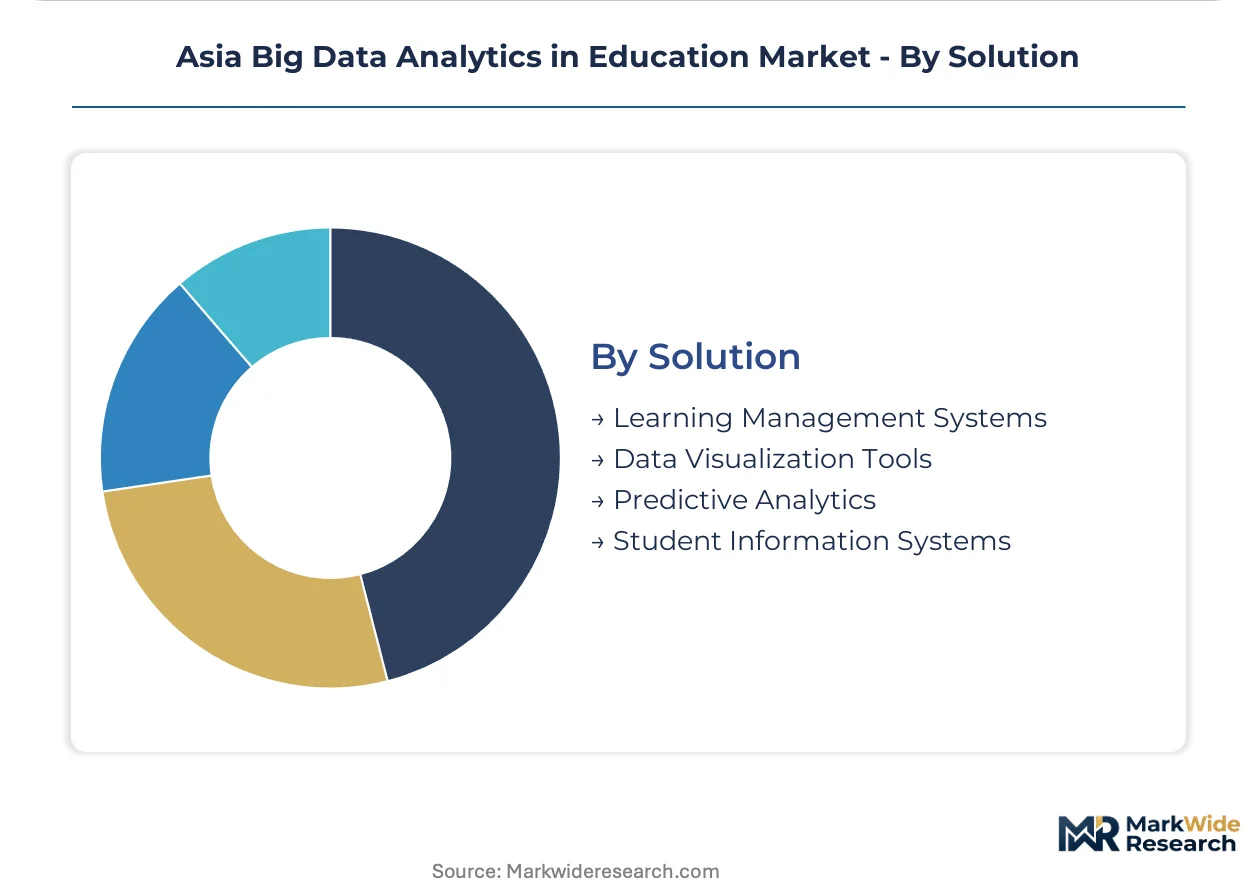
Solution:
Technology maturity and integration depth determine margin capture, with standalone visualization tools commoditizing fastest.
- Predictive Analytics:Algorithmic student-risk modeling identifies at-risk learners before withdrawal triggers. Solutions expanding fastest as K-12 Institutions modernize legacy infrastructure across emerging Asian economies, with real-time intervention capabilities commanding premium pricing.
- Learning Management Systems:Core instructional platforms with embedded analytics for content engagement tracking. Deep ERP integration capabilities sustain long-term contracts with established higher-education clients seeking unified data environments.
- Data Visualization Tools:Standalone dashboard and reporting interfaces for non-technical administrators.
- Student Information Systems:Administrative databases serving as foundational data sources for downstream analytics.
Margin depth concentrates in Predictive Analytics; contract duration extends longest for Learning Management Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Guangzhou-Shenzhen-Hong Kong Express Rail Link and submarine cable landing stations at Chung Hom Kok anchor Asia's education data infrastructure, compressing latency for real-time analytics deployments across East Asian university clusters.
China
Provincial universities in Jiangsu and Zhejiang are accelerating procurement of MIIT-certified cloud platforms for student retention analytics. MIIT cloud certification requirements are collapsing vendor qualification timelines to under 90 days for qualified providers. Shanghai's Yangpu district hosts the densest concentration of EdTech R&D facilities, where edge computing pilots for campus-level data processing are operationalizing sub-500 millisecond dashboard response times.
India
Federal skill-development mandates are forcing universities in Maharashtra and Karnataka to deploy data-driven enrollment tracking systems with placement outcome visibility. BIS data-localization standards are mandating sovereign storage of student records, compelling foreign platform vendors to rearchitect infrastructure for domestic data residency. Hyderabad's HITEC City cluster concentrates the highest density of analytics implementation partners serving state universities under digital campus initiatives.
Japan
Research-intensive universities in Kanto are deploying comprehensive analytics stacks spanning research output tracking to alumni engagement. METI guidelines on educational data governance are shaping procurement criteria for algorithmic transparency in student-facing predictive models. Tokyo's Shibuya district anchors the regional headquarters concentration for multinational platform vendors seeking university system contracts.
South Korea
K-12 institutions in Seoul Capital Area are modernizing legacy student information infrastructure with predictive analytics modules. MFDS-aligned data security frameworks are influencing procurement specifications for cloud-based learning management platforms. Pangyo Techno Valley hosts the dominant cluster of domestic EdTech developers integrating real-time intervention capabilities for personalized learning pathways.
Singapore
Polytechnic institutions are prioritizing adaptive content delivery platforms with embedded competency gap analysis for workforce reskilling programs. The country's national digital education framework mandates cloud-first procurement, compressing vendor selection cycles for analytics deployments. One-North district concentrates the regional headquarters operations for platform providers serving Southeast Asian expansion strategies.
Asia Big Data Analytics in Education Market Competitive Landscape
Listed leaders compete with private specialists across certification-qualified platform tiers, with ISO/IEC 27001 compliance collapsing the vendor landscape into a smaller pool of qualified providers. The competitive structure stratifies around hyperscale cloud anchors, specialized predictive analytics developers, and ERP-integrated platform incumbents. Three archetypes dominate: cloud infrastructure gatekeepers leveraging distributed data center footprints, risk-modeling specialists targeting large university systems, and enterprise software incumbents sustaining long-term contracts through deep system integration. M&A activity concentrates on acquiring algorithmic auditing capabilities, while strategic partnerships with hyperscale cloud providers dominate market access strategies.
Within the cloud infrastructure tier, Microsoft Corporation and IBM Corporation exemplify contrasting positioning approaches, with the former anchoring multi-institutional deployments through Azure cloud certification advantages and the latter occupying a specialized niche in predictive student-risk modeling. SAP SE represents the ERP-integrated incumbent archetype, sustaining contract duration through unified data environment value propositions. These three companies illustrate how vendor qualification requirements are reshaping competitive positioning across Asian education markets.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| SAS Institute |
| Tableau Software |
| TIBCO Software |
| Alteryx, Inc. |
| Blackboard, Inc. |
| Others |
Value Network & Pricing Analysis
Subscription-based capacity reservation contracts lock in multi-year cloud infrastructure access for Asian universities while fixing operational expenditure visibility against enrollment volatility. Chinese provincial procurement teams favor these structures to align MIIT-certified platform costs with federal digital education mandates.
Pricing Analysis
Certification level (ISO/IEC 27001 vs non-certified) creates the primary spread between qualified platform providers and excluded vendors. Three-tier pricing structure across premium certified, standard compliant, and economy non-compliant levels stratifies the vendor landscape. Pricing pressure stems from hyperscale cloud provider concentration in East Asian data centers compressing compute margins. K-12 institutions exhibit highest price sensitivity due to annual budget constraints, while research-intensive universities prioritize compliance over cost.
Supply Chain Analysis
Just-in-time provisioning dominates cloud-native deployments as EdTech companies scale compute elastically with enrollment fluctuations without strategic stockpiling. Supply concentrates in China, India, and Singapore for hyperscale data center capacity. Raw material dependencies include specialized GPUs for machine learning workloads, sovereign-certified storage hardware for BIS compliance, and sub-500 millisecond latency networking equipment. Single-source vulnerability runs through MIIT cloud certification bottlenecks. Distribution runs through direct enterprise sales teams and systems integrators in HITEC City and One-North clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source analytics frameworks and low-code predictive modeling tools threaten incumbent platform providers by democratizing algorithmic capabilities previously locked behind enterprise contracts. Substitution risk intensifies as Indian and Southeast Asian universities face budget constraints.
For Market Incumbents: Consolidate algorithmic auditing capabilities through targeted capability acquisitions to close operational gaps universities face in validating student-facing predictive models. Deepen backward integration into sovereign cloud infrastructure to satisfy India's BIS data-localization requirements and China's MIIT certification demands, defending contract duration against domestic challengers.
For New Entrants and Emerging Players: Algorithmic transparency tooling for EU AI Act compliance represents a critical service-layer gap where multinational incumbents under-serve Asian jurisdictions. Target K-12 infrastructure modernization across Southeast Asian emerging economies as the most penetrable vertical. Lead with edge computing pilots for campus-level data processing to reduce latency without full cloud dependency.
For Investors and Strategic Acquirers: Specialized predictive analytics developers with ISO/IEC 27001 pre-certification and existing MIIT cloud compliance offer the strongest acquisition target archetype for platform consolidation plays. Long-term viability hinges on regulatory alignment across multiple Asian jurisdictions rather than single-market dominance. Watch for mandatory algorithmic auditing regulations crossing implementation thresholds as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Cloud Certification Acquisition | Compresses vendor qualification timelines below 90 days for Chinese provincial university contracts. |
| Algorithmic Auditing Capability Buildout | Closes operational gaps in university technical capacity to validate predictive models for bias. |
| Edge Computing Architecture Deployment | Enables sub-500 millisecond dashboard latency in connectivity-constrained Southeast Asian K-12 environments. |
| BIS Data-Localization Infrastructure | Mandates sovereign storage rearchitecture to maintain Indian higher education market access. |
| ERP Integration Channel Partnership | Sustains long-term contract duration through unified data environment value propositions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing chief information officers at Chinese provincial universities, Indian state procurement leads, EdTech platform engineers, and systems integration specialists in Hyderabad and Singapore. Secondary validation drew from MIIT cloud certification registries, BIS data-localization compliance filings, hyperscaler capex disclosures, and federal skill-development mandate documentation. Bottom-up enrollment tracking system deployments were triangulated against top-down national digital education framework commitments.
Across the analysis window, the forecasting framework modeled deployment architecture, institutional tier, application function, and regulatory jurisdiction as core segmentation dimensions. CAGRs were derived from enrollment volatility patterns, cloud procurement cycle compression, and predictive analytics technology maturation curves. Industry-specific inputs included real-time dashboard latency thresholds and ISO/IEC 27001 certification penetration rates.
Forecasts assume regulatory continuity in China's MIIT certification regime and India's BIS data-localization standards; material policy shifts would require re-modeling. Specific risks include mandatory algorithmic auditing mandates and extraterritorial EU AI Act enforcement. Revision becomes warranted when sovereign storage requirements cross implementation thresholds in additional Asian jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Smart Education System Market
Educational Technology (EdTech)
Global AI in Education Market
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
Digital Classroom Market
Educational Technology (EdTech)
Higher Education Technology Market
Educational Technology (EdTech)
North America Digital Education Market
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
Global Gamification in Education Market
Educational Technology (EdTech)
Global Smart Classroom Market
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
Virtual Schools Market
Educational Technology (EdTech)
Student Response System Market
Educational Technology (EdTech)
Digital Badges Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
E Learning Virtual Reality Market