
 Educational Consulting and Training Market | 2026-2036
Educational Consulting and Training Market Size, Share, and Industry Trends Forecast 2026-2036
Educational Consulting and Training Market Insights
The educational consulting and training industry is decoupling into two distinct value layers: high-touch strategic advisory engagements priced for transformation outcomes versus commoditized content delivery competing on cost per learner. Deloitte leverages its institutional assessment practice to anchor premium contracts with university systems undergoing accreditation overhauls. Pearson competes through curriculum development specialization, while Huron Consulting Group dominates strategic planning mandates for distressed educational nonprofits seeking operational turnaround.
Educational consulting and training encompasses advisory services and instructional programs designed to improve institutional performance, learner outcomes, and workforce competency through evidence-based methodologies, structured pedagogy, and technology-mediated delivery mechanisms. The field applies psychometric frameworks, competency mapping, and learning management system integration to align human capital development with organizational objectives. Curriculum development and teacher training command the deepest margin pools as public institutions face accountability mandates, while online courses and hybrid training represent the fastest-expanding delivery mode as asynchronous platforms reduce marginal cost per participant. Corporate clients and K-12 schools generate divergent demand profiles, with the former prioritizing measurable skill acquisition and the latter emphasizing compliance-driven certification.
The US Department of Education, India's National Council for Teacher Education, and China's Ministry of Education collectively shape market access through accreditation requirements, educator certification standards, and cross-border program approval protocols that filter which providers qualify for institutional contracts. ISO 29993 for learning services and the European Training Foundation's quality benchmarks further constrain product design for multinational delivery. Stakeholders must monitor how generative AI alters credentialing authority and whether regulatory bodies recalibrate oversight frameworks to address algorithmic assessment validity.
Market Dynamics
Artificial intelligence-powered adaptive learning platforms are compressing pricing power for standardized content delivery while amplifying premiums for outcome-guaranteed strategic advisory engagements.
Growth Catalysts
- Workforce Upskilling Mandates:Technology firms and financial services companies are expanding service contracts for competency-based training programs tied to measurable productivity gains.
- ISO 29993 Certification Standards:Quality benchmarks for learning services are filtering provider eligibility for multinational institutional contracts, advantaging accredited consultancies.
- Public-Private Partnership Scaling:The United States, China, and India are accelerating educator certification and institutional transformation programs through blended funding mechanisms.
Market Restraints
- Algorithmic Assessment Validity Gaps:Regulatory bodies have not recalibrated oversight frameworks to address generative AI credentialing authority, creating compliance uncertainty.
- Content Commoditization Pressure:Asynchronous platform proliferation is eroding marginal cost structures for standardized curriculum delivery.
- Cross-Border Program Approval Friction:China's Ministry of Education maintains stringent protocols that delay multinational provider market entry timelines.
Strategic Opportunities
- Distressed Institutional Turnaround:Operational restructuring mandates for educational nonprofits represent underserved white space for strategic planning specialists.
- AI-Human Hybrid Delivery Convergence:Platforms combining adaptive algorithms with high-touch coaching are capturing premium pricing in corporate learning segments.
- European Training Foundation Benchmark Alignment:Quality standard harmonization creates channel expansion pathways for ISO-compliant providers into EU institutional markets.
Industry Challenges
- Psychometric Framework Integration:Learning management system vendors face complexity aligning competency mapping tools with legacy institutional assessment infrastructure.
- Accreditation Overhaul Timeline Compression:University systems undergoing simultaneous curriculum redesign and certification recalibration strain implementation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Educational Consulting and Training Market |
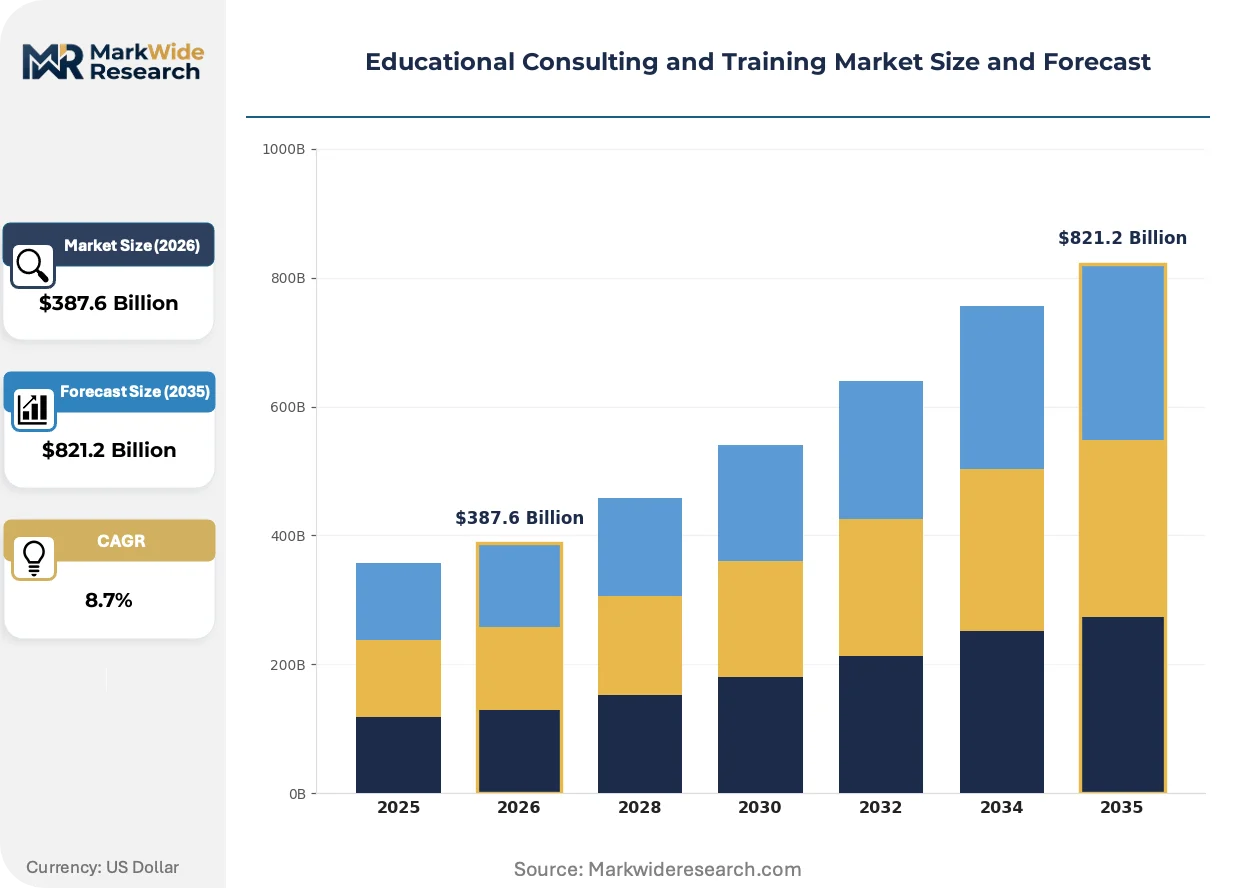
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
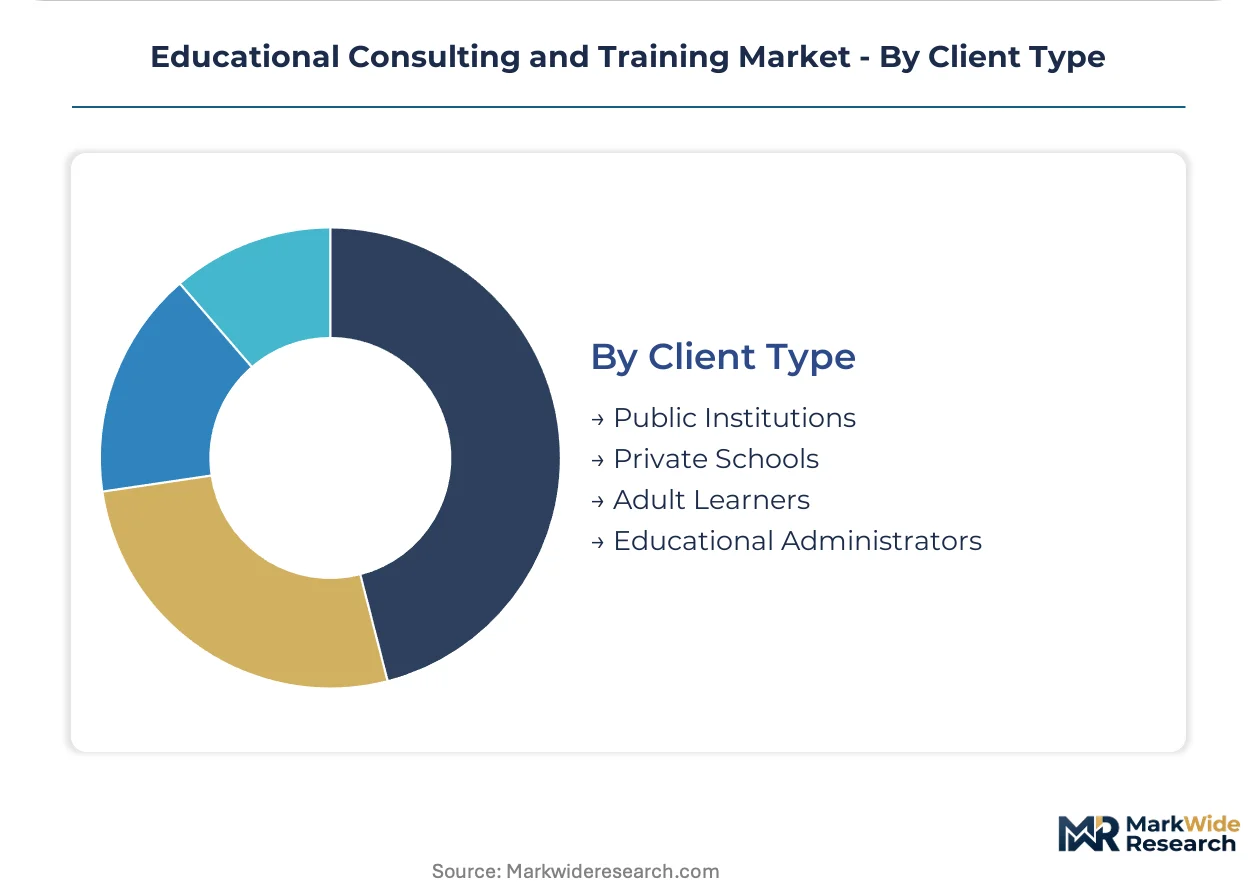
| Segmentation | Service Type: Curriculum Development, Teacher Training, Institutional Assessment, Strategic Planning End User: K-12 Schools, Universities, Educational Nonprofits, Corporate Clients Delivery Mode: In-Person Workshops, Online Courses, Hybrid Training, Consulting Sessions Client Type: Public Institutions, Private Schools, Adult Learners, Educational Administrators |
| Companies Covered | Accenture, Deloitte, PwC, McKinsey & Company, Boston Consulting Group, Ernst & Young, KPMG, Pearson, Huron Consulting Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Educational Consulting and Training Market Trends and Innovations
Delivery mechanisms are bifurcating between hyper-personalized AI-mediated pathways and intensive human-facilitated transformation engagements, reshaping how training outcomes get measured and priced.
Adaptive learning engines are unifying diagnostic assessment, content sequencing, and progress monitoring into continuous feedback loops. Corporate learning and development teams at technology firms are deploying these platforms for technical skill acquisition at scale. The technology is unifying previously siloed training functions into integrated competency development systems that compress time-to-proficiency metrics.
The EU AI Act's risk classification framework for educational algorithms is forcing providers to document automated decision-making transparency. EdTech platforms deploying predictive analytics for learner progression now face conformity assessment obligations. European Training Foundation quality benchmarks are tightening alignment requirements for AI-mediated credentialing programs.
Enterprise buyers are consolidating vendor relationships around outcome-guaranteed performance contracts rather than per-seat licensing. Technology and financial services procurement teams now demand measurable productivity lift clauses in training service agreements. This shift is most visible in United States corporate learning budgets, where CFO oversight of learning and development spend has intensified accountability requirements.
Educational Consulting and Training Market Segmentation
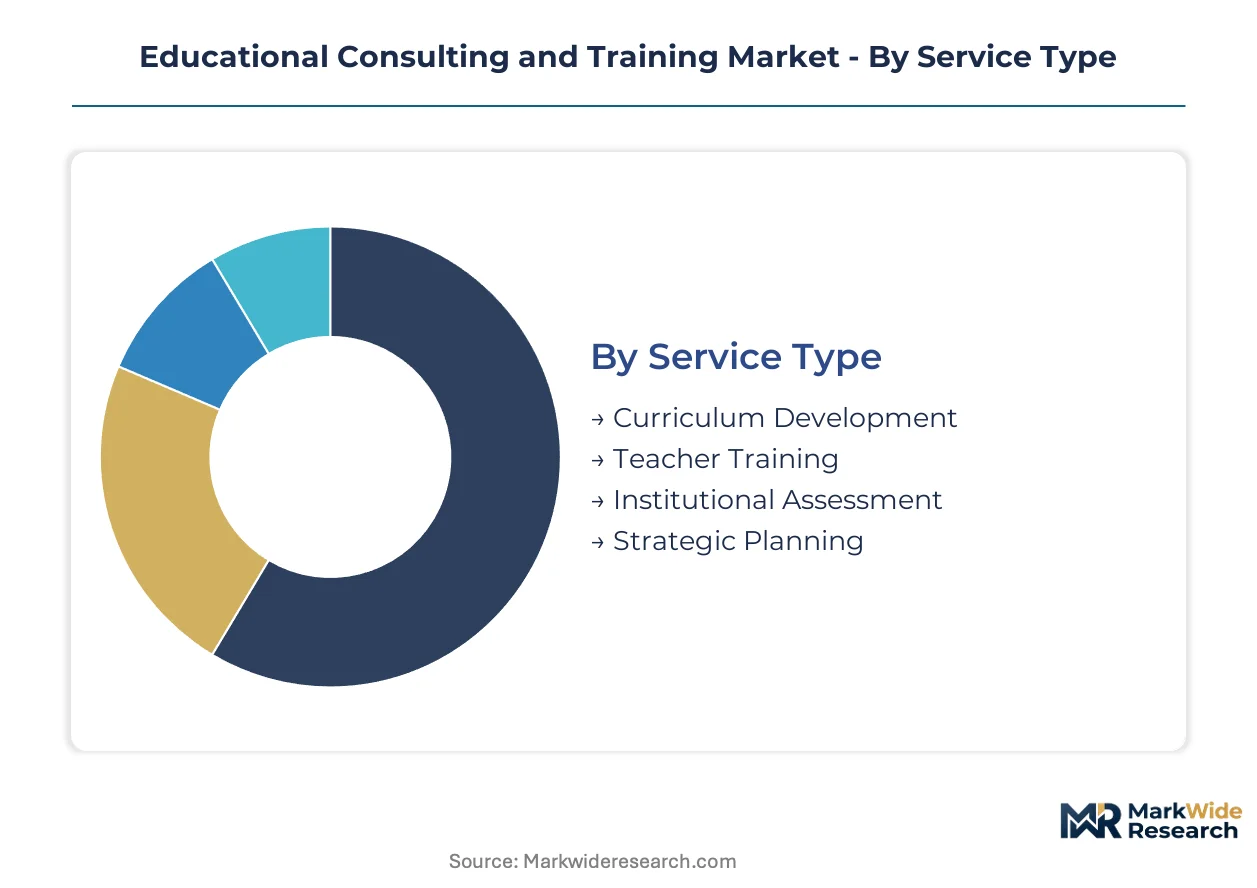
Educational consulting and training providers structure offerings around distinct procurement patterns that separate compliance-driven institutional buyers from outcome-focused corporate clients. Service architecture, delivery modality, and client governance type each create independent pricing corridors and margin profiles.
Service Type:
Buyer selection pivots on whether the engagement targets immediate workforce competency gaps or long-term institutional transformation mandates.
- Curriculum Development:Structured instructional design services align learning objectives with accreditation standards and workforce competency frameworks. Demand clusters at public K-12 districts facing state accountability overhauls and universities redesigning degree pathways for employability metrics.
- Teacher Training:Certification preparation and pedagogical upskilling programs integrate evidence-based instruction methods with classroom technology deployment. India's National Council for Teacher Education and China's Ministry of Education are scaling public-private delivery partnerships, compressing implementation timelines for credentialing at scale.
- Institutional Assessment:Accreditation readiness audits and performance benchmarking against ISO 29993 learning service standards.
- Strategic Planning:Operational turnaround and long-range financial sustainability planning for distressed educational nonprofits.
Curriculum Development leads on scale; Teacher Training leads on momentum.
End User:
Volume concentration tracks divergent budget authority structures, with corporate learning and development teams commanding discretionary spend versus public institutions navigating appropriations cycles.
- K-12 Schools:District-level procurement of compliance-focused training tied to federal and state educator certification mandates. United States Title I funding streams and state department of education accountability frameworks shape contract timing and scope.
- Universities:Accreditation overhaul and curriculum redesign engagements for research and teaching institutions. Demand intensifies where regional accreditors impose simultaneous assessment and competency-mapping requirements.
- Educational Nonprofits:Operational restructuring and board governance advisory for tuition-dependent institutions facing enrollment pressures.
- Corporate Clients:Competency-based technical training with productivity-guaranteed performance clauses. Technology firms and financial services companies in the United States are consolidating vendor relationships around outcome-based contracts.
Corporate Clients expand most quickly; K-12 Schools anchor contract volume.
Delivery Mode:
Cost per learner and time-to-proficiency metrics separate synchronous high-touch formats from asynchronous scale plays.
- In-Person Workshops:Intensive facilitator-led sessions for complex skill transfer and leadership development cohorts. Premium pricing persists where peer interaction and real-time coaching accelerate behavioral change.
- Online Courses:Self-paced modular content with automated assessment and progress tracking. Asynchronous platforms erode marginal delivery costs while compressing pricing power for standardized curriculum.
- Hybrid Training:Blended synchronous and asynchronous pathways combining adaptive content sequencing with scheduled coaching touchpoints.
- Consulting Sessions:Advisory engagements delivered through scheduled video or on-site interactions for strategic planning mandates.
Online Courses dominate learner volume; Hybrid Training captures the steepest expansion trajectory.
Client Type:
Governance structure and procurement authority determine contract complexity and payment risk profiles.
- Public Institutions:Government-funded schools and universities subject to competitive bidding and appropriations-dependent payment schedules. United States Department of Education grant programs and state procurement codes filter vendor eligibility.
- Private Schools:Independent and parochial institutions with board-governed budget authority and faster decision cycles.
- Adult Learners:Individual professionals purchasing credentialing and upskilling through direct-to-consumer channels or employer tuition assistance.
- Educational Administrators:Superintendents, provosts, and nonprofit executives commissioning strategic advisory for institutional transformation.
Public Institutions anchor aggregate contract value; Adult Learners are gaining share fastest through direct digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce upskilling mandates and educator certification programs concentrate procurement activity in the United States, China, India, Germany, and the United Kingdom. These geographies host the deepest corporate learning budgets and most active public-private partnership frameworks.
United States
Corporate learning and development teams at technology firms and financial services companies are consolidating vendor relationships around outcome-based contracts. The US Department of Education shapes market access through Title I funding streams and competitive bidding requirements for institutional contracts. Greater Boston and Silicon Valley anchor demand for AI-human hybrid training platforms.
China
Public-private partnerships for educator certification are scaling rapidly through blended funding mechanisms. The Ministry of Education maintains stringent cross-border program approval protocols that filter multinational provider eligibility. Yangtze River Delta cities concentrate procurement for institutional transformation mandates.
India
The National Council for Teacher Education is accelerating credentialing programs through compressed implementation timelines. State-level procurement codes and central government appropriations cycles shape contract timing for K-12 districts. Karnataka and Maharashtra host the deepest concentration of curriculum development demand.
Germany
Industrial apprenticeship restructuring and dual education system modernization are expanding service contracts for competency-based training. The European Training Foundation's quality benchmarks constrain product design for multinational delivery. Bavaria and Baden-Württemberg anchor demand for ISO 29993-compliant learning services.
United Kingdom
University systems undergoing simultaneous accreditation overhaul and curriculum redesign are straining implementation capacity. Office for Students regulatory frameworks and regional accreditor mandates shape contract scope for institutional assessment services. London and the Southeast concentrate strategic advisory demand for distressed educational nonprofits.
Educational Consulting and Training Market Competitive Landscape
Top-tier vendors anchor outcome-guaranteed strategic advisory engagements, while mid-tier specialists compete on curriculum development specialization and regional accreditation expertise. The vendor base stratifies across three strategic archetypes: global professional services networks with institutional assessment practices, specialized curriculum developers with psychometric framework integration capabilities, and turnaround-focused consultancies targeting distressed educational nonprofits. Competitive moves concentrate on M&A for adaptive learning technology assets and strategic partnerships with learning management system vendors.
Among global professional services networks, Deloitte, Accenture, and McKinsey & Company exemplify the premium advisory archetype through their institutional transformation practices. Pearson occupies a position representing specialized curriculum developers with deep psychometric and assessment expertise. Huron Consulting Group anchors the distressed institutional turnaround segment. These named entities collectively illustrate how competitive positioning separates high-touch strategic mandates from commoditized content delivery.
| Leading Market Players |
|---|
| Accenture |
| Deloitte |
| PwC |
| McKinsey & Company |
| Boston Consulting Group |
| Ernst & Young |
| KPMG |
| Pearson |
| Huron Consulting Group |
| Others |
Pricing and Supply Chain Analysis
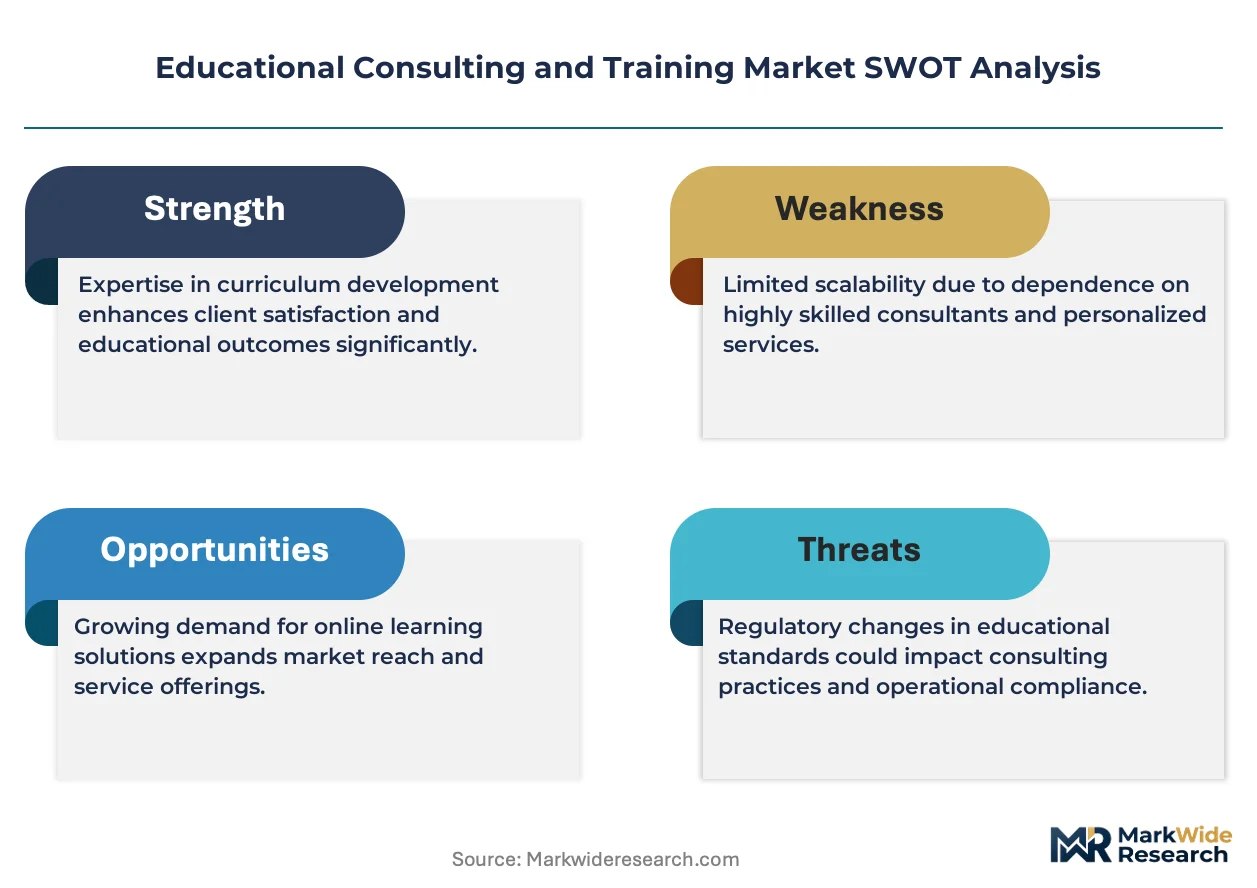
ISO 29993 learning service standards gate qualified supply and premium-tier pricing access by filtering which consultancies qualify for multinational institutional contracts, compressing margins for non-accredited providers while amplifying premiums for certified advisory practices in the United States, China, and India.
Pricing Analysis
The bundled-vs-unbundled service split separates outcome-guaranteed strategic advisory engagements from commoditized content delivery. Project-based contracts with productivity-guaranteed performance clauses command premiums in corporate learning segments, while per-seat licensing for asynchronous online courses faces downward pressure from platform proliferation. Price differentiation rests on ISO 29993 certification tier and customization depth. Technology firms and financial services companies show lowest price sensitivity; K-12 districts navigating appropriations cycles exhibit highest.
Supply Chain Analysis
Certification and qualification gating concentrates qualified supplier networks in the United States, the United Kingdom, and Germany where ISO 29993-accredited consultancies and psychometric framework developers anchor. Raw material inputs draw from learning management system platforms, adaptive learning engines, and subject-matter expert networks. Single-source vulnerability runs through proprietary AI assessment algorithms. Distribution runs through direct enterprise sales teams, channel partnerships with learning management system vendors, and public procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: corporate learning budgets in the United States command outcome-based premiums three to five times higher than compliance-driven public procurement in India, creating margin capture opportunities for providers with cross-border delivery infrastructure.
For Market Incumbents: Acquire adaptive learning technology assets to anchor AI-human hybrid delivery capabilities. Defensive consolidation should prioritize learning management system integration partnerships that lock out emerging platform-native entrants, while certification investment in EU AI Act compliance creates regulatory moats against mid-tier specialists lacking conformity assessment resources. For New Entrants and Emerging Players: Enter via distressed institutional turnaround mandates in the United Kingdom and United States where implementation capacity constraints at university systems create white-space for operational restructuring specialists. Target educational nonprofits facing enrollment pressures with board governance advisory, leveraging direct-to-administrator digital channels that bypass incumbent RFP processes. For Investors and Strategic Acquirers: Roll-up economics work for specialized curriculum developers with psychometric framework integration capabilities because accreditation overhaul timelines compress implementation windows and favor scaled providers with simultaneous curriculum redesign and competency-mapping capacity. Watch for inflection when generative AI credentialing authority triggers regulatory recalibration of oversight frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Adaptive Learning Technology | Pearson and mid-tier specialists compete for AI assessment engines that unify diagnostic and progress monitoring. |
| ISO 29993 Certification Investment | Accreditation gates multinational contracts in Germany and creates procurement eligibility in EU institutional markets. |
| Public-Private Partnership Formation | India's National Council for Teacher Education and China's Ministry of Education compress implementation timelines for credentialing at scale. |
| AI-Human Hybrid Platform Launch | Corporate learning teams at technology firms pay premiums for adaptive algorithms combined with scheduled coaching touchpoints. |
| Distressed Institutional Turnaround Mandate | Huron Consulting Group anchors demand from tuition-dependent nonprofits in London and the Southeast facing enrollment pressures. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with chief learning officers, university provosts, state procurement officers, and curriculum directors with secondary validation against US Department of Education grant databases, ISO certification registries, European Training Foundation quality benchmark publications, and corporate learning and development budget disclosures. Bottom-up service provider revenue analysis and top-down market sizing triangulated volume estimates.
Comparable historical performance anchored projection assumptions across the modeling period, with segmentation dimensions including service type, end user category, delivery mode, and client governance structure. CAGRs derived from fitted growth curves applied to baseline contract value data, incorporating inputs from public-private partnership scaling announcements and workforce upskilling mandate disclosures.
Inputs from accreditation bodies and corporate procurement teams were available through the study window; gaps in algorithmic assessment validity regulatory guidance introduce uncertainty bands around AI-mediated credentialing adoption curves. Forecasts reflect documented assumptions on partnership scaling velocity and compliance timeline compression. A model refresh is warranted upon material change in EU AI Act enforcement posture or ISO 29993 recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Corporate Training and Talent Development
Corporate Training Services Market
Corporate Training and Talent Development
Asia-Pacific Management Consulting Services Market
Corporate Training and Talent Development
Integrated Talent Management Market
Corporate Training and Talent Development
France Outplacement Services Market
Corporate Training and Talent Development
Europe Executive Search (Headhunting) Market
Corporate Training and Talent Development
Executive Coaching Certification Market
Corporate Training and Talent Development
Corporate Training Software Market
Corporate Training and Talent Development
Corporate eLearning Market
Corporate Training and Talent Development
Asia-Pacific Corporate Training Market
Corporate Training and Talent Development
Asia Pacific HR Professional Services Market
Corporate Training and Talent Development
Talent As a Service Market
Corporate Training and Talent Development
Middle East and Africa Management Consulting Services Market
Corporate Training and Talent Development
Private Tutoring Market
Corporate Training and Talent Development
Corporate Workforce Development Training Market
Corporate Training and Talent Development
Competency-Based Education Spending Market
Corporate Training and Talent Development
Frontline Workers Training Market