
 Global Mechatronics and Robotics Courses Market | 2026-2036
Global Mechatronics and Robotics Courses Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mechatronics and Robotics Courses Market Outlook
Industrial robotics technician pipelines is bifurcating between legacy automation maintenance and AI-integrated systems engineering, creating parallel certification tracks with uneven employer recognition. ABB leverages its robot OEM installed base to anchor proprietary training ecosystems across Nordic manufacturing clusters. Bosch Rexroth competes through hydraulics-to-robotics curriculum bridges that sustain German Mittelstand loyalty. KUKA Robotics dominates automotive-sector course placements by bundling certification with robot lease agreements.
Mechatronics and robotics courses integrate mechanical engineering, electronics, control systems, and computer science into interdisciplinary curricula centered on programmable logic controllers, servo motor tuning, and sensor fusion architectures. These programs prepare technicians and engineers to deploy, maintain, and optimize automated production lines, autonomous guided vehicles, and collaborative robot workstations. Online course type offerings are capturing the fastest enrollment velocity as manufacturing employers adopt asynchronous reskilling models for shift workers. Advanced level of instruction segments carry the deepest margin pools due to vendor-specific certification premiums from equipment manufacturers. Hybrid delivery mode is gaining structural share where hands-on robot access requires physical lab proximity yet theory modules scale digitally.
ISO 10218 safety standards and IEC 61508 functional safety frameworks shape curriculum content by mandating risk assessment modules and protective stop verification protocols. Germany's KBA and Japan's METI both influence training mandates through industrial safety inspectorates that audit workforce competency against national qualification frameworks. South Korea's MFDS-equivalent industrial safety regulator and China's SAMR push localization requirements that redirect course content toward domestic robot brands. Stakeholders must monitor whether emerging EU AI Act classifications for autonomous robotic systems trigger new training disclosure obligations that fragment certification portability across jurisdictions.
Market Dynamics
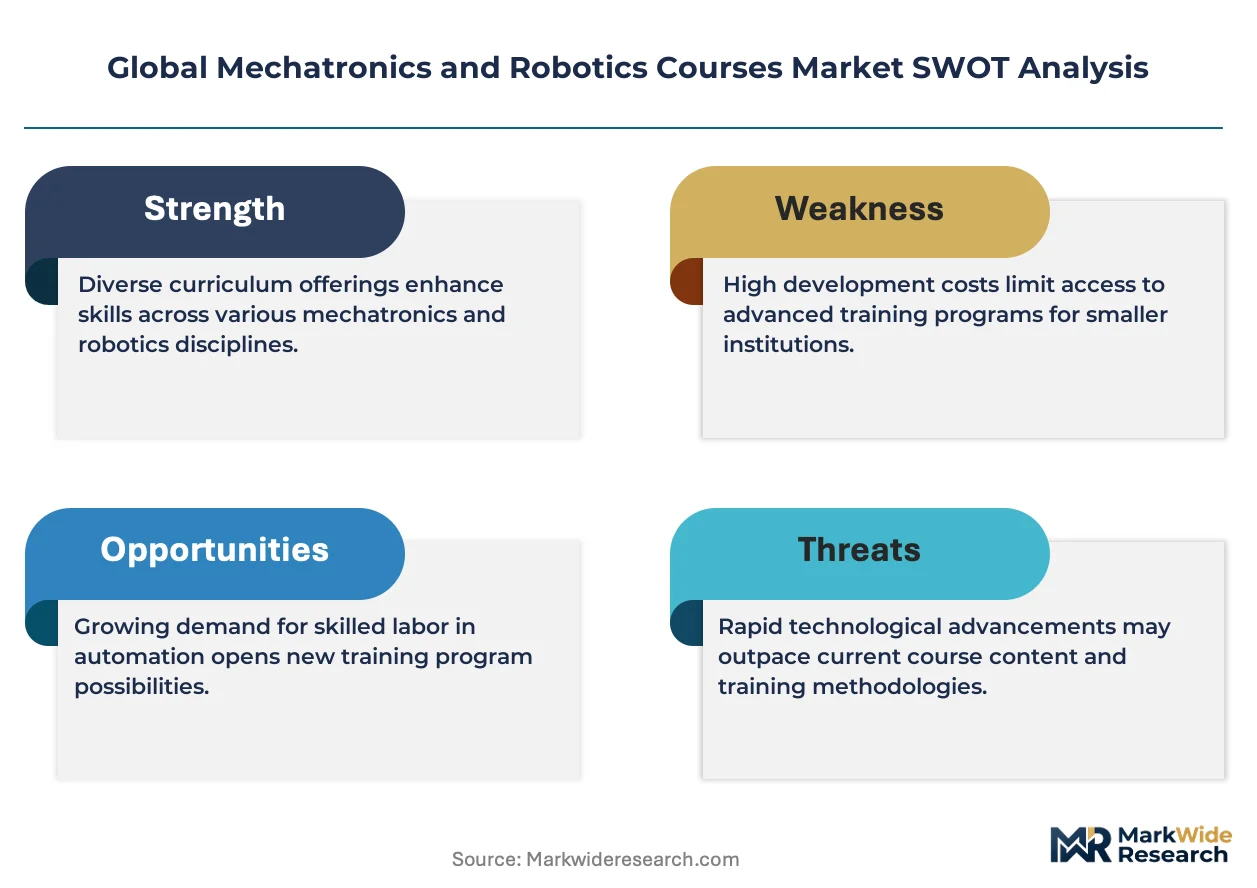
Vendor-specific certification ecosystems are fragmenting workforce mobility as equipment manufacturers lock training content to proprietary hardware platforms, forcing employers to duplicate reskilling investments across multiple robot brands.
Growth Catalysts
- ISO 10218-1 and ISO 10218-2 safety mandates:German automotive OEMs now require certified technicians for collaborative robot deployments, expanding mandatory training volumes at Tier-1 suppliers.
- Semiconductor fabrication automation:Samsung and SK Hynix suppliers in South Korea's Gyeonggi corridor are absorbing mechatronics graduates at premium placement rates, pulling curriculum demand toward cleanroom robotics.
- AI-integrated motion control:Machine learning-based trajectory optimization is creating new competency requirements that legacy PLC programmers must acquire through formal certification tracks.
Market Restraints
- Physical lab infrastructure costs:Industrial robot hardware and safety cage requirements impose capital barriers that limit course provider entry outside manufacturing-dense regions.
- Vendor certification lock-in:ABB, KUKA, and Fanuc proprietary curricula fragment credential portability, forcing technicians to retrain when switching employers.
- Asynchronous online limitations:Servo motor tuning and force-feedback calibration require tactile learning that pure digital delivery cannot replicate, capping enrollment in remote-only programs.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for electronics and automotive sectors are triggering greenfield factory investments that will require localized technician training infrastructure.
- EU AI Act autonomous system classifications:Emerging disclosure obligations for high-risk robotic applications may create mandatory retraining windows for existing certified workforces.
- Digital twin integration:Virtual commissioning platforms are enabling remote hands-on simulation, allowing course providers to serve dispersed industrial clusters without physical robot density.
Industry Challenges
- Dual-track competency gaps:Technicians trained on legacy relay-logic systems lack the Python and ROS foundations required for AI-integrated robot programming, forcing costly parallel hiring.
- IEC 61508 functional safety audit timelines:Certification bodies face backlogs in verifying protective stop protocols, delaying course launches and graduate placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mechatronics and Robotics Courses Market |
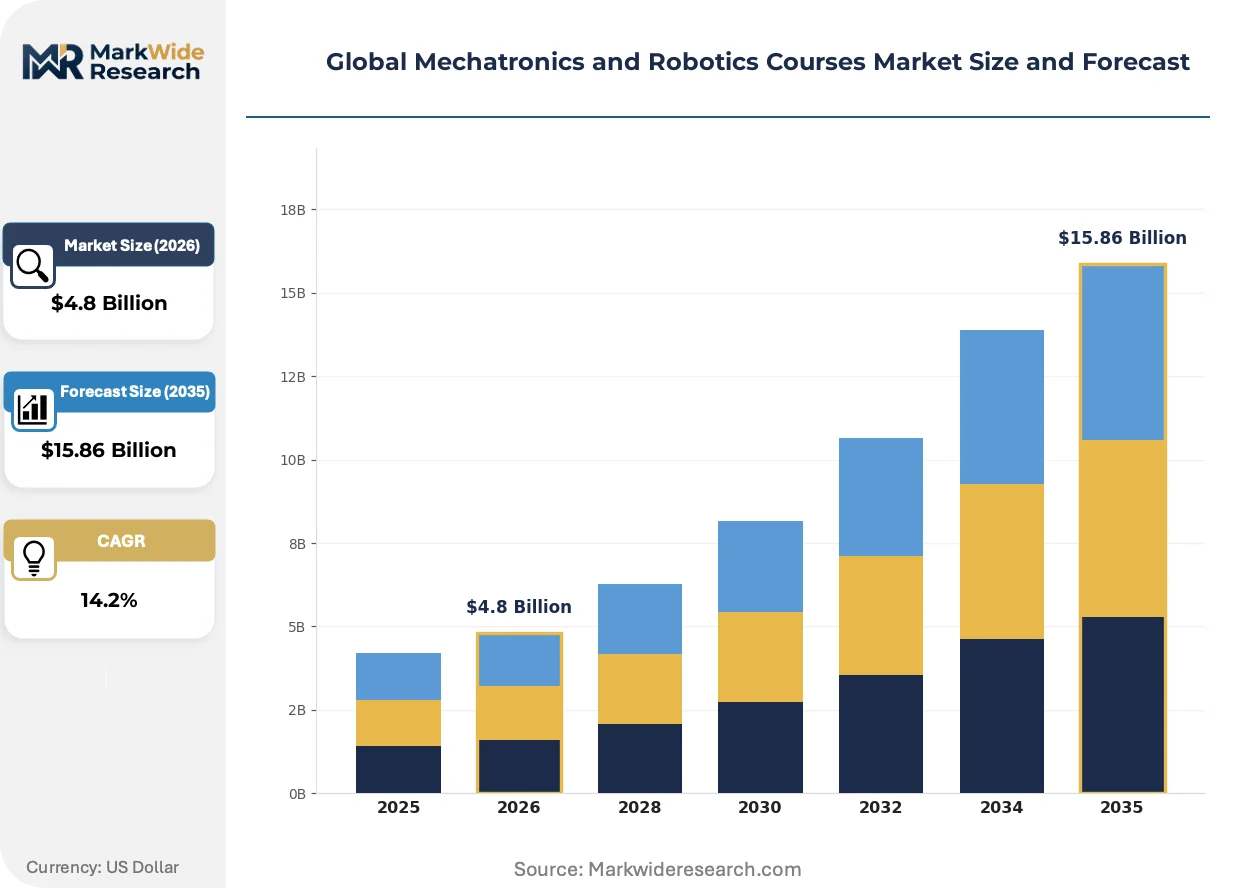
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Course Type: Online, In-Person, Hybrid, Certification Target Audience: Students, Professionals, Hobbyists, Corporates Level of Instruction: Beginner, Intermediate, Advanced, Specialized Medium of Instruction: English, Spanish, Mandarin, Others |
| Companies Covered | Hennepin Technical College, Novatech Robo Pvt Ltd, British Columbia Institute of Technology, ABB, Bosch Rexroth, KUKA Robotics, Technisys, ARM Holdings, Mechatronics Labs S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mechatronics and Robotics Courses Market Strategic Shifts
Training delivery models are bifurcating between vendor-captive certification ecosystems and open-architecture competency frameworks, with employer procurement preferences increasingly dictating which pathway dominates regional markets.
Virtual commissioning software paired with haptic feedback gloves is supplanting physical robot access for foundational motion programming instruction. Community colleges in Michigan and Ohio are adopting these platforms to serve automotive supplier networks without capital-intensive lab investments. This compression of hardware dependency is enabling course providers to enter secondary manufacturing markets previously excluded by robot density requirements.
The EU AI Act's risk-based classification system for autonomous robotic systems is mandating documented competency trails for high-risk deployments. German industrial safety inspectorates under KBA oversight now audit workforce qualification records against these disclosure standards. Automotive OEMs in Stuttgart and Wolfsburg are responding by bundling retraining clauses into robot lease agreements to ensure continuous compliance.
Employer-sponsored asynchronous reskilling is displacing traditional full-time enrollment for incumbent manufacturing workers. Bosch Rexroth and similar equipment vendors are unbundling theory modules into micro-credential stacks that shift workers complete between production cycles. This consumption-pattern shift is most visible in Germany's Mittelstand sector, where small-batch manufacturers cannot release technicians for extended classroom programs.
Global Mechatronics and Robotics Courses Market Segmentation
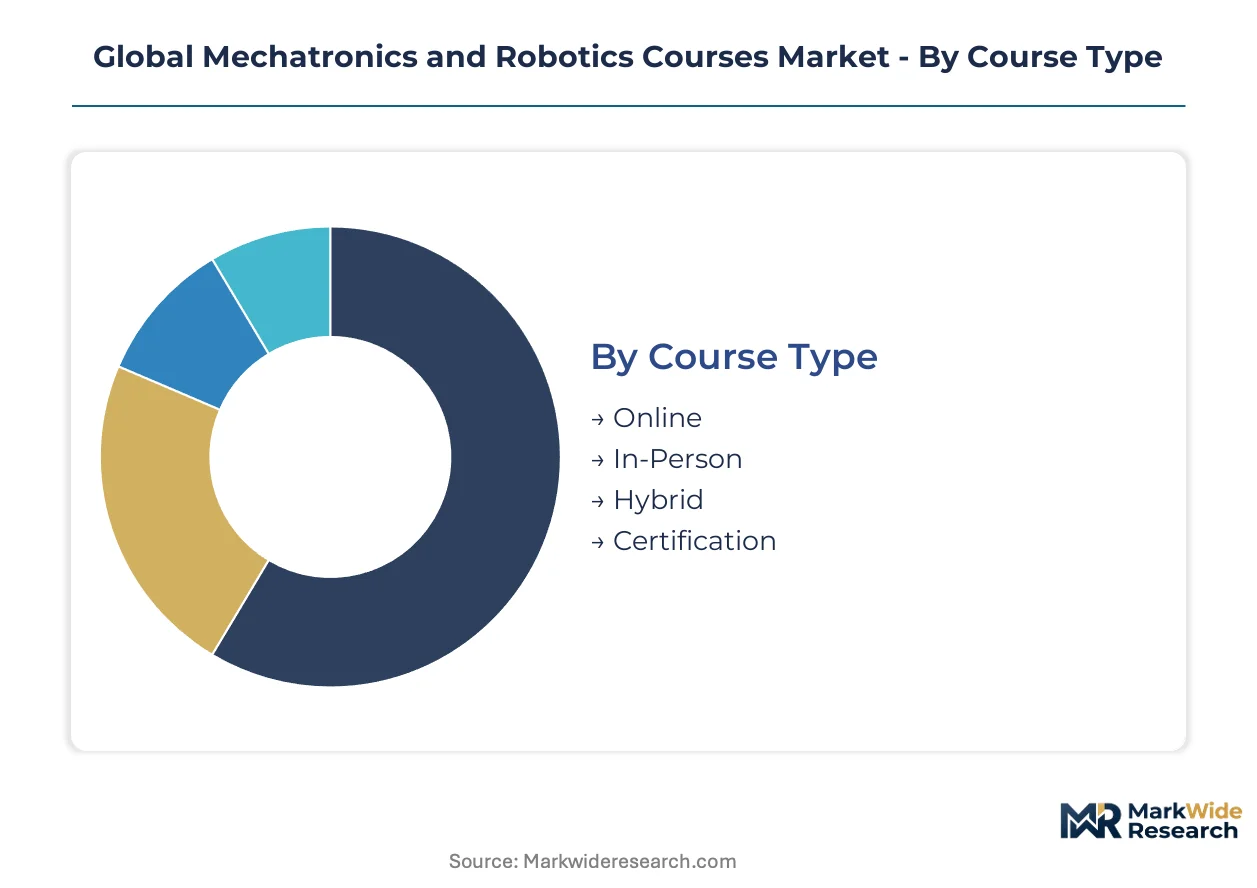
Course providers structure offerings around regulatory compliance requirements and employer procurement patterns. Segmentation reveals how ISO 10218 certification mandates and AI-integrated competency gaps reshape enrollment flows across delivery modes and skill tiers.
Course Type:
Regulatory frameworks differentiate delivery modes through safety audit requirements and physical lab mandates.
- Online:Asynchronous modules scale theory instruction for shift workers at Bosch Rexroth and similar Mittelstand employers. Enrollment velocity climbs fastest where employers adopt micro-credential stacks for incumbent technician reskilling between production cycles.
- In-Person:Mandatory for ISO 10218-1 collaborative robot safety certification requiring protective stop verification and risk assessment demonstrations. German automotive OEMs and Tier-1 suppliers absorb concentrated volumes in Stuttgart and Wolfsburg clusters.
- Hybrid:Theory modules deliver digitally while hands-on robot access requires physical lab proximity. Community colleges in Michigan and Ohio deploy this model to serve automotive supplier networks without capital-intensive full lab investments.
- Certification:Vendor-specific credentialing from ABB, KUKA, and Fanuc dominates automotive sector placements. Proprietary curricula fragment workforce mobility and force retraining upon employer switches.
Established volume favors in-person delivery; emerging adoption favors online expansion.
Target Audience:
Employer sponsorship patterns concentrate procurement by workforce category and reskilling urgency.
- Students:University engineering programs integrate mechatronics curricula with PLC programming and servo motor tuning fundamentals. South Korean semiconductor fabrication corridors absorb graduates at premium placement rates from Samsung and SK Hynix suppliers.
- Professionals:Incumbent technicians require Python and ROS foundations for AI-integrated robot programming. Legacy relay-logic programmers face costly parallel hiring pressures without formal certification tracks.
- Hobbyists:Entry-level robotics kits and maker-space access drive non-vocational enrollment. Limited relevance for industrial safety compliance mandates.
- Corporates:Greenfield factory investments under India's PLI scheme trigger localized technician training infrastructure demand. Production-linked incentives for electronics and automotive sectors reshape procurement scale.
Corporate contracts command premium pricing; professional segments drive recurring enrollment.
Level of Instruction:
Competency depth determines certification portability and salary placement outcomes.
- Beginner:Foundational mechanical engineering, electronics, and control systems introduction. Community colleges and vocational institutes capture volume in manufacturing-dense regions.
- Intermediate:Programmable logic controller deployment and sensor fusion architecture implementation. Serves technicians bridging legacy automation maintenance toward AI-integrated systems.
- Advanced:Machine learning-based trajectory optimization and virtual commissioning platforms. Deepest margin pools from vendor-specific certification premiums attached to equipment manufacturer partnerships.
- Specialized:Cleanroom robotics for semiconductor fabrication and autonomous guided vehicle optimization. Samsung and SK Hynix suppliers in Gyeonggi corridor pull curriculum demand toward contamination-controlled environments.
Advanced instruction captures margin concentration; specialized tracks expand fastest.
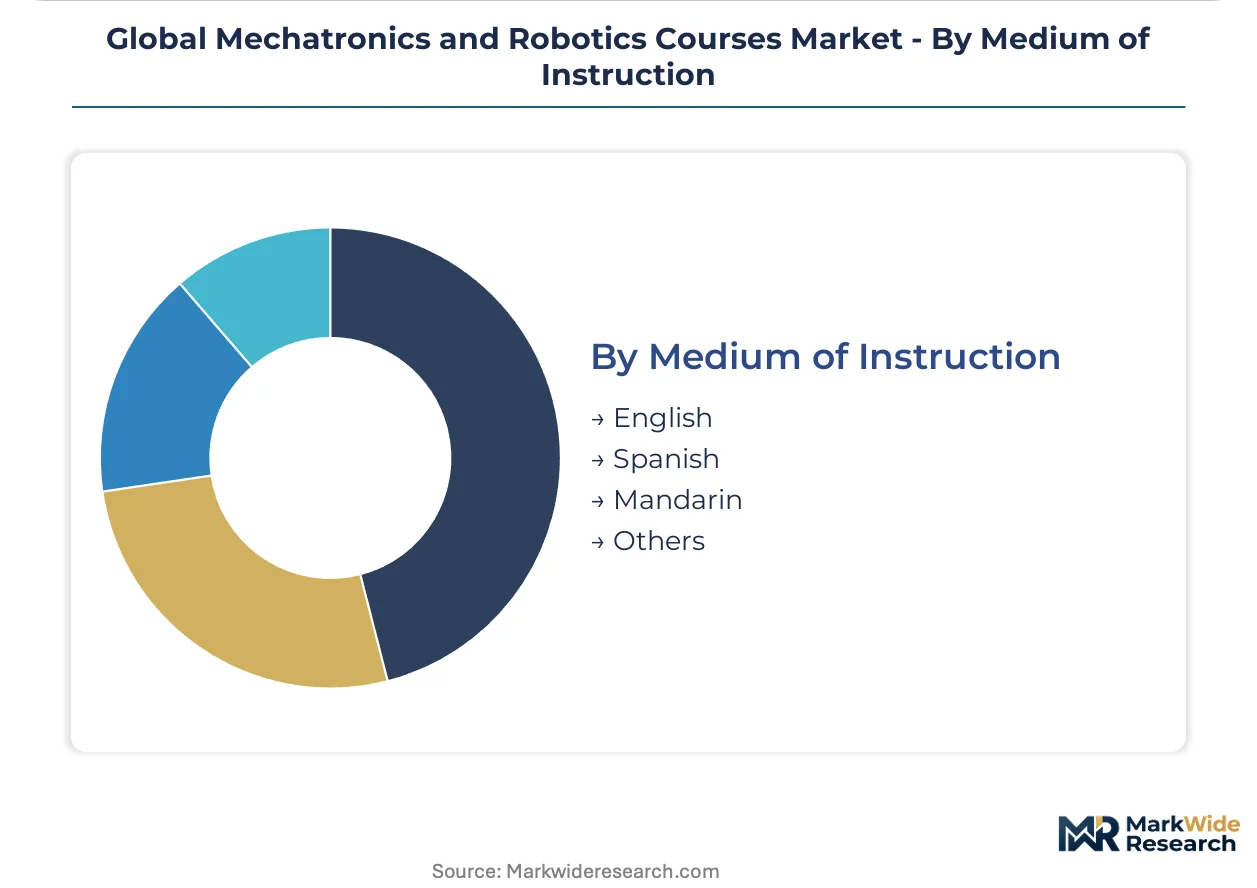
Medium of Instruction:
Localization requirements from national regulators redirect content toward domestic robot brands and workforce demographics.
- English:Dominates vendor-specific certification ecosystems from ABB, KUKA, and Fanuc. Global manufacturing employers standardize procurement around English-medium credentials for workforce mobility.
- Spanish:Growing relevance for Latin American manufacturing expansion and US-Mexico border industrial clusters. Regional automotive supplier networks drive curriculum localization.
- Mandarin:China's SAMR pushes localization requirements toward domestic robot brands. Course content redirects from international OEM curricula toward indigenous equipment manufacturer standards.
- Others:Japanese, German, and Korean language instruction serves protected national qualification frameworks. METI and KBA oversight mandates shape domestic training mandates.
English maintains certification portability; Mandarin gains structural share through localization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs consume mechatronics training through mandatory ISO 10218 certification clauses embedded in supplier contracts, while South Korean semiconductor fabs absorb technicians through premium placement pipelines. This divergence—regulatory compulsion versus talent arbitrage—shapes distinct procurement patterns across manufacturing clusters.
Germany
KBA industrial safety inspectorates audit workforce competency against national qualification frameworks, forcing Tier-1 suppliers in Stuttgart and Wolfsburg to maintain certified technician pools. Bosch Rexroth anchors proprietary training ecosystems across Mittelstand manufacturing clusters. The Baden-Württemberg automotive corridor concentrates in-person certification volumes for collaborative robot deployments.
South Korea
Samsung and SK Hynix suppliers in the Gyeonggi semiconductor fabrication corridor absorb mechatronics graduates at premium placement rates, pulling curriculum demand toward cleanroom robotics. The country's industrial safety regulator mandates contamination-controlled environment training for high-precision fabrication roles. Seoul Capital Area technical institutes dominate advanced instruction segments for AI-integrated motion control systems.
United States
Community colleges in Michigan and Ohio deploy hybrid delivery models to serve automotive supplier networks without capital-intensive full lab investments. OSHA-aligned safety frameworks shape protective stop verification protocols in collaborative robot coursework. The Midwest manufacturing belt captures concentrated enrollment for PLC programming and servo motor tuning fundamentals.
Japan
METI oversight influences training mandates through industrial safety inspectorates that audit workforce competency against JIS standards. Automotive manufacturers expand in-house robotics training programs to meet ISO 10218 safety compliance requirements for collaborative deployments. The Nagoya-Toyota industrial corridor sustains vendor-specific certification volumes from Fanuc and other domestic robot OEMs.
India
Production-linked incentives for electronics and automotive sectors trigger greenfield factory investments requiring localized technician training infrastructure. The country's national industrial regulator pushes curriculum localization toward domestic equipment standards. Maharashtra and Gujarat manufacturing clusters absorb the initial wave of corporate-sponsored reskilling contracts for incumbent automation maintenance workers.
Global Mechatronics and Robotics Courses Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with equipment manufacturers leveraging installed base dominance to anchor proprietary certification ecosystems. The upper tier captures margin concentration through vendor-specific credential premiums bundled with hardware lease agreements. Three archetypes define competitive positioning: robot OEMs with captive training divisions, independent technical institutes with regulatory accreditation, and hybrid platform providers bridging asynchronous theory with physical lab access. Dominant competitive moves include curriculum bundling with equipment procurement contracts and geographic expansion through community college partnership networks.
Within the equipment-integrated tier, ABB, KUKA Robotics, and Bosch Rexroth exemplify divergent strategic anchors. ABB leverages its Nordic manufacturing cluster presence to sustain proprietary certification ecosystems. KUKA Robotics occupies a position defined by automotive-sector course placement density. Bosch Rexroth represents the hydraulics-to-robotics curriculum bridge model sustaining German Mittelstand loyalty. These three collectively illustrate how hardware installed base translates into training content lock-in.
| Leading Market Players |
|---|
| Hennepin Technical College |
| Novatech Robo Pvt Ltd |
| British Columbia Institute of Technology |
| ABB |
| Bosch Rexroth |
| KUKA Robotics |
| Technisys |
| ARM Holdings |
| Mechatronics Labs S.r.l. |
| Others |
Value Chain & Pricing Dynamics
Three-month lead times for industrial robot hardware procurement from Germany and Japan concentrate pricing power with ABB, KUKA, and Fanuc, forcing course providers to absorb equipment premiums or pass through costs to corporate training contracts. This inventory pressure feeds directly into vendor-specific certification premiums, where bundled hardware-software training packages command substantial margins over open-architecture alternatives.
Pricing Analysis
Long-term offtake contracts dominate corporate training procurement, with Bosch Rexroth and similar equipment vendors locking in multi-year service agreements that bundle certification with robot lease arrangements. Price differentiation centers on certification tier—ISO 10218 safety credentials command substantial premiums over foundational PLC programming—and volume scale, where Tier-1 automotive suppliers negotiate enterprise discounts unavailable to Mittelstand manufacturers. Cost compression in intermediate instruction segments is intensifying because community colleges and vocational institutes compete for the same employer sponsorship pools. Corporate buyers exhibit lowest price sensitivity for advanced AI-integrated motion control certification, while hobbyist and entry-level segments face acute pressure from free online alternatives.
Supply Chain Analysis
Just-in-time inventory strategies prevail among course providers serving semiconductor fabrication corridors, where Samsung and SK Hynix supplier networks demand rapid technician deployment without capital-intensive robot stockpiling. Hardware supply concentrates in Germany, Japan, and South Korea, with ABB's Nordic manufacturing base, KUKA's Augsburg production, and Fanuc's Yamanashi facilities anchoring equipment availability. Component dependencies span servo motors from Japan's precision manufacturers, programmable logic controllers from German automation specialists, and sensor arrays from South Korean electronics suppliers. Single-source vulnerability runs through Fanuc's dominance in automotive-sector collaborative robot installations, where alternative OEM training curricula cannot substitute without full equipment replacement. Distribution runs through direct OEM channels for vendor-captive certification, with independent technical institutes sourcing refurbished hardware through secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics and robotics courses sit in early-cycle expansion as manufacturing employers confront acute technician shortages for AI-integrated automation deployments. Semiconductor fabrication automation and collaborative robot safety mandates create durable demand tailwinds across multiple geographies.
For Market Incumbents: Fortify certification portability defenses by deepening ISO 10218 and IEC 61508 accreditation moats before EU AI Act disclosure obligations fragment credential standards. Invest in virtual commissioning platform partnerships to reduce physical lab dependency and serve dispersed industrial clusters without capital-intensive hardware replication. Threats from open-architecture competency frameworks and micro-credential unbundling require proactive employer lock-in through bundled retraining clauses in robot lease agreements. For New Entrants and Emerging Players: Differentiate on cleanroom robotics specialization for semiconductor fabrication corridors, where Samsung and SK Hynix supplier networks absorb graduates at premium placement rates with limited incumbent competition. Target India's PLI scheme manufacturing clusters through localized technician training infrastructure partnerships with greenfield electronics and automotive investors. Go-to-market through community college partnership networks avoids direct confrontation with vendor-captive certification ecosystems. For Investors and Strategic Acquirers: Long-term, this sits as a workforce infrastructure play because automation penetration rates across manufacturing sectors require sustained reskilling investment regardless of cyclical output fluctuations. Acquisition targets should emphasize independent technical institutes with regulatory accreditation and hybrid delivery capabilities bridging asynchronous theory with physical lab access. The signal to watch is EU AI Act implementation timelines for high-risk robotic system classifications, which may trigger mandatory retraining windows and expand addressable market scope.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Commissioning Platform Deployment | Reduces hardware dependency for community colleges serving Michigan and Ohio automotive suppliers. |
| ISO 10218 Certification Accreditation Investment | Locks in mandatory training volumes at German Tier-1 suppliers facing KBA safety audits. |
| Cleanroom Robotics Curriculum Development | Captures premium placement pipelines from Samsung and SK Hynix suppliers in Gyeonggi corridor. |
| India PLI Scheme Localization Partnership | Positions for greenfield factory training demand in Maharashtra and Gujarat manufacturing clusters. |
| Micro-Credential Unbundling for Shift Workers | Serves Bosch Rexroth Mittelstand employers adopting asynchronous reskilling between production cycles. |
Study Parameters
A standing panel of plant engineering directors, technical training managers at automotive OEMs, community college workforce development leads, and industrial safety compliance officers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation from ISO standards documentation, IEC functional safety frameworks, national qualification framework filings under Germany's KBA and Japan's METI, and corporate training procurement disclosures. Bottom-up enrollment data from course providers triangulated against top-down manufacturing employment projections and automation investment flows.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including course delivery mode, target audience category, instruction level tier, and geographic regulatory cluster. CAGRs derived from historical enrollment trajectories, employer sponsorship growth rates, and capital expenditure patterns in manufacturing automation. Industry-specific forecast inputs incorporated semiconductor fabrication capacity expansion timelines and collaborative robot deployment mandates under evolving safety inspectorate requirements.
Material uncertainties—regulatory reclassification under EU AI Act, vendor certification portability fragmentation, and physical lab infrastructure cost inflation—sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained manufacturing automation investment and employer reskilling willingness without explicit contractual guarantees. Practitioners should keep alternative scenarios live as national industrial safety mandates and equipment manufacturer training ecosystem strategies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
North America IT Training Market
Professional Development and Training
United States Executive Education Program Market
Professional Development and Training
Cognitive Assessment and Training Market
Professional Development and Training
United States Soft Skills Training Market
Professional Development and Training
Europe Soft Skills Training Market
Professional Development and Training
Technical and Vocational Education Market
Professional Development and Training
US Life Coaching Market
Professional Development and Training
Europe Leadership Development Program Market
Professional Development and Training
Canada Executive Education Program Market
Professional Development and Training
HSE Consulting Training Services Market
Professional Development and Training
Personal Development Market
Professional Development and Training
GCC Soft Skills Training Market
Professional Development and Training
Executive Coaching and Leadership Development Market
Professional Development and Training
Global Soft Skills Training Market
Professional Development and Training
Global Social and Emotional Learning (SEL) Market
Professional Development and Training
Human Resource Professional Services Market