
 A2 Infant Formula Market | 2026-2036
A2 Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
A2 Infant Formula Market Insights
Pediatric nutritionist shortages across major dairy markets is collapsing quality assurance bandwidth at manufacturing facilities. The a2 Milk Company leverages its proprietary A2 protein sourcing and herd certification to sustain premium positioning in Australia and China. Nestlé anchors its competitive stance through extensive R&D infrastructure spanning multiple continents. Danone differentiates via specialized medical nutrition expertise that extends into regulated infant feeding categories.
A2 infant formula refers to dairy-based nutritional products manufactured exclusively from cow milk containing the A2 beta-casein protein variant, excluding the A1 variant linked to digestive discomfort in some infants. Standard production requires A2 genotype verification of dairy herds, followed by segregated processing at protein levels below 0.3% A1 contamination threshold to preserve functional digestibility claims. Powdered formula dominates current manufacturing volumes due to extended shelf stability and lower logistics costs, while ready-to-feed liquid formats capture expanding margin pools among convenience-seeking caregivers in premium urban channels. Stage 1 formulations for neonates aged zero to six months represent the most regulated and clinically scrutinized segment, though Stage 3 products for toddlers twelve months and older generate faster volume growth as feeding transitions extend.
FDA oversees infant formula manufacturing standards and nutrient specifications in the United States under the Federal Food, Drug, and Cosmetic Act, while China's NMPA and GB 10765-2021 standards govern product registration, labeling, and protein content claims in the world's largest import market. EFSA's novel food assessments and CE marking requirements shape European market access pathways for A2-specific health positioning. Stakeholders must monitor evolving protein labeling thresholds and cross-border e-commerce enforcement as regulatory divergence between major import jurisdictions intensifies scrutiny on digestibility claims and clinical substantiation.
Market Dynamics
China's NMPA registration tightening under revised GB 10765-2021 standards is compressing import pathways and forcing manufacturers to rebuild clinical substantiation dossiers from protein sourcing through finished product labeling.
Growth Catalysts
- GB 10765-2021 Protein Standards:China's revised national food safety standard for infant formula mandates stricter beta-casein characterization, creating regulatory pull for verified A2 sourcing protocols that exclude A1 contamination above 0.3% thresholds.
- Pediatric Gastroenterology Demand:Parents of infants presenting with milk protein sensitivity symptoms are driving prescription-adjacent purchasing through hospital-affiliated maternity channels in Shanghai, Beijing, and Guangzhou.
- A2 Genotyping Technology:PCR-based herd certification methods now enable dairy cooperatives in Victoria and New South Wales to segregate A2 milk streams at collection, reducing protein cross-contamination risk in downstream processing.
Market Restraints
- A2 Herd Scarcity:Only 30% of global dairy cattle carry the A2A2 genotype, concentrating raw material supply among specialized breeders in Australia and select New Zealand cooperatives.
- Segregated Processing Infrastructure:Dedicated A2-only production lines require capital outlays for protein detection equipment and facility isolation, elevating fixed cost structures versus commodity dairy processing.
- Clinical Substantiation Burden:EFSA's novel food assessment framework demands randomized controlled trial data for digestive comfort claims, extending product development timelines by 18-36 months for European market entry.
Strategic Opportunities
- Tier-Two Chinese Urban Channels:Chengdu, Hangzhou, and Wuhan maternity hospitals show rising A2 formula inquiries from middle-class parents seeking digestive-friendly alternatives beyond saturated Beijing-Shanghai corridors.
- Ready-to-Feed Liquid Formats:Convenience-seeking caregivers in premium urban channels are accepting 40-60% price premiums for pre-mixed liquid products versus powdered equivalents, opening margin expansion pools.
- Cross-Border E-Commerce Enforcement Gaps:Daigou channels and bonded warehouse zones currently operate with labeling flexibility that licensed importers lack, creating arbitrage windows for agile supply chain operators.
Industry Challenges
- Pediatric Nutritionist Shortage:Manufacturing facilities in Australia and China report collapsing quality assurance bandwidth as specialized talent migrates to clinical settings offering superior compensation.
- Protein Detection Certification:Third-party verification of sub-0.3% A1 contamination requires ELISA or mass spectrometry protocols that few contract laboratories can execute at commercial scale, creating testing bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | A2 Infant Formula Market |
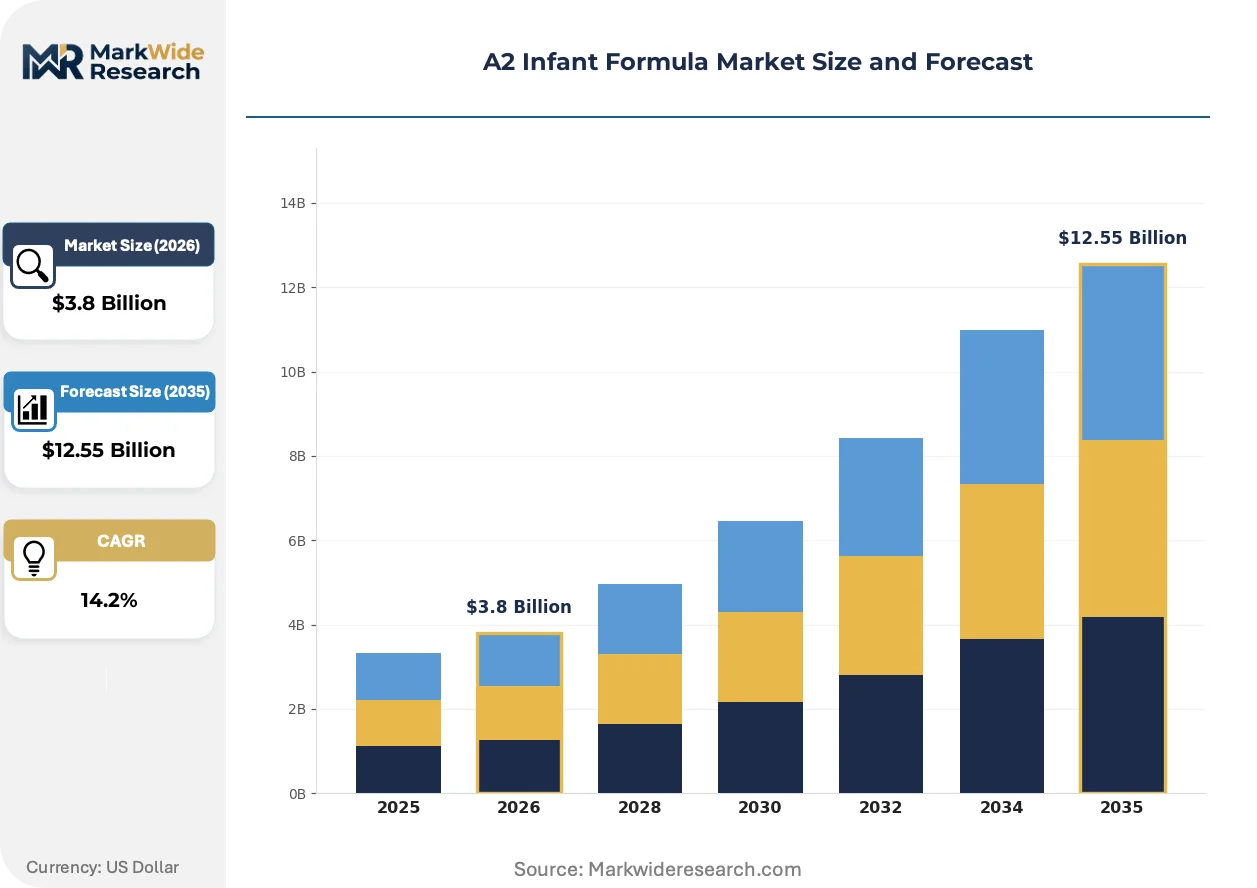
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Formula, Liquid Formula, Concentrated Formula, Ready-To-Feed Formula Formulation Stage: Stage 1 (0-6 months), Stage 2 (6-12 months), Stage 3 (12+ months), Special Dietary Needs Application: Hospital Use, Home Feeding, Daycare Centers, Pediatric Clinics End User: Neonatal Units, Maternity Wards, Pediatricians, Caregivers |
| Companies Covered | The a2 Milk Company, Nestlé, Danone, Abbott, Bellamy’s Organic, Bubs Australia Limited, Holle baby food, Synlait Milk, Arla Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
A2 Infant Formula Market Trends and Innovations
Protein verification technologies and regulatory divergence between import jurisdictions are reshaping how A2 infant formula manufacturers structure clinical substantiation and supply chain segregation protocols.
Mass spectrometry-based beta-casein differentiation is supplanting less precise ELISA methods in premium manufacturing facilities. Australian dairy processors serving the China export market are adopting liquid chromatography-tandem mass spectrometry (LC-MS/MS) to document A1 protein absence at batch release. This technology shift is compressing competitive positioning around laboratories capable of ISO 17025-accredited protein quantification.
China's NMPA has intensified scrutiny on cross-border e-commerce infant formula listings, requiring GB standard compliance documentation even for gray-market channels. The industrial consequence is a bifurcation between licensed registrants with full clinical dossiers and daigou operators facing delisting risk. Premium urban maternity channels in Shanghai and Beijing are responding by consolidating procurement around NMPA-registered brands with verified supply chain documentation.
Hospital-affiliated maternity stores are displacing traditional retail pharmacy distribution for first-time A2 formula purchases. New parents in China's tier-one cities increasingly receive product recommendations from lactation consultants and pediatric nurses during postnatal consultations, shifting initial trial decisions into clinical-adjacent retail environments. This channel migration is most visible in Beijing's municipal hospital maternity wings and Shanghai's women and children's medical centers.
A2 Infant Formula Market Segmentation
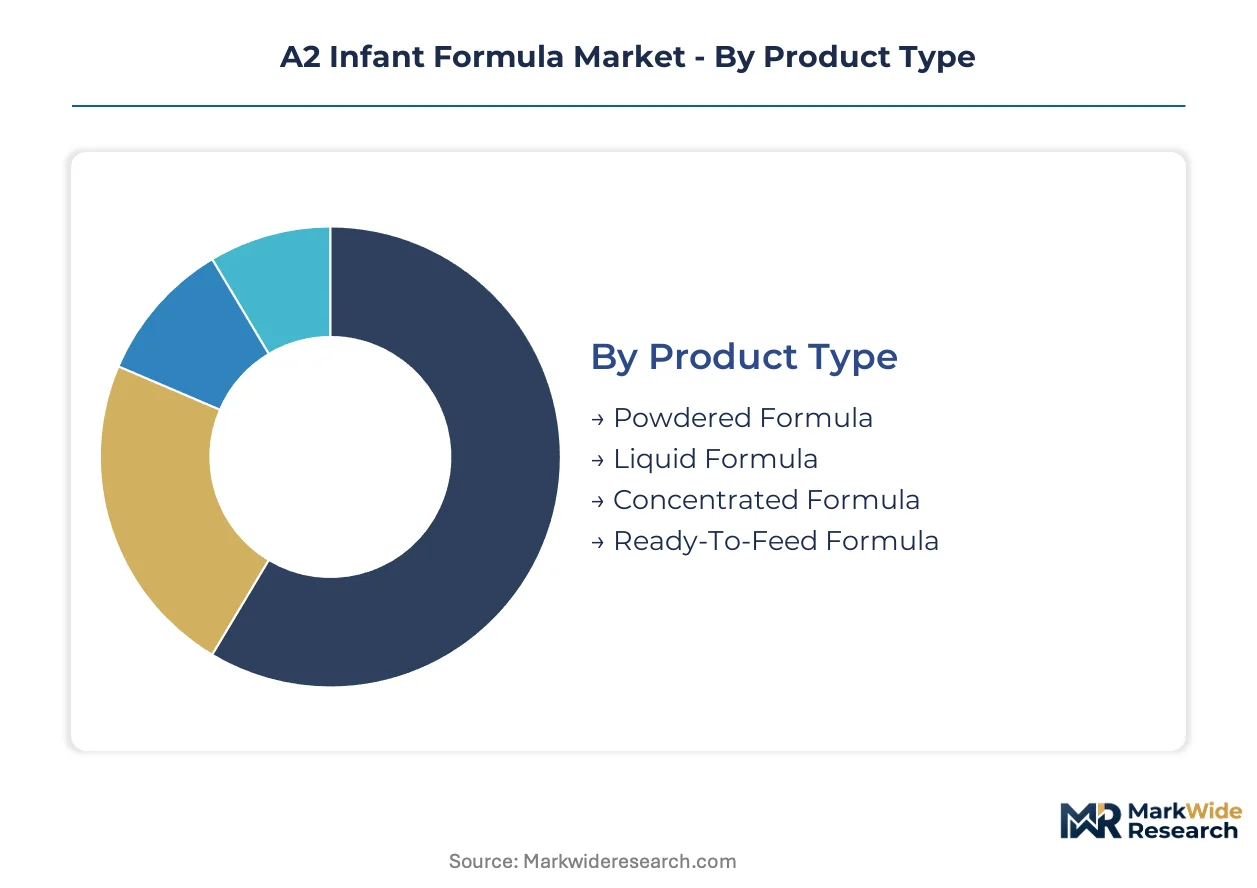
A2 infant formula segmentation reflects divergent regulatory scrutiny across product formats and feeding stages. Manufacturers must align certification protocols with jurisdiction-specific protein labeling thresholds for each segment tier.
Product Type:
GB 10765-2021 mandates distinct beta-casein documentation for powdered versus liquid formats, with ready-to-feed products facing additional sterility validation requirements.
- Powdered Formula:Dehydrated milk protein blends requiring reconstitution with water dominate manufacturing volumes due to extended shelf stability and lower logistics costs. Demand concentrates in Australia's dairy processing corridors serving China's tier-one urban maternity channels, though NMPA registration tightening is compressing import pathways for non-registered brands.
- Ready-To-Feed Formula:Pre-mixed sterile liquid products eliminate reconstitution errors and capture 40-60% price premiums from convenience-seeking caregivers. Demand clusters in Shanghai and Beijing hospital-affiliated maternity stores where lactation consultants influence first-time purchase decisions during postnatal consultations.
- Liquid Formula:Concentrated liquid requiring dilution occupies a narrowing niche between powder and ready-to-feed formats, primarily distributed through Australian supermarket chains and select Chinese cross-border e-commerce platforms.
- Concentrated Formula:Reduced-water liquid preparations requiring dilution serve cost-conscious segments in New Zealand domestic markets and select Southeast Asian import channels with less stringent protein verification requirements.
Powdered formula handles the majority of throughput; ready-to-feed is gaining share fastest among premium urban caregivers.
Formulation Stage:
Cost tier differentiation separates clinically scrutinized neonatal formulations from margin-accretive toddler products with relaxed nutrient specifications.
- Stage 1 (0-6 months):Formulations for neonates face the most intensive regulatory scrutiny under FDA infant formula nutrient specifications and China's GB 10765-2021 protein standards. Manufacturing facilities in Victoria and New South Wales deploy PCR-based herd certification and LC-MS/MS batch testing to document sub-0.3% A1 contamination for NMPA registration dossiers.
- Stage 3 (12+ months):Toddler formulations operate under reduced clinical substantiation burdens while generating faster volume growth as feeding transitions extend. Demand concentrates in China's tier-two urban channels including Chengdu, Hangzhou, and Wuhan where middle-class parents seek digestive-friendly alternatives beyond saturated Beijing-Shanghai corridors.
- Stage 2 (6-12 months):Transitional formulations bridge neonatal and toddler nutrition requirements, primarily distributed through pediatric clinic dispensing networks in Australia's major metropolitan centers.
- Special Dietary Needs:Hypoallergenic and medical nutrition variants require EFSA novel food assessments for European market access, extending development timelines by 18-36 months.
Stage 1 commands the highest certification investment per liter; Stage 3 is expanding most quickly as toddler feeding durations lengthen.
Application:
Customer type migration is displacing traditional retail pharmacy distribution toward clinical-adjacent procurement channels.
- Hospital Use:Neonatal units and maternity wards in Beijing's municipal hospitals and Shanghai's women and children's medical centers are consolidating procurement around NMPA-registered brands with verified supply chain documentation.
- Home Feeding:Direct-to-consumer channels span licensed importers, daigou operators, and bonded warehouse zones with varying labeling flexibility.
- Pediatric Clinics:Specialist consultation settings drive prescription-adjacent purchasing for infants presenting milk protein sensitivity symptoms.
- Daycare Centers:Institutional bulk procurement remains limited due to specialized storage requirements and caregiver liability concerns.
Hospital use anchors quality-assured volume; home feeding channels show the steepest expansion trajectory as cross-border e-commerce enforcement gaps create arbitrage windows.
End User:
Supply concentration among specialized pediatric nutritionists is collapsing quality assurance bandwidth at manufacturing facilities.
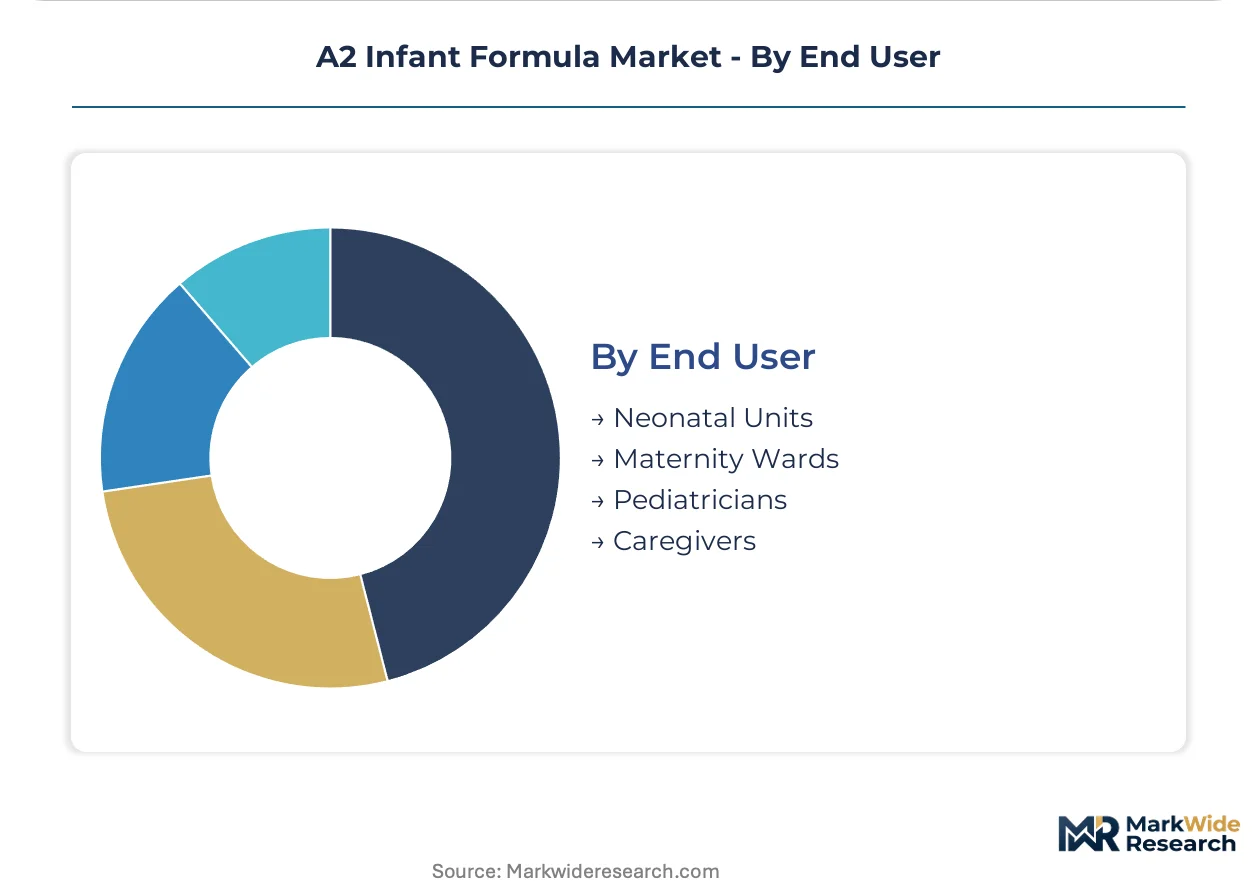
- Caregivers:Parents seeking digestive-friendly alternatives for infants with milk protein sensitivity represent the fastest-expanding buyer segment, driving inquiries through hospital-affiliated maternity channels and online parent communities.
- Neonatal Units:Specialized hospital departments require ISO 17025-accredited protein quantification documentation and batch-level mass spectrometry verification.
- Maternity Wards:Postnatal care settings in China's tier-one cities increasingly embed formula recommendations into discharge protocols.
- Pediatricians:Clinical practitioners influence trial decisions through diagnostic referrals for suspected cow milk protein intolerance.
Caregivers drive volume decision-making; neonatal units impose the most stringent documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA's GB 10765-2021 standards anchor regulatory gravity in China, while FDA nutrient specifications and EFSA novel food assessments shape parallel compliance pathways in North America and Europe. Raw material supply concentrates in Australian dairy corridors serving export demand.
China
Parents in Shanghai, Beijing, and Guangzhou drive prescription-adjacent purchasing through hospital-affiliated maternity channels for infants with milk protein sensitivity. NMPA registration tightening under revised GB standards compresses import pathways and forces clinical substantiation rebuilds. Tier-two cities including Chengdu, Hangzhou, and Wuhan show rising middle-class inquiries as feeding transitions extend.
Australia
Dairy cooperatives in Victoria and New South Wales deploy PCR-based herd certification to segregate A2 milk streams at collection. TGA oversees manufacturing facility inspections and export health certificates for China-bound shipments. Sydney and Melbourne processing corridors concentrate protein detection equipment and ISO 17025-accredited laboratory capacity.
United States
FDA infant formula nutrient specifications under the Federal Food, Drug, and Cosmetic Act govern manufacturing standards and protein content claims. Pediatric gastroenterology demand clusters in metropolitan hospital systems seeking digestive-friendly alternatives. California and New York distribution hubs handle bonded warehouse logistics for cross-border e-commerce fulfillment.
New Zealand
Select cooperatives maintain specialized A2A2 genotype breeding programs to supply raw material for premium export formulations. The country's national food safety regulator enforces dairy export certification protocols aligned with destination market requirements. Canterbury and Waikato dairy regions concentrate herd segregation infrastructure and downstream processing investment.
Germany
EFSA novel food assessment frameworks demand randomized controlled trial data for digestive comfort claims, extending European market entry timelines. Holle baby food exemplifies specialized organic positioning within this regulatory environment. Bavaria and North Rhine-Westphalia host medical nutrition R&D clusters serving regulated infant feeding categories.
A2 Infant Formula Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the A2 infant formula market. The a2 Milk Company and Nestlé occupy positions with proprietary sourcing and multi-continental infrastructure, while regional specialists concentrate on single-market registration depth. Two strategic archetypes dominate: herd-certified originators with backward integration into A2 genotype verification, and medical nutrition extenders leveraging clinical channel relationships. Competitive moves center on NMPA registration dossier completion and mass spectrometry batch testing capability acquisition.
Within the originator archetype, The a2 Milk Company and Bubs Australia Limited exemplify herd-certified sourcing models tied to Australian dairy regions. Synlait Milk occupies a processing-specialist position supplying third-party brand owners. Danone and Nestlé sit within the medical nutrition tier, extending regulated infant feeding expertise across multiple continental markets. Abbott represents the clinical-channel anchor with hospital-affiliated distribution infrastructure.
| Leading Market Players |
|---|
| The a2 Milk Company |
| Nestlé |
| Danone |
| Abbott |
| Bellamy's Organic |
| Bubs Australia Limited |
| Holle baby food |
| Synlait Milk |
| Arla Foods |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Australian dairy cooperatives and Chinese licensed importers lock in A2A2 genotype milk access while stabilizing landed cost visibility against protein certification volatility. These arrangements concentrate pricing power among herd-certified originators capable of documenting sub-0.3% A1 contamination through ISO 17025-accredited mass spectrometry protocols.
Pricing Analysis
Shanghai and Beijing hospital-affiliated maternity channels command 40-60% premiums over Australian domestic supermarket pricing for identical SKUs. Three-tier pricing structure across premium, standard, and economy levels separates NMPA-registered brands with full clinical dossiers from gray-market daigou imports and unverified powder formulations. Pricing pressure stems from NMPA registration tightening forcing manufacturers to absorb ELISA and LC-MS/MS testing costs without passing through to price-sensitive tier-two urban buyers. Caregivers in Chengdu, Hangzhou, and Wuhan exhibit highest price sensitivity, while neonatal units in tier-one municipal hospitals demonstrate lowest elasticity due to procurement consolidation around verified supply chains.
Supply Chain Analysis
Australia and New Zealand anchor global A2 beta-casein raw material supply through specialized A2A2 genotype breeding programs concentrated in Victoria, New South Wales, Canterbury, and Waikato. Downstream processing draws from PCR-based herd certification at collection, segregated tanker logistics, and dedicated production lines with protein detection equipment. Single-source vulnerability concentrates in third-party contract laboratories capable of ISO 17025-accredited batch testing, where testing bottlenecks currently extend release timelines. Distribution runs through TGA-certified export facilities serving China-bound shipments, with bonded warehouse zones in Shanghai and Guangzhou handling licensed importer volumes alongside parallel daigou channel flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from regulatory cyclicality as China's NMPA completes its GB 10765-2021 transition and stabilizes registration pathways for substantiated dossiers.
For Market Incumbents: Shield NMPA-registered positioning by accelerating mass spectrometry batch testing capability acquisition before third-party laboratory capacity constraints worsen. Consolidate procurement relationships with Australian dairy cooperatives maintaining PCR-based herd certification to defend against emerging originators from New Zealand's Canterbury region. Channel control through hospital-affiliated maternity store partnerships represents the critical defensive lever against daigou arbitrage erosion. For New Entrants and Emerging Players: Anchor in tier-two Chinese urban channels where middle-class parent inquiries for digestive-friendly alternatives are rising fastest and NMPA-registered brand presence remains thinner than in saturated Beijing-Shanghai corridors. Target Stage 3 toddler formulations where clinical substantiation burdens relax and volume growth accelerates as feeding transitions extend. A go-to-market angle emphasizing lactation consultant education programs at Chengdu and Wuhan municipal hospital maternity wings bypasses traditional retail pharmacy gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward herd-certified originators with backward integration into A2 genotype verification and established NMPA registration dossiers rather than medical nutrition extenders facing European EFSA novel food assessment delays. Long-term viability across a 5-10 year window hinges on protein detection technology ownership and clinical channel relationships that survive regulatory enforcement intensification. The signal to watch is NMPA cross-border e-commerce delisting velocity, which would accelerate procurement consolidation around licensed registrants and compress gray-market arbitrage windows.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Registration Dossier Completion | Full GB 10765-2021 compliance unlocks hospital-affiliated maternity channel access in tier-one cities. |
| Mass Spectrometry Testing Capability Acquisition | LC-MS/MS batch verification compresses competitive positioning around ISO 17025-accredited laboratory capacity. |
| Tier-Two Urban Channel Expansion | Chengdu, Hangzhou, and Wuhan maternity hospitals show rising middle-class parent inquiries beyond saturated corridors. |
| Ready-to-Feed Liquid Format Launch | Pre-mixed sterile products capture 40-60% price premiums from convenience-seeking caregivers in premium channels. |
| Pediatric Nutritionist Talent Recruitment | Manufacturing facility quality assurance bandwidth is collapsing as specialized talent migrates to clinical settings. |
Research Methodology
Desk research of NMPA registration databases, GB standard compliance filings, and Australian dairy export certification records preceded structured interviews with pediatric nutritionists at manufacturing facilities, regulatory affairs leads at infant formula brand owners, procurement managers at Chinese hospital-affiliated maternity channels, and herd certification specialists at Australian dairy cooperatives. Secondary validation drew from TGA export health certificates, China customs import data, and EFSA novel food assessment documentation. Bottom-up volume modeling across product formats and formulation stages was triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across the projection horizon isolates volume drivers by formulation stage, product format, and regional regulatory cluster, with particular sensitivity to NMPA enforcement intensity and EFSA assessment timelines. Segmentation dimensions modeled include product type, formulation stage, application channel, and end user category. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points, with protein verification technology adoption curves and hospital channel procurement consolidation rates serving as industry-specific forecast inputs.
Material uncertainties — NMPA cross-border e-commerce enforcement escalation, EFSA novel food assessment outcome variability, and A2A2 genotype herd expansion rates — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory stability and protein detection laboratory capacity scaling that could require revision if these factors deviate materially. Recalibration cycles align with material shifts in Chinese infant formula import policy and European novel food assessment precedents.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
Anti-Spit Up Formula Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
Kids Food and Beverages Market
Baby Food and Infant Formula
Omega 3 Ingredients for Infant Food Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Baby Food and Infant Formula Market
Baby Food and Infant Formula
Japan Baby Food and Infant Formula Market