
 Parenteral Formula Market | 2026-2036
Parenteral Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Parenteral Formula Market Insights
EU MDR is rebalancing the cost-of-entry calculus for parenteral formula manufacturers seeking European market access. Baxter International leverages its vertically integrated IV solutions platform to sustain competitive manufacturing scale across multiple geographies. Fresenius Kabi anchors its position through specialized lipid emulsion formulations that dominate critical care nutrition channels. B. Braun Melsungen competes on integrated delivery systems that combine parenteral nutrition bags with infusion pumps.
Parenteral formula comprises sterile, complete or partial nutrient solutions delivered intravenously to patients with non-functional gastrointestinal tracts, typically containing dextrose, amino acids, lipids, electrolytes, vitamins, and trace elements in concentrations calibrated to metabolic requirements. Specialty parenteral formula commands premium positioning due to disease-specific formulations for renal failure, hepatic impairment, and metabolic stress, while standard parenteral formula remains the volume backbone of hospital formularies. Critical care nutrition represents the dominant application segment, with oncology support registering the fastest structural expansion as cancer centers expand ambulatory infusion services.
FDA oversight of 503B outsourcing facilities and EU MDR device-nutrition combination requirements create dual compliance architectures that favor manufacturers with dedicated regulatory affairs infrastructure and quality management systems. The country's national pharmaceutical regulator in Japan, PMDA, maintains distinct stability testing protocols for lipid emulsion products that constrain import flexibility. Stakeholders must monitor evolving USP compounding standards and their interface with ready-to-use commercial products to anticipate procurement shifts between hospital-compounded and manufacturer-supplied alternatives.

Market Dynamics
Hospital procurement departments are consolidating purchasing authority for ready-to-use parenteral nutrition bags, compressing vendor rosters and elevating infection control specifications as the primary selection criterion over unit cost.
Growth Catalysts
- Surgical Volume Expansion:Rising procedure counts in United States tertiary centers sustain institutional demand for perioperative parenteral nutrition support.
- EU MDR Compliance Thresholds:Device-nutrition combination requirements in Europe are filtering out subscale manufacturers and concentrating contract awards among quality-certified suppliers.
- Ambulatory Infusion Infrastructure:Oncology centers across Japan are expanding outpatient parenteral nutrition services, creating new channel pull for lipid emulsion formulations.
Market Restraints
- Soybean Oil Input Volatility:Lipid emulsion feedstock costs fluctuate with agricultural commodity markets, compressing margin predictability for manufacturers.
- Single-Source API Concentration:Amino acid active pharmaceutical ingredient supply clusters in China, exposing formulators to geopolitical supply interruption risk.
- Stability Testing Burden:Japan's PMDA maintains distinct shelf-life validation protocols that extend product registration timelines and deter import flexibility.
Strategic Opportunities
- Critical Care Specialization:Disease-specific formulations for hepatic and renal failure remain underdeveloped relative to metabolic stress applications, creating formulation white space.
- Outsourcing Facility Partnerships:FDA 503B guidance creates compliance pathways for hospital systems to access manufacturer-quality products without captive compounding infrastructure.
- Integrated Delivery Convergence:Smart infusion pump connectivity with parenteral nutrition bag barcoding is unifying administration safety systems in United States academic medical centers.
Industry Challenges
- Sterile Compounding Workforce Scarcity:Pharmacy technician training pipelines for aseptic technique lag hospital expansion of parenteral nutrition services.
- Legacy System Integration Friction:Electronic health record compatibility with automated compounder documentation creates workflow disruption during technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parenteral Formula Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Parenteral Formula, Specialty Parenteral Formula, Pediatric Parenteral Formula, Lipid Emulsion, Amino Acid Solutions Application: Critical Care Nutrition, Oncology Support, Neonatal Nutrition, Postoperative Recovery, Malnutrition Management End User: Hospitals, Home Healthcare Providers, Specialized Clinics, Long-Term Care Facilities, Ambulatory Surgical Centers Delivery Mode: Continuous Infusion, Intermittent Infusion, Bolus Injection, Patient-Controlled Infusion |
| Companies Covered | Baxter International, B. Braun Melsungen, Fresenius Kabi, Otsuka Pharmaceutical Factory, Grifols, Terumo, Sichuan Kelun Pharmaceutical, Aculife Healthcare, Nutricia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parenteral Formula Market Trends and Innovations
Product development in parenteral nutrition is converging on safety-engineered delivery systems and regulatory-compliant ready-to-use formats that reduce hospital compounding burden.
Multi-chamber bag technology is unifying previously separate macronutrient storage, enabling amino acid, dextrose, and lipid emulsion cohabitation without pre-administration mixing. United States health systems with high surgical throughput are adopting these formats fastest. This unification is compressing pharmacy labor allocation and reducing contamination risk exposure.
EU MDR device classification rules are reclassifying parenteral nutrition bags with integrated ports as Class IIb medical devices, triggering notified body involvement and clinical evaluation requirements. Manufacturers with existing IV therapy device portfolios are absorbing compliance costs across product lines. Critical care units in Germany and France are prioritizing MDR-certified suppliers in renewal negotiations.
Consolidated purchasing agreements are concentrating contract awards among suppliers offering comprehensive formulary coverage across standard and specialty parenteral nutrition lines. Group purchasing organizations in the United States are unbundling historically separate nutrition and fluid contracts. Academic medical centers in the Northeast and Midwest are most advanced in this procurement rationalization.
Parenteral Formula Market Segmentation

Parenteral formula segmentation reveals how regulatory pathways and clinical use cases fragment procurement strategies across healthcare settings. Product categories carry distinct certification burdens, while application and end-user dimensions determine pricing power and contract tenure.
Product Type:
Standard formulations face FDA 510(k) clearance pathways, while specialty and pediatric lines trigger PMA or HDE requirements that extend approval timelines.
- Standard Parenteral Formula:Complete macronutrient solutions with fixed dextrose-amino acid ratios for adult metabolic maintenance. Hospital formularies in the United States purchase these in highest volumes for perioperative support, with procurement offices prioritizing ready-to-use bag formats over compounding.
- Specialty Parenteral Formula:Disease-calibrated compositions for hepatic failure, renal impairment, or metabolic stress with modified electrolyte and amino acid profiles. Academic medical centers in Germany and France demand these for ICU nutrition protocols, with EU MDR Class IIb certification now mandatory for bag-plus-port configurations.
- Pediatric Parenteral Formula:Osmolality-adjusted solutions for neonatal and infant metabolic requirements.
- Lipid Emulsion:Soybean oil or alternative oil-source emulsions providing essential fatty acids and caloric density.
- Amino Acid Solutions:Protein hydrolysate or crystalline formulations for nitrogen replacement.
Standard parenteral formula sits at the top of the volume ranking, with specialty parenteral formula climbing the fastest.
Application:
Critical care and oncology applications command premium pricing due to extended treatment durations and specialized monitoring requirements.
- Critical Care Nutrition:ICU-based parenteral support for hemodynamically unstable patients with gastrointestinal failure. United States tertiary centers sustain the highest utilization rates, with surgical volume expansion driving formulary standardization around triple-chamber bag systems.
- Oncology Support:Ambulatory infusion services for cancer patients with mucositis, obstruction, or post-surgical gut dysfunction. Japan's expanding outpatient chemotherapy centers are pulling lipid emulsion demand fastest, with PMDA stability protocols shaping product registration strategies.
- Neonatal Nutrition:Low-birthweight infant metabolic support in NICU settings.
- Postoperative Recovery:Short-term perioperative nutrition for major abdominal or gastrointestinal surgery.
- Malnutrition Management:Home-based parenteral nutrition for chronic intestinal failure.
Critical care nutrition captures the largest revenue pool, while oncology support gains share fastest.
End User:
Procurement sophistication varies sharply across settings, with hospitals consolidating contracts while home care fragments across regional distributors.
- Hospitals:Integrated health systems with centralized pharmacy and nutrition committees. Group purchasing organizations in the United States are unbundling fluid and nutrition contracts, concentrating awards among suppliers with full formulary coverage.
- Home Healthcare Providers:Regional infusion services managing long-term parenteral nutrition for intestinal failure patients. Reimbursement complexity and nursing labor costs constrain margin structures.
- Specialized Clinics:Oncology and gastroenterology ambulatory centers with focused infusion capabilities.
- Long-Term Care Facilities:Skilled nursing settings with limited compounding infrastructure.
- Ambulatory Surgical Centers:Same-day surgery facilities with minimal parenteral nutrition utilization.
Hospitals dominate absolute volume, with home healthcare providers expanding most quickly.
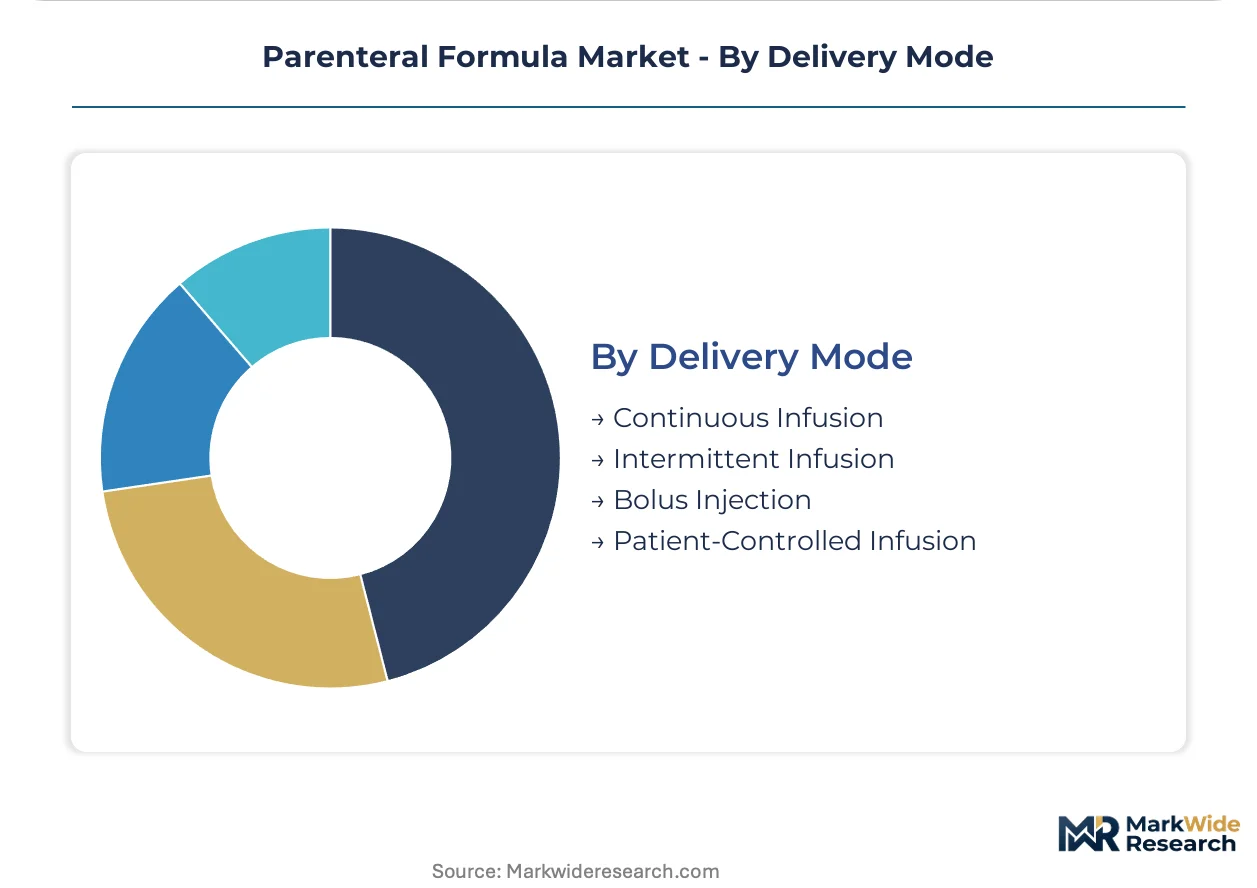
Delivery Mode:
Infusion methodology determines device compatibility and pharmacy labor allocation, with continuous formats requiring pump integration.
- Continuous Infusion:24-hour nutrient delivery via central venous access with electronic pump control. United States academic medical centers are converging on smart pump connectivity with barcoded bag verification.
- Intermittent Infusion:Cyclic delivery over 8-16 hours mimicking oral feeding patterns. Home healthcare settings prefer this mode for patient mobility and sleep normalization.
- Bolus Injection:Rapid manual administration for emergency or limited-access scenarios.
- Patient-Controlled Infusion:Self-administered bolus capability with lockout safeguards.
Continuous infusion maintains the highest utilization share, with intermittent infusion rising fastest in home care channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The parenteral formula industry traces its commercial origins to mid-20th century pharmaceutical development in the United States and Germany, where intravenous nutrition protocols first achieved standardized manufacturing scale.
United States
Tertiary surgical centers sustain the highest institutional procurement volumes for perioperative parenteral nutrition support. FDA 503B outsourcing facility guidance rebalances compliance burdens toward vertically integrated suppliers with dedicated quality infrastructure. Academic medical centers in the Northeast and Midwest are consolidating purchasing authority around infection-control specifications.
Germany
Critical care units in German university hospitals prioritize EU MDR Class IIb certified suppliers for bag-plus-port configurations in ICU nutrition protocols. The country's notified body involvement in clinical evaluation requirements filters subscale manufacturers from contract renewals. Manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia absorb compliance costs across IV therapy device portfolios.
Japan
Outpatient chemotherapy centers are expanding ambulatory parenteral nutrition services, pulling lipid emulsion demand through oncology channels. PMDA maintains distinct stability testing protocols for lipid emulsion products that constrain import flexibility and extend registration timelines. Tokyo and Osaka metropolitan areas concentrate the country's infusion infrastructure expansion.
France
Hospital procurement offices in Île-de-France and Auvergne-Rhône-Alpes prioritize MDR-certified suppliers in formulary renewal negotiations. ANSM oversight of device-nutrition combinations elevates quality certification as a primary selection criterion. Lyon and Paris academic hospital networks are standardizing around triple-chamber bag systems for surgical throughput.
China
Domestic amino acid active pharmaceutical ingredient supply clusters expose formulators to geopolitical interruption risk while sustaining cost-competitive manufacturing. NMPA regulatory pathways for sterile nutrition products favor manufacturers with captive API production. Sichuan and Jiangsu provinces host concentrated pharmaceutical manufacturing capacity for intravenous solutions.
Parenteral Formula Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with established IV therapy platforms. Baxter International, B. Braun Melsungen, and Fresenius Kabi occupy positions that span device and pharmaceutical boundaries, compressing vendor rosters through formulary breadth. Strategic moves concentrate on M&A for regulatory infrastructure acquisition and capacity expansion for ready-to-use bag formats.
Within the diversified conglomerate tier, Baxter International and Fresenius Kabi exemplify archetypes that leverage vertical manufacturing scale across multiple geographies. B. Braun Melsungen occupies a position emphasizing integrated delivery systems. Otsuka Pharmaceutical Factory and Grifols represent regional specialists with concentrated home-market positions. Sichuan Kelun Pharmaceutical anchors Chinese domestic supply for amino acid and electrolyte solutions.
| Leading Market Players |
|---|
| Baxter International |
| B. Braun Melsungen |
| Fresenius Kabi |
| Otsuka Pharmaceutical Factory |
| Grifols |
| Terumo |
| Sichuan Kelun Pharmaceutical |
| Aculife Healthcare |
| Nutricia |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement departments concentrated in United States academic medical centers and German university hospitals dictate contract structures through consolidated purchasing authority. Their specification of infection-control standards and EU MDR Class IIb certification requirements creates pricing stratification across quality tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified specialty formulations from standard ready-to-use bags and compounded alternatives. Price differentiation rests on certification grade and volume scale, with oncology and critical care applications commanding premiums. Pricing pressure stems from soybean oil feedstock volatility and API cost fluctuations. Home healthcare providers exhibit highest price sensitivity due to reimbursement constraints, while United States tertiary centers prioritize safety specifications over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle institutional demand through group purchasing organization contracts, while regional distributors serve fragmented home care markets. Geographic supply concentration centers on China for amino acid APIs, Germany for device-nutrition combinations, and Japan for lipid emulsion stability protocols. Manufacturing draws from soybean oil, crystalline amino acids, and multi-chamber bag films as critical inputs. Single-source API concentration in Chinese manufacturing clusters exposes formulators to geopolitical interruption risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate on ready-to-use bag formats that displace hospital compounding labor and capture premium positioning through EU MDR certification.
For Market Incumbents: Anchor formulary breadth across standard and specialty parenteral nutrition lines to defend against GPO contract consolidation. Deepen backward integration into amino acid API production to mitigate single-source concentration risk in China. Prioritize MDR certification investment for bag-plus-port configurations to maintain access to German and French academic hospital networks. For New Entrants and Emerging Players: E-commerce-enabled direct procurement platforms offer lower-friction access to mid-tier United States health systems bypassing traditional GPO structures. Target oncology ambulatory infusion services in Japan's expanding outpatient chemotherapy centers as the most penetrable segment. Lead with disease-specific hepatic and renal formulations where incumbent coverage remains thin. For Investors and Strategic Acquirers: Diversified medical technology conglomerates with IV therapy platforms are the most active acquirer in this space, seeking regulatory infrastructure and manufacturing scale. Long-term viability favors targets with captive API supply and MDR-ready quality systems. Monitor PMDA registration timelines for lipid emulsion products as an inflection indicator for Japanese market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Notified body involvement unlocks German and French ICU contract renewals. |
| Backward Integration into API Supply | Captive amino acid production mitigates China concentration risk. |
| Multi-Chamber Bag Manufacturing Scale-Up | Triple-chamber formats reduce pharmacy labor and contamination exposure. |
| Hospital System Partnership | Integrated delivery agreements with United States academic medical centers secure volume. |
| Reimbursement Strategy | CMS coding alignment for home parenteral nutrition expands addressable patient population. |
Research Methodology
Direct dialogue with hospital pharmacy directors, GPO contract managers, regulatory affairs leads, and critical care clinicians grounded qualitative findings in procurement decision-making realities. Secondary validation drew from FDA 503B guidance documents, EU MDR technical files, PMDA stability protocols, and hospital formulary databases. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, and end-user dimensions.
Segment-level value outputs combined volume projections with pricing intelligence across standard, specialty, and pediatric formulation tiers. The analytical framework incorporated surgical volume trajectories, ambulatory infusion infrastructure expansion, and regulatory compliance cost absorption throughout the forecast period. CAGRs derived from regression analysis of historical procurement patterns and elasticity estimates for infection-control specification premiums.
The model assumes a particular technology adoption path; alternative pathways for smart pump connectivity and barcode verification would alter the outlook for continuous infusion segment growth. Forecasts reflect assumptions regarding EU MDR implementation timelines and PMDA registration efficiency that geopolitical developments or regulatory backlog could revise. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
South America Organic Baby Food Market
Baby Food and Infant Formula
Baby Infant Formula Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Infant Formula Ingredients Market