
 Soy Drinks Market | 2026-2036
Soy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Drinks Market Analytics
North American organic soy processing capacity is realigning toward aseptic carton filling and extended shelf-life formats. Vitasoy International Holdings Ltd. leverages its Hong Kong manufacturing heritage to dominate Asian distribution networks. Alpro, operating under Danone S.A., anchors European refrigerated shelf space through branded plant-based portfolios. Eden Foods Inc. specializes in certified organic and non-GMO ingredient sourcing for premium health food channels.
Soy drinks are aqueous extracts of soaked, ground, and filtered soybeans, typically standardized to protein levels between 2.5% and 4.0% and homogenized for suspension stability. The product serves as a functional dairy milk alternative in direct consumption, barista applications, and infant nutrition extension products. Flavored and fortified variants command margin premiums in supermarkets and online retailers where health claims drive repeat purchase behavior. Tetra pack formats lead volume throughput in food service and institutional channels due to ambient distribution economics and reduced cold-chain dependency.
The FDA governs soy drink labeling and nutrient content claims under the Federal Food, Drug, and Cosmetic Act, while the USDA Organic seal shapes premium tier access. EFSA and national EU regulators enforce allergen disclosure and protein quality scoring under evolving plant-based beverage frameworks. China's SAMR monitors GB standard compliance for imported and domestically produced soy beverages. Stakeholders must track divergence between regional protein fortification rules and packaging recyclability mandates to avoid market access friction.
Market Dynamics
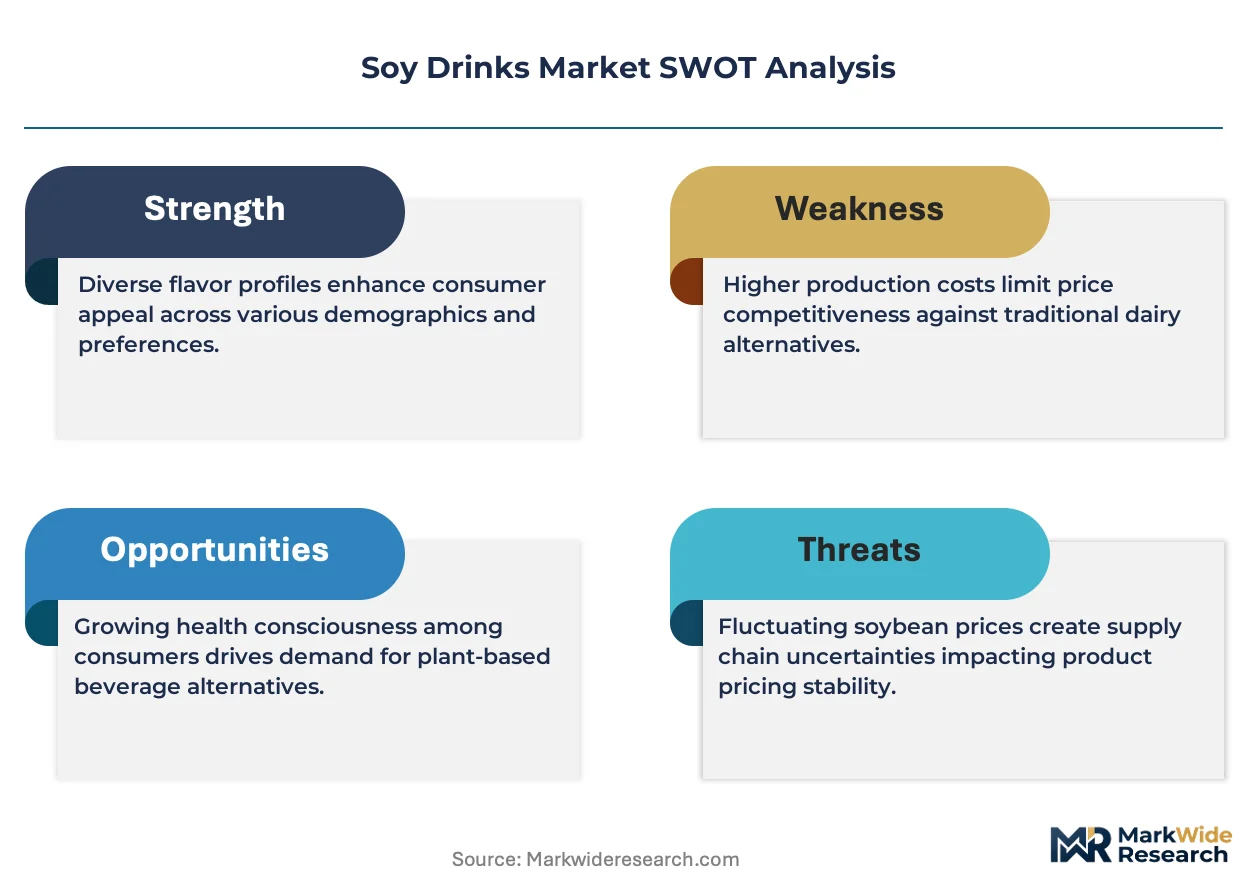
Plant-based beverage labeling harmonization is fragmenting across jurisdictions, forcing manufacturers to maintain parallel formulation and packaging specifications for shelf access in major economies.
Growth Catalysts
- Protein fortification mandates:China's GB standards for soy beverage nutrient density are accelerating reformulation investments among domestic processors seeking retail distribution licenses.
- Barista-grade functionality:Specialty coffee chains in metropolitan India are specifying high-protein soy bases for latte art stability, creating technical pull-through for homogenization equipment upgrades.
- Aseptic carton economics:Extended shelf-life formats are reducing cold-chain dependency in Southeast Asian food service channels where refrigerated logistics remain underdeveloped.
Market Restraints
- Soybean input volatility:Argentine and Brazilian harvest fluctuations are transmitting price instability to crushing margins and extract costs for beverage manufacturers.
- Allergen disclosure friction:EFSA's evolving protein quality scoring frameworks are creating compliance uncertainty for exporters targeting European Union retail channels.
- Oat and almond substitution:Neutral-flavored alternative bases are displacing soy in premium positioning across North American natural food retailers.
Strategic Opportunities
- Fortified infant nutrition extensions:China's SAMR is streamlining registration pathways for micronutrient-enriched soy beverages targeting pediatric dietary supplementation.
- Direct-to-subscription models:Urban Chinese consumers are adopting scheduled delivery platforms for ambient soy milk, bypassing traditional grocery intermediaries.
- Carbon labeling alignment:EU Green Deal corporate sustainability reporting requirements are creating first-mover advantage for processors with verified lifecycle assessments.
Industry Challenges
- Clean-label formulation expertise:Phosphate-free suspension stabilization requires enzymatic processing capabilities scarce among mid-scale manufacturers.
- Organic certification timelines:USDA Organic and EU organic equivalence negotiations are delaying multi-territory product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Drinks Market |
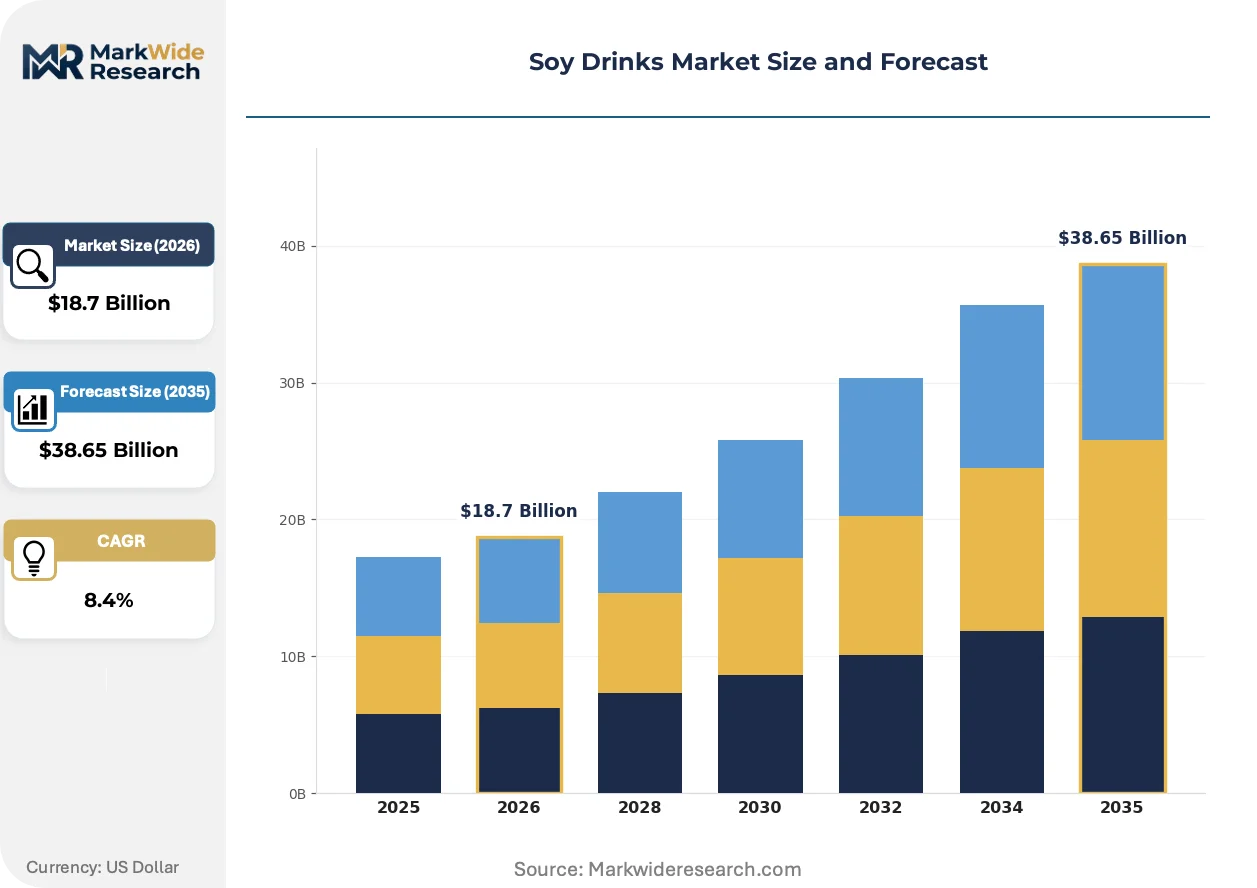
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Flavored, Unsweetened, Fortified Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Shops Packaging Type: Bottles, Tetra Packs, Cans, Pouches End User: Individual Consumers, Restaurants, Cafes, Food Services |
| Companies Covered | Vitasoy International Holdings Ltd., Earth’s Own Food Company Inc., Alpro (Danone S.A.), Eden Foods Inc., Pacific Foods of Oregon, LLC, Kikkoman Corporation, SunOpta Inc., The Hain Celestial Group, Inc., Morinaga Milk Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Drinks Market Evolving Landscape
Processing technology convergence and packaging format diversification are compressing production batch economics while expanding consumption occasions beyond traditional breakfast positioning.
High-pressure processing is consolidating quality assurance protocols across premium soy beverage lines. Cold-pressed extraction equipment suppliers are reporting accelerated adoption among North American organic processors seeking extended refrigerated shelf life without thermal degradation. This consolidation is compressing the technical gap between artisanal and industrial production scales.
REACH chemical safety registrations are reshaping European supply chain qualification requirements for imported soy protein isolates. Manufacturers sourcing Asian-origin ingredients face expanded documentation burdens for residual solvent testing. German and Dutch retail buyers are now requiring third-party verification as a condition of listing.
Subscription-based replenishment is displacing conventional supermarket purchasing among urban Chinese households. Digital-native brands are capturing recurring revenue through app-managed delivery schedules, while traditional processors struggle to integrate direct-to-consumer logistics. Shanghai and Beijing metropolitan clusters exhibit the highest penetration of this channel shift.
Soy Drinks Market Segmentation
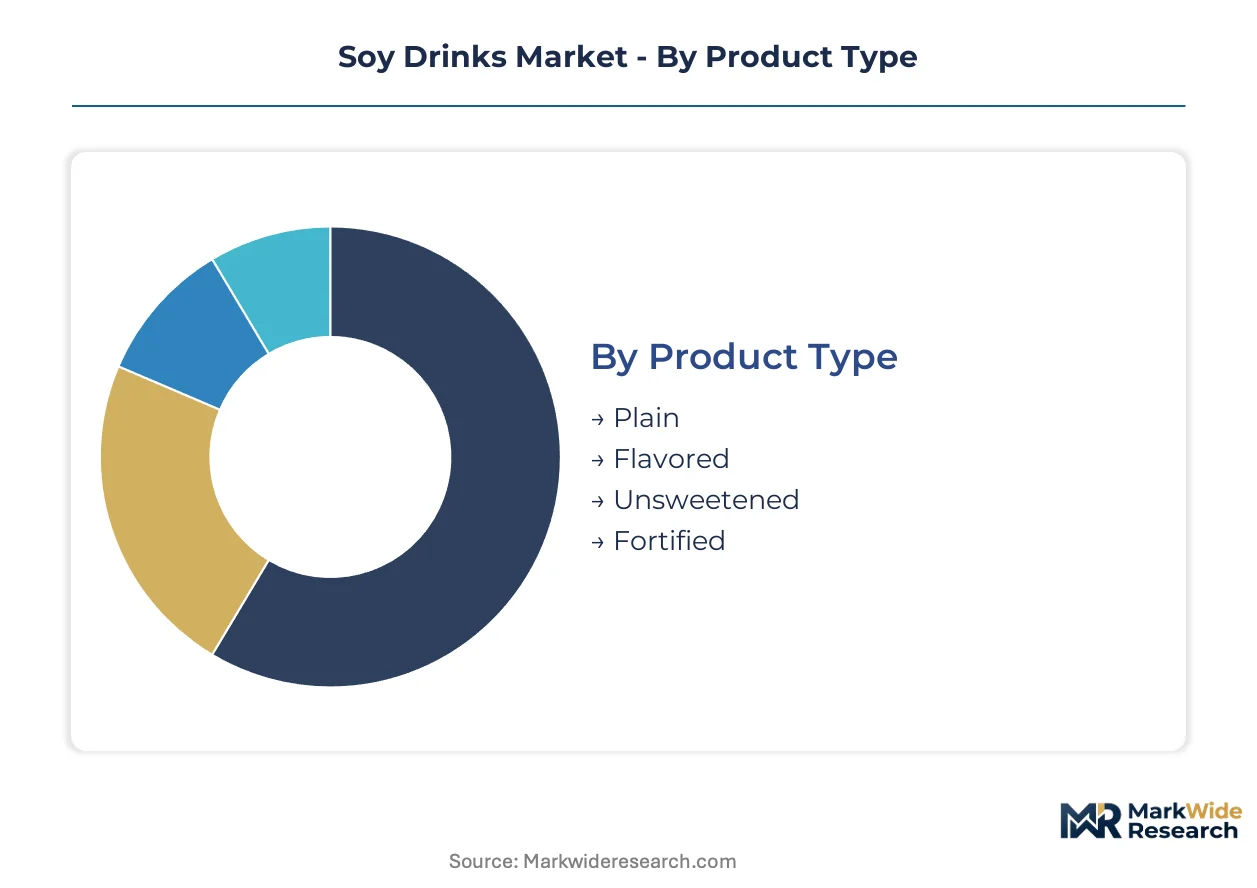
Soy drink manufacturers segment offerings to capture divergent purchasing logics across retail and food service channels. Technical specifications, packaging economics, and end-use functionality each create distinct margin profiles that shape portfolio prioritization.
Product Type:
Flavor and fortification choices signal health-positioning intent at the point of purchase.
- Plain:Unflavored formulations with 2.5-4.0% protein content serve as the cost baseline for price-sensitive households and industrial ingredient applications. Volume concentrates in Chinese urban retail where ambient cartons dominate household pantry stocking.
- Flavored:Vanilla, chocolate, and regional variants command shelf space premiums in North American refrigerated dairy aisles. Demand clusters around grab-and-go convenience positioning in metropolitan US and Canadian markets where taste masking drives trial conversion.
- Unsweetened:Zero-added-sugar positioning targets diabetic and low-glycemic dietary protocols. Chinese SAMR labeling requirements for sugar content claims are accelerating SKU proliferation in domestic supermarket chains.
- Fortified:Calcium, vitamin D, and B12 enrichment targets nutritional parity with dairy milk. Pediatric dietary supplementation registrations under China's streamlined SAMR pathways are expanding distribution into pharmacy and maternal health channels.
Volume sits with Plain; growth tilts toward Fortified.
Distribution Channel:
Channel selection determines cold-chain requirements and margin capture mechanics.
- Supermarkets:Refrigerated and ambient shelf placement in mass retail drives household penetration. Barista-grade functionality specifications from Indian specialty coffee chains are pulling high-protein formulations through modern trade formats in Mumbai and Bangalore.
- Health Food Stores:Certified organic and non-GMO positioning commands 30-50% price premiums. Eden Foods and comparable suppliers anchor premium placement in North American natural food cooperatives where ingredient transparency drives loyalty.
- Online Retailers:Direct-to-subscription platforms bypass traditional grocery intermediaries. Shanghai and Beijing metropolitan clusters exhibit the highest penetration of app-managed recurring delivery for ambient soy milk.
- Specialty Shops:Asian grocery formats and ethnic food retailers stock imported heritage brands. Vitasoy's Hong Kong manufacturing heritage dominates these channels through established distributor relationships.
Supermarkets capture absolute volume; Online Retailers are climbing the fastest.
Packaging Type:
Format economics align with shelf-life requirements and consumption occasion patterns.
- Tetra Packs:Aseptic carton technology enables ambient distribution with 6-12 month stability. Southeast Asian food service channels favor this format where refrigerated logistics remain underdeveloped.
- Bottles:PET and HDPE containers dominate refrigerated retail in North American and European markets. Extended shelf-life variants using high-pressure processing are compressing quality gaps with aseptic alternatives.
- Cans:Metal packaging serves vending machine and institutional food service applications. Limited penetration outside Japanese convenience retail and specific export markets.
- Pouches:Flexible packaging targets single-serve portability and school lunch programs. Emerging adoption in Chinese direct-to-consumer subscription models for portion-controlled delivery.
Tetra Packs hold installed volume; Bottles gain share fastest.
End User:
Application-specific functionality requirements fragment procurement specifications.
- Individual Consumers:Direct household consumption spans breakfast, cooking, and beverage replacement occasions. Urban Chinese and metropolitan Indian penetration is deepest where dairy alternatives have achieved cultural normalization.
- Restaurants:Bulk procurement of neutral-flavored bases for kitchen sauce and soup applications. EFSA allergen disclosure requirements are creating compliance friction for European food service distributors.
- Cafes:Barista-grade foam stability and latte art performance specifications. Indian specialty chains are driving technical pull-through for homogenization equipment upgrades among processor suppliers.
- Food Services:Institutional catering and hospitality procurement at volume price points. USDA Organic seal requirements shape premium tier access in North American school and hospital nutrition programs.
Individual Consumers dominate volume; Cafes show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentine and Brazilian soybean harvests anchor raw-material flows for beverage processors worldwide. Crushing margins in South America transmit directly to extract costs for manufacturers across Asia, Europe, and North America.
China
Urban households in Shanghai and Beijing drive ambient soy milk consumption through direct-to-subscription platforms. SAMR monitors GB standard compliance for protein fortification and labeling claims. The Yangtze River Delta concentrates processing capacity where domestic processors seek retail distribution licenses under tightening nutrient density rules.
United States
Refrigerated dairy aisles in metropolitan markets carry flavored and unsweetened variants targeting grab-and-go convenience. FDA labeling requirements under the Federal Food, Drug, and Cosmetic Act govern nutrient content claims. The Pacific Northwest anchors organic processing clusters where high-pressure processing equipment adoption is accelerating.
Germany
REACH chemical safety registrations reshape supply chain qualification for imported soy protein isolates. EFSA allergen disclosure requirements create compliance friction for exporters targeting EU retail channels. The North Rhine-Westphalia corridor hosts retail buyers demanding third-party verification for residual solvent testing.
India
Specialty coffee chains in Mumbai and Bangalore specify high-protein soy bases for latte art stability. FSSAI standards govern packaged food labeling and fortification claims. Metropolitan penetration runs deepest in southern and western states where dairy alternatives have achieved cultural normalization.
Japan
Metal-packaged variants serve vending machine and institutional food service applications. METI oversees food labeling and functional food claims under national standards. The Kanto region around Tokyo maintains heritage brand distribution through established convenience retail networks.
Soy Drinks Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and distribution network depth. The vendor base spans multinational food conglomerates, Asian heritage brands, and North American organic specialists. Three archetypes dominate: scale-driven dairy diversifiers, Asia-Pacific heritage manufacturers, and certified organic purists. Capacity expansion in aseptic carton filling and strategic partnerships for co-manufacturing represent the primary competitive vectors.
Among Asia-Pacific heritage manufacturers, Vitasoy International Holdings Ltd. exemplifies regional distribution dominance built on Hong Kong manufacturing origins. Within the organic specialist tier, Eden Foods Inc. occupies a position defined by certified ingredient sourcing protocols. At the scale-driven end, Alpro represents dairy conglomerate diversification into plant-based portfolios under European corporate ownership.
| Leading Market Players |
|---|
| Vitasoy International Holdings Ltd. |
| Earth's Own Food Company Inc. |
| Alpro (Danone S.A.) |
| Eden Foods Inc. |
| Pacific Foods of Oregon, LLC |
| Kikkoman Corporation |
| SunOpta Inc. |
| The Hain Celestial Group, Inc. |
| Morinaga Milk Industry Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap processors across East Asia anchor supply-side discipline through generational control of crushing assets and long-term offtake relationships with cooperatives. This ownership pattern insulates input costs from spot-market volatility while enabling premium pricing for heritage-branded ambient cartons in urban Chinese households.
Pricing Analysis
Extended shelf-life warranty bundling distinguishes aseptic carton formats from refrigerated alternatives that carry shorter freshness guarantees. Three-tier pricing structure across premium organic, standard fortified, and economy plain tiers reflects USDA Organic certification costs and protein fortification grade. Pricing pressure stems from oat and almond substitution in North American natural food retailers where neutral-flavored bases displace soy. Price-sensitive mass-market households in Chinese urban retail drive volume, while least-sensitive health food store patrons absorb 30-50% premiums for non-GMO verification.
Supply Chain Analysis
Domestic-content mandates under China's GB standards are reshaping sourcing patterns for protein isolates and fortification premixes. Raw material flows draw from Argentine and Brazilian crushing capacity, with secondary dependence on North American organic soybean premiums. Soybean input volatility, phosphate suspension stabilizers, and aseptic carton barrier materials constitute critical dependencies. Single-source vulnerability concentrates in South American harvest fluctuations that transmit directly to extract costs. Distribution runs through modern trade supermarkets in volume, with direct-to-subscription platforms capturing fastest growth in metropolitan China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic carton filling technology is displacing legacy refrigerated bottling infrastructure as extended shelf-life formats reduce cold-chain dependency across Southeast Asian food service channels.
For Market Incumbents: Lock in barista-grade formulation partnerships with Indian specialty coffee chains before homogenization equipment upgrades consolidate supplier relationships. Defend margin position through backward integration into organic soybean crushing in the Pacific Northwest, countering oat-milk substitution threats in North American natural food retail. Certification investment in EU Green Deal carbon labeling protocols creates first-mover access to sustainability-reporting-driven procurement. For New Entrants and Emerging Players: Urban Chinese subscription-platform households represent the most penetrable buyer archetype, bypassing traditional grocery intermediaries through app-managed recurring delivery. White-space targets include fortified infant nutrition extensions under China's streamlined SAMR registration pathways and phosphate-free clean-label formulations for premium health food channels. Go-to-market execution should prioritize direct-to-consumer logistics integration over conventional distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor certified organic specialists with established USDA equivalence documentation in North American premium channels. Long-term viability hinges on 5-10 year protein fortification mandate expansion across Asian regulatory frameworks. Acquisition targets should demonstrate enzymatic processing capabilities for clean-label suspension stabilization. The signal to watch is EU organic equivalence negotiation timelines that currently delay multi-territory launches.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Carton Capacity Expansion | Extended shelf-life formats reduce cold-chain dependency in Southeast Asian food service channels where refrigerated logistics remain underdeveloped. |
| Backward Integration into Organic Crushing | Pacific Northwest processing clusters secure non-GMO soybean supply against Argentine and Brazilian harvest volatility transmission. |
| Barista-Grade Formulation Partnerships | Indian specialty coffee chains in Mumbai and Bangalore drive technical specifications for high-protein bases with latte art stability. |
| Carbon Labeling Certification Investment | EU Green Deal corporate sustainability reporting requirements create procurement advantage for processors with verified lifecycle assessments. |
| Direct-to-Consumer Platform Launch | Shanghai and Beijing metropolitan clusters exhibit highest penetration of app-managed recurring delivery for ambient soy milk. |
Research Methodology
Document review covered trade customs data, SEC filings from publicly traded processors, and GB standard compliance records, complemented by interviews with plant-based beverage R&D directors, supermarket category buyers, and aseptic packaging equipment suppliers. Secondary validation drew from FDA labeling guidance documents, EFSA allergen disclosure frameworks, and SAMR registration pathway announcements. Bottom-up volume modeling triangulated against top-down category spend estimates.
Segment-level projections across product type, distribution channel, packaging format, and end-user application fed into analytical framework outputs across the analysis window. CAGRs were derived from regression-based trending of historical volume trajectories adjusted for protein fortification mandate acceleration and barista-grade functionality specification expansion. Industry-specific inputs included homogenization equipment upgrade cycles and organic certification equivalence negotiation timelines.
Revisions become necessary when South American harvest fluctuations exceed historical variance bands or when EU protein quality scoring frameworks diverge from current EFSA consultation drafts. Forecasts reflect documented assumptions regarding regulatory pathway streamlining and cold-chain infrastructure development rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
US and Canada Tonic Water Market
Beverages
Tonic Water Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Canned Beverages Market
Beverages
South America Dairy Based Beverages Market
Beverages
North America Fruit Juice Market
Beverages
India Cafes & Bars Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Europe Bottled Water Market
Beverages
Global Squash Drinks Market
Beverages
Wellness Water Market
Beverages
Bubble Food and Beverages Market
Beverages
Mixers Market
Beverages
Powdered Beverages Market
Beverages
South America Bottled Water Market