
 Ready to Drink Margarita Market | 2026-2036
Ready to Drink Margarita Market Size, Share, and Industry Trends Forecast 2026-2036
Ready to Drink Margarita Market Analytics
Multi-pack bundling of assorted flavors is broadening buyer choice in the ready-to-drink margarita aisle. Diageo leverages its global distribution network to secure premium placement in major retail chains. Jose Cuervo anchors its position through deep tequila heritage and brand recognition among casual consumers. Cutwater Spirits differentiates via craft positioning and flavor innovation in the canned cocktail segment.
Ready to drink margaritas comprise pre-mixed alcoholic beverages combining tequila, citrus, and sweetener in shelf-stable formats, typically bottled at 10-15% ABV for immediate consumption without bartending equipment. The manufacturing process involves batch blending, pasteurization or cold-fill stabilization, and nitrogen dosing to preserve freshness during distribution. Flavored variants command expanding shelf space as retailers chase incremental turns, while cans outpace bottles in velocity within convenience and grocery channels. Online retail captures outsized growth among Millennial and Gen X cohorts prioritizing subscription replenishment and discovery.
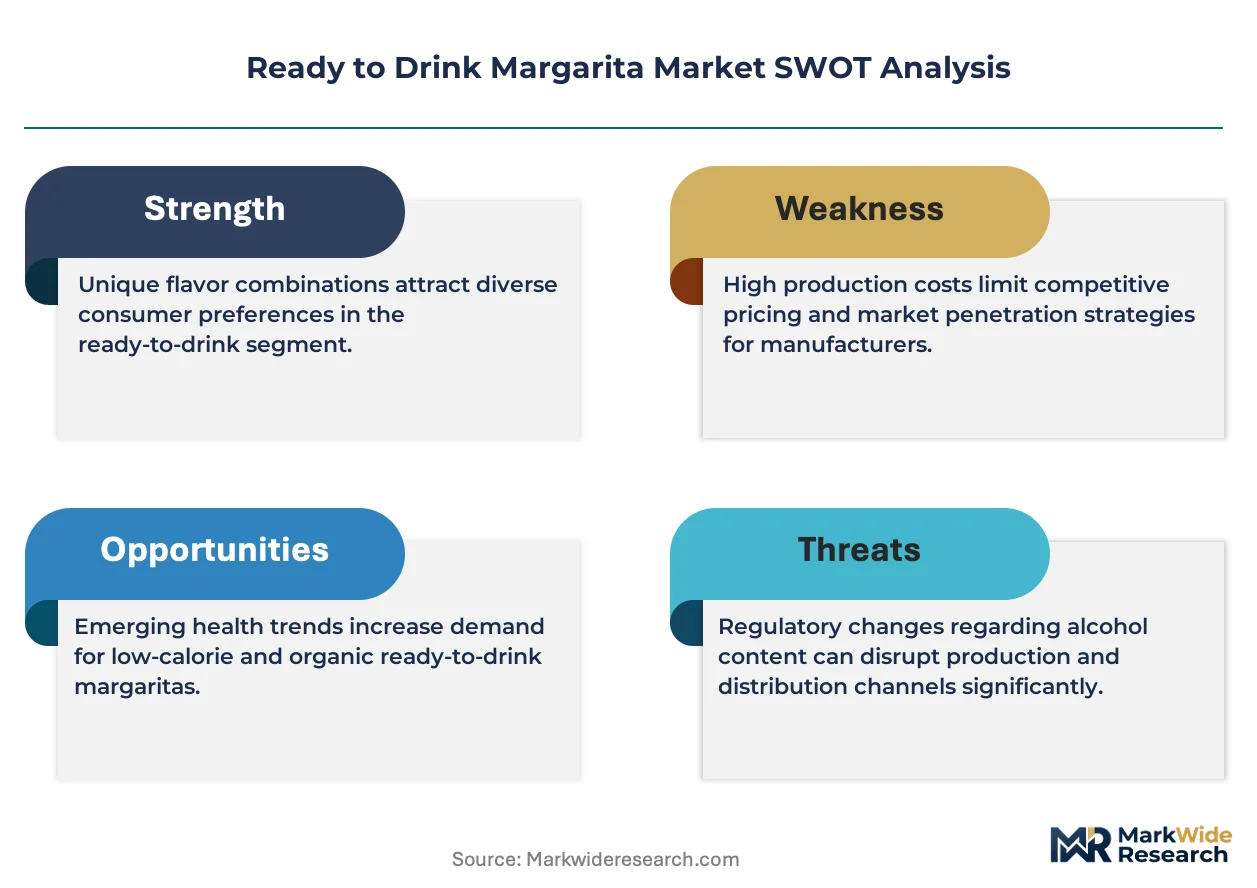
The US TTB mandates formula approval and COLA certification before interstate commerce, extending launch timelines for new SKUs. FDA oversees allergen labeling and nutritional disclosure requirements that influence packaging design and consumer communication strategies. State-level alcohol beverage control boards impose additional tier-system restrictions affecting direct-to-consumer shipping eligibility. Stakeholders must monitor evolving state-by-state distribution reforms and TTB guidance on hemp-derived additives that could reshape permissible ingredient decks.
Market Dynamics
The ready to drink margarita category is experiencing a structural compression between convenience-driven volume expansion and regulatory certification timelines that elongate new product introductions. TTB formula approval processes create a 4-6 month gate that separates formulation innovation from shelf availability, privileging established portfolios with approved SKUs.
Growth Catalysts
- Millennial cohort preference:Urban consumers aged 28-43 prioritize grab-and-go formats over at-home mixing, expanding the addressable occasion set from parties to commuting and outdoor recreation.
- TTB streamlined COLA pathways:Pre-approved flavor modifications for base tequila formulas reduce recertification burdens for line extensions, accelerating seasonal rotation programs.
- Nitrogen dosing technology:Cold-fill stabilization without thermal pasteurization preserves volatile citrus aromatics, enabling cleaner ingredient declarations that align with clean-label retail mandates.
Market Restraints
- Agave supply concentration:Jalisco highlands and Tamaulipas lowlands supply 85% of blue weber agave, exposing cost structures to harvest-cycle volatility and climate-induced yield compression.
- Three-tier distribution lock-in:State beverage control boards mandate wholesaler intermediation, blocking direct-to-consumer shipping in 35 states and capping margin capture for craft entrants.
- Glass-to-aluminum conversion capex:Bottling line retrofits for slim-can formats require $2-4 million per facility, consolidating production among capitalized national brewers.
Strategic Opportunities
- Subscription replenishment channels:DTC platforms in permissive states bypass slotting fee barriers, capturing lifetime value through auto-replenishment algorithms tuned to consumption velocity.
- Hemp-derived additive frameworks:Evolving TTB guidance on cannabinoid infusions could unlock functional positioning claims currently prohibited under standard malt-beverage regulations.
- Non-traditional retail penetration:Fitness studios, airport lounges, and hotel minibars represent unsaturated points of interception for premium single-serve formats.
Industry Challenges
- Flavor chemist talent scarcity:Formulation expertise bridging tequila stability, citrus oxidation prevention, and sugar-alcohol balance concentrates among a handful of beverage consulting groups.
- State-by-state label compliance:California Prop 65 warnings, New York bottle deposit requirements, and Texas volume restrictions fragment packaging runs and inflate SKU complexity.
- Cold-chain integrity gaps:Ambient-distribution networks degrade sensory quality in heat-stressed markets, requiring nitrogen-flush investments that smaller brands cannot amortize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready to Drink Margarita Market |
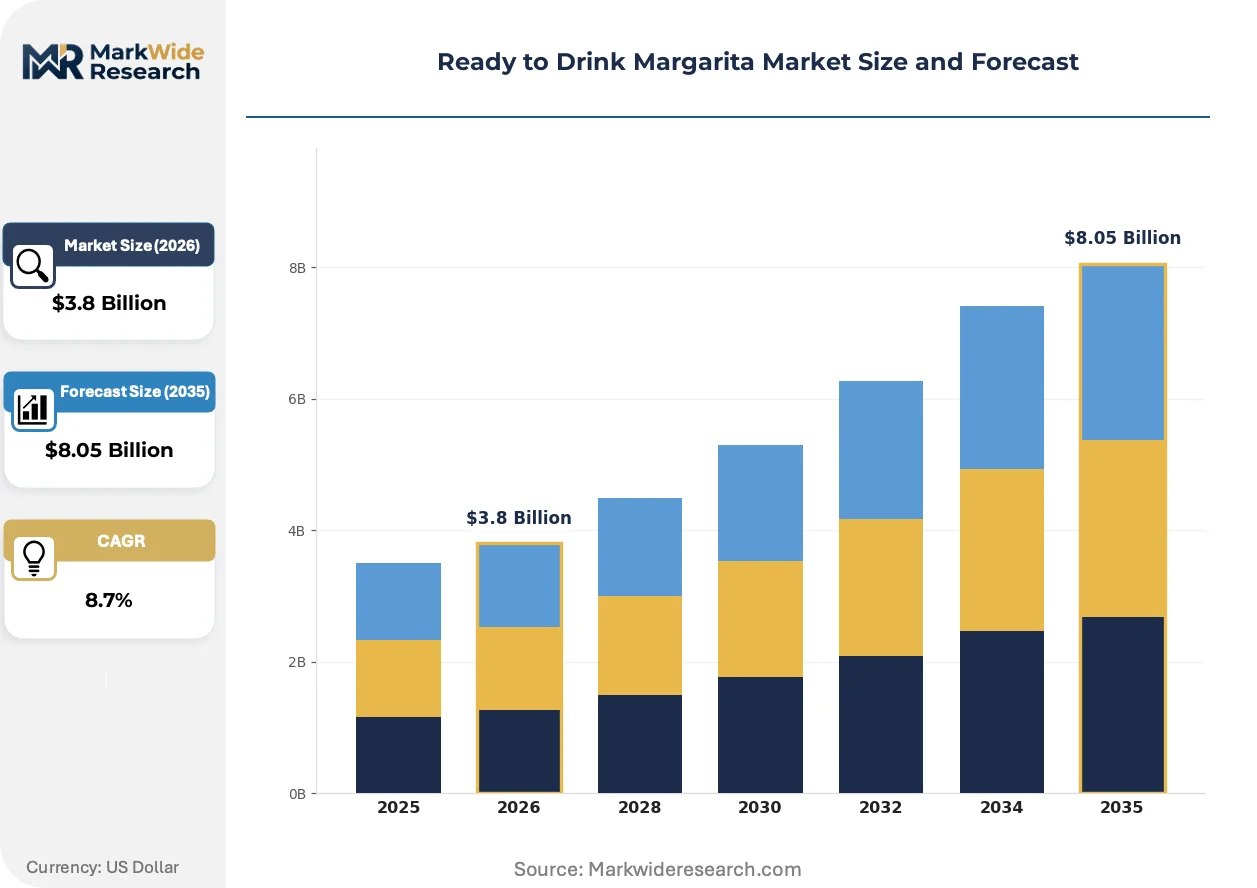
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Flavored, Organic, Low Calorie Packaging Type: Cans, Bottles, Pouches, Kegs Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Liquor Stores Customer Type: Millennials, Gen X, Event Planners, Casual Consumers |
| Companies Covered | Diageo, Bacardi Limited, Jose Cuervo, Cutwater Spirits, 1800, On The Rocks, Rancho La Gloria, Zing Zang, Tia Linda’s, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready to Drink Margarita Market Evolving Landscape
Product architecture is fragmenting into occasion-specific formats that trade alcohol by volume for portability and discretion. Manufacturers are reconfiguring liquid chemistry and packaging geometry simultaneously to capture marginal drinking moments previously served by beer or spirits.
Aseptic cold-fill technology is modularizing production economics for mid-scale entrants. Regional craft distilleries in Texas and California are adopting skid-mounted nitrogen-dosing systems that slot into existing bottling halls without dedicated canning lines. This equipment flexibility collapses minimum efficient scale thresholds, enabling 10,000-case production runs that previously required 50,000-case commitments to contract packers.
TTB guidance on hemp-derived cannabinoids is forcing reformulation contingency planning across the innovation pipeline. Brands are developing parallel SKU architectures—one compliant with current standards, one awaiting regulatory clarity—that double R&D overhead but position first-mover advantage if Schedule III reclassification proceeds. The uncertainty most acutely affects flavor houses supplying both alcoholic and adjacent functional beverage categories.
Discovery purchasing is migrating from retail aisle to algorithmic curation. Millennial and Gen X buyers rely on subscription platform recommendation engines rather than shelf visibility, compressing the traditional role of slotting fees and end-cap placement. This behavioral shift concentrates volume among platforms with robust personalization infrastructure, disadvantaging brands dependent on impulse conversion in physical channels.
Ready to Drink Margarita Market Segmentation
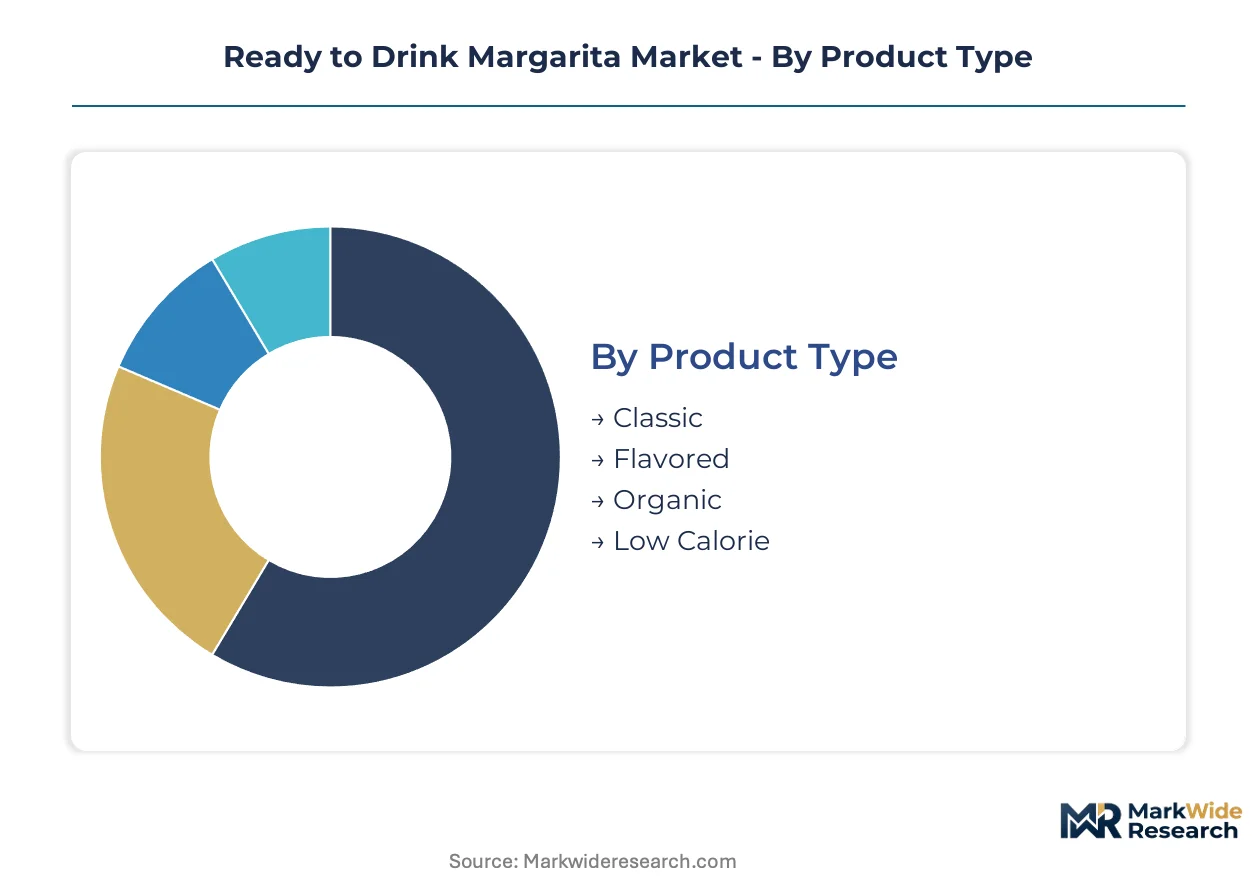
Segmentation in the ready-to-drink margarita category reveals how occasion specificity and channel economics fragment what appears as a single beverage market. Understanding these divides exposes where margin pools concentrate and which format innovations command disproportionate shelf investment.
Product Type:
Volume leadership sits with familiar taste profiles, while premium expansion concentrates in health-positioned variants that trade alcohol efficiency for permissibility.
- Classic:Traditional lime-forward formulations at 10-15% ABV anchor supermarket placement and repeat purchase rates. Demand clusters in Texas, California, and Florida, where established tequila heritage brands dominate refrigerated sets and drive seasonal velocity spikes.
- Flavored:Mango, strawberry, and watermelon extensions capture trial-oriented buyers seeking variety without bartending complexity. Concentrated growth in urban convenience channels and music festival vending, where visual packaging differentiation triggers impulse selection.
- Organic:USDA-certified agave and citrus inputs appeal to clean-label adherents in coastal metropolitan markets. Positioned at 40-60% price premiums in specialty grocers.
- Low Calorie:Sub-100-calorie formulations using alternative sweeteners expand among fitness-adjacent consumers. Distribution concentrates in club stores and subscription platforms with nutritional filtering.
Today's leader: Classic. Tomorrow's challenger: Low Calorie.
Packaging Type:
Aluminum displacement of glass is restructuring manufacturing capital requirements and cold-chain economics simultaneously.
- Cans:Slim 12-ounce and 16-ounce aluminum formats dominate convenience store velocity and outdoor occasion penetration. Nitrogen-dosed cold-fill lines preserve volatile aromatics without pasteurization heat damage.
- Bottles:Glass and PET containers retain premium positioning in liquor stores and restaurant takeaway, where transparency signals quality. Higher shipping cube costs limit e-commerce viability.
- Pouches:Flexible film formats enable single-serve portability for beach, pool, and stadium venues with strict glass prohibitions. TTB label compliance challenges constrain design flexibility.
- Kegs:Stainless steel and disposable bag-in-box systems serve event catering and hospitality pre-batch needs. Volume concentrates in resort corridors and wedding venue clusters.
Cans capture the steepest expansion trajectory as retailers reallocate refrigerated linear footage from bottles.
Distribution Channel:
Channel selection determines margin capture versus brand building tradeoffs, with three-tier system constraints fragmenting direct access.
- Online Retail:Subscription platforms and alcohol delivery apps bypass slotting fee barriers in permissive states. Auto-replenishment algorithms concentrate volume among digitally native brands with robust customer data infrastructure.
- Supermarkets:Grocery chains command the largest absolute volume through multi-pack displays and seasonal promotional cycles. TTB COLA certification requirements extend lead times for SKU authorization.
- Convenience Stores:Immediate consumption occasions drive single-serve can velocity at premium per-ounce pricing. Refrigerated door space competition with beer and seltzer intensifies.
- Liquor Stores:Controlled-state outlets and independent retailers preserve higher-ABV and premium-format distribution. Staff recommendation influence sustains brand discovery outside mass advertising.
Supermarkets anchor current volume. Online retail is gaining share fastest through generational purchasing migration.
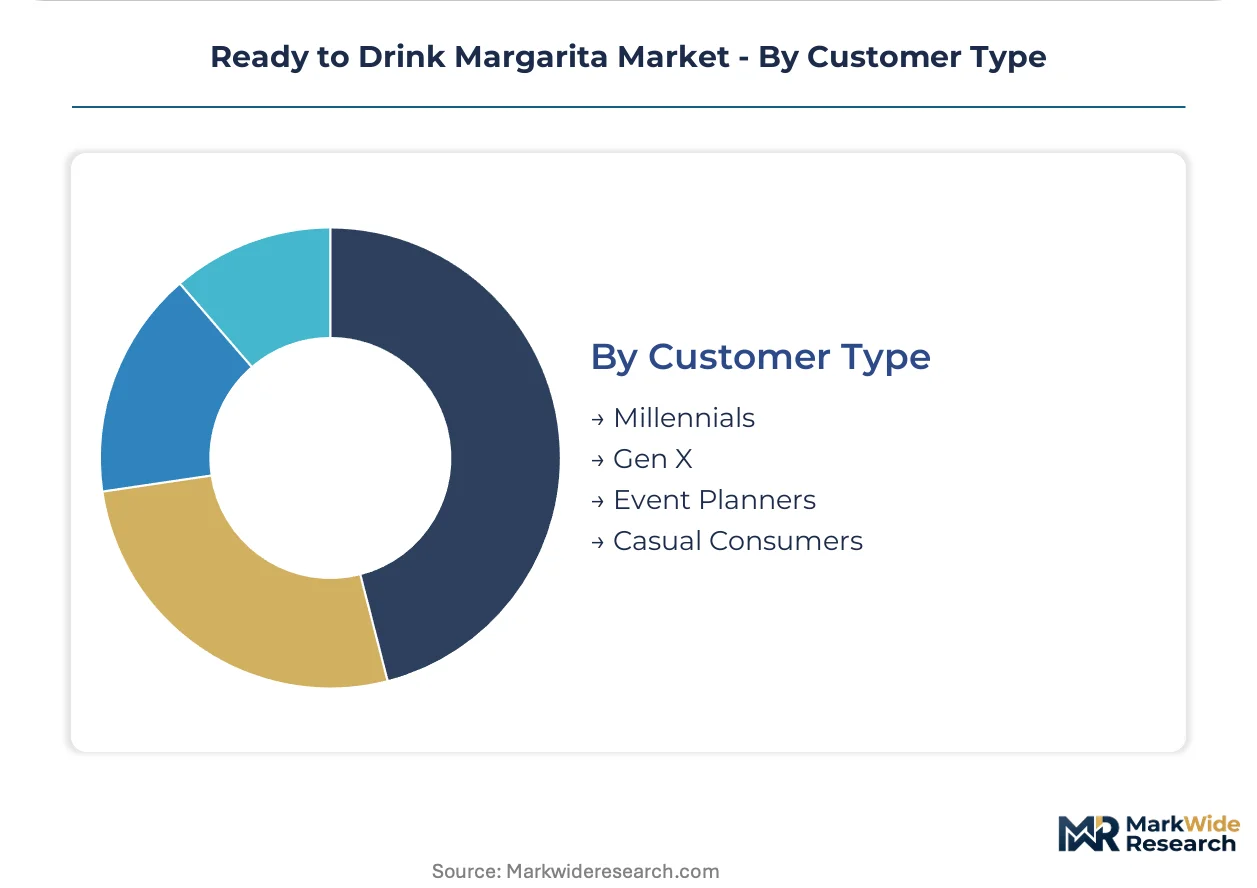
Customer Type:
Generational cohorts diverge sharply in discovery behavior, with platform-native buyers abandoning aisle-based selection entirely.
- Millennials:Urban consumers aged 28-43 prioritize grab-and-go formats and flavor experimentation. Discovery occurs through social platform curation and subscription algorithm recommendations rather than retail visibility.
- Gen X:Buyers aged 44-59 balance convenience with established brand trust, sustaining heritage tequila label loyalty. Concentrated in suburban supermarket and club store channels.
- Event Planners:Corporate and social occasion coordinators demand keg and bulk-format reliability with consistent quality. Procurement runs through beverage distributors with venue relationships.
- Casual Consumers:Infrequent, occasion-driven purchasers respond to promotional pricing and seasonal packaging. Lowest lifetime value but highest trial conversion sensitivity.
Millennials drive premium mix shift. Event Planners deliver the most predictable bulk volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's tequila heritage established the foundation for ready-to-drink margarita production, with Jalisco's agave cultivation regions supplying the raw material base that now supports manufacturing across North American and European markets.
United States
Millennial urban consumers in Texas, California, and Florida drive volume through convenience channels and subscription platforms. The TTB enforces formula approval and COLA certification requirements that extend new product launch timelines by 4-6 months. Austin and San Diego host concentrated craft distilling clusters where nitrogen-dosing cold-fill technology enables smaller production runs.
Mexico
Jalisco highlands and Tamaulipas lowlands supply 85% of blue weber agave, creating supply concentration that exposes cost structures to harvest-cycle volatility. The Mexican government's Denominación de Origen regulations protect tequila authenticity standards and restrict production geography. Guadalajara anchors contract manufacturing capacity serving export markets.
Canada
Provincial liquor control boards in Ontario, Quebec, and British Columbia govern distribution through government retail monopolies that limit direct-to-consumer shipping. Health Canada oversees nutritional labeling and allergen disclosure requirements affecting packaging design. Toronto and Vancouver concentrate premium import demand through specialty retailers.
Germany
Discerning consumers in Berlin, Munich, and Hamburg demonstrate receptivity to organic-certified and low-calorie variants at 40-60% price premiums. The BfR (Federal Institute for Risk Assessment) evaluates novel food ingredients including alternative sweeteners used in reduced-calorie formulations. Hamburg's beverage logistics hub facilitates distribution across Northern European markets.
United Kingdom
London's on-trade channel and supermarket multiples drive canned format adoption among urban professionals aged 28-43. The Portman Group's code of practice on alcohol marketing influences packaging design and promotional restrictions. Manchester and Birmingham expand refrigerated retail sets as grocers reallocate linear footage from beer to ready-to-serve cocktails.
Ready to Drink Margarita Market Competitive Landscape
Premium-margin players sit above commodity-margin players across distribution access and brand heritage dimensions, with heritage tequila labels commanding superior slotting fee recovery and seasonal promotional support. The vendor base concentrates among multinational spirits conglomerates with approved TTB formula portfolios and regional craft distilleries leveraging localized production flexibility. Three strategic archetypes dominate: global spirits houses with integrated tequila supply chains, craft-positioned specialists emphasizing flavor innovation, and contract-manufactured private labels serving retail-owned brands. Competitive moves center on M&A activity targeting craft distilleries with approved formulations and strategic partnerships with nitrogen-dosing equipment suppliers to collapse minimum efficient scale thresholds.
Within the heritage-tier segment, Diageo and Jose Cuervo occupy positions that exemplify contrasting approaches to tequila authenticity and mass-market accessibility. Cutwater Spirits represents the craft-specialist archetype, differentiating through flavor innovation in canned formats. Among these named entities, geographic origin spans London-based multinational structure, Mexican family-owned heritage, and California craft positioning respectively.
| Leading Market Players |
|---|
| Diageo |
| Bacardi Limited |
| Jose Cuervo |
| Cutwater Spirits |
| 1800 |
| On The Rocks |
| Rancho La Gloria |
| Zing Zang |
| Tia Linda's |
| Others |
Value Network & Pricing Analysis
Blue weber agave harvest cycles in Jalisco and Tamaulipas transmit cost volatility through three distinct pricing tiers, with premium heritage brands capturing margin insulation while contract-manufactured private labels absorb commodity squeezes. The concentration of raw material sourcing in Mexico's highlands creates asymmetric pricing power that favors vertically integrated tequila houses over craft entrants dependent on spot agave markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by brand heritage and distribution channel access. Price differentiation rests on TTB formula approval status and nitrogen-dosing production capability, with certified heritage labels commanding 40-60% premiums in liquor stores. Cost compression in the economy tier is intensifying because agave supply volatility and aluminum can conversion capex consolidate production among capitalized national brewers. Casual consumers in convenience channels exhibit highest price sensitivity, while event planners and subscription subscribers demonstrate lowest elasticity due to quality consistency requirements.
Supply Chain Analysis
Single-source vulnerability sits with Jalisco highlands agave cultivation, where Denominación de Origen regulations restrict production geography to five Mexican states. Raw material sourcing draws from blue weber agave, aluminum can sheet, and nitrogen-dosing equipment suppliers concentrated in Mexico, the United States, and Germany respectively. Supply chain risk centers on climate-induced yield compression in the 8-10 year agave maturation cycle. Distribution runs through mandated three-tier wholesaler intermediation in 35 US states, capping direct margin capture and fragmenting cold-chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ready to drink margarita market functions as a regulatory compounder, where TTB COLA certification timelines create durable moats that privilege incumbents with approved SKU portfolios. Streamlined pre-approved flavor modification pathways accelerate seasonal rotation programs, entrenching formula-rich heritage houses.
For Market Incumbents: Acquire nitrogen-dosing cold-fill equipment suppliers to collapse minimum efficient scale thresholds and block craft competitor production access. Secure long-term agave offtake agreements in Jalisco highlands to lock in cost structures against harvest-cycle volatility. The three-tier distribution lock-in threatens margin compression; counter by building direct-to-consumer subscription infrastructure in permissive states.
For New Entrants and Emerging Players: Fitness-adjacent consumers seeking sub-100-calorie formulations represent the most penetrable buyer archetype underserved by heritage brands' full-calorie portfolios. Target organic-certified positioning in coastal metropolitan markets where 40-60% price premiums sustain niche economics. Pursue skid-mounted production systems enabling 10,000-case runs without contract packer commitments as the go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where craft distilleries hold approved TTB formulations but lack capital for canning line retrofits. Long-term viability favors targets with dual competencies in tequila stability chemistry and citrus oxidation prevention. The signal to watch is evolving TTB guidance on hemp-derived cannabinoids, which could unlock functional positioning claims and reshape permissible ingredient decks.
| Strategic Initiative | Industry Significance |
|---|---|
| TTB Formula Portfolio Expansion | Pre-approved flavor modifications accelerate seasonal SKU rotation against 4-6 month certification gates. |
| Nitrogen-Dosing Equipment Partnership | Cold-fill technology access collapses minimum efficient scale thresholds for mid-scale entrants. |
| Subscription Platform Infrastructure | Auto-replenishment algorithms capture Millennial lifetime value outside three-tier distribution constraints. |
| Agave Supply Vertical Integration | Long-term offtake agreements in Jalisco hedge harvest-cycle volatility and secure cost predictability. |
| Non-Traditional Retail Penetration | Fitness studios and airport lounges represent unsaturated points of interception for premium single-serve formats. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with TTB officials, beverage distribution executives, craft distillery operators, and nitrogen-dosing equipment suppliers alongside secondary validation. Secondary sources encompassed TTB COLA certification databases, FDA allergen labeling guidance, state beverage control board distribution regulations, and Nielsen retail velocity data. Bottom-up SKU-level volume tracking and top-down category expenditure analysis triangulated market sizing.
Segment-weighting approaches distributed volume and value across product type, packaging format, distribution channel, and customer cohort dimensions throughout the forecast period. CAGRs derived from historical velocity patterns and projected channel shift assumptions, with specific inputs including agave harvest cycle modeling and generational purchasing behavior migration rates.
Underlying measurement precision varies by segment; online retail and subscription platform data carry tighter precision than informal hospitality channel estimates. Forecasts reflect documented assumptions about TTB regulatory stability, three-tier distribution persistence, and aluminum packaging conversion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
GCC Bottled Water Market
Beverages
Carbonated Soft Drinks Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
Blackstrap Molasses Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Beverage Premix Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Soft Serve Premix Market
Beverages
Baby Drinks Market
Beverages
Global Vinegar Market
Beverages
Fermented Foods and Beverages Market
Beverages
Italy Probiotic Drinks Market
Beverages
Premium Bottled Water Market
Beverages
Ginger Ale Market
Beverages
Water Bottle Market
Beverages
Chocolate Powdered Drinks Market