
 Molecular Microbiology Market | 2026-2036
Molecular Microbiology Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Microbiology Market Foresight
Direct distribution to hospital laboratories is tilting toward consolidated procurement networks managed by group purchasing organizations. bioMérieux leverages its syndromic panel portfolio to anchor relationships with large health systems in France and the United States. Thermo Fisher Scientific sustains competitive positioning through backward integration into reagent chemistry and instrument firmware. QIAGEN specializes in sample preparation automation, occupying a narrow but defensible position upstream of most molecular workflows.
Molecular microbiology encompasses the detection, identification, and characterization of microorganisms through nucleic acid amplification, hybridization, and sequencing techniques, typically operating at sensitivity thresholds of 10–100 copies per reaction for pathogen detection. Its primary commercial purpose centers on accelerating diagnostic turnaround for bloodstream infections, respiratory panels, and antimicrobial resistance profiling in clinical and public health settings. Reagents capture recurring revenue streams with margin profiles superior to capital equipment, while next-generation sequencing displaces Sanger platforms in reference laboratories handling outbreak surveillance. Clinical diagnostics absorbs the majority of installed base utilization, though food safety applications are gaining traction among contract testing laboratories serving multinational processors.
The FDA oversees premarket notification and clinical trial design for molecular diagnostic devices under its IVD framework, while the EMA coordinates centralized assessments for companion diagnostics and high-risk infectious disease assays across EU member states. ISO 15189 accreditation requirements for medical laboratories shape instrument validation protocols and quality management expectations in both regulated markets. Stakeholders must monitor evolving reimbursement pathways for multiplex PCR panels and prepare for MDR-driven conformity reassessments that will compress commercialization timelines for European launches.
Market Dynamics
The FDA's accelerated pathway for nucleic acid-based diagnostics is compressing product development timelines while simultaneously fragmenting competitive positioning between rapid point-of-care developers and centralized laboratory platforms.
Growth Catalysts
- EU IVDR transition:The European Union's In Vitro Diagnostic Regulation is forcing early movers to capture market share through MDR-driven conformity reassessments before smaller competitors complete technical documentation.
- Syndromic panel expansion:Hospital laboratories in the United States are expanding respiratory and bloodstream infection menus to reduce time-to-result for sepsis protocols.
- Antimicrobial resistance surveillance:Public health reference laboratories across Germany, China, and France are deploying next-generation sequencing for outbreak tracing and resistance gene mapping.
Market Restraints
- Reagent supply concentration:Polymerase and oligonucleotide production clusters in southern Germany and coastal China create geographic vulnerability for manufacturers dependent on just-in-time chemistry.
- Capital intensity barriers:Instrument placement cycles require 18-24 month validation timelines at academic medical centers, locking out mid-tier diagnostic firms without balance sheet depth.
- Workflow integration friction:Laboratory information system compatibility gaps between legacy middleware and cloud-based analysis platforms delay adoption at integrated delivery networks.
Strategic Opportunities
- Food safety testing expansion:Contract laboratories serving multinational protein processors in Brazil and Australia are adopting pathogen detection workflows previously confined to clinical settings.
- Sample preparation automation:Magnetic bead-based nucleic acid extraction is converging with liquid handling robotics to create walk-away systems for understaffed hospital microbiology departments.
- China NMPA pathway:The National Medical Products Administration's streamlined Class III diagnostic review process is opening registration opportunities for multiplex PCR panels.
Industry Challenges
- Bioinformatics talent scarcity:Clinical laboratories lack computational biologists capable of interpreting variant calls from metagenomic sequencing, forcing reliance on vendor-locked analysis pipelines.
- Reimbursement pathway uncertainty:CMS and private payers in the United States have not established consistent coding for multiplex panels beyond respiratory pathogens, compressing margins for gastrointestinal and meningitis assays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Microbiology Market |
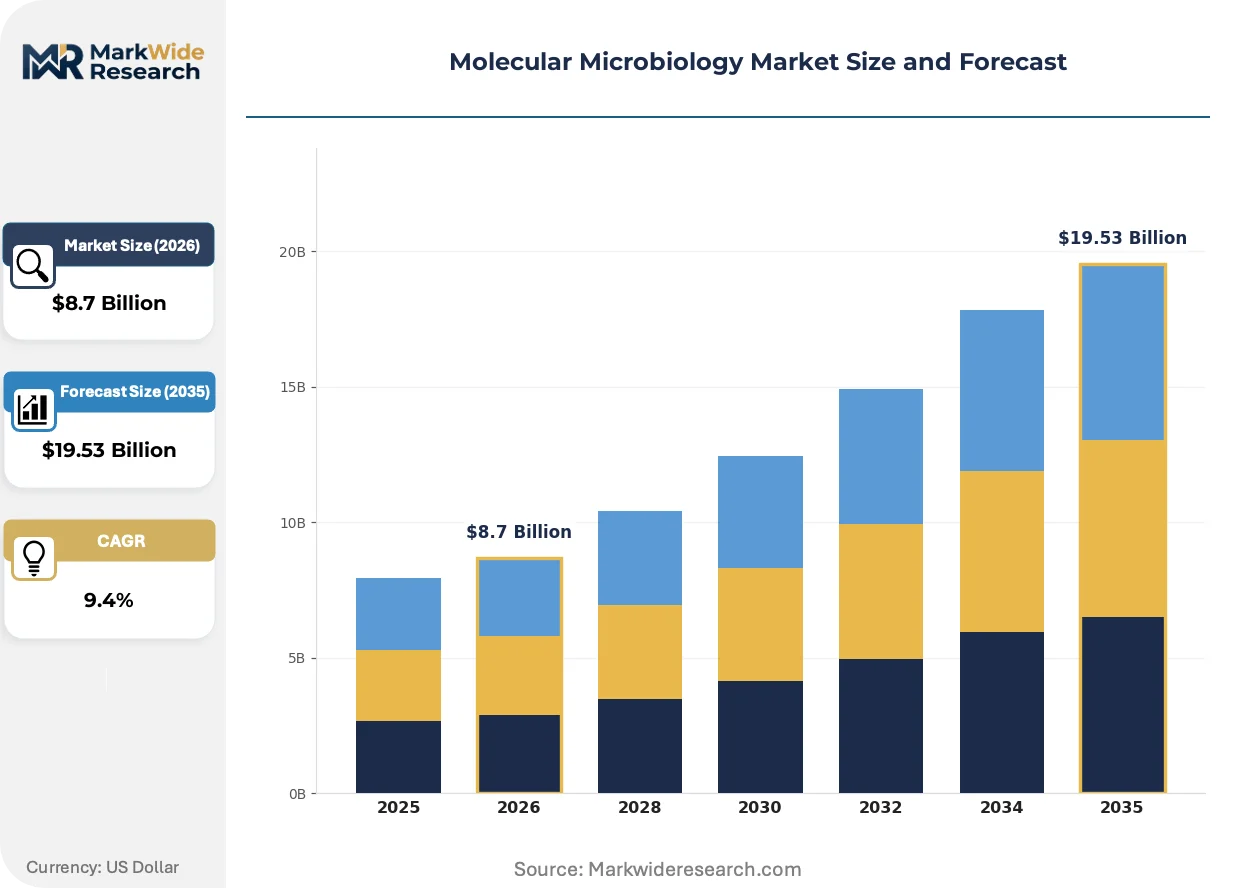
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR Instruments, DNA Sequencers, Reagents, Microscopes Application: Clinical Diagnostics, Research Laboratories, Environmental Testing, Food Safety End User: Hospitals, Academic Institutes, Pharmaceutical Companies, Biotechnology Firms Technology: Next-Generation Sequencing, Microarray, Sanger Sequencing, CRISPR |
| Companies Covered | bioMérieux, Thermo Fisher Scientific Inc., Becton, Dickinson and Company, Merck KGaA, Danaher Corporation, Roche, QIAGEN, Illumina, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Microbiology Market Shifts & Advancements
Convergence between digital PCR and next-generation sequencing is eroding the boundary between quantitative viral load monitoring and untargeted pathogen discovery in clinical microbiology workflows.
Digital PCR platforms are hybridizing with microfluidic cartridge architectures to enable absolute quantification of antimicrobial resistance genes at the point of care. Community hospitals in the United States are piloting these systems for rapid MRSA screening prior to surgical intervention. The technology is hybridizing previously separate quantitative and qualitative testing workflows into single-instrument deployments.
The FDA's enforcement discretion policy for laboratory-developed tests is narrowing, requiring more molecular microbiology assays to pursue premarket notification or de novo classification. Manufacturers must now submit clinical validation data for multiplex panels that previously operated under LDT exemptions. Reference laboratories in the United States are responding by outsourcing regulatory submissions to specialized consulting firms rather than building internal capabilities.
Group purchasing organizations are consolidating procurement authority for molecular diagnostics across multi-hospital health systems in the United States and Germany. Independent laboratories and smaller health systems are losing direct vendor relationships as contracting shifts to centralized supply chain offices. This concentration is most visible in the southeastern United States, where regional GPOs now control instrument placement decisions for over sixty percent of hospital beds.
Molecular Microbiology Market Segmentation
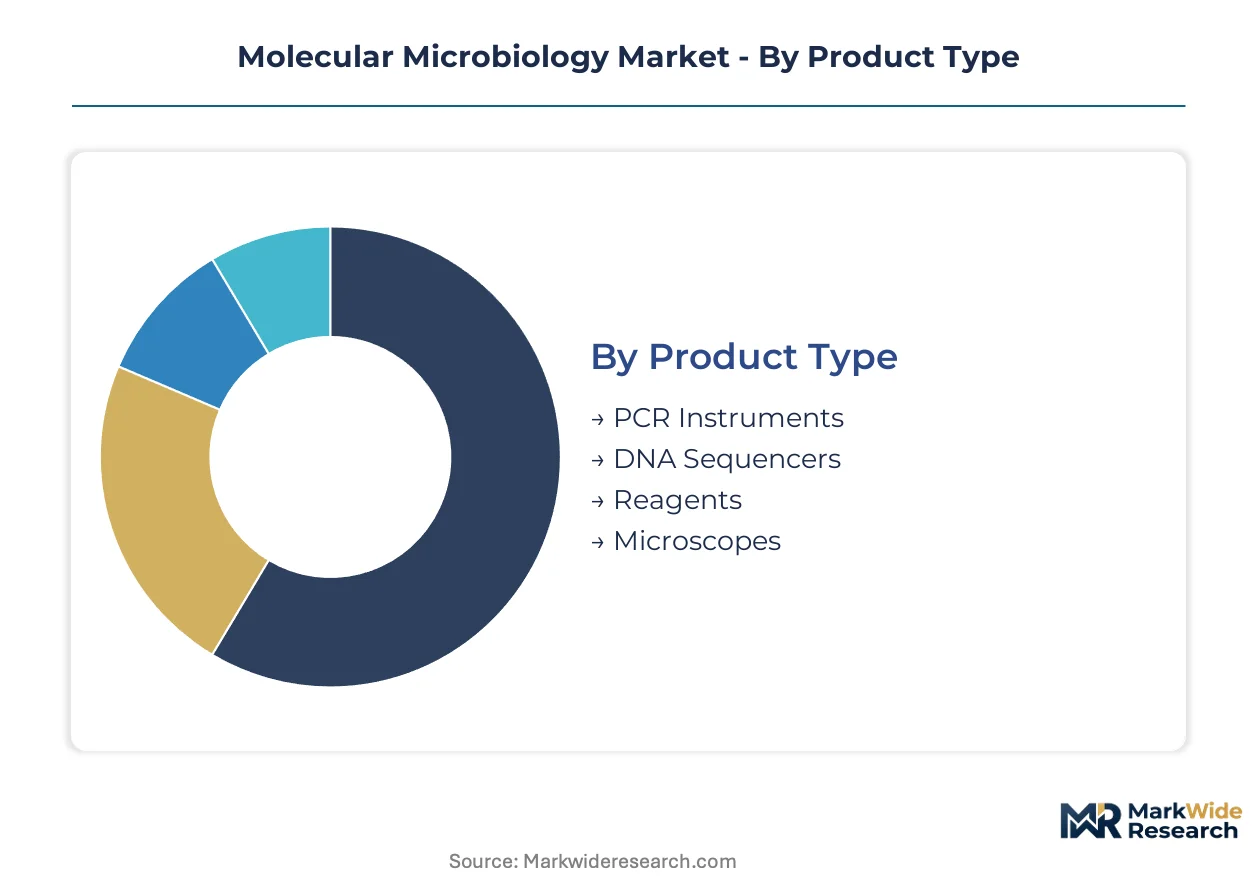
Segmentation in molecular microbiology reveals how capital intensity, workflow integration requirements, and reimbursement pathways fragment purchasing behavior across customer types. Product portfolios must align with distinct validation timelines and consumable replenishment rhythms that vary sharply between hospital laboratories and research institutions.
Product Type:
Cost tier determines procurement authority and margin structure across instrument categories and recurring consumables.
- Reagents:Polymerase master mixes, extraction kits, and probe chemistries generate recurring revenue streams with superior margin profiles. Hospital laboratories in the United States and Germany absorb the majority of volume through syndromic panel consumption.
- PCR Instruments:Thermal cyclers and real-time detection systems anchor laboratory workflows with 10–100 copy sensitivity thresholds. Academic medical centers in France and China drive placement cycles requiring 18–24 month validation timelines.
- DNA Sequencers:Benchtop platforms for outbreak surveillance and resistance gene mapping.
- Microscopes:Fluorescence and confocal systems for visual confirmation of amplification results.
Reagents command the established base. The steepest expansion runs through PCR instruments as hospital laboratories expand infectious disease menus.
Application:
End-use setting shapes sensitivity requirements, turnaround expectations, and regulatory scrutiny intensity.
- Clinical Diagnostics:Bloodstream infection panels, respiratory pathogen detection, and antimicrobial resistance profiling operate under FDA and EMA oversight. Hospital laboratories in the United States concentrate demand for multiplex PCR with sepsis protocol integration.
- Food Safety:Pathogen detection workflows for Salmonella, Listeria, and E. coli surveillance migrate from clinical to industrial settings. Contract testing laboratories in Brazil and Australia adopt nucleic acid methods for multinational protein processors.
- Research Laboratories:Untargeted metagenomic sequencing and novel pathogen discovery without diagnostic claims.
- Environmental Testing:Water quality monitoring and biodefense surveillance applications.
Clinical diagnostics absorbs the majority of installed base utilization. Food safety applications are climbing the fastest as regulatory scrutiny intensifies across food supply chains.
End User:
Customer type dictates purchasing consolidation patterns and technical support requirements.
- Hospitals:Integrated delivery networks and academic medical centers consolidate procurement through group purchasing organizations. The southeastern United States exhibits concentrated GPO control over instrument placement decisions.
- Pharmaceutical Companies:Companion diagnostic development and clinical trial support drive demand for validated nucleic acid platforms.
- Academic Institutes:Basic research funding supports exploratory sequencing without diagnostic regulatory burdens.
- Biotechnology Firms:CRISPR-based detection development and proprietary assay commercialization.
Hospitals command the established base. Pharmaceutical companies represent the fastest-growing trajectory as companion diagnostic pipelines expand.
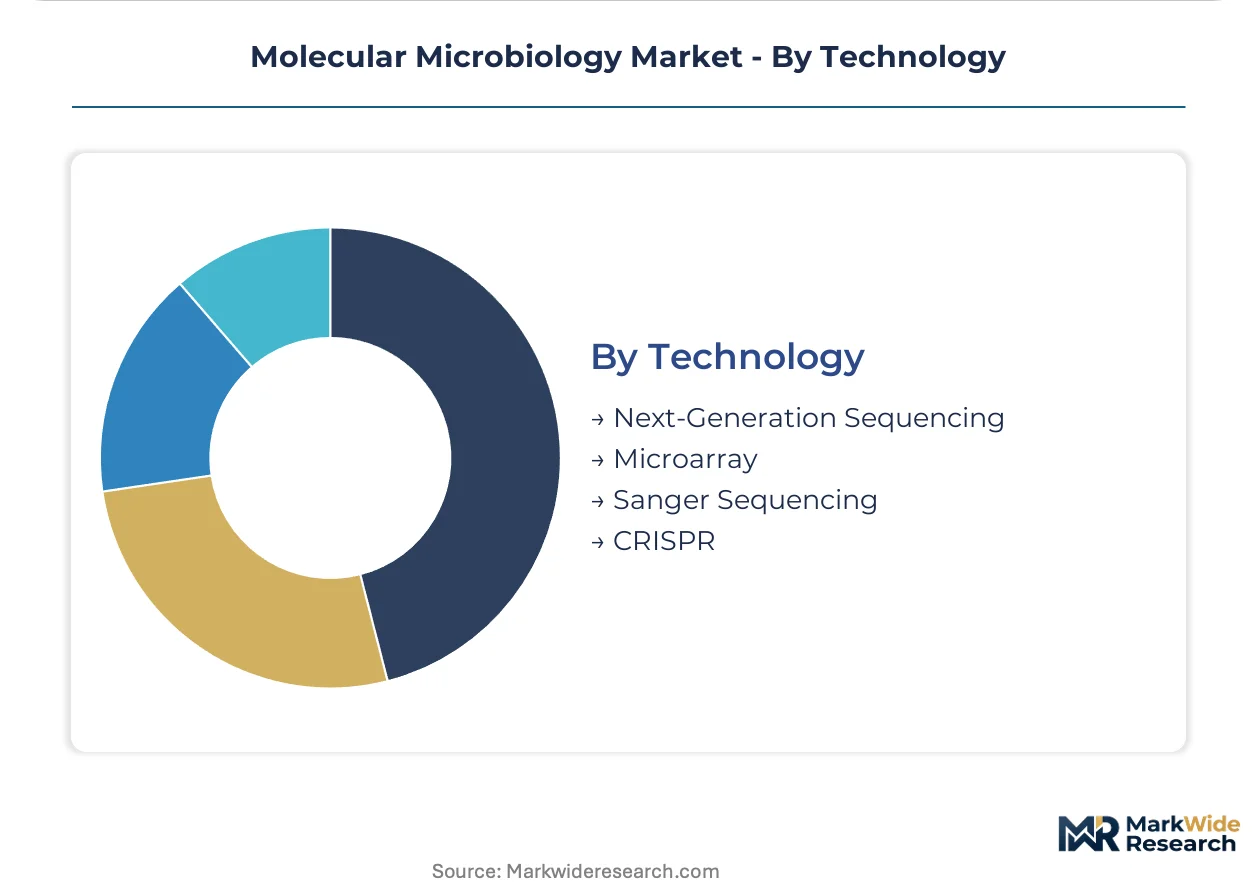
Technology:
Maturity gradient separates established platforms from emerging methods still seeking workflow integration.
- Next-Generation Sequencing:Untargeted pathogen discovery and resistance gene mapping displace Sanger platforms in reference laboratories. Public health institutions in Germany, China, and France deploy these systems for outbreak tracing.
- CRISPR:Cas12 and Cas13-based detection enables point-of-care nucleic acid testing with reduced thermal cycling requirements. Community hospitals in the United States pilot these systems for rapid MRSA screening.
- Microarray:Hybridization-based detection for established pathogen panels with standardized interpretation.
- Sanger Sequencing:Targeted confirmation sequencing for variant validation in reference workflows.
Next-generation sequencing commands the established base. CRISPR platforms are gaining share fastest as point-of-care applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites the Netherlands' distribution role for temperature-sensitive reagents moving into German hospital laboratories. Molecular diagnostics supply chains thread through specific maritime and air freight corridors that concentrate instrument placement decisions.
United States
Academic medical centers in Boston and Houston drive 18–24 month validation cycles for multiplex PCR platforms. The FDA's accelerated pathway for nucleic acid-based diagnostics compresses premarket notification timelines for syndromic panel developers. Group purchasing organizations across the southeastern United States now control instrument placement decisions for over sixty percent of hospital beds.
Germany
Public health reference laboratories in Berlin and Munich deploy next-generation sequencing for antimicrobial resistance surveillance and outbreak tracing. The EU's In Vitro Diagnostic Regulation forces manufacturers through MDR-driven conformity reassessments that compress commercialization timelines. Polymerase and oligonucleotide production clusters in southern Germany create geographic concentration for just-in-time chemistry supply.
China
The National Medical Products Administration's streamlined Class III diagnostic review process accelerates registration for multiplex PCR panels. Hospital laboratories in Shanghai and Beijing expand molecular testing menus for infectious disease diagnostics. Reference laboratories in Guangzhou province drive instrument placement and reagent consumption for respiratory pathogen detection.
France
bioMérieux anchors relationships with large health systems through syndromic panel portfolios deployed in Paris and Lyon hospital networks. ANSM oversight shapes quality management expectations for medical laboratory accreditation under ISO 15189. The Île-de-France region concentrates demand for sample preparation automation in academic medical center microbiology departments.
Australia
Contract testing laboratories serving multinational protein processors in Queensland and New South Wales adopt pathogen detection workflows previously confined to clinical settings. TGA regulatory frameworks govern in vitro diagnostic device registration for food safety applications. Sydney-based reference laboratories pilot magnetic bead-based nucleic acid extraction converging with liquid handling robotics.
Molecular Microbiology Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and sample preparation niches. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with backward integration into reagent chemistry, pure-play diagnostic specialists anchoring relationships through syndromic panels, and sequencing platform developers displacing legacy Sanger installations. Competitive moves concentrate on M&A to capture companion diagnostic pipelines and strategic partnerships to secure laboratory information system compatibility.
Among diversified conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify platform integrators with captive supply chains spanning instruments and consumables. QIAGEN occupies a narrow but defensible position upstream of most molecular workflows, specializing in sample preparation automation that feeds downstream detection platforms. These three anchors illustrate how competitive positioning fragments between system-level vendors and component specialists rather than consolidating around unified end-to-end offerings.
| Leading Market Players |
|---|
| bioMérieux |
| Thermo Fisher Scientific Inc. |
| Becton, Dickinson and Company |
| Merck KGaA |
| Danaher Corporation |
| Roche |
| QIAGEN |
| Illumina |
| Abbott |
| Others |
Supply & Pricing Matrix
The Port of Rotterdam's cold-chain logistics infrastructure channels temperature-sensitive reagents into German hospital laboratories, where freight cost volatility amplifies price differentiation between bulk-contract academic medical centers and spot-buying community hospitals. Polymerase master mix producers leverage southern Germany's chemistry clusters to extract volume-premium spreads from buyers locked into syndromic panel consumption.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the installed base. Premium tiers attach to ISO 15189-accredited academic medical centers demanding 18-24 month validation support and firmware customization, while economy tiers serve price-sensitive contract laboratories in Brazil and Australia. Cost compression in the standard tier intensifies because group purchasing organizations consolidate procurement authority across southeastern United States health systems. Reference laboratories exhibit lowest price sensitivity due to reimbursement pass-through mechanisms, whereas independent microbiology departments face acute margin pressure from capital intensity barriers.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate supplier-financing arrangements between reagent manufacturers and hospital procurement offices, straining working capital for mid-tier diagnostic firms. Polymerase and oligonucleotide production draws from southern Germany, coastal China, and Massachusetts biotechnology corridors. Magnetic bead chemistries and fluorogenic probe sets constitute critical input dependencies. Single-source vulnerability concentrates in Taq polymerase fermentation capacity, where biosafety-level containment requirements limit qualified suppliers. Distribution runs through temperature-controlled air freight for time-sensitive PCR consumables and maritime containerized shipping for instrument platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity surfaces as FDA enforcement discretion narrows for laboratory-developed tests, forcing reference laboratories to outsource regulatory submissions and creating service niches for specialized consulting firms.
For Market Incumbents: Pre-empt margin erosion in multiplex PCR panels by backward integration into probe chemistry manufacturing and firmware development. Thermo Fisher Scientific's captive supply chain model demonstrates how reagent production control defends pricing power against emerging CRISPR-based point-of-care developers. Anchor hospital system relationships through ISO 15189 accreditation support services that extend beyond instrument placement into ongoing quality management consulting.
For New Entrants and Emerging Players: Australia's contract testing laboratories serving multinational protein processors offer underpenetrated entry points for food safety pathogen detection workflows previously confined to clinical settings. Magnetic bead-based nucleic acid extraction converging with liquid handling robotics creates white-space opportunities in understaffed hospital microbiology departments. Target Brazil's protein processing sector with regulatory consulting bundled into assay validation packages, leveraging ANVISA pathway familiarity as differentiation.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates spinning off non-core diagnostic divisions as they refocus on therapeutic pipelines. Mid-cap pure-play specialists with syndromic panel portfolios and established GPO relationships present viable acquisition profiles over a multi-year holding period. Monitor FDA premarket notification submission volumes for multiplex gastrointestinal and meningitis panels as inflection indicators for reimbursement pathway clarity.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Submission Outsourcing | Reference laboratories lacking internal FDA expertise purchase compliance services from specialized consulting firms. |
| Sample Preparation Automation | Magnetic bead extraction systems reduce staffing requirements in understaffed hospital microbiology departments. |
| Food Safety Workflow Migration | Contract laboratories in Brazil and Australia adopt clinical-grade nucleic acid methods for protein processor surveillance. |
| Companion Diagnostic Pipeline Capture | Pharmaceutical companies drive fastest-growing demand trajectory for validated nucleic acid platforms. |
| Cloud-Based Analysis Platform Integration | Laboratory information system compatibility gaps delay adoption at integrated delivery networks seeking middleware solutions. |
Research Methodology
Operator-level perspectives from hospital laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA centralized assessment reports, hospital procurement databases, and CMS reimbursement coding updates. Bottom-up instrument placement and reagent consumption estimates triangulated against top-down market sizing from trade flow analysis and manufacturer revenue disclosures.
Scenario-bracketing framed the analytical approach across the analysis window, modeling volume and value outputs through segmentation by product type, application, end user, and technology maturity gradient. CAGRs derived from regression analysis of historical placement cycles and reagent replenishment rhythms, incorporating infectious disease outbreak frequency patterns and antimicrobial resistance surveillance program expansion as industry-specific forecast inputs.
Practitioners should monitor FDA enforcement discretion policy evolution, EU IVDR technical documentation completion rates, and NMPA Class III review timeline compression for early signals of competitive positioning shifts. Forecasts reflect assumptions regarding regulatory pathway stability and reimbursement coding expansion; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Galactosidase Market
Industrial Microbiology
Microbial Rennet Market
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Microbial Cell Banking Market
Industrial Microbiology
Global Microbiome Therapeutics Market
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
Global Microbial Testing Market
Industrial Microbiology
Middle East Feed Probiotics Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Global Microbial Identification Market
Industrial Microbiology
Eubiotics Market