
 Global Arabinogalactan Market | 2026-2036
Global Arabinogalactan Market Size, Share, and Industry Trends Forecast 2026-2036
Global Arabinogalactan Market Foresight
EU REACH registration requirements for novel food ingredients is pivoting the cost-of-entry calculus for arabinogalactan suppliers seeking European market access. Lonza leverages its pharmaceutical-grade manufacturing infrastructure to sustain compliance leadership across multiple jurisdictions. Ametis JSC anchors its position through captive larch wood sourcing in Siberia, while Larex Inc. differentiates via specialized extraction protocols for dietary supplement purity.
Arabinogalactan is a water-soluble polysaccharide composed of galactose and arabinose units, typically extracted from larch tree heartwood through hot-water processing and subsequent purification to achieve beta-linked galactan backbone structures with molecular weights ranging from 10,000 to 120,000 Daltons. Its primary commercial purpose centers on immune modulation through macrophage activation and gut microbiome prebiotic functionality in human and veterinary applications. Powder formulations dominate pharmaceutical and nutraceutical manufacturing due to superior stability and dosing precision, while liquid extracts occupy growing positions in functional beverage applications where rapid dissolution matters. The food and beverage segment sustains mature demand through bakery and dairy texturizer applications, whereas cosmetics represents an emerging margin pool as formulators seek plant-derived humectants.
FDA dietary supplement cGMP enforcement, EFSA novel food authorization pathways, and USDA organic certification standards collectively shape product development timelines and label claim substantiation requirements for arabinogalactan suppliers. These frameworks elevate testing burdens for imported raw materials while creating competitive separation between certified and uncertified supply sources. Stakeholders must monitor evolving pharmacopeial monograph developments and microbiome research validation to anticipate which application segments will command premium positioning.
Market Dynamics
Pharmaceutical-grade purification standards are compressing supplier margins while simultaneously creating competitive separation between certified and uncertified arabinogalactan sources across multiple jurisdictions.
Growth Catalysts
- REACH compliance mandates:EU ECHA registration requirements for novel food ingredients are forcing investment in analytical infrastructure, benefiting established suppliers with existing quality management systems.
- Prebiotic functionality validation:Gut microbiome research from clinical nutrition partnerships is expanding arabinogalactan applications beyond immune support into digestive health positioning.
- Siberian larch concentration:Captive sourcing of heartwood raw material in Eastern Russia provides cost-advantaged feedstock security for integrated producers.
Market Restraints
- Input cost volatility:Larch timber pricing fluctuates with Russian export restrictions and alternative construction material demand cycles.
- Supply concentration risk:Over-reliance on Larix sibirica and Larix occidentalis species creates botanical sourcing vulnerability to climate stress in specific forest zones.
- Substitution pressure:Inulin and fructooligosaccharides compete for prebiotic formulation slots at lower price points in functional food applications.
Strategic Opportunities
- Brazil regulatory opening:ANVISA novel food pathways for plant polysaccharides remain underdeveloped relative to North American and European frameworks, creating first-mover positioning potential.
- Cosmetic humectant pivot:Formulators seeking alternatives to petroleum-derived glycerin are testing arabinogalactan in premium skincare emulsions.
- Direct-to-consumer channel:Subscription nutraceutical platforms bypass traditional pharmaceutical distribution, capturing margin previously allocated to wholesale intermediaries.
Industry Challenges
- Analytical chemistry capacity:Beta-linked galactan backbone characterization requires specialized NMR and chromatography expertise that remains scarce outside established pharmaceutical testing laboratories.
- cGMP certification timelines:FDA dietary supplement manufacturing audits extend 18-24 months for new facility qualification, delaying market entry for emerging suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Arabinogalactan Market |
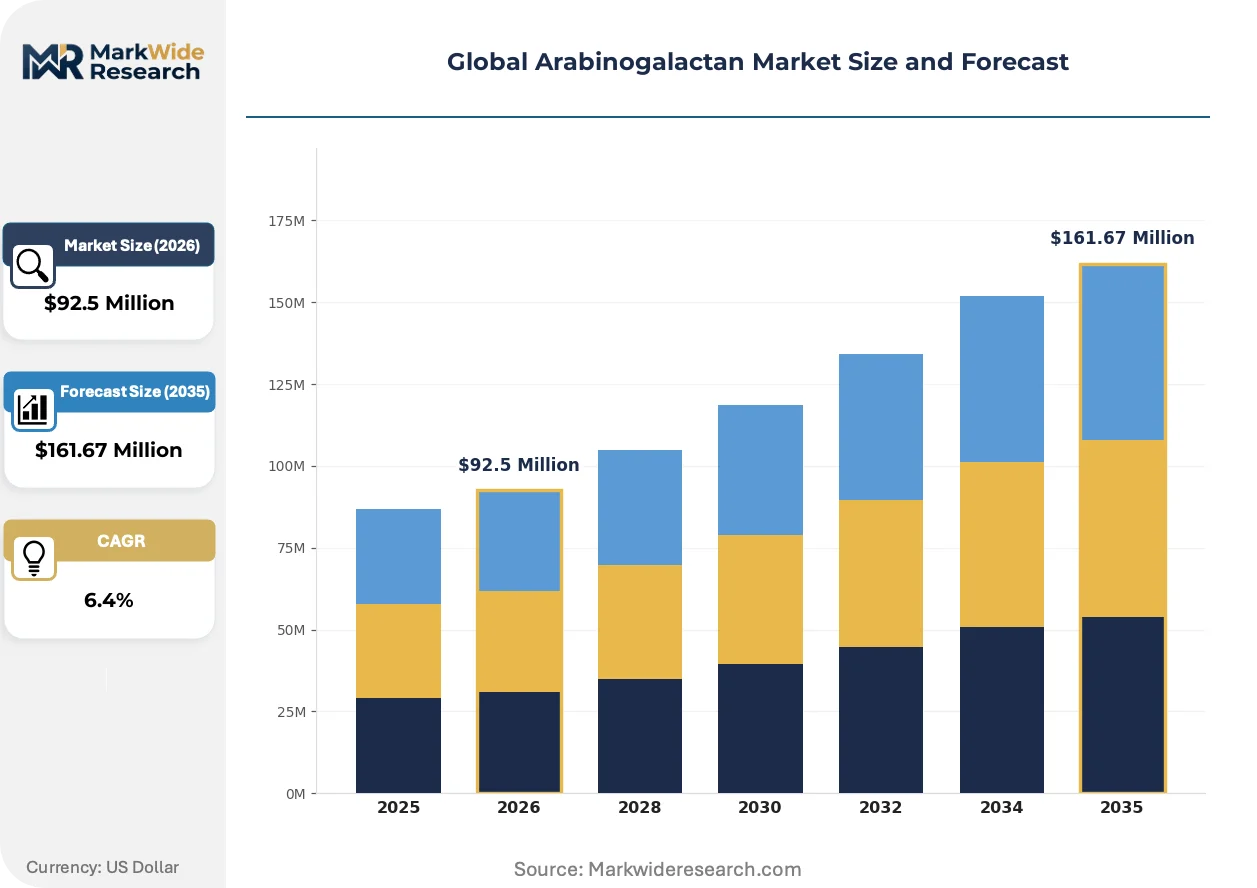
| Market Size in 2026 | $92.5 Million |
| Market Size in 2035 | $161.67 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulverized, Granular, Liquid, Powder Application: Food & Beverage, Pharmaceuticals, Nutraceuticals, Cosmetics End User: Food Manufacturers, Cosmetic Companies, Pharmacies, Health Stores Distribution Channel: Online, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Lonza, Ametis JSC, Larex Inc., Pure Encapsulations, VetriScience Laboratories, FoodScience of Vermont, Thorne Research Inc., Archer Daniels Midland Company, Jilin Forest Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Arabinogalactan Market Shifts & Advancements
Continuous processing technology and microbiome science are converging to reshape how arabinogalactan is manufactured, validated, and positioned across therapeutic and wellness applications.
Membrane filtration systems are expanding into arabinogalactan purification workflows, replacing traditional ethanol precipitation methods. German pharmaceutical contract manufacturers are adopting these systems to reduce solvent handling costs and improve batch-to-batch consistency. This technology shift is expanding into mid-tier suppliers seeking REACH-compliant production without capital-intensive infrastructure rebuilds.
EFSA novel food authorization pathways are tightening toxicological data requirements for plant-derived polysaccharides entering European food applications. The regulation now demands 90-day subchronic studies and full allergenicity assessments that were previously waived for structurally characterized ingredients. Dietary supplement formulators are responding by bifurcating product lines between pharmaceutical-grade and food-grade specifications.
Clinical nutrition procurement is consolidating around single-source supplier contracts with integrated testing capabilities. Hospital systems and long-term care networks are replacing spot purchasing with multi-year agreements that bundle raw material supply with stability testing and regulatory documentation. This pattern is most visible in United States integrated delivery networks seeking liability reduction through supply chain certification.
Global Arabinogalactan Market Segmentation
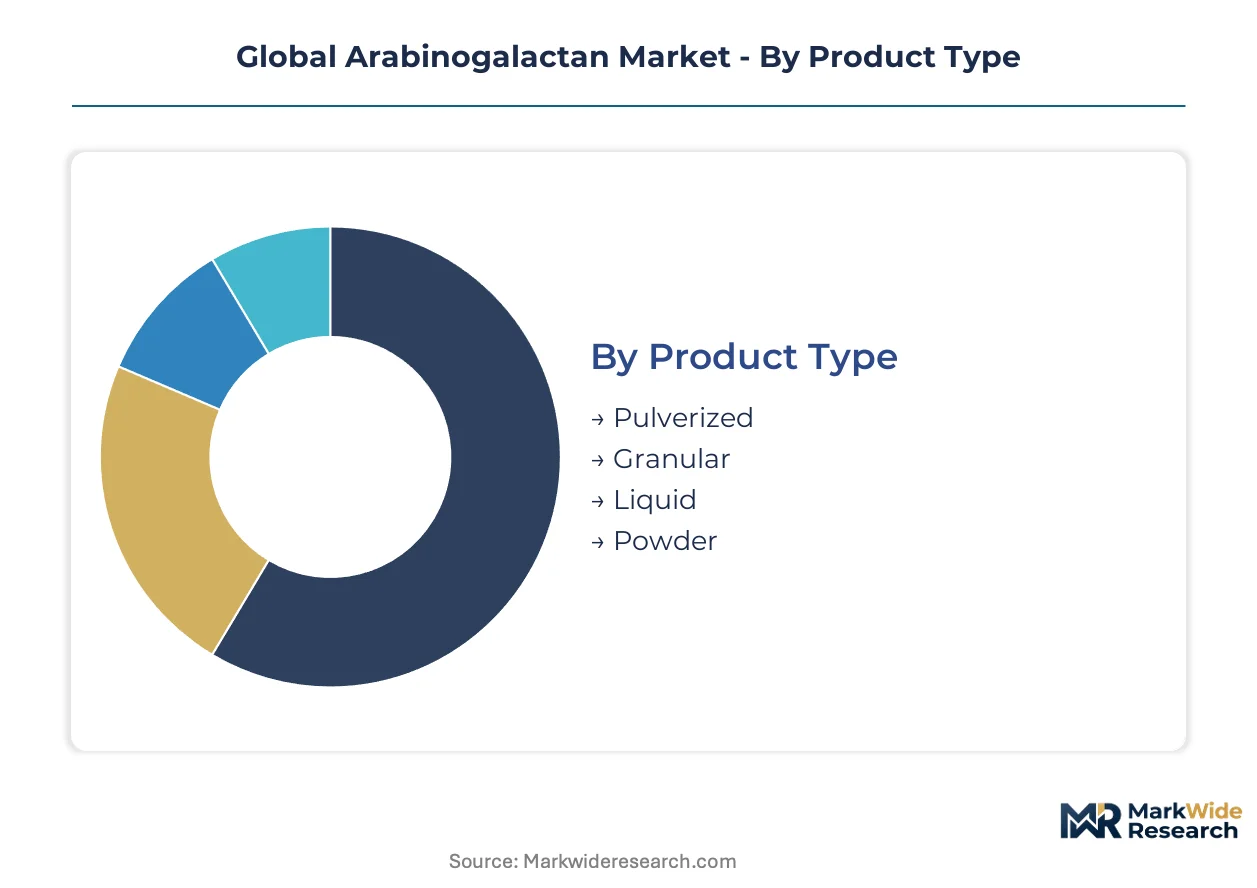
Arabinogalactan suppliers configure production assets around physical form factors that determine dissolution kinetics and formulation compatibility. Segment boundaries reflect divergent purity standards between pharmaceutical and food-grade applications, with regulatory pathways forcing distinct testing protocols and facility qualifications.
Product Type:
Standardization dominates powder and liquid grades, while pulverized and granular forms accommodate custom particle-size specifications for niche formulation requirements.
- Powder:Spray-dried arabinogalactan achieves consistent particle distribution between 80-200 microns, enabling precise dosing in capsule and tablet manufacturing. Pharmaceutical compounders in Germany specify this grade for immune-support formulations requiring batch-to-batch analytical reproducibility under EMA pharmacopeial standards.
- Liquid:Aqueous extracts at 20-30% solids concentration serve functional beverage manufacturers seeking rapid hydration without powder dispersion steps. United States-based direct-to-consumer brands are driving volume here through ready-to-drink prebiotic positioning.
- Pulverized:Coarse mechanical milling produces irregular particle morphology for bakery applications where water-binding capacity outweighs dissolution speed.
- Granular:Agglomerated particles reduce dusting during high-volume food processing, favored by dairy texturizer formulators.
Most installed capacity flows through Powder. Expansion is steepest in Liquid.
Application:
Margin stratification separates pharmaceutical-grade immune modulation from commodity food texturization, with certification requirements determining facility investment thresholds.
- Pharmaceuticals:cGMP-compliant production delivers beta-linked galactan backbones with molecular weight verification via size-exclusion chromatography. FDA enforcement of 21 CFR Part 111 is consolidating procurement around suppliers with in-house NMR spectroscopy capabilities.
- Nutraceuticals:Dietary supplement positioning occupies the pricing middle tier, with United States health practitioner channels demanding USP-verified identity testing. Subscription platform growth is expanding direct-to-consumer penetration beyond traditional retail pharmacy.
- Food & Beverage:EFSA novel food authorization limits label claims to prebiotic fiber content, constraining premium pricing relative to health-positioned segments.
- Cosmetics:Plant-derived humectant positioning targets premium skincare emulsions, though toxicological dossier requirements under EU Cosmetics Regulation delay market entry for new suppliers.
Pharmaceuticals commands the highest unit economics. Nutraceuticals is climbing the fastest.
End User:
Procurement sophistication varies dramatically across buyer types, from commodity spot purchasing to multi-year single-source contracts with embedded stability testing.
- Food Manufacturers:High-volume bakery and dairy producers specify technical-grade arabinogalactan for moisture retention and shelf-life extension. Russian larch-derived supply dominates this price-sensitive segment through Ametis JSC's captive Siberian sourcing.
- Pharmacies:Compounding pharmacies in Switzerland and Germany stock pharmaceutical-grade powder for personalized immune-support protocols, with Swissmedic oversight ensuring pharmacopeial compliance.
- Cosmetic Companies:Premium formulators in France test arabinogalactan as glycerin alternatives, though ANSM notification requirements extend development timelines.
- Health Stores:United States independent retailers represent fragmented demand for branded nutraceutical SKUs, with shelf placement contingent on third-party certification seals.
Food Manufacturers absorb the largest absolute volume. Pharmacies deliver the steepest margin expansion.
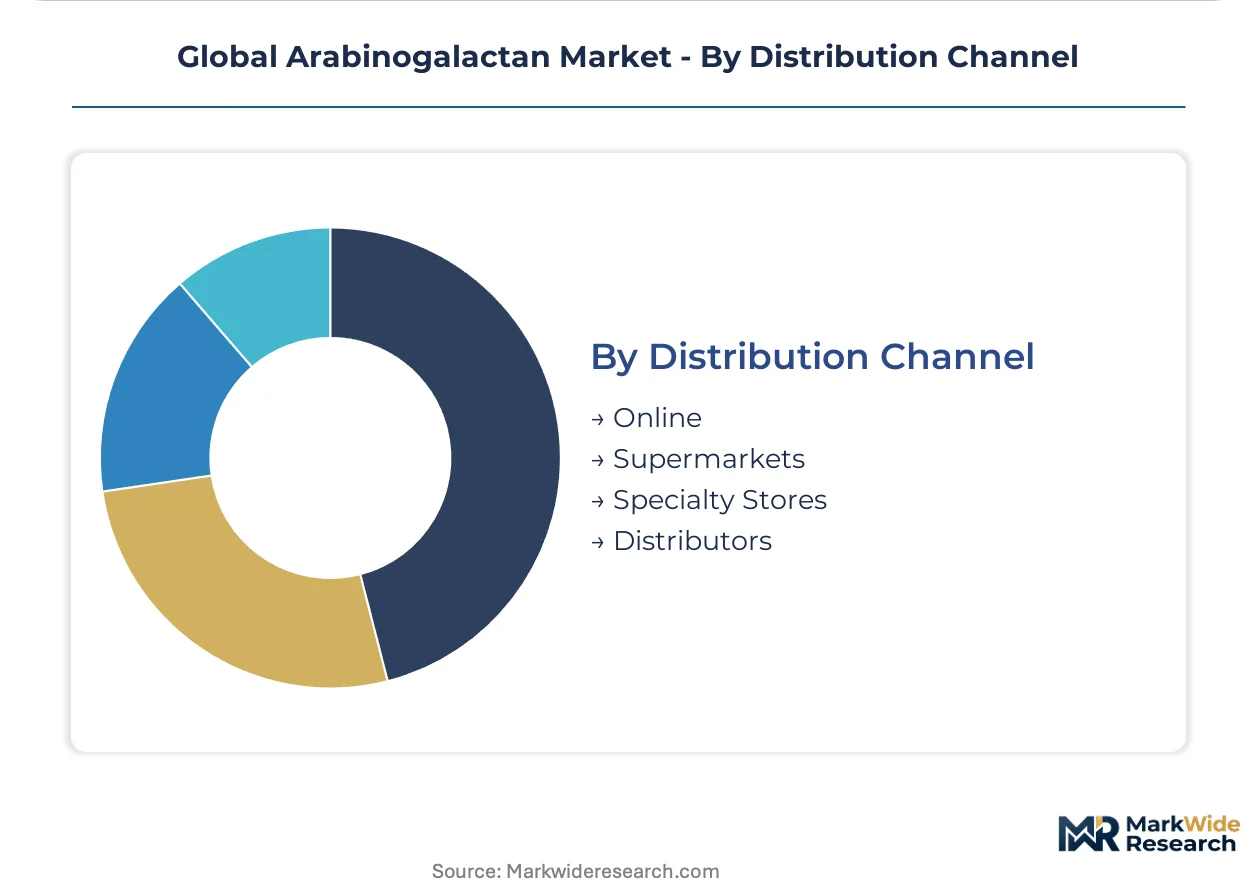
Distribution Channel:
Channel selection determines working capital intensity and regulatory documentation burden, with direct digital sales bypassing traditional wholesale margin extraction.
- Distributors:Pharmaceutical and nutraceutical wholesalers in the United States bundle arabinogalactan with complementary immune ingredients, capturing value through technical specification support and lot traceability documentation.
- Online:Direct-to-consumer platforms eliminate intermediary markups, though FDA dietary supplement labeling compliance and state-level sales tax complexity create operational overhead.
- Specialty Stores:Natural product retailers in Germany emphasize organic certification and origin transparency, with EU organic logo requirements filtering supplier eligibility.
- Supermarkets:Mass-market grocery placement remains limited to functional beverage applications with established consumer recognition.
Distributors handle the majority of pharmaceutical-grade flow. Online is gaining share fastest among nutraceutical brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Arabinogalactan commercialization originated in North American larch forests during the mid-twentieth century, with extraction infrastructure later migrating to Siberian woodlands as Soviet-era timber operations expanded. Today, regulatory divergence between jurisdictions shapes where purification capacity concentrates and which purity grades command premium positioning.
United States
FDA dietary supplement cGMP enforcement under 21 CFR Part 111 consolidates procurement around suppliers with in-house analytical capabilities. Direct-to-consumer nutraceutical platforms in Utah and California bypass traditional pharmaceutical distribution, capturing margin previously allocated to wholesale intermediaries. Boston-area clinical nutrition partnerships are expanding arabinogalactan use in immune-support protocols for hospital systems.
Germany
EMA pharmacopeial standards and ECHA REACH compliance mandates elevate testing burdens for imported raw materials. Pharmaceutical contract manufacturers in Bavaria adopt membrane filtration systems to reduce solvent handling costs while maintaining batch-to-batch consistency. Frankfurt-area distributors bundle arabinogalactan with complementary immune ingredients, capturing value through technical specification support.
Russia
Captive sourcing of Larix sibirica heartwood in Eastern Siberia provides cost-advantaged feedstock security for integrated producers. Russian export restrictions on larch timber introduce input cost volatility that ripples through global pricing structures. Irkutsk-region extraction facilities supply technical-grade material to price-sensitive food manufacturers across Eurasia.
Switzerland
Swissmedic oversight ensures pharmacopeial compliance for compounding pharmacies stocking pharmaceutical-grade powder. Basel-area formulators emphasize organic certification and origin transparency, with EU organic logo requirements filtering supplier eligibility. Zurich-based procurement offices coordinate multi-year single-source contracts with embedded stability testing for European hospital networks.
China
NMPA novel food authorization pathways for plant-derived polysaccharides remain underdeveloped relative to North American frameworks, creating regulatory uncertainty for imported ingredients. Shandong Province extraction facilities serve domestic bakery and dairy texturizer applications where water-binding capacity outweighs dissolution speed. Beijing-based research institutions validate gut microbiome prebiotic functionality to support domestic label claims.
Global Arabinogalactan Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with captive raw material access and certified pharmaceutical-grade production infrastructure. Supplier margins compress under REACH and FDA purity mandates while simultaneously creating competitive separation between certified and uncertified sources. Three archetypes dominate: Siberian-integrated timber processors, North American pharmaceutical contract manufacturers, and European quality-system specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as players seek regulatory compliance leadership across multiple jurisdictions.
Within the integrated-processor tier, Ametis JSC anchors its position through captive larch wood sourcing in Siberia, exemplifying backward integration into upstream timber operations. Lonza occupies the pharmaceutical-grade manufacturing position, representing quality-system leadership across EMA and FDA jurisdictions. Larex Inc. sits within the specialized-extraction archetype, differentiating via dietary supplement purity protocols. These three entities collectively illustrate how regulatory compliance capabilities and raw material security determine competitive positioning in constrained supply environments.
| Leading Market Players |
|---|
| Lonza |
| Ametis JSC |
| Larex Inc. |
| Pure Encapsulations |
| VetriScience Laboratories |
| FoodScience of Vermont |
| Thorne Research Inc. |
| Archer Daniels Midland Company |
| Jilin Forest Industry |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade certification against food-grade commodity positioning splits the arabinogalactan market into divergent pricing and sourcing configurations. FDA cGMP compliance and EMA pharmacopeial standards create 40-60% price premiums over technical-grade material, while REACH-registered supply draws from a narrower supplier base than uncertified feedstock.
Pricing Analysis
Bundled regulatory documentation and stability testing services command premiums over unbundled raw material transactions. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and technical-grade levels reflects certification investment recovery and analytical capability amortization. Cost compression in the technical-grade tier intensifies because Russian larch export restrictions introduce feedstock volatility. Food manufacturers exhibit highest price sensitivity, while hospital procurement networks prioritize single-source liability reduction over unit cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Larix sibirica and Larix occidentalis concentration in Eastern Siberia and the North American Pacific Northwest. Captive heartwood sourcing in Russia, extraction infrastructure in Germany, and formulation capacity in the United States constitute the dominant geographic triangle. Raw material dependencies encompass larch timber harvesting rights, hot-water extraction equipment, and membrane filtration systems. Regulatory restriction risk manifests through EU REACH registration deadlines and Russian export licensing. Distribution runs through pharmaceutical wholesalers in Germany and direct-to-consumer platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The arabinogalactan market represents a late-cycle quality story as clinical nutrition procurement consolidates around certified single-source suppliers with embedded testing capabilities.
For Market Incumbents: Acquire NMR spectroscopy and chromatography analytical assets to defend against emerging membrane filtration technology disruptors. Expand cGMP-certified capacity in Bavaria or Utah to capture hospital system multi-year contract consolidation. Deepen upstream control over Siberian larch harvesting concessions before Russian timber export restrictions tighten further. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Brazilian and Chinese markets offers entry positioning where ANVISA and NMPA pathways remain underdeveloped relative to Western frameworks. Target functional beverage liquid extract applications in the United States direct-to-consumer channel, where rapid dissolution requirements favor new processing approaches over incumbent powder infrastructure. Pursue cosmetic humectant formulation partnerships with French premium skincare brands seeking petroleum-derived glycerin alternatives. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance mandates and FDA cGMP enforcement eliminate sub-scale suppliers lacking analytical infrastructure investment capacity. Five-to-ten-year viability favors vertically integrated timber-to-extraction specialists with captive Siberian sourcing and multi-jurisdictional certification. Monitor EFSA novel food authorization timelines as inflection indicators for food-grade premium expansion relative to pharmaceutical-grade margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Adoption | German contract manufacturers reduce solvent handling costs while achieving EMA pharmacopeial batch consistency. |
| Siberian Larch Harvesting Concession Expansion | Ametis JSC secures cost-advantaged feedstock security against Russian export restriction volatility. |
| cGMP Certification Investment | Utah and California facilities capture direct-to-consumer nutraceutical margin previously allocated to wholesale intermediaries. |
| EFSA Novel Food Authorization Pursuit | |
| Cosmetic Humectant Toxicological Dossier Development | French formulators access EU Cosmetics Regulation-compliant plant-derived alternatives to petroleum-derived glycerin. |
Research Methodology
Multiple input streams — extraction facility operators, pharmaceutical compounders, dietary supplement brand managers, and regulatory affairs specialists — were reconciled against customs trade data, EFSA novel food submission records, FDA 21 CFR Part 111 inspection reports, and SEC filings from publicly traded ingredient suppliers. Bottom-up capacity modeling across Siberian, German, and North American production sites was cross-validated with top-down demand estimation from hospital procurement databases and nutraceutical subscription platform disclosures.
Historical volume trajectories were cross-referenced against expert panel assessments of REACH compliance investment timelines and cGMP audit completion rates across the projection horizon. Segmentation modeling incorporated product form factor, application purity tier, end-user procurement sophistication, and distribution channel regulatory burden. CAGRs were derived from weighted scenario analysis of clinical nutrition partnership expansion, prebiotic functionality validation research, and cosmetic humectant adoption curves.
The model assumes a particular technology adoption path; alternative pathways for continuous membrane filtration versus traditional ethanol precipitation would alter the outlook for mid-tier supplier cost structures and batch consistency benchmarks. Forecasts incorporate assumptions regarding Russian timber export policy stability, EFSA toxicological data requirement enforcement, and gut microbiome research publication velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Global Microbiome Therapeutics Market
Industrial Microbiology
Ripening Cultures Market
Industrial Microbiology
Global Microbial Testing Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Lactic Acid Bacteria Market
Industrial Microbiology
Global Bacterial Cell Culture Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
B-Glucuronidase Enzymes Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Industrial Bioprocessing Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Eubiotics Market