
 Global Avocado Market | 2026-2036
Global Avocado Market Size, Share, and Industry Trends Forecast 2026-2036
Global Avocado Market Analysis
Subscription-based ripening-as-a-service is expanding how distributors monetize avocado inventory, shifting revenue from commodity sales to managed freshness contracts. Mission Produce Inc. leverages vertical integration across Peruvian and Mexican growing regions to sustain year-round supply continuity. Westfalia Fruit anchors its competitive position through proprietary rootstock breeding programs that improve yield consistency under variable climate conditions.
Avocado denotes the fruit of Persea americana, a Lauraceae species containing 15-30% oil by fresh weight, with Hass cultivars dominating commercial trade due to their thick, pebbled skin and extended post-harvest shelf life of 14-21 days under controlled atmosphere. The fruit serves as a functional ingredient in food manufacturing, prized for its monounsaturated lipid profile and emulsification properties in dressings and spreads. Hass avocados occupy the dominant margin pool across product type segments, while foodservice channels within distribution are capturing volume growth as restaurant chains standardize avocado menu placements. Online retail represents the fastest-expanding distribution channel, though wholesale still controls the majority of physical volume flow.
The USDA's Animal and Plant Health Inspection Service enforces phytosanitary import protocols that determine seasonal market access for Mexican and Peruvian suppliers. Mexico's SAGARPA and Peru's SENASA administer parallel export certification systems that shape origin-based competitive positioning. EU phytosanitary standards under the EU Green Deal are tightening residue monitoring and carbon footprint disclosure requirements. Stakeholders must monitor how evolving deforestation-free supply chain mandates reshape sourcing geography and compliance costs.
Market Dynamics
Phytosanitary certification requirements under Mexico's SADER program and the EU Green Deal are forcing exporters to restructure traceability infrastructure, shifting competitive advantage toward vertically integrated suppliers with captive cold-chain logistics.
Growth Catalysts
- EU Green Deal deforestation-free mandates:Importers into European markets must demonstrate geolocated sourcing compliance, creating first-mover advantage for operations with satellite-verified orchard mapping.
- Foodservice channel standardization:Quick-service restaurant chains in the United States are locking in multi-year avocado volume commitments, de-risking grower revenue through contracted offtake.
- Controlled atmosphere ripening technology:Distributors deploying ethylene management systems can extend post-harvest shelf life from 14 days to 21 days, reducing retail shrinkage and enabling longer supply chains.
Market Restraints
- Input cost volatility in irrigation infrastructure:Drip system components and energy-intensive groundwater pumping in Michoacán orchards compress margins during drought cycles.
- Supply concentration in Mexican Pacific states:Over 80% of export-grade Hass volume originates from four Mexican states, exposing buyers to localized climate shocks and labor disruption.
- Water-intensive cultivation physics:Avocado trees require approximately 1,000 liters of water per kilogram of fruit, drawing regulatory scrutiny in water-stressed growing regions.
Strategic Opportunities
- Underpenetrated Indian food processing sector:Domestic oil extraction capacity remains minimal despite rising urban demand for functional ingredients in plant-based spreads.
- Carbon footprint disclosure tooling:Early adopters of lifecycle assessment software can preempt EU Green Deal compliance requirements and capture premium positioning in Northern European retail.
- Convergence of blockchain traceability and IoT sensors:Integrated platforms that marry temperature logging with immutable ledger records enable real-time quality verification for foodservice buyers.
Industry Challenges
- Phytosanitary certification timeline compression:Mexico's SADER and Peru's SENASA export clearance windows are narrowing, requiring faster pathogen testing turnaround without compromising accuracy.
- Rootstock propagation skill scarcity:Grafting expertise for climate-resilient cultivars concentrates among aging agronomists in Michoacán, constraining orchard renovation rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Avocado Market |
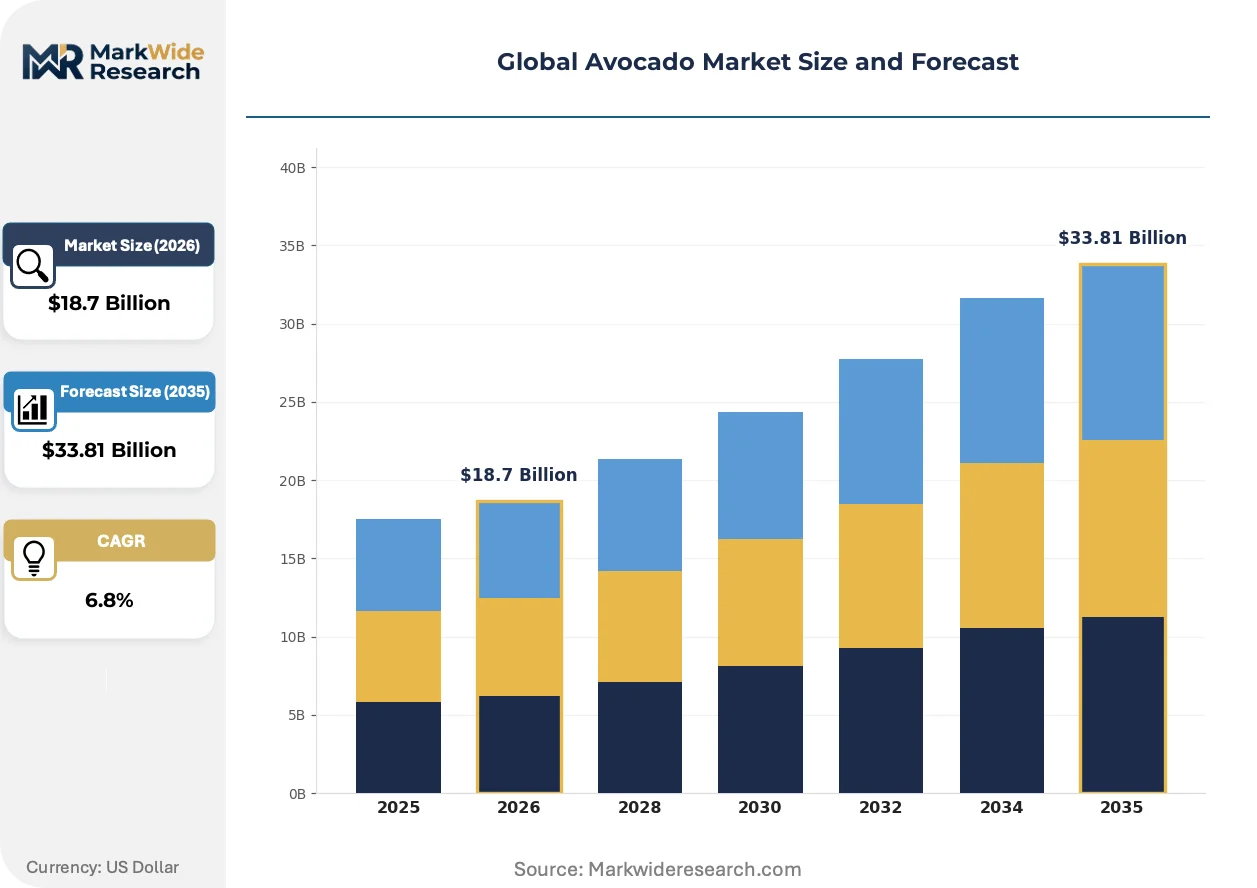
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hass, Fuerte, Bacon, Pinkerton Distribution Channel: Supermarkets, Online Retail, Foodservice, Wholesale End User: Households, Restaurants, Food Manufacturers, Retailers Application: Salads, Dips, Smoothies, Spreads |
| Companies Covered | Calavo Growers Inc., West Pak Avocado Inc., Westfalia Fruit, Mission Produce Inc., Empacadora Avehass S.A. de C.V., Aguacates JBR, Henry Avocado Corporation, Del Rey Avocado Co. Inc., Camposol S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Avocado Market Emerging Trajectories
Post-harvest technology deployment and regulatory disclosure requirements are compressing the traditional wholesale-distributor-retail value chain, rewarding operators who integrate ripening control with compliance documentation.
Controlled atmosphere storage is consolidating ripening-as-a-service economics. Third-party logistics providers in the United States and the Netherlands are installing ethylene scrubbing and nitrogen flushing systems to manage avocado firmness remotely. Foodservice buyers now contract for delivered-ready fruit rather than accepting raw green deliveries, compressing margin capture toward the distributor with ripening infrastructure.
The EU Green Deal is tightening residue monitoring protocols for imports entering Rotterdam and Hamburg. SENASA-certified Peruvian exporters and SADER-authorized Mexican suppliers face expanded documentation requirements for pesticide Maximum Residue Limits and carbon intensity disclosures. Smallholder cooperatives without digitized orchard records are losing access to EU supermarket private-label programs.
Buyer procurement is fragmenting across direct-to-grower contracting and spot-market purchasing. Large United States retail chains are bypassing traditional importers to negotiate seasonal offtake directly with Peruvian and Mexican producer associations. This disintermediation concentrates volume risk with origin-country exporters while compressing trading margins for legacy import houses in Los Angeles and Miami.
Global Avocado Market Segmentation
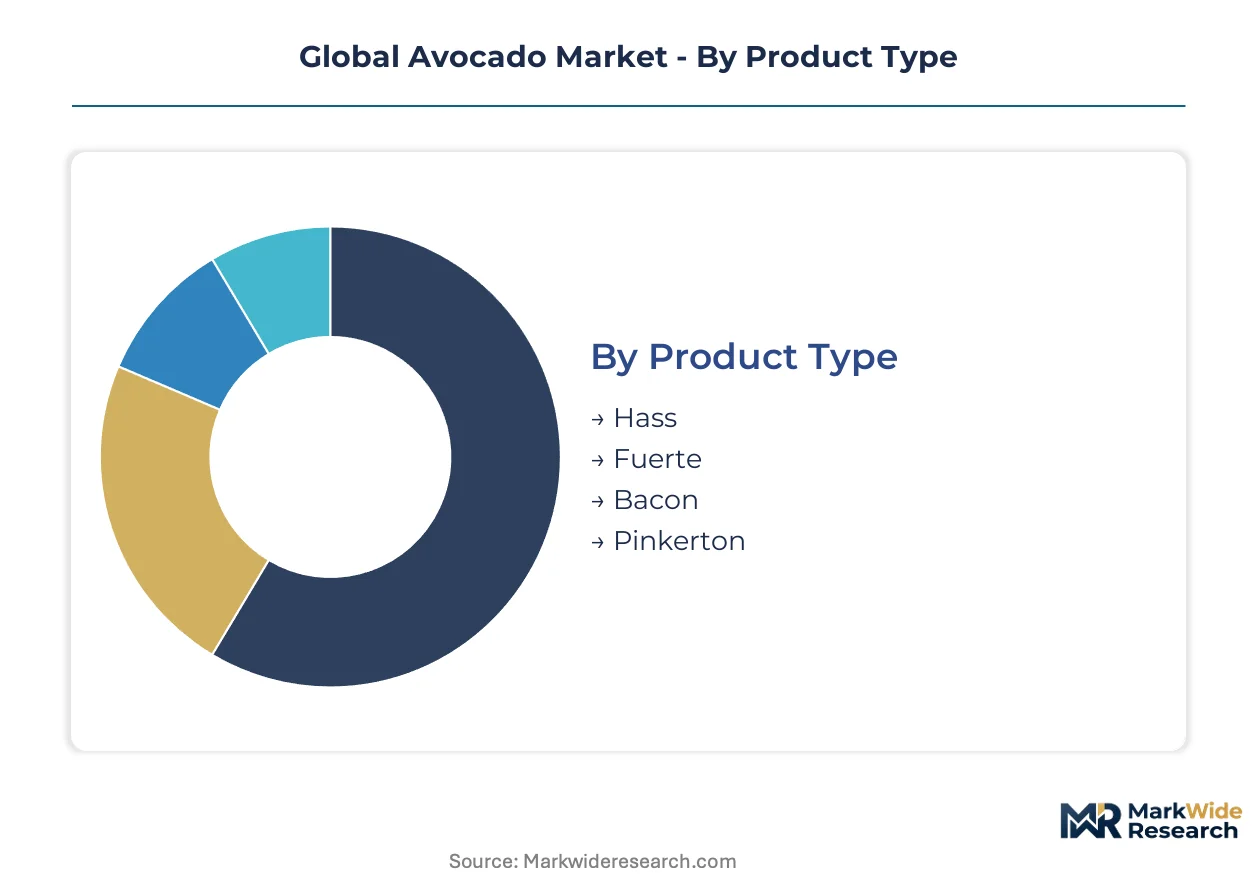
Avocado market segmentation reveals how ripening technology and phytosanitary compliance reshape value capture across product formats and channel structures. Distinct margin pools emerge between standardized bulk shipments and customized ripening-as-a-service contracts.
Product Type:
Standardization dominates at the commodity tier while proprietary breeding programs differentiate premium positioning across this category.
- Hass:Thick, pebbled skin delivers 14-21 day post-harvest shelf life under controlled atmosphere, with monounsaturated oil content reaching 15-20% by fresh weight. United States foodservice chains specify Hass cultivars exclusively for menu standardization, locking in contracted offtake from Michoacán and Peruvian suppliers. Leading the category by volume: Hass. Growing fastest: proprietary rootstock variants with drought tolerance.
- Fuerte:Smooth, thin skin and pear-shaped profile yield 12-18% oil content with shorter shelf life, limiting export viability to regional European markets. Spanish and Israeli growers target Fuerte toward domestic processing channels where oil extraction economics favor lower per-unit input costs.
- Bacon:Cold-hardy cultivar with 10-12% oil content serves niche winter production in California's San Joaquin Valley and Chile's Central Valley, supplying domestic fresh markets during off-peak import windows.
- Pinkerton:Extended neck geometry and 18-22% oil concentration attract premium positioning in Japanese retail and Northern European specialty grocers, though limited propagation constrains volume scale.
Hass commands absolute volume leadership. Pinkerton climbs fastest in premium-tier positioning.
Distribution Channel:
Channel selection determines who controls ripening infrastructure and compliance documentation costs.
- Supermarkets:United States and German retail chains demand delivered-ready fruit with firmness specifications, transferring ripening investment to distributor partners. Volume concentrates with vertically integrated suppliers operating ethylene management systems in Rotterdam and Los Angeles cold storage.
- Online Retail:Direct-to-consumer fulfillment requires precise ripeness staging across last-mile logistics. Expanding most quickly: subscription-based avocado delivery services in United Kingdom and Netherlands urban corridors.
- Foodservice:Quick-service restaurant chains contract for specification-grade fruit, bypassing traditional importers to negotiate directly with Peruvian producer associations and Mexican grower cooperatives.
- Wholesale:Legacy import houses in Miami and Hamburg retain physical volume control but face margin compression as buyers fragment procurement across direct contracting and spot markets.
Wholesale retains the largest physical throughput. Online retail shows steepest expansion trajectory.
End User:
User type dictates packaging format, ripeness specification, and documentation requirements.
- Households:Retail-packaged single and twin-count units dominate United States and European supermarket penetration, with ripeness indicators driving repeat purchase behavior.
- Restaurants:Foodservice buyers prioritize delivered-ready firmness and lot-level traceability for menu consistency, contracting ripening-as-a-service from third-party logistics providers.
- Food Manufacturers:Industrial processors in Netherlands and California extract avocado oil for plant-based spread formulations, requiring SADER or SENASA-certified bulk shipments with residue documentation.
- Retailers:Supermarket private-label programs in Germany and France demand geolocated sourcing compliance under EU Green Deal deforestation-free mandates, excluding smallholder cooperatives without digitized orchard records.
Households absorb the largest consumption volume. Food manufacturers scale fastest in contracted offtake structures.
Application:
Application format determines oil content requirements and processing infrastructure investment.
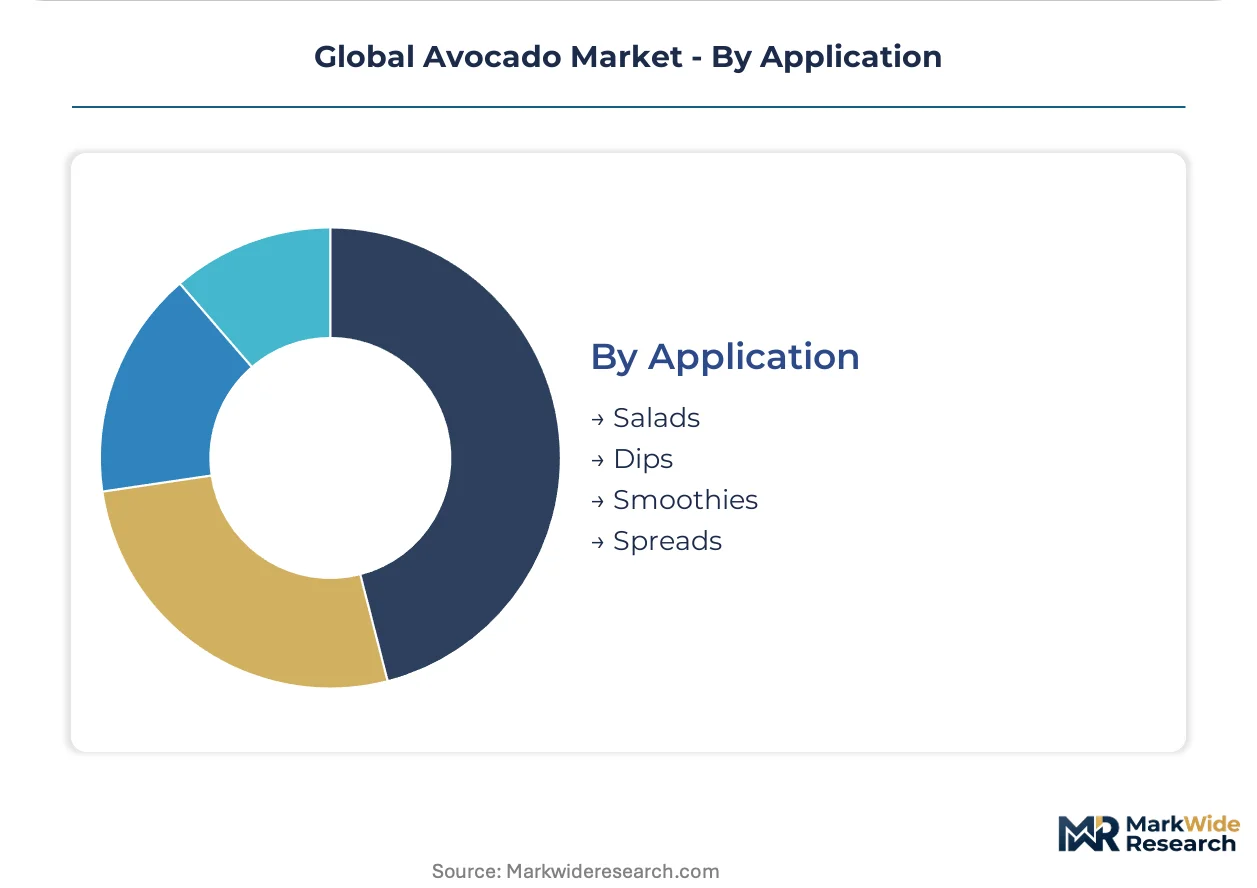
- Salads:Fresh sliced and diced formats require precise ripeness staging for foodservice pre-prep operations, with United States chain restaurants standardizing avocado as core menu architecture.
- Dips:Guacamole and avocado-based spreads demand high-oil Hass cultivars with emulsification stability, processed in California and Mexico border facilities for North American distribution.
- Smoothies:Frozen pulp segments target health-positioned beverage chains in United Kingdom and Australia, with IQF processing concentrating in Peruvian coastal facilities.
- Spreads:Oil extraction for plant-based butter alternatives drives industrial demand in Netherlands and Germany, where EU Green Deal carbon disclosure requirements shape supplier selection.
Salads capture the highest fresh-volume consumption. Spreads demonstrate the fastest industrial application growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico harvests the majority of export-grade Hass volume while the United States absorbs the largest import share, creating a trade flow that defines hemispheric supply economics. European demand concentrates in Germany and the Netherlands as compliance requirements intensify. Asian markets remain underdeveloped relative to per-capita income levels.
Mexico
Michoacán orchards supply over 80% of US-bound Hass exports through the Lázaro Cárdenas port corridor. SADER certification timelines compress export clearance windows, favoring vertically integrated packers with in-house cold-chain infrastructure. Jalisco's emerging production zones attract irrigation investment as water stress constrains Pacific state expansion.
United States
California's San Joaquin Valley growers target winter domestic windows when Mexican import volumes contract. USDA APHIS phytosanitary protocols determine seasonal market access for cross-border shipments. Los Angeles and Miami cold-storage hubs consolidate ripening-as-a-service capacity for foodservice redistribution.
Peru
Ica Valley producers counter-seasonal Mexican supply with SENASA-certified shipments reaching Rotterdam and Philadelphia during northern hemisphere summer gaps. EU Green Deal deforestation-free mandates exclude smallholder cooperatives lacking geolocated orchard documentation. Trujillo processing clusters expand IQF frozen pulp capacity for European industrial buyers.
Netherlands
Rotterdam's port infrastructure anchors European import logistics, with ethylene-managed ripening facilities serving German and French supermarket chains. EFSA residue monitoring protocols under EU Green Deal implementation reshape supplier qualification criteria. Venlo distribution corridors specialize in delivered-ready fruit specifications for quick-service restaurant procurement.
Germany
Discounter retail chains drive private-label avocado penetration in Berlin and Hamburg metropolitan zones. CSRD-aligned carbon footprint disclosure requirements favor suppliers with lifecycle assessment documentation. Munich-based food manufacturers contract bulk oil extraction volumes for plant-based spread formulations.
Global Avocado Market Vendor Landscape
Capital-heavy producers compete with asset-light distributors across a market structure that rewards captive orchard ownership and controlled-atmosphere infrastructure. Tier-one operators consolidate through backward integration into rootstock breeding and forward integration into ripening services. Three archetypes dominate: vertically integrated origin-country exporters, third-party logistics providers with ethylene management systems, and specialty cultivar developers with proprietary germplasm. Competitive moves concentrate on multi-year offtake contracting with foodservice chains and satellite-verified orchard mapping for EU Green Deal compliance.
Within the integrated exporter tier, Mission Produce Inc. and Westfalia Fruit exemplify scale-driven positioning through geographic diversification across multiple growing regions. California-based Henry Avocado Corporation occupies a position among domestic US suppliers focused on winter production windows. Peruvian S.A. de C.V. structures including Empacadora Avehass and Camposol S.A. represent South American counter-seasonal supply capacity. These archetypes illustrate how competitive advantage flows toward operators combining origin-country production control with destination-market ripening infrastructure.
| Leading Market Players |
|---|
| Calavo Growers Inc. |
| West Pak Avocado Inc. |
| Westfalia Fruit |
| Mission Produce Inc. |
| Empacadora Avehass S.A. de C.V. |
| Aguacates JBR |
| Henry Avocado Corporation |
| Del Rey Avocado Co. Inc. |
| Camposol S.A. |
| Others |
Supply Flow & Price Mechanics
Captive cold-chain infrastructure anchors both supply position and pricing power across the avocado trade, with vertically integrated operators in Michoacán and Ica Valley capturing margin through in-house ripening services that commodity traders cannot replicate. Mexico's SADER certification timelines and EU Green Deal deforestation-free mandates force compliance investment that consolidates advantage toward operators with satellite-verified orchard mapping and ethylene-managed storage.
Pricing Analysis
Margin tightening in the wholesale tier traces to buyer fragmentation across direct-to-grower contracting and spot-market purchasing, compressing legacy importer margins in Los Angeles and Miami. Contract-based long-term offtake dominates foodservice procurement, with quick-service restaurant chains locking in volume commitments that de-risk grower revenue. Price differentiation rests on certification grade under SADER and SENASA protocols plus ripening-as-a-service bundling. Food manufacturers show highest price sensitivity due to bulk oil extraction economics, while Japanese retail buyers of Pinkerton cultivars absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Certification gating under EU Green Deal deforestation-free mandates and USDA APHIS phytosanitary protocols restricts market access to operators with geolocated sourcing documentation and residue testing infrastructure. Supply concentrates in Mexico, Peru, and California, with over 80% of export-grade Hass volume originating from four Mexican Pacific states. Raw material dependencies center on drip irrigation components, ethylene management systems, and controlled-atmosphere storage equipment. Single-source vulnerability from Michoacán concentration exposes buyers to localized climate shocks and labor disruption. Distribution runs through Rotterdam, Los Angeles, and Miami cold-storage hubs with ripening-as-a-service capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water stress in Michoacán and Jalisco constrains orchard expansion, propping pricing across the projection horizon as supply growth lags foodservice demand acceleration.
For Market Incumbents: Lock in multi-year offtake contracts with United States quick-service restaurant chains before direct-to-grower procurement fragments volume further. Deepen backward integration into proprietary rootstock breeding to secure climate resilience as drought cycles intensify margin pressure. Satellite-verify orchard mapping to preempt EU Green Deal compliance exclusion from German and French supermarket private-label programs. For New Entrants and Emerging Players: The premium-to-economy price gap in Indian food processing offers white-space entry where domestic oil extraction capacity remains minimal despite rising urban demand for functional ingredients. Target underpenetrated frozen pulp segments in United Kingdom and Australia health-positioned beverage chains. Pursue ripening-as-a-service partnerships with third-party logistics providers rather than competing against their ethylene management infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated origin-country exporters with captive cold-chain assets and SADER or SENASA certification authority. Long-term viability favors operators combining orchard ownership in multiple hemispheres with destination-market ripening infrastructure. Watch for inflection in EU Green Deal enforcement intensity that would accelerate smallholder cooperative exclusion and consolidate volume toward compliant integrated players.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Foodservice Offtake Contracting | De-risks grower revenue against spot-market volatility while locking volume share. |
| Satellite-Verified Orchard Mapping | Enables EU Green Deal deforestation-free compliance and German supermarket qualification. |
| Controlled-Atmosphere Ripening Infrastructure | Extends post-harvest shelf life from 14 days to 21 days, reducing retail shrinkage. |
| Proprietary Rootstock Breeding Program | Improves yield consistency under variable climate conditions in Michoacán and Ica Valley. |
| Blockchain-IoT Traceability Integration | Marries temperature logging with immutable ledger records for real-time foodservice verification. |
Methodological Framework
USDA trade statistics, SADER export clearance records, and EU phytosanitary inspection reports formed the secondary backbone, cross-referenced against primary interviews with packhouse operations managers, cold-chain logistics directors, foodservice procurement leads, and supermarket category buyers. Bottom-up and top-down triangulation validated volume estimates across Mexican, Peruvian, and Californian supply clusters.
Bottom-up modeling anchored the analytical lens, building from orchard-level yield assumptions and export certification throughput while top-down checks against foodservice and retail consumption patterns calibrated final outputs. Segmentation dimensions spanned cultivar type, distribution channel structure, end-user format, and application processing tier. CAGRs derived from historical trade flow trajectories and contracted offtake pipeline visibility, with water stress indices and phytosanitary clearance velocity as avocado-specific forecast inputs.
Inputs from SADER, SENASA, and USDA APHIS were available through the study window; gaps in smallholder cooperative digitization rates introduce uncertainty bands around EU market access projections. Forecasts reflect documented assumptions on climate stress severity and enforcement trajectory of deforestation-free mandates. A model refresh is warranted upon material change in EU Green Deal implementation intensity or Michoacán water allocation policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
Fresh Figs Market
Fruits and Vegetables
Global Shiitake Mushroom Market
Fruits and Vegetables
Raisins Market
Fruits and Vegetables
Cranberries Market
Fruits and Vegetables
Date Fruit Market
Fruits and Vegetables
Lingonberry Market
Fruits and Vegetables
North America Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Global Orange Market
Fruits and Vegetables
Packaged Fresh Fruits Market
Fruits and Vegetables
Fruit Punnet Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Edible Flowers Market
Fruits and Vegetables
Guava Puree Market