
 Smart Car Tracking Systems Market | 2026-2036
Smart Car Tracking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Car Tracking Systems Market Analytics
Israeli telematics module producers is realigning capacity toward AI-enabled edge computing for vehicle diagnostics. Geotab Inc. leverages its open-platform architecture to sustain developer ecosystem loyalty across North American fleet accounts. Verizon Connect anchors its position through integrated video telematics and compliance management tools for commercial carriers. CalAmp competes in asset-tracking adjacencies while extending its software subscription revenue base.
Smart car tracking systems encompass hardware-software combinations that capture geolocation, vehicle telemetry, and driver behavior data through GPS receivers, cellular modems, and onboard diagnostic interfaces transmitting at 4G/5G or satellite frequencies. These systems serve commercial fleet operators, insurers, and individual owners by enabling real-time visibility, risk scoring, and operational optimization. GPS trackers occupy the largest product category due to universal compatibility with passenger and commercial vehicles, while OBD trackers represent the fastest-growing segment as plug-and-play installation eliminates professional wiring costs. Cellular technology dominates connectivity architecture, though satellite links are gaining traction in remote-route freight and mining applications where terrestrial coverage fails.
The Federal Communications Commission governs spectrum allocation for telematics devices in the United States, while the European Union's GDPR and Cybersecurity Act impose data sovereignty and breach-notification obligations on cross-border fleet platforms. The National Highway Traffic Safety Administration influences crash-data recorder standards that overlap with tracking system design requirements. Stakeholders must monitor evolving type-approval frameworks for V2X communication modules, as regulatory convergence between automotive safety and data privacy regimes will determine which platform architectures achieve scalable deployment.
Market Dynamics
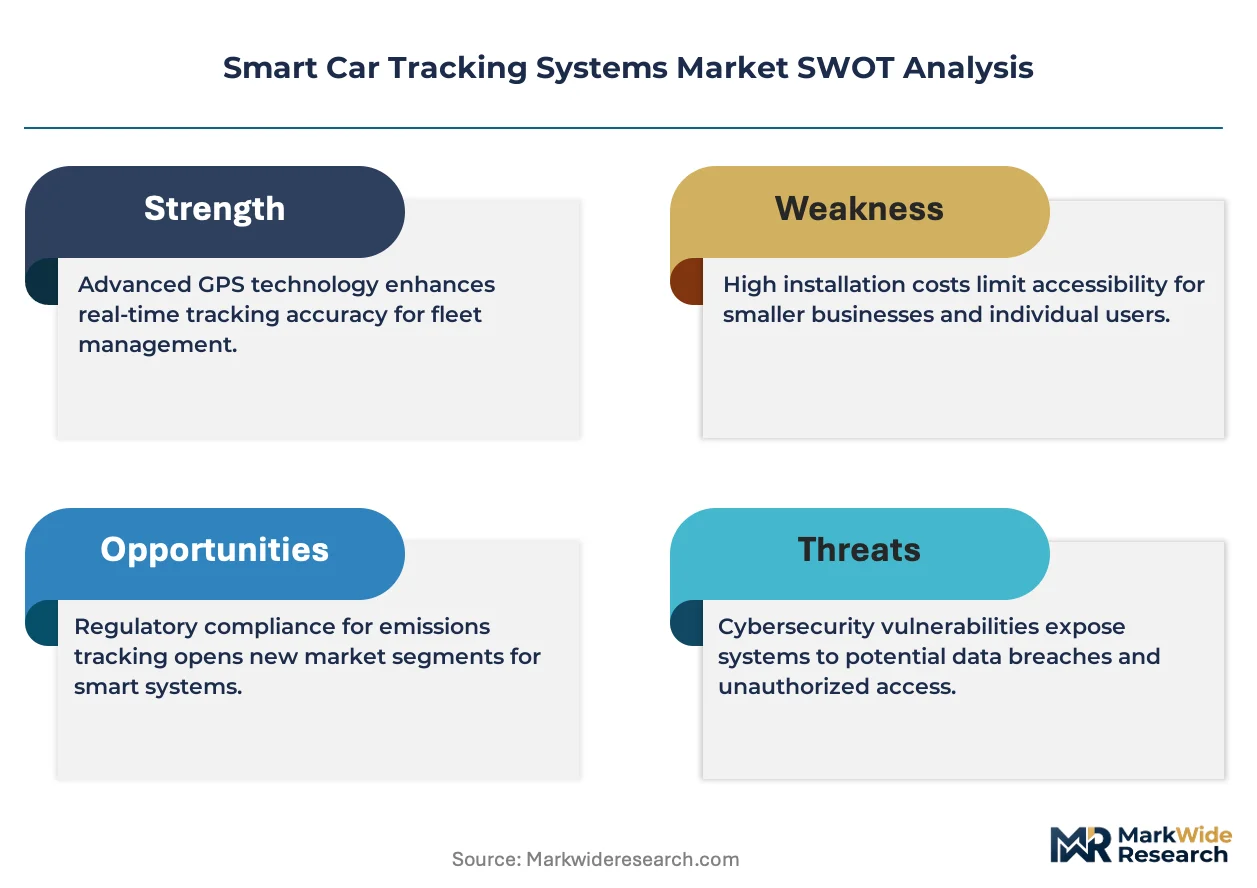
Fleet operators now mandate real-time visibility into vehicle diagnostics, fuel consumption, and driver safety metrics as baseline procurement requirements. This operational imperative is compressing hardware margins while elevating software subscription valuations across the vendor landscape.
Growth Catalysts
- EU Cybersecurity Act:Mandatory certification for connected-vehicle components is accelerating OEM integration of factory-fitted telematics modules in Germany and France.
- Insurance telematics:Usage-based pricing models require granular driving behavior data, pulling OBD plug-in devices into passenger vehicle aftermarket channels.
- Edge AI silicon:Israeli module producers are embedding inference engines directly into tracking hardware, enabling predictive maintenance without cloud latency.
Market Restraints
- Cellular modem supply:Concentrated fabrication in Taiwan and South Korea creates vulnerability to semiconductor allocation disruptions.
- GPS signal jamming:Electromagnetic interference in urban canyons and conflict zones degrades location accuracy below fleet operator thresholds.
- GDPR compliance costs:Cross-border data sovereignty requirements impose architectural constraints on cloud-hosted fleet management platforms.
Strategic Opportunities
- Brazil ANVISA pathway:Regulatory frameworks for pharmaceutical cold-chain logistics are creating demand for temperature-monitored vehicle tracking in São Paulo and Rio de Janeiro corridors.
- Satellite-cellular hybrid:Mining operators in Western Australia and Chilean Atacama require seamless handoff between terrestrial and orbital connectivity.
- Video telematics convergence:Integration of cabin-facing cameras with telematics platforms opens driver coaching and claims adjudication revenue streams.
Industry Challenges
- Firmware security patching:Over-the-air update infrastructure demands specialized DevSecOps talent scarce outside Tel Aviv and Bangalore engineering clusters.
- Legacy fleet integration:Pre-CAN-bus vehicles require analog sensor retrofitting, complicating unified platform deployment for mixed-age commercial fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Car Tracking Systems Market |
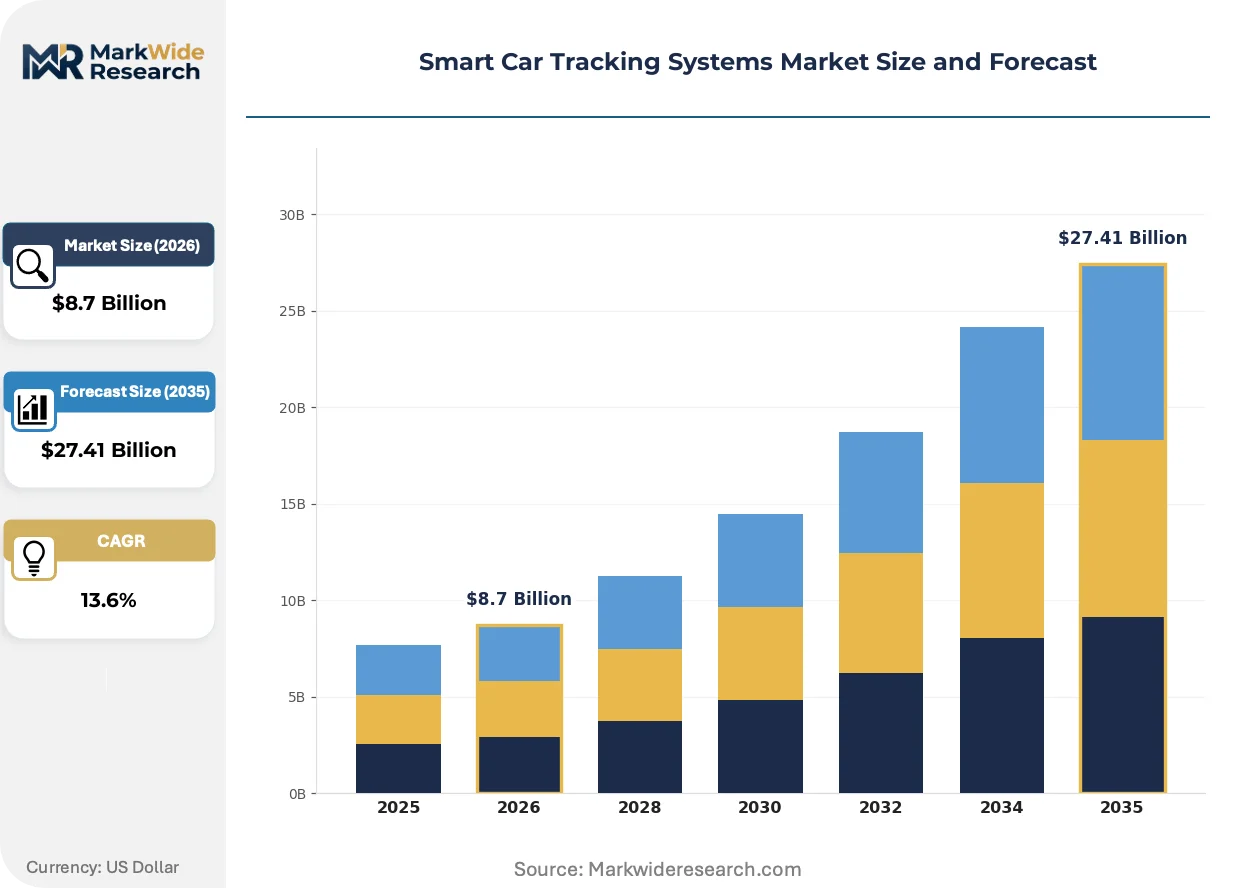
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Trackers, OBD Trackers, Bluetooth Trackers, RFID Trackers Technology: Cellular, Satellite, Wi-Fi, Zigbee End User: Fleet Management, Individual Consumers, Automotive Manufacturers, Insurance Companies Application: Real-Time Tracking, Theft Recovery, Driver Behavior Monitoring, Route Optimization |
| Companies Covered | Geotab Inc., Verizon Connect, TomTom International BV, CalAmp, TELTONIKA, Samsara, ORBCOMM, Cartrack, Sensata Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Car Tracking Systems Market Evolving Landscape
Telematics architecture is bifurcating between lightweight cloud-reliant systems and autonomous edge-computing platforms capable of local inference. This technological divergence is fragmenting vendor roadmaps and reshaping partnership strategies across the ecosystem.
AI-enabled edge processors are consolidating diagnostic workloads onto single-chip modules that execute anomaly detection without cellular backhaul. Heavy-duty freight carriers in Germany and long-haul operators across the US Interstate system are piloting these systems to maintain visibility in dead-zone corridors. The shift is compressing reliance on centralized cloud analytics while elevating hardware BOM costs.
The EU AI Act's risk classification framework is imposing documentation and audit requirements on automated driver-scoring algorithms. Telematics providers serving European commercial fleets must now maintain algorithmic transparency registers and human-in-the-loop override protocols. This regulatory architecture most directly affects insurers deploying automated premium adjustment models.
Subscription bundling is displacing perpetual hardware licensing as the dominant commercial model. Fleet management platforms now package device costs into monthly per-vehicle fees, transferring capital expenditure to operating budgets. This financing restructuring is most advanced in North American fleet accounts above 500 vehicles, where procurement teams prioritize cash-flow predictability over asset ownership.
Smart Car Tracking Systems Market Segmentation
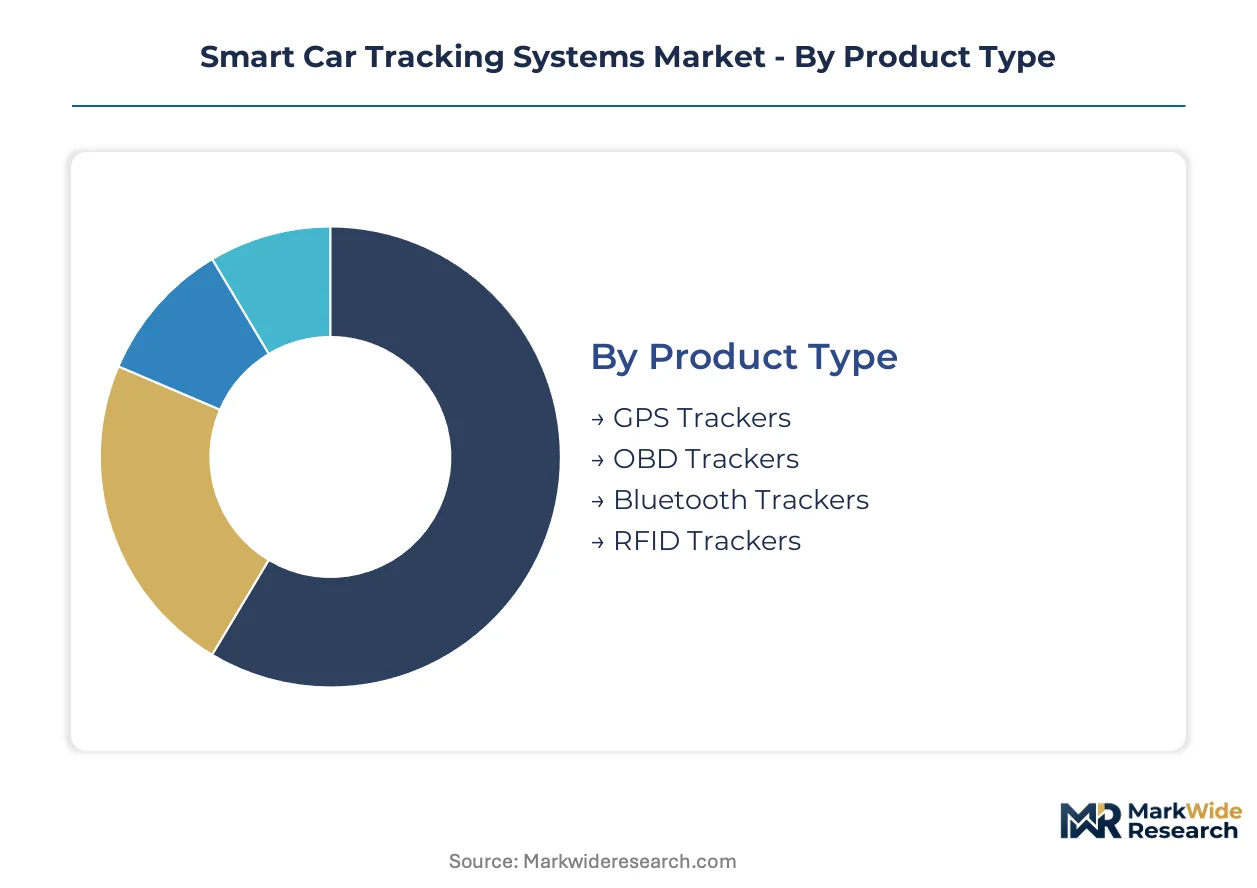
Segmentation in smart car tracking systems reveals distinct procurement patterns across hardware form factors, connectivity architectures, and buyer sophistication levels. Fleet operators prioritize real-time telemetry and regulatory compliance, while individual consumers favor plug-and-play simplicity and subscription flexibility.
Product Type:
Hardware differentiation centers on installation complexity, diagnostic depth, and power autonomy requirements across buyer tiers.
- GPS Trackers:Self-contained units combining GPS receivers with cellular modems in weatherized enclosures. Demand concentrates in German automotive OEM factory-fit programs and North American long-haul freight fleets requiring universal vehicle compatibility without OBD port dependency.
- OBD Trackers:Plug-in modules extracting CAN-bus diagnostic data alongside location telemetry. Insurance telematics programs in France and aftermarket channels in São Paulo corridor are pulling these devices fastest due to zero-installation deployment and immediate driver behavior visibility.
- Bluetooth Trackers:Short-range proximity devices leveraging smartphone tethering for location relay. Individual consumers in urban Japan and European city-car segments deploy these for parking location and theft recovery in dense metropolitan zones.
- RFID Trackers:Passive or active radio-frequency tags for yard management and controlled-access verification. Industrial mining operations in Western Australia and Chilean Atacama integrate these with satellite-cellular hybrids for asset handoff tracking.
Volume sits with GPS Trackers; growth tilts toward OBD Trackers.
Technology:
Connectivity architecture selection trades bandwidth cost against coverage continuity and latency tolerance for specific operational profiles.
- Cellular:Dominant 4G/5G modem architectures enabling real-time streaming telemetry and over-the-air firmware updates. Fleet management platforms above 500 vehicles in the United States and freight corridors across Germany standardize on cellular for its balance of bandwidth and hardware economy.
- Satellite:Orbital link terminals for beyond-cellular coverage in remote-route freight and resource extraction. Mining operators in Western Australia and Chilean Atacama require seamless terrestrial-to-satellite handoff where cellular infrastructure fails entirely.
- Wi-Fi:Local area connectivity for depot-based fleet synchronization and high-bandwidth data offload. Urban last-mile delivery operators in São Paulo and Rio de Janeiro leverage Wi-Fi for route optimization uploads during vehicle downtime.
- Zigbee:Low-power mesh networking for intra-vehicle sensor aggregation and short-range asset proximity detection. Cold-chain pharmaceutical logistics under Brazil ANVISA frameworks in São Paulo corridor deploy Zigbee for temperature sensor clustering alongside primary tracking.
Deployment breadth favors Cellular; steepest expansion trajectory belongs to Satellite.
End User:
Buyer categories separate by fleet scale, regulatory exposure, and integration depth with existing operational systems.
- Fleet Management:Commercial operators mandating real-time visibility into diagnostics, fuel consumption, and driver safety metrics as baseline procurement. These buyers dominate volume in North American accounts above 500 vehicles and German automotive OEM integrated programs.
- Individual Consumers:Private vehicle owners prioritizing theft recovery and usage-based insurance discounts. Demand clusters in French insurance telematics programs and Japanese urban parking location use cases.
- Automotive Manufacturers:OEMs embedding factory-fitted telematics modules for warranty compliance and connected services revenue. German KBA type-approval frameworks and EU Cybersecurity Act certification requirements are accelerating integration timelines.
- Insurance Companies:Underwriters deploying usage-based pricing models requiring granular driving behavior data. These entities are pulling OBD plug-in devices into passenger vehicle aftermarket channels fastest in France and São Paulo corridor.
Revenue concentration rests with Fleet Management; share gains are sharpest among Insurance Companies.
Application:
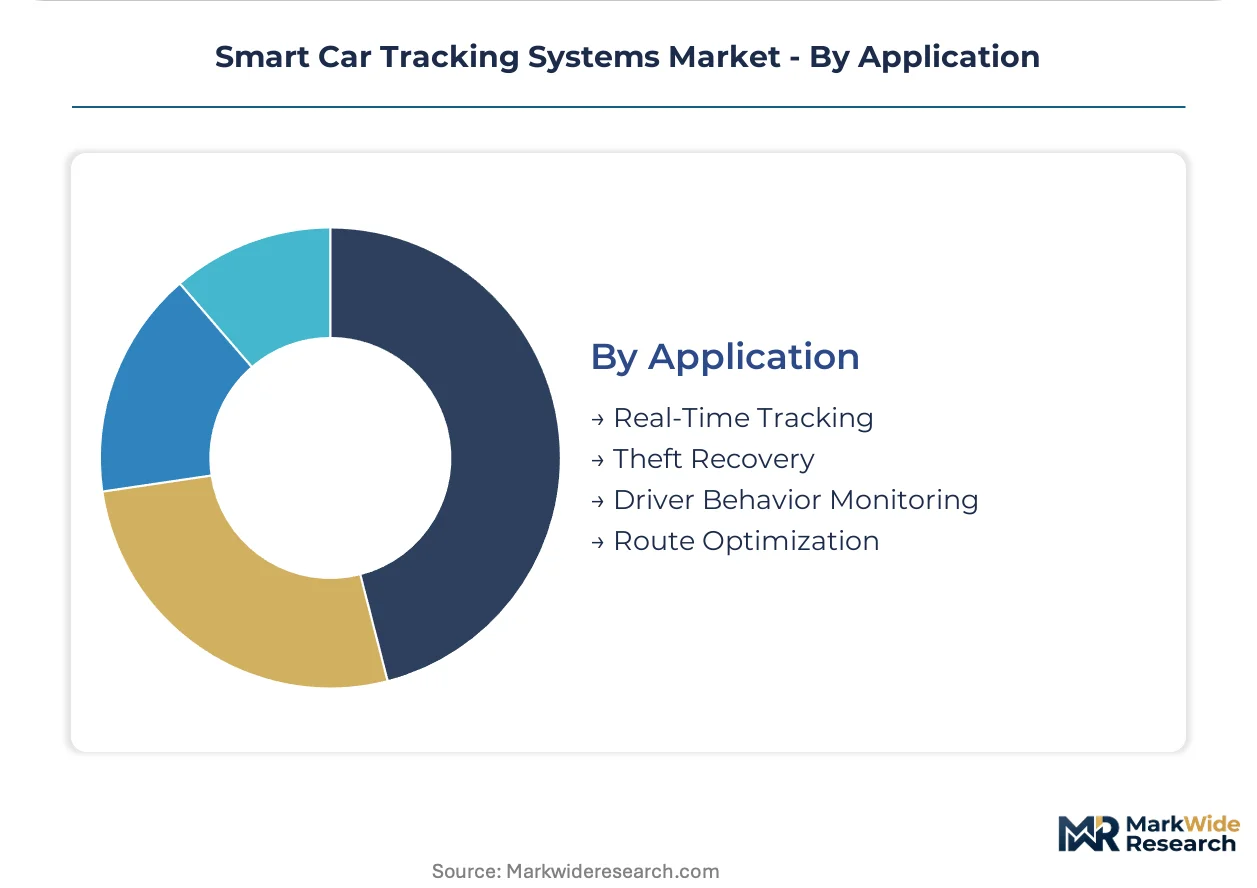
Functional use case prioritization reflects operational risk profiles and regulatory compliance obligations across buyer segments.
- Real-Time Tracking:Continuous geolocation visibility with sub-minute update frequencies for dispatch optimization. Fleet operators across US Interstate system and German freight corridors treat this as non-negotiable baseline capability.
- Theft Recovery:Stolen vehicle location and immobilization services triggered by unauthorized movement alerts. Individual consumers in Japanese urban centers and Brazilian metropolitan zones prioritize this for asset protection.
- Driver Behavior Monitoring:Acceleration, braking, and cornering telemetry for risk scoring and coaching. Insurance telematics programs in France and fleet safety initiatives in Germany embed these algorithms under EU AI Act transparency requirements.
- Route Optimization:Algorithmic path planning incorporating traffic, fuel cost, and delivery window constraints. Last-mile operators in São Paulo and Rio de Janeiro corridors deploy this for fuel efficiency gains in dense urban environments.
Platform ubiquity centers on Real-Time Tracking; algorithmic sophistication is advancing fastest in Driver Behavior Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication in Taiwan and South Korea anchors cellular modem supply chains for telematics hardware. German automotive OEMs and North American freight operators drive procurement volumes across distinct regulatory environments.
United States
Fleet operators above 500 vehicles mandate real-time diagnostics and driver safety metrics as baseline requirements. The FCC governs spectrum allocation for telematics devices while the NHTSA influences crash-data recorder standards overlapping with tracking system design. Engineering talent clusters in Silicon Valley and Austin sustain over-the-air firmware development for commercial platforms.
Germany
Automotive OEMs integrate factory-fitted telematics modules for warranty compliance and connected services revenue. The KBA type-approval framework and EU Cybersecurity Act certification accelerate integration timelines for connected-vehicle components. Manufacturing concentrates in Baden-Württemberg and Bavaria where Bosch and Continental anchor supplier ecosystems.
Israel
Telematics module producers realign capacity toward AI-enabled edge computing for vehicle diagnostics. The country's national cybersecurity regulator imposes breach-notification obligations on connected-vehicle component exports. Tel Aviv engineering clusters specialize in DevSecOps talent for firmware security patching infrastructure.
Brazil
ANVISA regulatory frameworks for pharmaceutical cold-chain logistics create demand for temperature-monitored vehicle tracking in São Paulo and Rio de Janeiro corridors. The national telecommunications regulator oversees cellular spectrum allocation for fleet management platforms. Last-mile delivery operators in São Paulo deploy Wi-Fi for route optimization uploads during vehicle downtime.
Australia
Mining operators in Western Australia require seamless terrestrial-to-satellite connectivity handoff where cellular infrastructure fails entirely. The national communications regulator manages spectrum for remote-area telematics deployment. Perth-based engineering teams support satellite-cellular hybrid installations for resource extraction fleets.
Smart Car Tracking Systems Market Competitive Landscape
Global majors compete with regional champions across platform architecture and developer ecosystem loyalty. The vendor landscape compresses hardware margins while elevating software subscription valuations. Three archetypes dominate: open-platform specialists, integrated video telematics providers, and edge-AI module producers. Capacity expansion and strategic partnerships constitute the primary competitive moves as firms defend position in fleet accounts.
Among North American platform providers, Geotab Inc. and Verizon Connect exemplify contrasting approaches to fleet management ecosystem development. Geotab represents the open-platform archetype sustaining developer loyalty through API accessibility. Verizon Connect anchors the integrated solutions tier combining video telematics with compliance tooling. CalAmp occupies a position spanning asset-tracking adjacencies and software subscription revenue expansion. Israeli producers including TELTONIKA sit within the edge-computing specialization tier embedding inference engines directly into hardware modules.
| Leading Market Players |
|---|
| Geotab Inc. |
| Verizon Connect |
| TomTom International BV |
| CalAmp |
| TELTONIKA |
| Samsara |
| ORBCOMM |
| Cartrack |
| Sensata Technologies Inc. |
| Others |
Value Network & Pricing Analysis
Fleet operators above 500 vehicles in North America and Germany concentrate procurement volumes, compressing hardware margins while elevating software subscription valuations as the dominant commercial model across vendor tiers.
Pricing Analysis
Warranty bundling and factory-fit integration separate premium-tier OEM supply contracts from aftermarket hardware sales. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service inclusion. Cost compression in hardware components is intensifying because cellular modem supply constraints limit vendor negotiating leverage. Individual consumers in insurance telematics programs exhibit highest price sensitivity, while German automotive OEMs prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive manufacturers and North American freight fleets above 500 vehicles. Taiwan and South Korea anchor cellular modem fabrication, while Israeli engineering clusters feed edge-AI module development. Raw material dependencies span GPS receiver chipsets, 4G/5G baseband processors, and lithium-polymer power cells. Single-source vulnerability in Taiwan semiconductor fabrication creates systemic exposure to allocation disruptions. Distribution runs through Tier 1 automotive suppliers and specialized telematics platform vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Car Tracking Systems Market sits in a technology-transition phase as edge-AI silicon displaces cloud-dependent diagnostic architectures across commercial fleet deployments.
For Market Incumbents: Cement platform loyalty through API ecosystem investment and DevSecOps talent acquisition in Tel Aviv and Bangalore clusters. Hardware margin erosion from cellular modem supply constraints demands backward integration into edge-processor design. OEM factory-fit mandates under EU Cybersecurity Act certification requirements represent the priority defensive perimeter. For New Entrants and Emerging Players: Begin with satellite-cellular hybrid deployments in Western Australian mining corridors and Chilean Atacama resource extraction, where terrestrial coverage gaps create white-space demand. Brazilian pharmaceutical cold-chain logistics under ANVISA frameworks offer penetrable regulatory-driven entry. Channel partnership with regional fleet management platforms accelerates market access without direct sales infrastructure. For Investors and Strategic Acquirers: The window for entry favors edge-AI module specialists with automotive-grade certification progress and Israeli engineering presence. Long-term viability hinges on algorithmic transparency compliance under EU AI Act risk classification frameworks. Watch for firmware security patching infrastructure maturity as inflection indicator for scalable deployment capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Module Development | Israeli engineering clusters embed inference engines for predictive maintenance without cloud latency. |
| EU Cybersecurity Act Certification | German KBA type-approval frameworks accelerate OEM factory-fit integration timelines. |
| Satellite-Cellular Hybrid Deployment | Mining operators in Western Australia require seamless terrestrial-to-orbital connectivity handoff. |
| Video Telematics Convergence | Integration of cabin-facing cameras opens driver coaching and claims adjudication revenue streams. |
| Subscription Bundling Restructuring | North American fleet accounts above 500 vehicles prioritize cash-flow predictability over asset ownership. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fleet operations directors, telematics platform engineers, OEM procurement managers, and insurance telematics program leads combined with FCC spectrum allocation databases, EU Cybersecurity Act certification registries, and vehicle production statistics. Bottom-up unit economics and top-down market sizing triangulated volume and value estimates.
Data-stream reconciliation across hardware shipment volumes, software subscription registrations, and OEM integration timelines informed the analytical framework. Segmentation dimensions modeled include hardware form factor, connectivity architecture, fleet scale tier, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to technology adoption patterns across commercial fleet segments. Edge-AI processor deployment rates and satellite-cellular hybrid installation growth served as industry-specific forecast inputs throughout the projection horizon.
Underlying measurement precision varies by segment; GPS tracker hardware shipments carry tighter precision than emerging edge-AI module categories. Forecasts reflect assumptions regarding cellular infrastructure buildout rates, regulatory certification timelines, and semiconductor allocation normalization. Periodic stress-testing of base assumptions is recommended given firmware security patching talent scarcity and geopolitical exposure in Taiwan fabrication concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Temperature-Controlled Last-Mile Delivery Services Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Contactless Ticketing Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Smart Bus Shelters Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Parking Finder Apps Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
Connected Parking Solutions Market