
 Global Connected Mobility Solutions Market | 2026-2036
Global Connected Mobility Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Connected Mobility Solutions Market Foresight
Automotive OEM-direct software licensing is rewriting how connected mobility capabilities reach end users. Tesla leverages over-the-air update architecture to sustain recurring revenue streams from its vehicle-installed base. BMW Group anchors premium positioning through proprietary infotainment and driver assistance integration. Bosch competes across multiple technology layers, extending its reach from sensor hardware into cloud-based fleet analytics platforms.
Connected mobility solutions encompass integrated hardware-software systems that enable real-time data exchange between vehicles, infrastructure, and cloud platforms through cellular IoT, V2X, and 5G protocols operating at sub-6 GHz and mmWave frequencies. These systems serve commercial and municipal operators by optimizing route efficiency, reducing idle time, and enabling predictive maintenance across distributed vehicle assets. Fleet management and telematics solutions dominate current revenue pools, while V2X and 5G-enabled traffic management represent the fastest-expanding segments as cities deploy edge computing nodes. Infotainment occupies a mature margin position where Harman International Industries and Volkswagen Group battle for cockpit software control, whereas cellular IoT modules face pricing pressure from commoditizing GPS and Wi-Fi alternatives.
The U.S. Department of Transportation's V2X deployment guidance, the EU AI Act's algorithmic transparency requirements, and China's MIIT GB standards for intelligent connected vehicles collectively shape product certification timelines and cross-border data flow architectures. NHTSA crash-avoidance mandates and ETSI spectrum allocation rules for C-V2X directly determine which technology suppliers gain market access in North America versus Europe. Stakeholders must monitor regulatory divergence on data localization, as diverging GDPR-derived privacy frameworks and China's Cybersecurity Law create incompatible compliance baselines for global platform deployments.
Market Dynamics
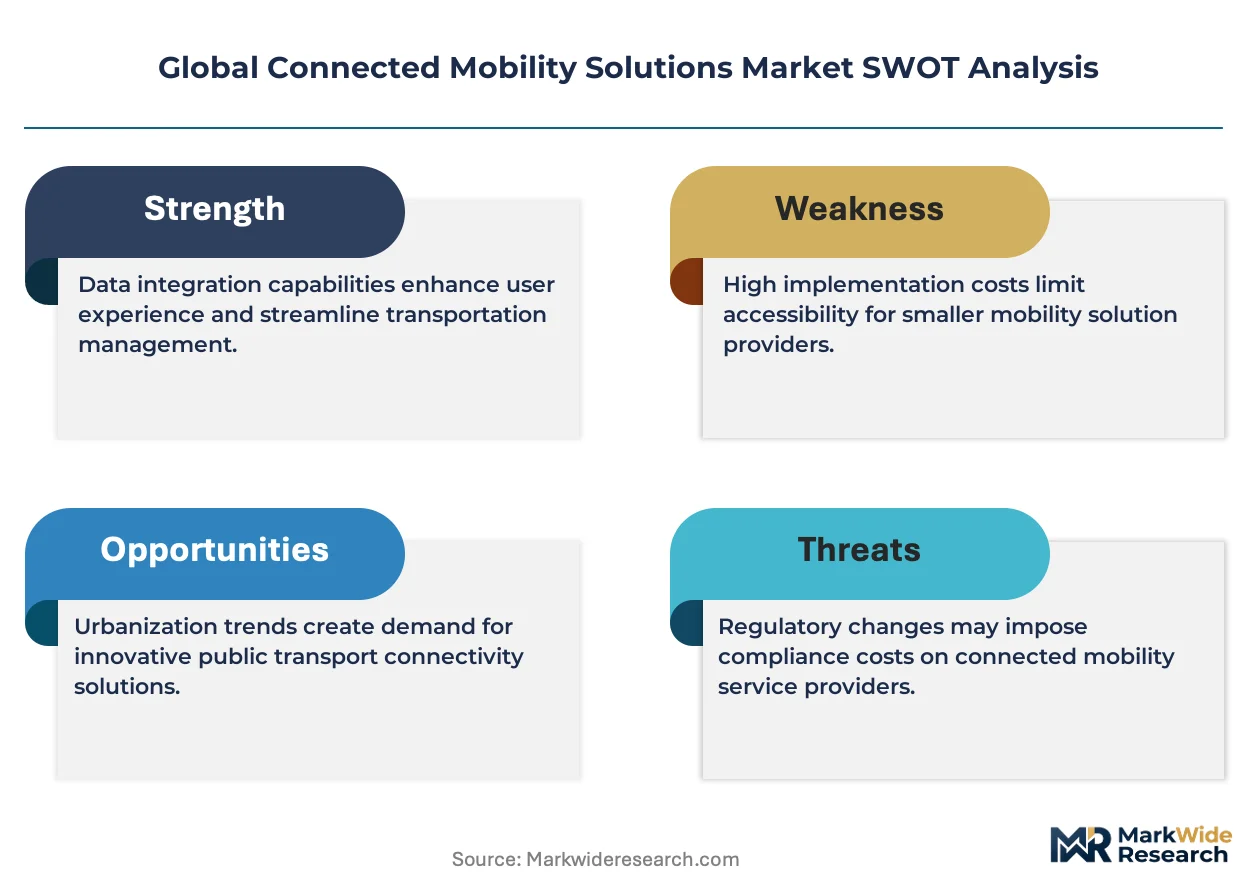
Cellular IoT module commoditization is compressing hardware margins while forcing suppliers toward recurring software revenue models anchored in fleet analytics and predictive maintenance subscriptions.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Vehicle manufacturers must deploy explainable AI for autonomous decision-making, creating certified demand for compliant middleware stacks across German and French automotive supply chains.
- China MIIT dual carbon policy enforcement:Intelligent transport ecosystems receive preferential licensing, accelerating OEM deployment of V2X-enabled energy management systems in municipal bus and logistics fleets.
- Edge computing node density:Urban traffic authorities in Singapore, Dubai, and Barcelona are installing roadside units that require compatible onboard units, pulling hardware refresh cycles forward.
Market Restraints
- Semiconductor input volatility:Automotive-grade cellular modems and GNSS chipsets face allocation constraints from concentrated foundry capacity in Taiwan, creating 26-40 week lead time variability.
- Regulatory fragmentation on data localization:China's Cybersecurity Law mandates domestic server storage while GDPR-derived frameworks in Germany and France impose cross-border transfer restrictions, forcing dual architecture investments.
- DSRC technology obsolescence risk:Early C-V2X adopters in the United States face stranded asset exposure as NHTSA withdraws interoperability commitments from legacy 5.9 GHz spectrum allocations.
Strategic Opportunities
- Underpenetrated Brazilian fleet telematics:ANVISA and CONTRAN regulations are mandating electronic logging for long-haul trucking, opening first-mover advantage for integrated platform providers before local champions consolidate.
- Insurance-telematics convergence:Usage-based coverage models in the United Kingdom and Italy require real-time driving behavior data streams, creating partnership channels between mobility platforms and underwriters.
- 5G-Advanced network slicing:German and South Korean carriers are offering guaranteed latency tiers for autonomous platooning applications, enabling premium service tiers for commercial vehicle operators.
Industry Challenges
- Embedded systems cybersecurity certification:UN R155 and ISO/SAE 21434 compliance timelines extend 18-24 months for new platform architectures, delaying revenue recognition.
- Legacy fleet integration complexity:Mixed-age vehicle assets with OBD-II versus CAN-FD diagnostic protocols require middleware abstraction layers that inflate deployment engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Connected Mobility Solutions Market |
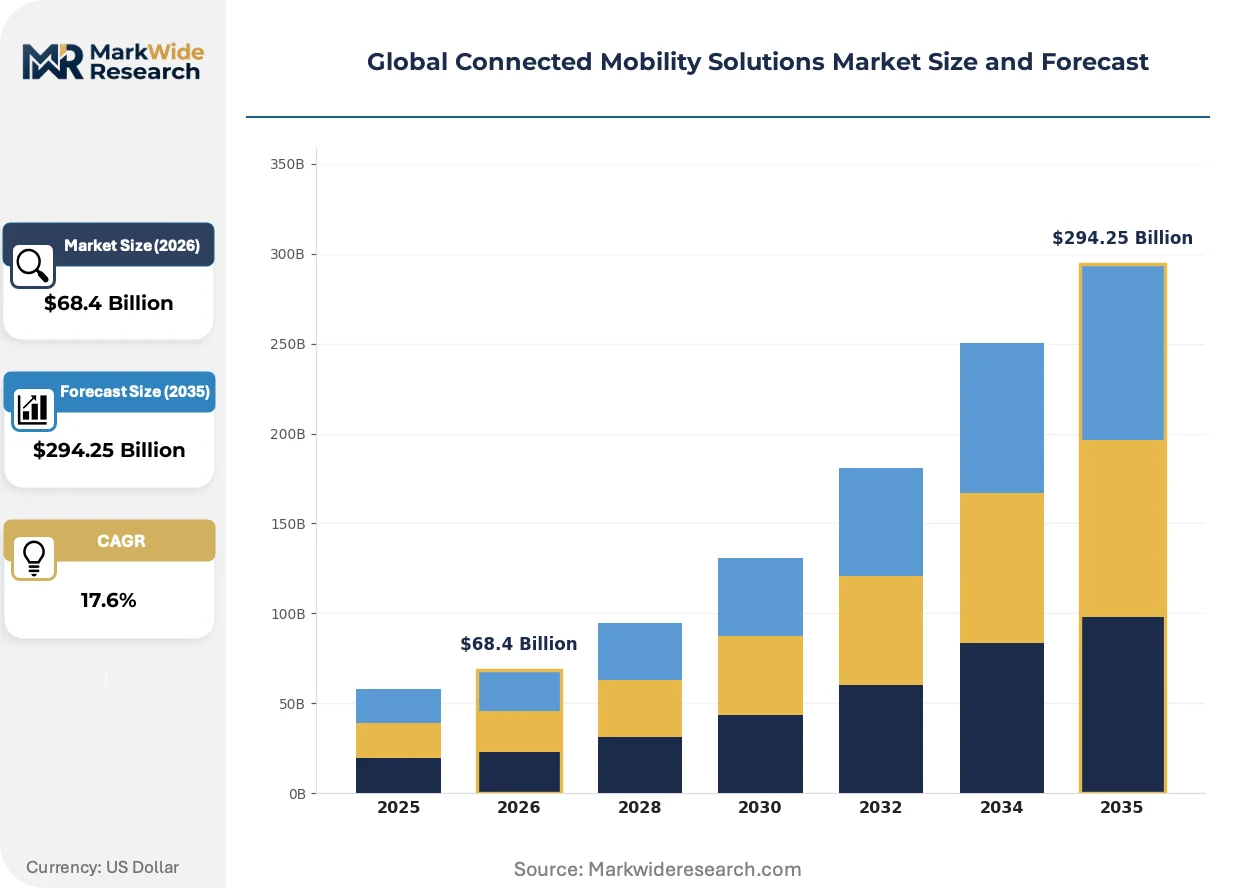
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $294.25 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Fleet Management, Telematics, Vehicle Tracking, Driver Assistance, Infotainment, Traffic Management Technology: 5G, LTE, V2X, GPS, Cellular IoT, Wi-Fi Application: Urban Transportation, Logistics, Public Transit Systems, Ride Sharing, Car Rental Services, Smart Parking End User: Vehicle Manufacturers, Fleet Operators, Transportation Authorities, Delivery Companies, Technology Service Providers |
| Companies Covered | Tesla, BMW Group, General Motors, Ford Motor Company, Continental AG, Toyota Motor Corporation, Volkswagen Group, Harman International Industries, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Connected Mobility Solutions Market Shifts & Advancements
Software-defined vehicle architectures are dissolving the boundary between hardware lifecycle and feature delivery, enabling continuous capability expansion without physical retrofit. This shift restructures how mobility services monetize installed base value.
Digital twin technology for predictive maintenance is virtualizing the traditional relationship between physical asset condition and service scheduling. Fleet operators in Germany and Japan are deploying high-fidelity powertrain simulations that compress diagnostic latency from weeks to hours. The technology is virtualizing aftermarket parts procurement by enabling component-level failure forecasting before fault codes trigger.
ETSI's mandatory C-V2X spectrum harmonization across EU member states is eliminating national fragmentation that previously forced hardware variants. Automotive suppliers must now certify single-SKU modules for pan-European deployment, reducing inventory complexity but intensifying compliance documentation burdens. German KBA type-approval timelines have extended 30% as test protocols incorporate cybersecurity validation.
Subscription-based feature activation is displacing upfront option bundling in premium vehicle segments. BMW Group and Mercedes-Benz customers in the United States and United Kingdom now unlock driver assistance capabilities through over-the-air purchases rather than factory configuration. This purchasing pattern shift concentrates lifetime value capture with OEMs while reducing dealer margin participation in technology upsells.
Global Connected Mobility Solutions Market Segmentation
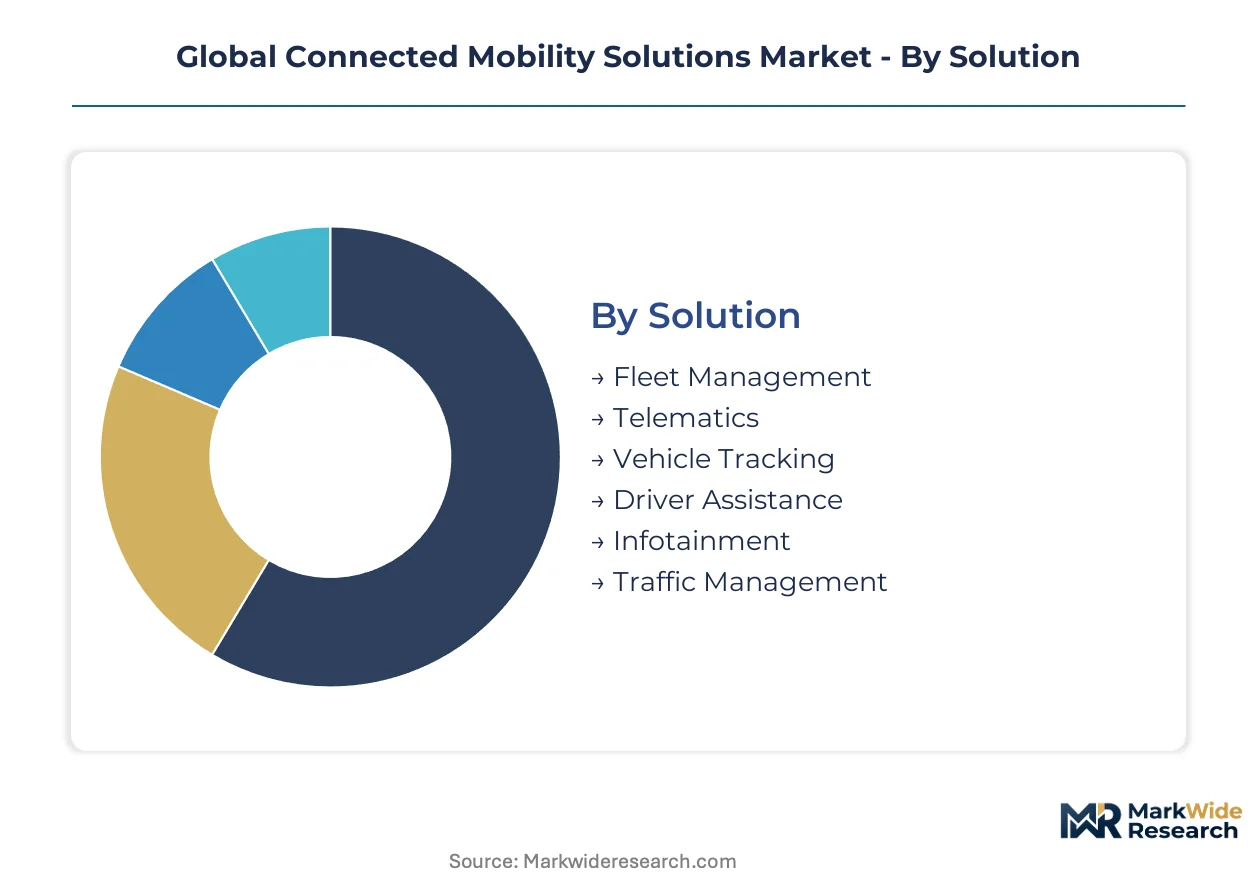
Segmentation in connected mobility solutions reveals divergent investment cycles across hardware, software, and service layers. Fleet operators prioritize telematics platforms with 3-5 year refresh windows, while municipal infrastructure deployments stretch across decade-long amortization schedules.
Solution:
Hardware-intensive segments turn inventory fastest, whereas software-heavy offerings sustain longer revenue recognition timelines through subscription architectures.
- Fleet Management:Integrated platforms combine cellular IoT hardware with cloud-based analytics dashboards for route optimization and fuel consumption monitoring. German logistics operators and Dubai-based fleet aggregators are consolidating procurement around single-vendor stacks to reduce integration overhead.
- Telematics:Onboard diagnostic units transmit engine health, location, and driver behavior data through embedded cellular modems. Brazilian long-haul trucking mandates under CONTRAN are accelerating replacement cycles for legacy OBD-II devices.
- Vehicle Tracking:GPS-GNSS fused positioning systems serve theft recovery and asset visibility use cases with minimal compute requirements.
- Driver Assistance:ADAS middleware stacks process camera and radar inputs for collision avoidance, requiring ISO 26262 functional safety certification.
- Infotainment:Cockpit software platforms integrate navigation, media, and third-party application ecosystems through automotive-grade Android or proprietary OS layers.
- Traffic Management:Edge-enabled signal coordination systems process V2X broadcasts from connected vehicles to optimize intersection throughput.
Fleet Management dominates installed base. Traffic Management is where expansion concentrates.
Technology:
Wireless protocols stratify by latency tolerance, with mission-critical applications demanding dedicated spectrum while cost-sensitive tracking tolerates unlicensed alternatives.
- 5G:Network slicing capabilities enable guaranteed latency tiers below 10 milliseconds for autonomous platooning and remote vehicle operation. South Korean carriers and German automotive testbeds are commercializing ultra-reliable low-latency service tiers for commercial vehicle operators.
- LTE:Cat-M1 and NB-IoT variants provide sufficient bandwidth for telematics and tracking at sub-5G hardware cost structures.
- V2X:C-V2X PC5 sidelink and DSRC alternatives enable direct vehicle-to-vehicle and vehicle-to-infrastructure communication without cellular network dependency. ETSI harmonization across EU member states is collapsing national hardware variants into single-SKU modules.
- GPS:Multi-constellation receivers incorporating Galileo, GLONASS, and BeiDou enhance accuracy in urban canyon environments.
- Cellular IoT:Embedded modules combining modem, processor, and antenna in compact form factors face commoditization pressure from Asian module vendors.
- Wi-Fi:802.11p derivatives and Wi-Fi 6 enable high-bandwidth local data offload for software updates and infotainment content caching.
LTE anchors current deployment volume. 5G is climbing the fastest as infrastructure density reaches critical mass in automotive manufacturing clusters.
Application:
Urban density and vehicle utilization rates determine technology stack complexity, with high-rotation applications justifying premium connectivity investments.
- Urban Transportation:Municipal bus and metro systems integrate real-time passenger information with traffic signal priority through centralized control centers. Singapore's Land Transport Authority and Barcelona's transit operators are deploying edge computing nodes for sub-second response times.
- Logistics:Long-haul freight and last-mile delivery fleets optimize routing through predictive traffic and warehouse dock scheduling integration.
- Public Transit Systems:Rail and bus networks prioritize passenger safety monitoring and capacity management over individual vehicle telemetry.
- Ride Sharing:Driver-rider matching platforms require continuous location streaming with battery-optimized mobile SDK implementations.
- Car Rental Services:Asset recovery and usage-based billing drive telematics adoption in airport and urban rental fleets.
- Smart Parking:Sensor networks and mobile payment integration reduce circling traffic and enforcement labor costs in congested city centers.
Logistics commands the largest hardware procurement volumes. Urban Transportation is gaining share fastest as municipal budgets recover and federal infrastructure funding flows to intelligent transport projects.
End User:
Procurement sophistication varies dramatically, with technology-native buyers demanding API-first platforms while traditional operators prioritize turnkey deployment simplicity.
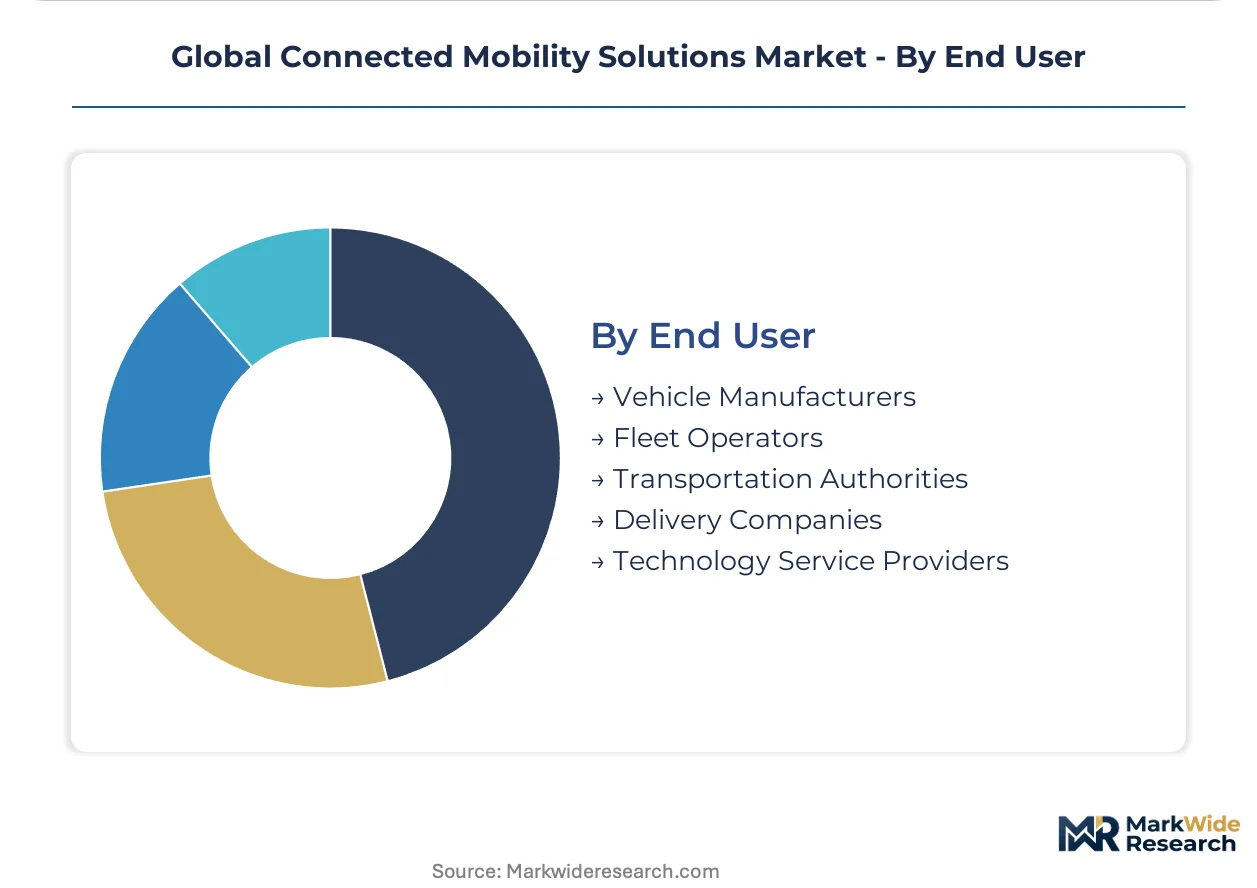
- Vehicle Manufacturers:OEMs integrate connected mobility capabilities at the electrical architecture design phase, enabling over-the-air update pathways and subscription revenue models. Tesla and BMW Group anchor proprietary stack development, while volume manufacturers license from Bosch and Harman International Industries.
- Fleet Operators:Commercial vehicle aggregators procure telematics at scale, negotiating volume discounts against standardized device specifications.
- Transportation Authorities:Municipal and national agencies mandate interoperability standards, creating certified supplier lists that constrain vendor selection.
- Delivery Companies:E-commerce fulfillment networks optimize last-mile routing through real-time driver behavior analytics and dynamic customer communication.
- Technology Service Providers:Cloud platforms and systems integrators white-label mobility solutions for downstream vertical markets.
Fleet Operators dominate installed base. Vehicle Manufacturers is where expansion concentrates as software-defined vehicle architectures dissolve hardware-software boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's V2X testbed anchors Germany's role in validating connected freight corridors, while Singapore's Tuas Mega Port underwrites autonomous container logistics trials that cascade into urban mobility standards.
United States
NHTSA's V2X deployment guidance and commercial platooning permits on Interstate corridors accelerate fleet operator procurement. The Department of Transportation's Infrastructure Investment and Jobs Act channels funding toward roadside unit installations. Michigan's automotive manufacturing clusters around Detroit host validation facilities where OEMs test C-V2X interoperability before national rollout.
Germany
KBA type-approval extensions and EU AI Act compliance timelines compress vendor certification windows. ETSI spectrum harmonization eliminates hardware variants previously required for cross-border fleet operations. Stuttgart's automotive engineering ecosystem concentrates software-defined vehicle development, with suppliers co-locating cybersecurity validation labs alongside OEM headquarters.
China
MIIT's GB standards for intelligent connected vehicles and dual carbon enforcement reshape municipal procurement criteria. The Cybersecurity Law mandates domestic data storage, fragmenting cloud architectures for multinational platform providers. Shanghai's Yangshan automated port and Beijing's intelligent transport corridors serve as testbeds for V2X-enabled energy management in logistics fleets.
Japan
METI's connected vehicle roadmaps prioritize automated highway systems and disaster-response mobility networks. Domestic OEMs integrate V2X capabilities into kei-car segments previously excluded from premium connectivity offerings. Nagoya's Chubu manufacturing belt hosts supplier parks where tier-one electronics firms prototype edge computing modules for traffic signal coordination.
South Korea
Sejong City's autonomous vehicle regulatory sandbox and 5G-Advanced network slicing trials create commercial deployment pathways. Korean carriers commercialize guaranteed latency tiers below 10 milliseconds for platooning applications. Busan's port automation projects extend V2X protocols into heavy freight corridors connecting manufacturing zones to maritime terminals.
Global Connected Mobility Solutions Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor hardware and modem supply. The market structures around three layers: automotive OEMs with proprietary stack control, tier-one suppliers spanning multiple technology domains, and pure-play software vendors monetizing through recurring subscriptions. Consolidation pressures concentrate in fleet analytics platforms where scale determines data network effects. Competitive moves center on strategic partnerships between carriers and automotive suppliers, plus backward integration into semiconductor sourcing to secure modem allocation.
Within the automotive OEM archetype, Tesla and BMW Group exemplify divergent pathways to software-defined vehicle monetization. Tesla's over-the-air update architecture sustains recurring revenue from its installed base, while BMW Group anchors premium positioning through proprietary infotainment integration. Bosch occupies a multi-layer position extending from sensor hardware into cloud-based fleet analytics, representing the tier-one supplier archetype that competes across technology boundaries. Harman International Industries sits within the cockpit software specialization tier, battling for infotainment platform control against automotive-owned alternatives.
| Leading Market Players |
|---|
| Tesla |
| BMW Group |
| General Motors |
| Ford Motor Company |
| Continental AG |
| Toyota Motor Corporation |
| Volkswagen Group |
| Harman International Industries |
| Bosch |
| Others |
Supply & Pricing Matrix
The Hamburg-Rotterdam freight corridor concentrates logistics procurement decisions among German and Dutch fleet operators, compressing hardware margins through consolidated volume negotiations while creating price differentiation between certified V2X-compliant modules and commoditized cellular IoT alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified driver assistance stacks from basic telematics and unlicensed GPS-only tracking. Certification grade and volume scale drive price differentiation, with German OEM procurement pools commanding steepest discounts. Cost compression in cellular IoT modules is intensifying because Asian module vendors are flooding spot markets. Fleet aggregators exhibit highest price sensitivity; premium vehicle manufacturers show lowest.
Supply Chain Analysis
Extended payment terms from German automotive OEMs now stretch 90-120 days, forcing tier-one suppliers to utilize supply-chain finance facilities anchored in Taiwanese and South Korean banking networks. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan; automotive-grade cellular modems and GNSS chipsets draw from these concentrated foundry pools. Single-source vulnerability around Taiwan Strait logistics threatens component availability. Distribution runs through tier-one supplier direct contracts with OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across North American and European long-haul segments has shifted procurement leverage toward buyers with 10,000-plus vehicle portfolios, fragmenting vendor pricing power.
For Market Incumbents: Insulate recurring revenue streams by deepening proprietary cloud analytics capabilities against pure-play software entrants. Secure captive supply of automotive-grade cellular modems through strategic foundry partnerships in South Korea. Prioritize UN R155 cybersecurity certification investment to extend KBA type-approval moats. For New Entrants and Emerging Players: Brazilian long-haul telematics underpenetration offers first-mover positioning before ANVISA mandates harden procurement requirements. Target municipal bus operators in Southeast Asian smart city corridors where edge computing infrastructure investments are accelerating. Pursue white-label partnerships with regional carriers to bypass direct OEM sales channel barriers. For Investors and Strategic Acquirers: Cloud-native fleet analytics specialists with API-first architectures represent priority acquisition targets as data network effects concentrate value. Five-to-ten-year viability hinges on platform scale thresholds where real-time vehicle data streams achieve predictive maintenance accuracy premiums. Monitor German KBA type-approval queue lengths as inflection indicator for vendor certification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | BMW Group and Tesla monetize over-the-air feature activation, displacing dealer margin capture. |
| C-V2X Spectrum Harmonization | ETSI-mandated single-SKU modules collapse EU national hardware variants, reducing inventory complexity. |
| Battery Supply Agreement | Electric fleet operators secure cell allocation priority as automotive-grade modem demand competes for foundry capacity. |
| Geographic Manufacturing Footprint | Stuttgart supplier parks co-locate cybersecurity validation labs with OEM headquarters, compressing certification timelines. |
| Charging Infrastructure Partnership | Intelligent transport corridors in Shanghai and Beijing integrate V2X-enabled energy management for logistics electrification. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, tier-one supplier procurement leads, fleet operations directors, and municipal transport authority planners; and secondary validation against MIIT GB standard filings, ETSI spectrum allocation records, NHTSA V2X deployment guidance, and vehicle production registration databases. Bottom-up and top-down triangulation cross-checked segment assumptions.
Forecast inputs considered solution layer, wireless protocol technology, application intensity, and end-user procurement sophistication across the analysis window. CAGRs derived from installed base expansion rates, technology refresh cycles, and regulatory compliance deadline clustering. Specific inputs included KBA type-approval timeline trajectories and edge computing node deployment densities in German and Singaporean testbeds.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Chinese state-backed platform providers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Mobility Market
Smart Transportation Solutions
Smart Rail Suite Solutions Market
Smart Transportation Solutions
Ride-Hailing Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Europe Bike Sharing Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Shared Vehicles Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Global Parking Management Software Market
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Smart Car Digital Key System Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Europe Smart Transportation Market
Smart Transportation Solutions
Sustainable Last-Mile Delivery Network Design Services Market
Smart Transportation Solutions
Micro Mobility Market