
 Mining Machinery Battery Market | 2026-2036
Mining Machinery Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Machinery Battery Market Foresight
Underground mine operators are reorganizing procurement priorities toward electrified fleets as diesel emissions costs mount. Caterpillar leverages its integrated powertrain engineering to anchor large-scale deployments across North American and Australian hard-rock sites. Komatsu competes through its dedicated underground electrification division, while Epiroc differentiates with battery-electric drilling and loading systems purpose-built for narrow-vein operations.
Mining machinery batteries are electrochemical energy storage systems engineered to power heavy-duty extraction, hauling, and material handling equipment in subterranean and open-pit environments, typically delivering sustained high-discharge currents across extreme temperature cycles and mechanical shock loads. Lithium-ion chemistry dominates new installations due to superior energy density and cycle life versus legacy lead-acid alternatives, though lead-acid retains substantial share in surface material handling where weight tolerance and capital constraints favor proven technology. Solid-state technology represents the fastest-growing R&D trajectory, with flow battery architectures gaining traction in fixed-site auxiliary power roles where scalability outweighs mobility requirements.
The EPA enforces Tier 4 Final and emerging zero-emission mandates for non-road equipment, directly compelling mine fleets toward battery-electric retrofits and original equipment purchases. The EU Green Deal and F-Gas Regulation further constrain diesel and fluorinated gas reliance, while ISO 19453 standards govern thermal and vibration resilience for battery systems in off-road machinery. Stakeholders must track regulatory divergence between jurisdictions to avoid stranded asset risk in multi-national mining portfolios.
Market Dynamics
The mining machinery battery market pivots on diesel displacement mandates tightening across underground operations, forcing capital reallocation from combustion powertrains to electrified haulage and drilling fleets.
Growth Catalysts
- EPA Tier 4 Final enforcement:Underground operators in the United States face escalating compliance costs for diesel particulate filtration, accelerating battery-electric retrofits of existing load-haul-dump equipment.
- Copper-gold extraction intensity:Hard-rock mines in Chile and Australia are expanding electrified fleet deployments to reduce ventilation energy costs in deep-level operations.
- Lithium-ion energy density gains:Cell chemistry improvements enable single-shift battery swaps replacing multi-shift diesel refueling cycles in narrow-vein extraction.
Market Restraints
- Cobalt supply concentration:Democratic Republic of Congo dominates raw material sourcing for high-nickel cathodes, creating price volatility exposure for battery pack manufacturers.
- Thermal runaway containment:Current battery management systems require redundant cooling architectures that add weight and volume penalties to mobile underground equipment.
- EU F-Gas Regulation friction:Restrictions on fluorinated greenhouse gases complicate thermal management fluid selection for battery cooling circuits in European mining operations.
Strategic Opportunities
- Canadian Arctic development:Remote northern mines in Canada lack grid connectivity, creating demand for modular battery-solar hybrid power stations supporting electrified auxiliary equipment.
- Solid-state chemistry convergence:Sulfide electrolyte research combined with silicon anode architectures promises energy density thresholds enabling all-day underground haulage without battery swapping.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive mining inputs incentivize European operators to source certified low-carbon battery systems for fleet renewals.
Industry Challenges
- High-voltage technician scarcity:Underground maintenance crews lack certification for 600V+ battery pack servicing, forcing mine operators to retrain or contract specialized electrical contractors.
- ISO 19453 compliance timelines:Vibration and thermal cycling certification for off-road battery systems extends product validation cycles by 18-24 months versus conventional powertrain approvals.
- Legacy equipment integration:Retrofit battery systems must interface with 20-year-old machine control architectures designed for hydraulic-diesel interfaces, complicating software harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Machinery Battery Market |
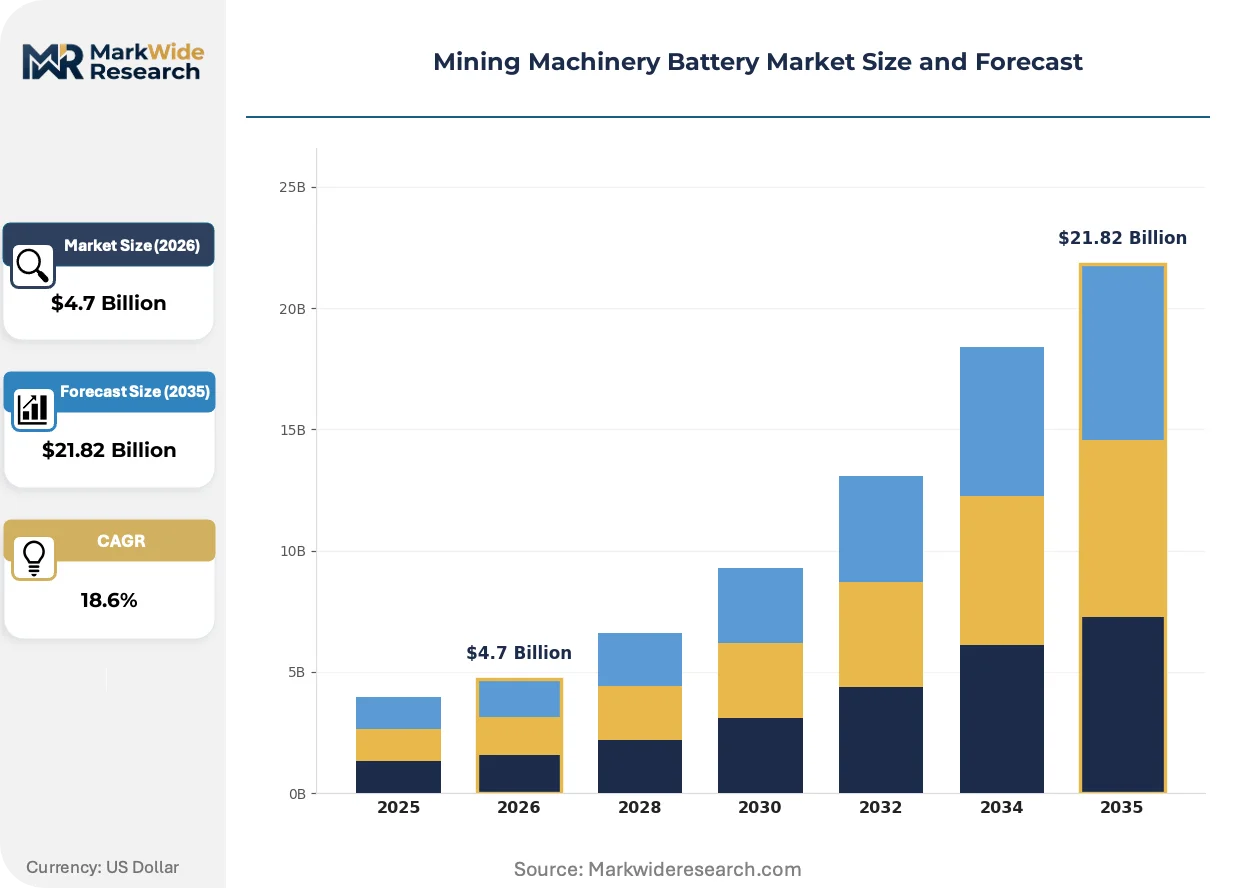
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Sodium-Sulfur Technology: Rechargeable, Non-Rechargeable, Solid-State, Flow Battery End User: Quarries, Underground Mines, Surface Mines, Material Handling Power Rating: Low Power, Medium Power, High Power, Ultra-High Power |
| Companies Covered | Contemporary Amperex Technology Co., Limited, LG Energy Solution, BYD Company Ltd., Caterpillar, Sandvik Mining and Rock Solutions, Epiroc, Samsung SDI, Panasonic Holdings Corporation, Komatsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Machinery Battery Market Shifts & Advancements
Battery chemistry evolution and regulatory stringency are compressing technology adoption cycles across underground mining operations, reshaping how fleets are financed, maintained, and deployed.
Solid-state lithium-metal cells are decomposing the traditional trade-off between energy density and thermal stability in underground haulage applications. Australian hard-rock operators are piloting sulfide-electrolyte prototypes in 50-tonne load-haul-dump units. This chemistry is decomposing the overnight charging infrastructure requirements that constrain current lithium-ion deployments.
The EU Green Deal's zero-emission mandate for non-road mobile machinery is forcing fleet procurement revisions across German and Swedish underground operations. Equipment lessors are restructuring contract terms to accommodate battery residual value uncertainty. Narrow-vein gold mines in Finland are accelerating original equipment purchases to secure delivery slots ahead of 2030 compliance deadlines.
Power-by-the-hour contracting is displacing capital purchase models for battery-electric fleets in Chilean copper operations. Komatsu and Epiroc are unbundling battery assets from machine sales, retaining ownership and charging infrastructure responsibility. This shift concentrates most visibly in Antofagasta and Atacama regions where water scarcity amplifies diesel cooling system operational costs.
Mining Machinery Battery Market Segmentation
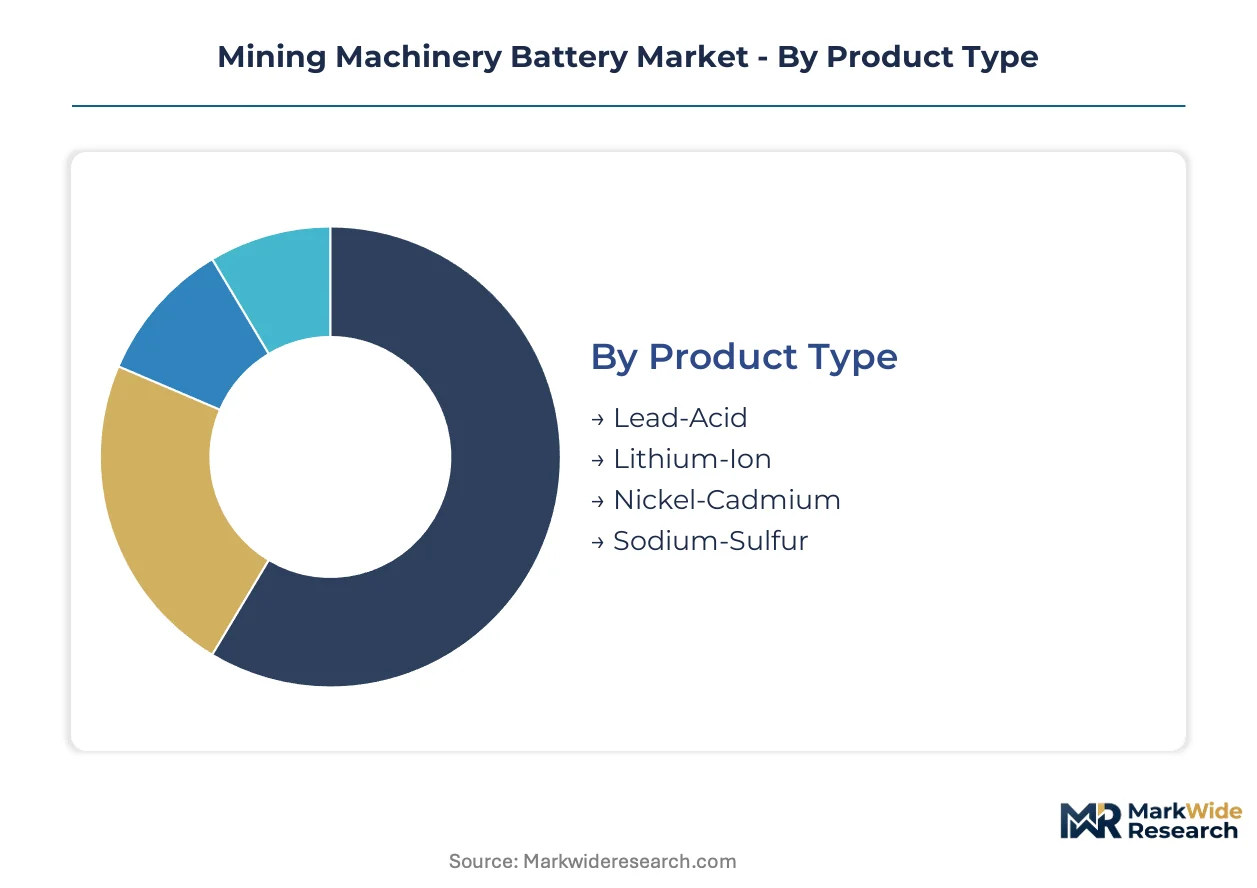
Segmentation in mining machinery batteries reveals how chemistry choices, duty cycles, and operational environments dictate procurement channels. Equipment OEMs, aftermarket distributors, and direct mine site contracts each favor distinct technical specifications.
Product Type:
Channel concentration varies sharply by chemistry: lithium-ion flows predominantly through OEM-integrated supply chains, while lead-acid sustains robust aftermarket distribution serving surface operations.
- Lithium-Ion:High energy density cells utilizing nickel-manganese-cobalt or lithium-iron-phosphate cathodes deliver sustained discharge rates for underground load-haul-dump equipment. Australian hard-rock copper-gold operators are consolidating procurement around this chemistry to reduce ventilation infrastructure costs in deep-level operations.
- Lead-Acid:Flooded and valve-regulated lead-acid designs rely on mature manufacturing infrastructure and established recycling loops. Surface material handling fleets in Chilean open-pit copper operations favor this chemistry where capital constraints and weight tolerance permit proven technology.
- Nickel-Cadmium:Sintered plate construction tolerates extreme temperature swings in Arctic Canadian mine sites where diesel-battery hybrid auxiliary systems require cold-crank reliability.
- Sodium-Sulfur:High-temperature ceramic electrolyte designs suit fixed-site power buffering applications at remote South African platinum operations lacking grid connectivity.
By volume, lead-acid leads. By growth pace, lithium-ion is ahead.
Technology:
Maturity gradients across technology architectures determine margin structures, with rechargeable systems commanding volume and solid-state capturing R&D investment intensity.
- Rechargeable:Lithium-ion and advanced lead-acid systems dominate mobile equipment deployments through established charging infrastructure networks.
- Non-Rechargeable:Primary lithium-thionyl chloride cells power emergency beacon and monitoring devices in confined underground environments where battery replacement cycles extend operational continuity.
- Solid-State:Sulfide and oxide electrolyte architectures promise energy density thresholds enabling single-shift underground haulage without battery swapping. Finnish narrow-vein gold operators are piloting prototypes ahead of EU zero-emission machinery mandates.
- Flow Battery:Vanadium redox systems scale to megawatt-hour capacity for fixed-site auxiliary power at remote Canadian Arctic developments where solar-battery hybrid architectures displace diesel generators.
Rechargeable systems anchor current revenue. Solid-state chemistry claims the steepest expansion trajectory.
End User:
Application-specific duty cycles and regulatory exposure create divergent specification requirements across extraction environments.
- Underground Mines:Diesel particulate regulations from EPA Tier 4 Final and EU Green Deal zero-emission mandates are accelerating battery-electric retrofits. Canadian deep-level nickel operations prioritize thermal runaway containment in confined shaft environments.
- Surface Mines:Open-pit copper and iron ore extraction in Western Australia favors high-capacity lithium-ion packs for electric drive haul trucks operating on established road grades.
- Quarries:Limestone and aggregate operations in Germany balance capital constraints against emerging carbon border adjustment exposure, favoring mid-power rechargeable systems.
- Material Handling:Port and stockyard equipment in Chilean Antofagasta region leverages power-by-the-hour contracting models unbundling battery assets from machine ownership.
Underground mines concentrate technology investment. Surface mines generate the largest unit volumes.
Power Rating:
Power tier selection correlates directly with equipment tonnage class and ventilation energy economics in deep operations.
- High Power:300-600 kWh systems propel 50-tonne load-haul-dump units in Australian hard-rock underground copper mines where diesel displacement yields ventilation cost reductions.
- Ultra-High Power:Megawatt-scale battery packs support 240-tonne surface haul truck electrification pilots in Chilean Atacama operations.
- Medium Power:100-200 kWh configurations serve narrow-vein drilling and bolting equipment in Finnish and Swedish underground gold-zinc mines.
- Low Power:Sub-50 kWh systems power personnel carriers and auxiliary lighting in Canadian potash operations.
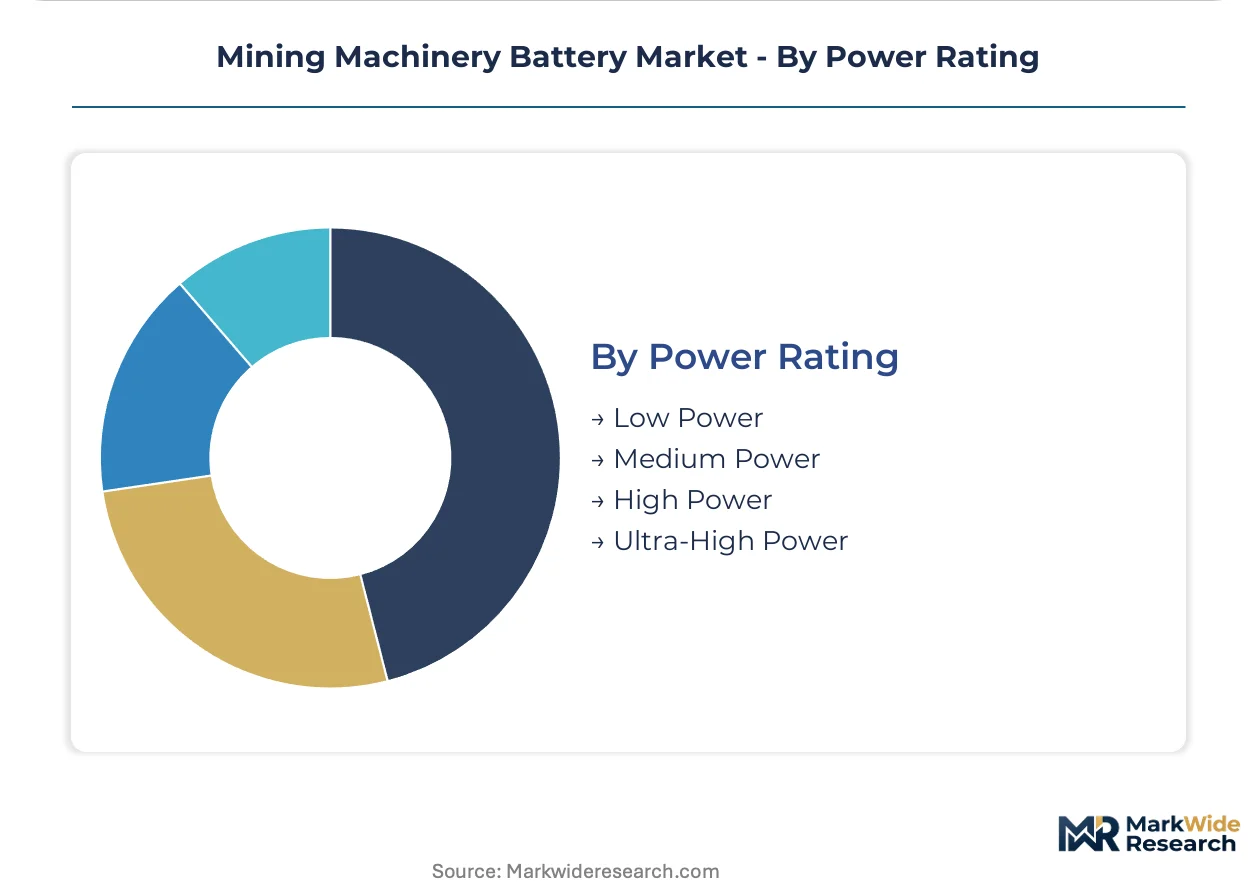
High power rating captures the dominant revenue share. Ultra-high power is climbing the fastest as surface haulage electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara heavy haul rail network underwrites Western Australia's dominance in surface mining electrification, while Chile's Escondida copper corridor and Canada's Arctic supply roads anchor underground fleet conversion demand across three continents.
Australia
Hard-rock copper-gold operations in Western Australia and Queensland are consolidating procurement around lithium-ion chemistry to slash ventilation energy costs in deep-level shafts. The Australian Renewable Energy Agency funds mine-site solar-battery hybrid pilots. Perth-based engineering clusters coordinate fleet electrification programs for Pilbara iron ore majors transitioning haul truck powertrains.
Chile
Antofagasta and Atacama region copper miners face acute water scarcity that amplifies diesel cooling system operational penalties. The Ministry of Mining's National Mining Policy 2050 mandates progressive fleet decarbonization timelines. Santiago-headquartered equipment lessors are restructuring power-by-the-hour contracts to unbundle battery assets from machine ownership.
Canada
Arctic and sub-Arctic nickel and diamond operations lack grid connectivity, driving demand for modular battery-solar hybrid auxiliary power stations. Natural Resources Canada's Critical Minerals Strategy accelerates electrification funding for remote northern developments. Sudbury and Val-d'Or mining clusters pilot solid-state prototypes in narrow-vein extraction environments.
United States
Underground metal mines in Arizona and Nevada confront escalating EPA Tier 4 Final compliance costs for diesel particulate filtration. The Inflation Reduction Act's clean energy tax credits subsidize battery-electric retrofits of existing load-haul-dump fleets. Denver and Salt Lake City equipment distributors anchor regional electrification service networks.
Sweden
Narrow-vein gold-zinc mines in Lapland and Bergslagen regions accelerate original equipment purchases ahead of EU Green Deal zero-emission machinery mandates. The Swedish Energy Agency funds battery thermal management research for Arctic operating conditions. Kiruna and Skellefteå mining technology clusters prototype sulfide-electrolyte solid-state cells for single-shift haulage.
Mining Machinery Battery Market Competitive Landscape
Listed leaders compete with private specialists across capital structure and customer integration depth. The market exhibits tiered concentration with integrated mining equipment OEMs anchoring premium fleet contracts while independent cell manufacturers supply aftermarket replacement cycles. Three archetypes dominate: diversified industrial conglomerates with captive battery engineering, pure-play lithium-ion specialists serving multiple end-markets, and mining equipment OEMs with electrification divisions. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure cathode material offtake and charging infrastructure deployment rights.
Within the diversified industrial tier, Caterpillar and Komatsu occupy positions bridging integrated powertrain engineering with large-scale mine site service networks. Contemporary Amperex Technology Co., Limited and LG Energy Solution exemplify the pure-play cell manufacturer archetype, supplying standardized lithium-ion packs across multiple heavy-duty applications. Epiroc represents the mining-specialist OEM category, anchoring narrow-vein electrification with purpose-built battery-electric drilling and loading architectures.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited |
| LG Energy Solution |
| BYD Company Ltd. |
| Caterpillar |
| Sandvik Mining and Rock Solutions |
| Epiroc |
| Samsung SDI |
| Panasonic Holdings Corporation |
| Komatsu |
| Others |
Supply & Pricing Matrix
Power-by-the-hour contracts in Chilean copper operations lock in multi-year battery asset access while insulating mine operators from cathode material price swings. This contracting structure concentrates procurement leverage with equipment lessors who retain residual value exposure across the fleet replacement cycle.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated lithium-ion packs from aftermarket lead-acid replacements and refurbished modular systems. Price differentiation hinges on ISO 19453 thermal certification grade and bundled charging infrastructure coverage. Cost compression in standard-tier configurations is intensifying because nickel-cobalt cathode volatility feeds through to pack pricing. Surface material handling fleets in Chilean open-pit operations exhibit highest price sensitivity due to capital constraints, while Australian deep-level underground operators prioritize premium-tier thermal containment despite cost premiums.
Supply Chain Analysis
Container availability constraints on the Shanghai-Antwerp and Busan-Long Beach trade lanes inflate inbound logistics costs for cathode active material shipments. Cell manufacturing concentrates in China, South Korea, and Japan, with pack assembly gravitating toward Australian and Canadian mining clusters. The supply chain draws from cobalt concentrates originating in the Democratic Republic of Congo, lithium carbonate from Chilean Atacama salares, and synthetic graphite from Chinese processing facilities. Single-source vulnerability around sulfide electrolyte precursors for solid-state prototypes constitutes the dominant structural risk. Distribution runs through OEM captive channels for lithium-ion systems and independent aftermarket distributors for lead-acid replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mining machinery battery market sits at an inflection where EPA Tier 4 Final enforcement and EU Green Deal zero-emission mandates are compressing technology adoption cycles from decades to single-digit years.
For Market Incumbents: Fortify cathode material supply security through backward integration into Australian lithium spodumene and Chilean cobalt hydroxide processing. Expand thermal management certification capacity ahead of ISO 19453 compliance deadlines to capture premium-tier pricing. Battery management system software standardization represents the critical lever for locking in fleet retrofit contracts against emerging solid-state challengers.
For New Entrants and Emerging Players: Aftermarket service gaps in high-voltage technician certification and 600V+ pack maintenance training offer white-space entry points. Canadian Arctic operations lacking grid connectivity present the most penetrable geography for modular battery-solar hybrid auxiliary power stations. A go-to-market angle anchored on power-as-a-service contracting can bypass incumbent OEM channel control.
For Investors and Strategic Acquirers: The market sits at a scaling phase that favors solid-state chemistry specialists with sulfide electrolyte pilot production. Long-term viability over the coming decade rests on cathode material offtake security and charging infrastructure deployment rights. Watch for EU carbon border adjustment implementation as the signal indicating accelerated fleet replacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Backward Integration | Captive lithium-cobalt supply from Chilean and Australian sources insulates margin pressure from commodity volatility. |
| Solid-State Pilot Production Scale-Up | Sulfide electrolyte manufacturing readiness positions suppliers ahead of EU zero-emission machinery mandates. |
| High-Voltage Technician Certification Programs | Training infrastructure addresses maintenance crew scarcity constraining underground fleet deployments. |
| Power-by-the-Hour Contract Structuring | Asset unbundling shifts residual value risk from mine operators to equipment lessors in Chilean copper operations. |
| ISO 19453 Thermal Compliance Investment | Vibration and cycling certification accelerates product validation for premium-tier underground equipment procurement. |
Research Methodology
Cross-validation between mine site engineering interviews and OEM product planning disclosures anchors the qualitative findings. Primary discussions with underground maintenance directors, fleet procurement managers at Australian hard-rock operations, battery pack engineering leads, and equipment lessor contract specialists combined with secondary analysis of EPA enforcement bulletins, EU Green Deal implementation timelines, Chilean Ministry of Mining policy documents, and Australian Renewable Energy Agency funding disclosures. Bottom-up cell chemistry demand modeling and top-down fleet electrification spend estimates triangulate volume figures.
Sensitivity analysis around cobalt price trajectories and solid-state chemistry convergence timelines tests forecast robustness. The analytical framework segments by chemistry type, power rating tier, and end-use environment across the projection horizon, with additional granularity on ventilation energy economics in deep-level operations. CAGRs derive from equipment replacement cycle compression and regulatory mandate phase-in schedules. Modeled inputs include copper-gold extraction intensity in Western Australia and nickel operation electrification funding under Canada's Critical Minerals Strategy.
Forecasts assume regulatory continuity in EPA Tier 4 Final enforcement and EU Green Deal machinery mandates; material policy shifts would require re-modeling. Forecasts reflect assumptions about lithium-ion energy density improvement trajectories and solid-state prototype commercialization timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mining Tester Market
Mining Equipment
Stone Crushing Equipment Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
Underground Mining Market
Mining Equipment
Global Dozers Market
Mining Equipment
Rock Duster Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Kazakhstan Mining Market
Mining Equipment
Mechanical Mine Clearance System Market
Mining Equipment
Smart Mining Market
Mining Equipment
DTH Drill Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Surface Mining Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Mining Remanufacturing Components Market