

Level 4 Autonomous Highway Trucking Market Size, Share, and Industry Trends Forecast 2026-2036
Level 4 Autonomous Highway Trucking Market Insights
Federal Motor Carrier Safety Administration rulemaking is recalibrating insurance and operator certification requirements for driverless Class 8 vehicles. Aurora Innovation leverages a vertically integrated hardware-software stack to sustain development velocity across multiple freight corridors. Torc Robotics anchors its roadmap in rigorous safety validation protocols that differentiate its approach from perception-heavy competitors. Waymo dominates structured highway environments where mapped operational design domains reduce edge-case exposure.
Level 4 autonomous highway trucking denotes commercial freight vehicles capable of sustained driverless operation within predefined operational design domains, typically relying on fused LiDAR-radar-camera perception stacks with redundant braking and steering actuators to achieve functional safety targets exceeding human baseline performance. The primary purpose is to reduce per-mile labor costs while extending permissible daily driving hours through automated operation. Tractor-trailers command the dominant share of near-term deployment capital, as unit economics improve most dramatically on long-haul routes where driver hours-of-service constraints currently limit asset utilization. LiDAR-based perception systems occupy the premium tier of autonomy technology spending, though camera-first architectures with supplemental radar are gaining ground among cost-sensitive fleet operators targeting regional distribution lanes.
The National Highway Traffic Safety Administration coordinates crashworthiness standards with FMCSA duty-of-care rules, while state-level departments of transportation in Arizona, Texas, and California issue permits that shape where commercial pilots may legally operate without safety drivers. ISO 26262 functional safety certification and SAE J3016 automation level definitions create baseline technical barriers that filter which system integrators may contract with risk-averse logistics carriers. Stakeholders must monitor how FMCSA resolves the driverless vehicle inspection and roadside enforcement gap, as this determination will either accelerate or stall fleet procurement timelines regardless of technical readiness.
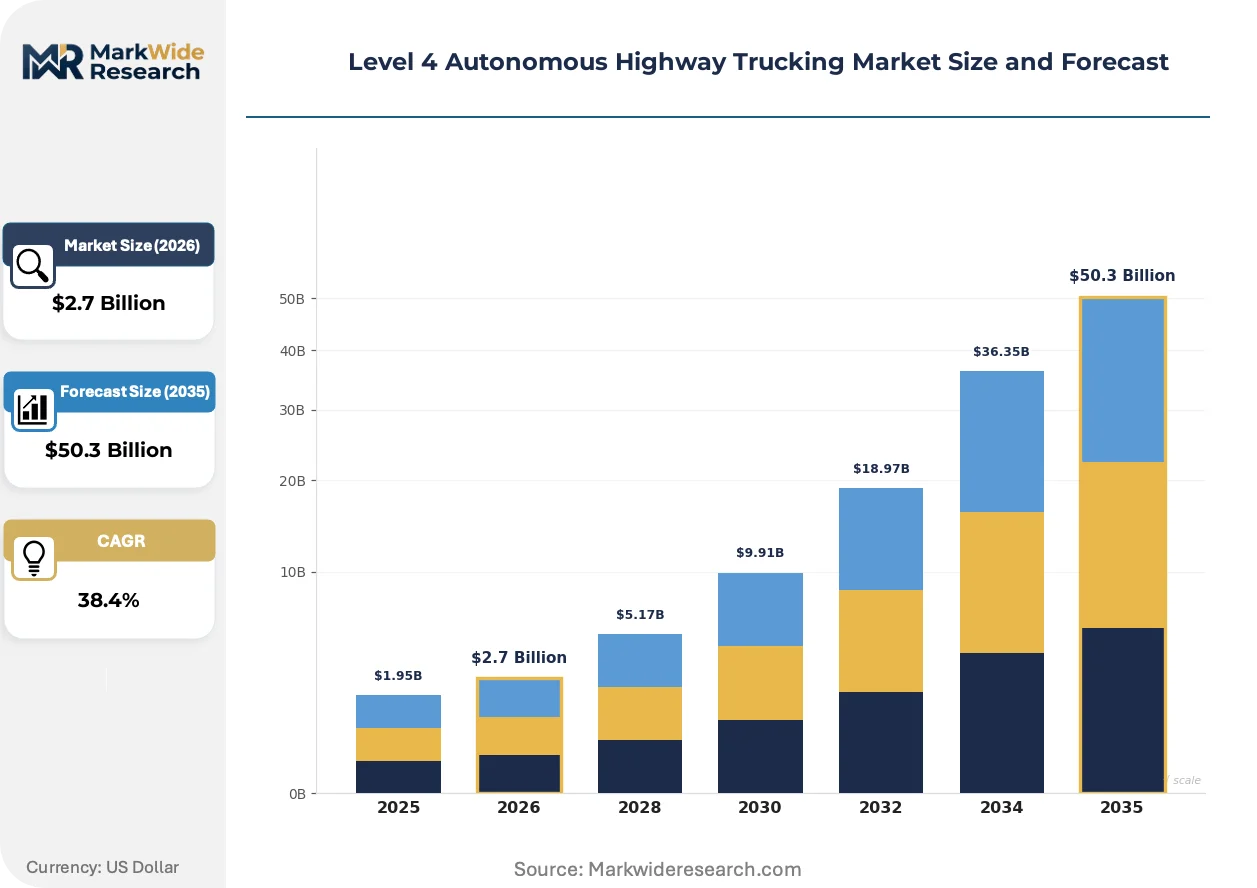
Market Dynamics
Federal Motor Carrier Safety Administration rulemaking on driverless vehicle inspection protocols is compressing fleet procurement timelines while recalibrating liability frameworks for commercial operators.
Growth Catalysts
- Hours-of-service automation:Level 4 systems bypass driver fatigue limits on interstate corridors, extending daily tractor-trailer utilization beyond human-regulated caps.
- FMCSA insurance recalibration:Evolving federal guidance on operator certification for driverless Class 8 vehicles reduces underwriting uncertainty for early adopters.
- LiDAR cost curves:Solid-state sensor manufacturing scale is collapsing per-unit perception stack costs for highway-speed redundancy requirements.
Market Restraints
- Redundant actuator supply concentration:Dual-circuit braking and steering hardware for 80,000-pound vehicles depends on a narrow tier of automotive Tier 1 suppliers.
- Roadside enforcement gaps:Absence of standardized driverless inspection protocols creates operational friction with state highway patrol agencies.
- Camera-first substitution pressure:Cost-sensitive regional fleets are piloting vision-dominant architectures that threaten LiDAR-based system margins.
Strategic Opportunities
- Middle-mile freight corridors:Distribution center-to-hub routes in Texas and Arizona offer lower-complexity operational design domains than long-haul interstate spans.
- ISO 26262 certification services:Functional safety validation consulting represents a high-margin adjacent as integrators seek carrier contracts.
- Teleoperations fallback networks:Remote human intervention infrastructure for edge-case handling enables geographic expansion beyond mapped highway corridors.
Industry Challenges
- Functional safety engineering scarcity:Talent pools for ASIL-D systems validation remain thin relative to program launch timelines.
- Legacy fleet integration complexity:Retrofit compatibility with existing trailer brake systems and fifth-wheel coupling mechanisms extends deployment cycles.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Level 4 Autonomous Highway Trucking Market Trends and Innovations
Perception architecture debates, federal rulemaking velocity, and procurement model experimentation are compressing competitive differentiation windows across the autonomous freight sector.
Sensor fusion stacks are absorbing validation burden from fleet operators by pre-certifying integrated hardware-software configurations against FMCSA safety benchmarks. Large trucking carriers with dedicated risk management functions are adopting these validated bundles faster than asset-light brokers. This consolidation of technical liability is absorbing smaller integrators who lack capital for end-to-end system testing.
NHTSA coordination with FMCSA on crashworthiness standards for driverless commercial vehicles is harmonizing previously fragmented federal oversight. The unified framework reduces compliance duplication for multi-state operators. Long-haul freight carriers with interstate authority are restructuring internal regulatory affairs teams to exploit this simplification.
Freight procurement is unbundling autonomous capability from traditional rate negotiations as shippers introduce technology-readiness scorecards into carrier selection. Asset-based carriers with live pilot programs are capturing contracted lane volume from broker-dependent competitors. This behavioral shift is most pronounced in Texas-Arizona-California corridor freight where regulatory permits enable demonstrated service reliability.
Level 4 Autonomous Highway Trucking Market Segmentation
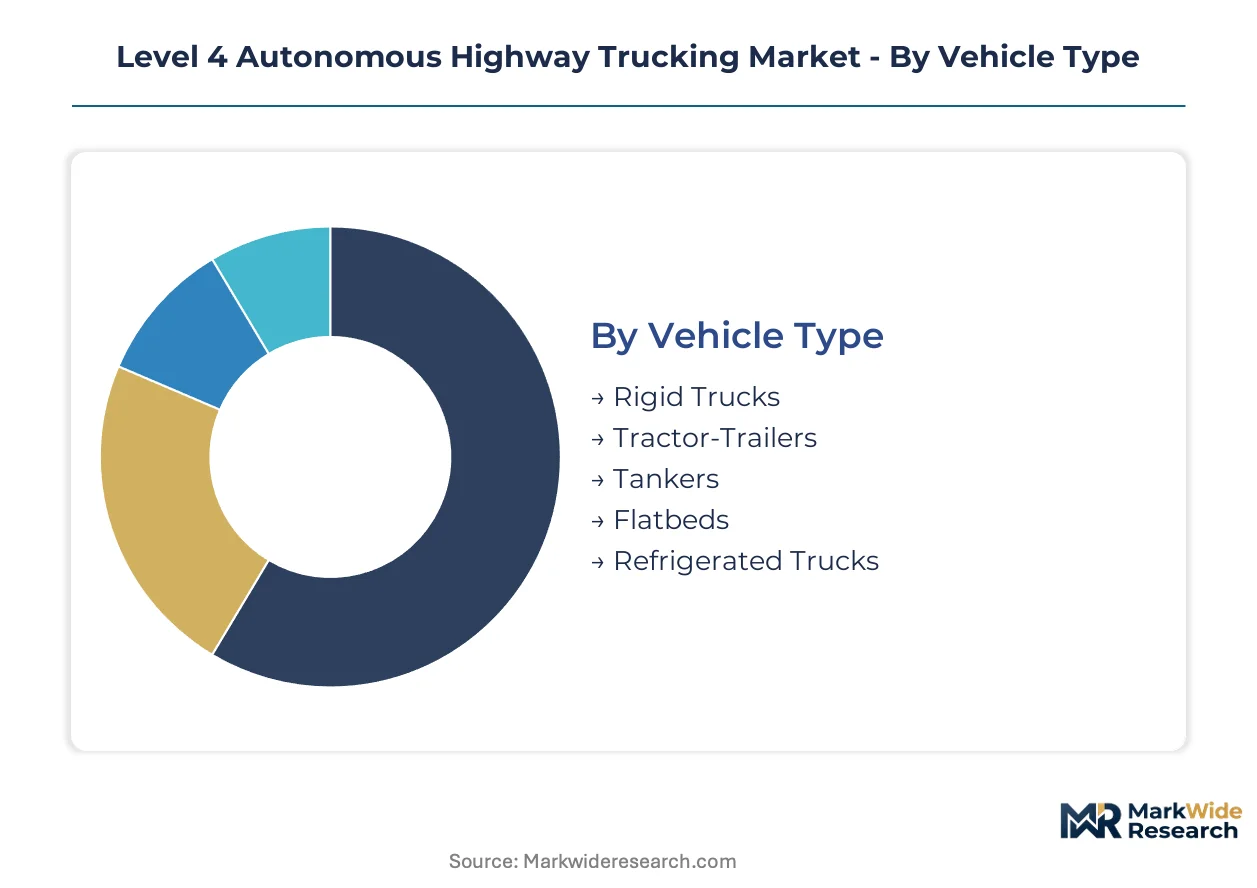
Segmentation in Level 4 autonomous highway trucking reveals how capital allocation and regulatory exposure vary across vehicle configurations and operational models. Fleet operators prioritize segments where automation delivers measurable hours-of-service relief against fixed hardware costs.
Vehicle Type:
Standalone autonomous platforms dominate long-haul deployment, while embedded retrofit systems serve regional operators seeking incremental automation without full fleet replacement.
- Tractor-Trailers:Class 8 tractors with fifth-wheel coupling dominate interstate corridor pilots, where 80,000-pound gross vehicle weight ratings justify redundant braking and steering actuators. Demand concentrates in Texas and Arizona freight lanes where FMCSA permits enable extended driverless testing.
- Rigid Trucks:Single-chassis configurations with integrated cargo bodies serve regional distribution networks where maneuvering complexity exceeds tractor-trailer suitability. California's Central Valley agricultural corridors show early procurement interest for refrigerated rigid variants.
- Refrigerated Trucks:Temperature-controlled autonomous units address pharmaceutical and perishable supply chains requiring uninterrupted cold-chain integrity.
- Flatbeds:Open-deck configurations present unique load-securing challenges that complicate automated pre-trip inspection protocols.
- Tankers:Liquid and gas-hauling trailers carry heightened hazardous materials regulatory burdens that delay autonomous certification timelines.
Volume placements concentrate in Tractor-Trailers; the faster expansion belongs to Refrigerated Trucks.
Autonomy Technology:
Cost tier stratification separates premium perception stacks from emerging camera-dominant architectures targeting price-sensitive regional operators.
- LiDAR:Solid-state laser scanning arrays provide centimeter-range precision at highway speeds, enabling 300-meter object detection in adverse weather. Long-haul freight corridors in Texas and Arizona specify LiDAR redundancy for commercial permit eligibility.
- Camera-Based:Vision-dominant systems leveraging neural network inference reduce hardware costs but require higher computational overhead and precise lighting conditions. Regional distribution pilots in California's Inland Empire test camera-first architectures for cost-constrained middle-mile routes.
- Radar:Frequency-modulated continuous-wave sensors penetrate precipitation and fog where optical systems degrade.
- AI Algorithms:Deep learning perception and path-planning software layers abstract sensor inputs into drivable trajectories.
- V2X Communication:Vehicle-to-infrastructure and vehicle-to-vehicle protocols enable cooperative awareness beyond line-of-sight sensing.
- Ultrasonic Sensors:Short-range proximity detection supports low-speed maneuvering in terminal and depot environments.
Procurement volume clusters in LiDAR-based configurations; camera-dominant architectures are climbing the fastest as solid-state manufacturing scales.
Use Case:
Application maturity varies by operational design domain complexity, with structured highway environments preceding urban and terminal operations.
- Long-Haul Freight:Interstate corridor operation between distant distribution centers maximizes hours-of-service automation value, with 500-plus-mile segments justifying dedicated autonomous assets. The Texas-Arizona-California triangle hosts the majority of permitted commercial pilots.
- Regional Distribution:Hub-to-spoke routes under 250 miles balance automation benefits against lower utilization rates and more complex terminal ingress/egress.
- Container Transport:Port drayage and intermodal terminal operations present repetitive route structures favorable to mapped operational design domains.
- Last-Mile Delivery:Urban density and unpredictable pedestrian interaction push autonomous timelines beyond current Level 4 capabilities.
- Bulk Cargo Shipping:Mining and construction material hauling in controlled-access environments offers isolated deployment opportunities.
Capital deployment concentrates in Long-Haul Freight; Regional Distribution shows the steepest expansion trajectory as middle-mile automation proves economically viable.
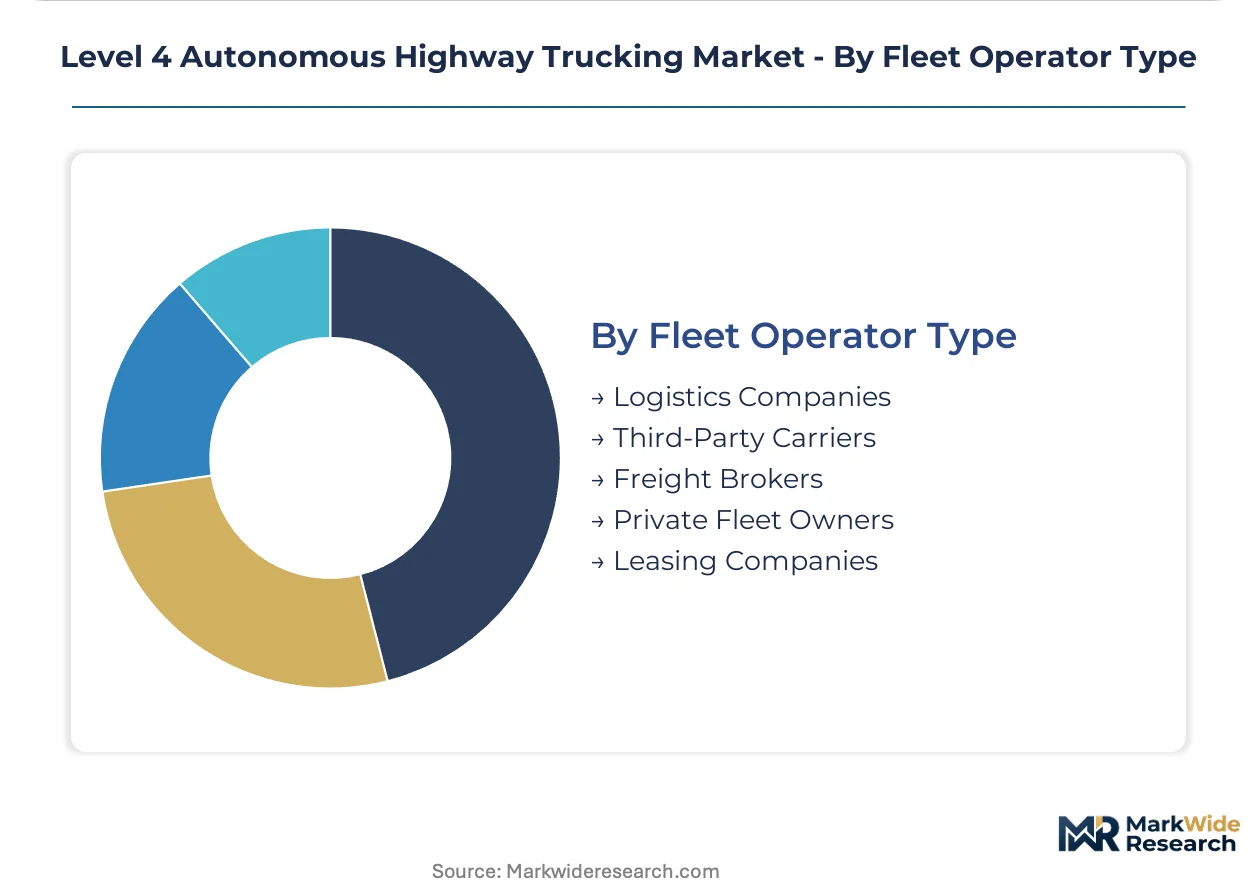
Fleet Operator Type:
Customer type determines procurement risk tolerance, with asset-heavy operators absorbing technology validation costs ahead of asset-light intermediaries.
- Logistics Companies:Integrated carriers with dedicated risk management functions and interstate operating authority structure autonomous procurement as competitive differentiation. Large asset-based operators in the Southwest corridor capture contracted lane volume through demonstrated pilot reliability.
- Private Fleet Owners:Captive trucking operations for retail and manufacturing shippers prioritize total cost of ownership reduction over rate arbitrage, accepting longer payback periods for automation capital.
- Third-Party Carriers:Contract trucking providers face shipper technology-readiness scorecards that increasingly weight autonomous capability in lane awards.
- Freight Brokers:Non-asset intermediaries lack direct procurement leverage but influence carrier selection criteria toward validated autonomous operators.
- Leasing Companies:Equipment finance providers structure residual value models around projected autonomous technology obsolescence curves.
Early adoption concentrates among Logistics Companies; Private Fleet Owners are gaining share fastest as shipper ESG mandates accelerate automation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States freight corridors concentrate autonomous trucking pilots where regulatory sandboxes permit extended driverless testing. Fleet operators prioritize interstate spans in southwestern states where hours-of-service automation delivers maximum asset utilization gains.
United States
Texas, Arizona, and California host the majority of permitted commercial pilots on interstate corridors. The Federal Motor Carrier Safety Administration recalibrates insurance frameworks for driverless Class 8 vehicles. Dallas-Fort Worth and Phoenix freight clusters anchor deployment capital as logistics carriers validate operational design domains.
Canada
Alberta and Ontario provinces test autonomous freight on controlled-access highways connecting distribution hubs. Transport Canada coordinates vehicle safety standards with provincial permitting authorities. The Calgary-Edmonton corridor hosts winter-weather validation programs for perception stack reliability.
Germany
Baden-Württemberg and Bavaria automotive clusters advance autonomous trucking through OEM-integrated development. The KBA certifies vehicle systems against UN ECE regulations for automated lane-keeping. Stuttgart and Munich engineering centers validate redundant actuator architectures for 40-tonne gross combinations.
China
Beijing-Tianjin-Hebei and Yangtze River Delta logistics corridors pilot autonomous freight under MIIT-connected vehicle mandates. GB standards govern automated driving system performance requirements. Shanghai port automation clusters test container drayage applications with vehicle-to-infrastructure coordination.
Sweden
Scandinavian freight operators test autonomous trucks on E4 motorway segments under Swedish Transport Agency permits. The country's national road administration coordinates with haulage associations on roadside enforcement protocols. Gothenburg automotive suppliers validate sensor fusion stacks for low-light winter conditions.
Level 4 Autonomous Highway Trucking Market Competitive Landscape
United States producers anchor one tier; European and Asian specialists hold differentiated positions through OEM partnerships and port automation focus. The vendor base stratifies across vertically integrated stack developers, Tier 1 automotive suppliers, and software-centric perception specialists. Three archetypes dominate: full-stack integrators controlling hardware-software interfaces, truck manufacturers embedding autonomy into new vehicle platforms, and AI-native startups targeting specific operational design domains. Competitive moves center on safety validation certification against ISO 26262 benchmarks and corridor-specific permit acquisition.
Within the full-stack integrator tier, Aurora Innovation and Kodiak Robotics represent North American development velocity focused on southwestern freight corridors. Torc Robotics anchors European-rooted safety validation rigor. Waymo exemplifies structured environment dominance through mapped operational design domains. These three occupy positions across the perception architecture spectrum from LiDAR-redundant to camera-augmented configurations.
| Leading Market Players |
|---|
| Aurora Innovation |
| Kodiak Robotics |
| Torc Robotics |
| Volvo Autonomous Solutions |
| PlusAI |
| Waabi |
| Waymo |
| Einride |
| Embark Trucks |
| Others |
Pricing and Supply Chain Analysis
Solid-state LiDAR sensor price indices cascading from Taiwan and South Korea contract manufacturers compress hardware stack costs, translating into tiered procurement thresholds that separate long-haul fleet operators from regional distribution buyers.
Pricing Analysis
Volume procurement concentrates among Southwest corridor logistics carriers with interstate authority, while margin capture concentrates with ISO 26262-certified integrators bundling perception hardware with validation services. Three-tier pricing structure across premium, standard, and economy levels separates redundant LiDAR-radar configurations from camera-augmented alternatives, with certification grade and after-sales teleoperations support as primary differentiation drivers. Cost compression in camera-first architectures is intensifying because solid-state manufacturing scales, pressuring LiDAR-based system margins. Asset-light freight brokers exhibit highest price sensitivity; integrated carriers with dedicated risk management functions demonstrate lowest sensitivity due to total cost of ownership framing.
Supply Chain Analysis
Dual-sourcing requirements from FMCSA-permitted fleet operators mandate qualified secondary suppliers for redundant braking actuators, forcing Tier 1 automotive suppliers in Germany, Japan, and Mexico to maintain parallel production lines. Raw material dependencies span rare-earth magnet arrays for LiDAR motors, high-purity silicon for solid-state photonic chips, and automotive-grade steel for chassis-integrated sensor mounts. Single-source vulnerability in 80,000-pound vehicle redundant steering hardware creates procurement bottlenecks during permit expansion phases. Distribution runs through direct OEM integration contracts for new autonomous platforms, with aftermarket retrofit channels serving regional operator price constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over safety validation certification and corridor-specific permit acquisition determines pricing power and carrier contract access.
For Market Incumbents: Anchor defensive positioning through captive production of ASIL-D validated perception stacks and exclusive partnerships with Arizona and Texas permitting authorities. Camera-first substitution pressure from cost-sensitive regional fleets threatens LiDAR-redundant system margins. Backward integration into solid-state LiDAR manufacturing secures component cost visibility against Taiwan and South Korea supply concentration. For New Entrants and Emerging Players: Fleet operator technology-readiness scorecards present the most penetrable channel partner type for ISO 26262 certification services and teleoperations fallback infrastructure. Middle-mile freight corridors in Texas and Arizona offer lower-complexity operational design domains than long-haul interstate spans. White-space targets include refrigerated autonomous units for pharmaceutical supply chains and container drayage pilots at Shanghai and Los Angeles port clusters. For Investors and Strategic Acquirers: Distressed-cycle entries favor functional safety engineering boutiques with ASIL-D validation track records in Germany and Sweden, where talent scarcity outstrips program launch timelines. Long-term viability hinges on integrators achieving multi-corridor permit portfolios rather than single-state concentration. The signal to watch is FMCSA resolution of driverless vehicle inspection protocols, which would either accelerate or stall fleet procurement timelines regardless of technical readiness.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 Certification Investment | Functional safety validation unlocks carrier contracts with risk-averse logistics operators in Southwest corridors. |
| Corridor-Specific Permit Acquisition | Texas and Arizona FMCSA permits enable demonstrated service reliability for contracted lane volume capture. |
| Teleoperations Infrastructure Buildout | Remote human intervention networks extend geographic expansion beyond mapped highway operational design domains. |
| Sensor Fusion Stack Integration | Pre-certified hardware-software bundles absorb technical liability from fleet operators accelerating procurement decisions. |
| Retrofit Compatibility Development | Legacy trailer brake system integration reduces deployment cycles for regional distribution operator adoption. |
Research Methodology
Multi-period observation of FMCSA permit issuance rates, LiDAR sensor contract pricing, and carrier pilot program announcements anchored the trend analysis, supplemented by interviews with autonomous system engineering directors, fleet risk management officers, Tier 1 automotive supplier procurement leads, and state DOT permitting administrators. Secondary validation drew from NHTSA crashworthiness filings, FMCSA rulemaking dockets, SEC autonomous vehicle developer disclosures, and vehicle production databases. Bottom-up segment sizing triangulated against top-down freight corridor volume estimates.
Input-output matrices mapped sensor cost curves and regulatory permit velocity against fleet procurement timelines across vehicle configuration, autonomy technology, use case, and operator type segmentation dimensions. CAGRs derived from fitted adoption curves incorporating hours-of-service automation value capture and insurance framework recalibration assumptions. Industry-specific forecast inputs included solid-state LiDAR manufacturing scale projections and FMCSA driverless inspection protocol resolution scenarios.
Caveats apply where FMCSA rulemaking delays, redundant actuator supply disruptions, or camera-first technology substitution could materially shift the outlook. Deviation in federal liability framework resolution would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.