
 Wire Protection and Routing Component Systems for Vehicles Market | 2026-2036
Wire Protection and Routing Component Systems for Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Protection and Routing Component Systems for Vehicles Market Insights
The EU Green Deal's embedded carbon thresholds for automotive supply chains is realigning sourcing priorities across wire protection procurement. LEONI leverages its European manufacturing footprint to meet tightened lifecycle requirements for conduit and loom assemblies. Yazaki anchors its position through backward integration into resin compounding for high-temperature routing channels. Sumitomo Electric Industries competes on scale, sustaining volume leadership across Japanese and Southeast Asian OEM programs.
Wire protection and routing component systems for vehicles encompass conduits, grommets, cable ties, looms, clips, and sleeves engineered to shield electrical conductors from abrasion, thermal degradation, and fluid ingress across operating temperatures from minus 40 to 150 degrees Celsius. These assemblies prevent short circuits and electromagnetic interference while organizing harness topology within confined engine bays and cabin architectures. Conduits and loom assemblies command the deepest margin pools due to their material complexity and custom extrusion requirements. Electric transport units represent the fastest-growing application dimension, driven by high-voltage cable routing needs at 400 to 800 volts. Polyamide and thermoplastic elastomer materials are displacing commodity PVC in thermal-critical zones near battery packs and inverters.
The EPA's vehicle emissions standards and the EU F-Gas Regulation shape material selection by restricting halogenated compounds and mandating recyclability documentation across Tier-1 supply tiers. China's MIIT enforces GB standards for high-voltage harness shielding that dictate metallic braid specifications and connector sealing grades. Stakeholders must monitor regulatory divergence between North American and European material compliance frameworks while calibrating regional production footprints to avoid tariff exposure and certification lag.
Market Dynamics
High-voltage platform electrification is fragmenting legacy harness architectures as OEMs redesign routing topologies around 400-800 volt battery systems and thermal management requirements.
Growth Catalysts
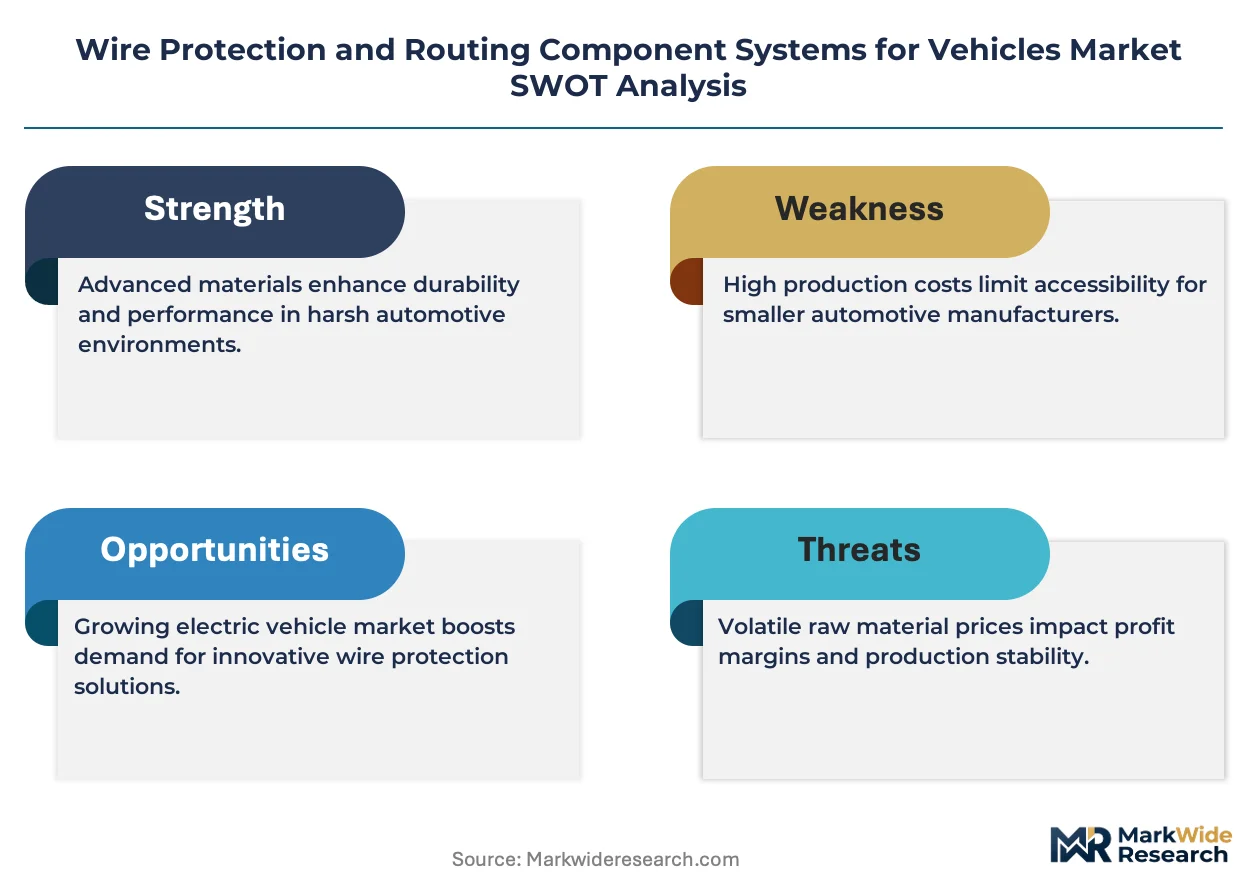
- EPA Tailpipe Standards:US emissions rules compel OEMs to electrify powertrains, multiplying high-voltage cable protection needs across battery electric and hybrid platforms.
- Polyamide Material Advances:Engineered thermoplastics withstand 150°C sustained exposure near inverters, displacing PVC in thermal-critical routing zones.
- China:MIIT-enforced GB standards for high-voltage harness shielding mandate metallic braid specifications that expand addressable component demand.
Market Restraints
- Resin Input Volatility:Polyamide and thermoplastic elastomer feedstock prices fluctuate with crude oil and caprolactam supply, compressing margin predictability for extrusion-dependent conduit manufacturers.
- Supply Concentration Risk:Advanced high-temperature resin compounding capacity clusters in Germany and Japan, creating geographic single-source vulnerability for North American harness assemblers.
- EU F-Gas Regulatory Friction:Restrictions on halogenated compounds in automotive applications force reformulation cycles that extend qualification timelines by 12-18 months.
Strategic Opportunities
- India:PLI scheme incentives for electric vehicle manufacturing are drawing harness protection procurement volumes that remain underpenetrated by specialized conduit suppliers.
- Wireless Power Transfer Integration:Inductive charging pad installations create demand for shielded routing systems that bridge underbody power electronics to battery management units.
- EU Green Deal Embedded Carbon Thresholds:Lifecycle documentation requirements favor suppliers with European manufacturing footprints and recycled content capabilities.
Industry Challenges
- High-Voltage Safety Certification:IEC 60664 and OEM-specific 800-volt isolation testing protocols require specialized test equipment and engineering talent that remains scarce outside Tier-1 supply bases.
- Legacy Harness Integration:12-volt and 48-volt architectures must coexist with new high-voltage systems, multiplying connector sealing and electromagnetic compatibility validation complexity.
- Tooling Capex Intensity:Custom extrusion dies for multi-lumen conduits and overmolded grommets demand six-figure capital commitments per vehicle platform program.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Protection and Routing Component Systems for Vehicles Market |
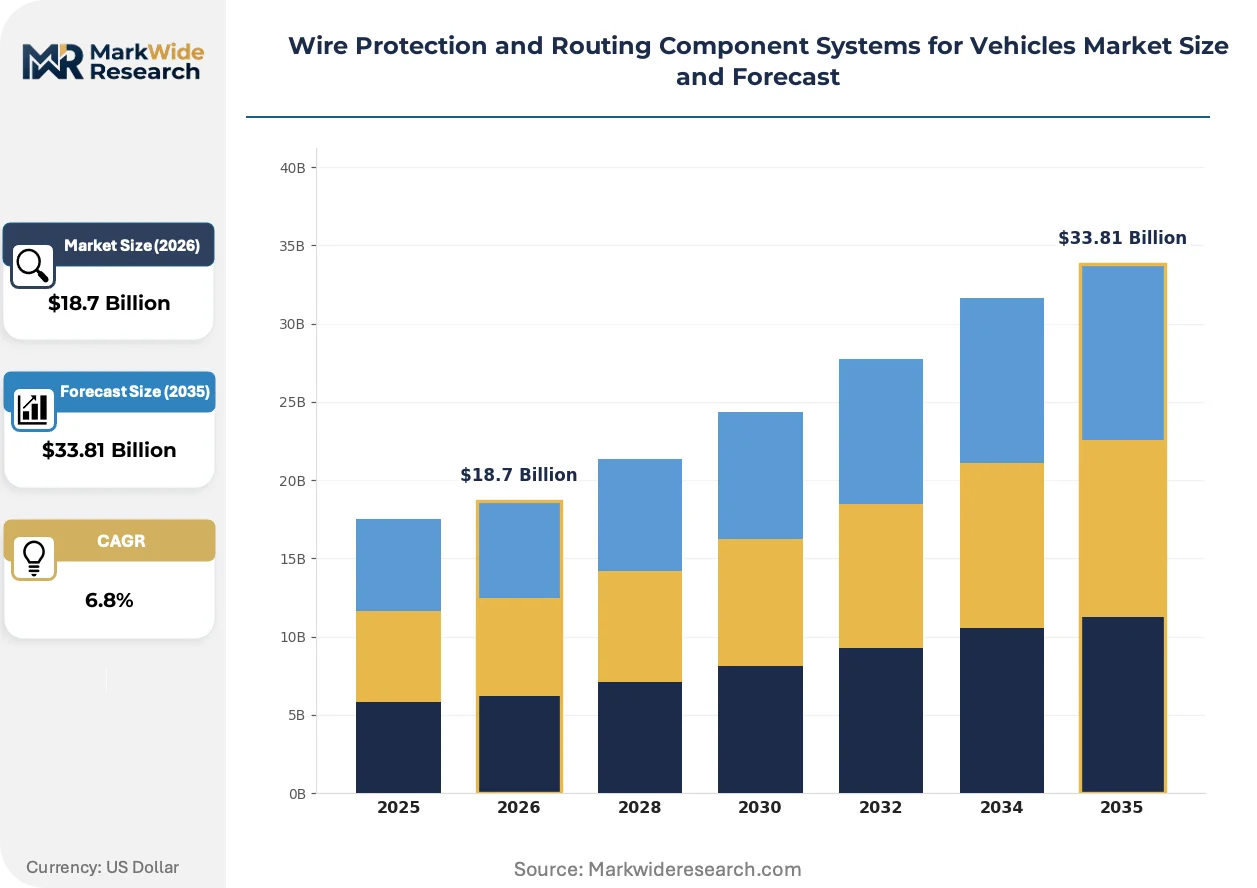
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Conduits, Grommets, Cable Ties, Looms, Clips, Sleeves Material: Polyethylene, Polyvinyl Chloride, Nylon, Thermoplastic Elastomers, Rubber, Metal Application: Passenger Cars, Commercial Trucks, Two-Wheelers, Off-road Vehicles, Specialty Vehicles, Electric Transport Units End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | HellermannTyton, Aptiv, LEONI, Yazaki, Sumitomo Electric Industries, Furukawa Electric, Coroplast Fritz Müller, Schlemmer, Delphi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Protection and Routing Component Systems for Vehicles Market Trends and Innovations
Material science advances and regulatory carbon accounting are converging to reshape how routing systems are designed, sourced, and validated across automotive supply tiers.
Multi-lumen extrusion technology is modularizing harness architecture by consolidating power, signal, and data lines within single conduit structures. European premium OEMs are specifying these integrated assemblies for battery pack internal routing to reduce part count and assembly labor. The approach compresses supplier tier complexity while demanding tighter dimensional tolerances from extrusion equipment.
REACH substance restrictions and RoHS amendments are phasing out specific plasticizers and flame retardants used in legacy PVC formulations. Compounders must reformulate halogen-free alternatives that maintain flexibility at minus 40°C while satisfying recyclability documentation requirements. Conduit manufacturers serving German OEM programs face the most accelerated compliance timelines.
Fleet operators and commercial vehicle buyers are consolidating harness procurement specifications across multiple OEM brands to secure volume pricing and standardize maintenance protocols. This buyer concentration pressures specialized routing component suppliers to qualify products across competing platform architectures. The pattern is most pronounced in North American last-mile delivery vehicle segments where total cost of ownership dominates sourcing decisions.
Wire Protection and Routing Component Systems for Vehicles Market Segmentation
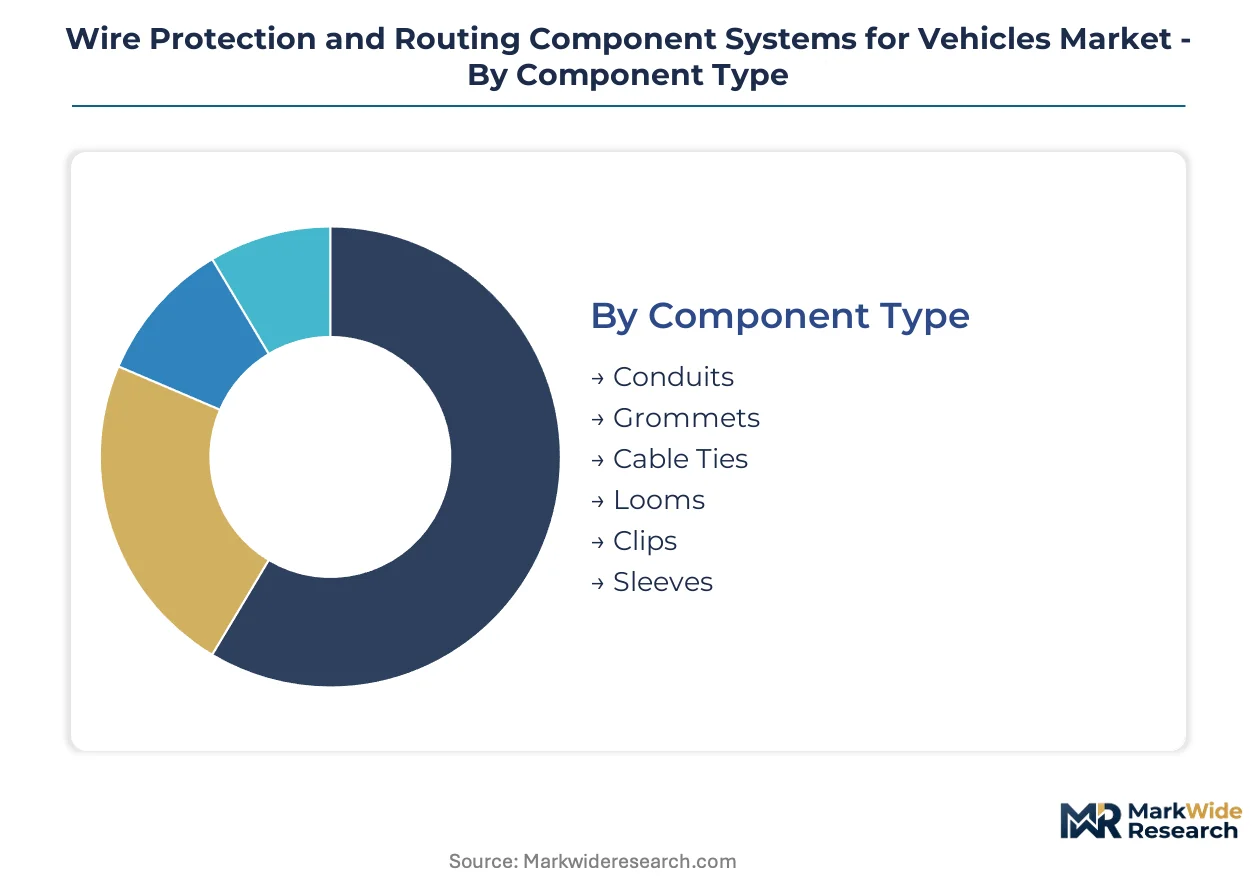
Wire protection and routing component systems fragment across four dimensions that shape procurement economics. Component complexity and thermal tolerance separate premium from commodity tiers. Material chemistry determines regulatory compliance windows. Application voltage levels and end-user integration depth drive margin architecture.
Component Type:
Buyers differentiate by assembly complexity and extrusion precision requirements.
- Conduits:Multi-lumen extruded channels route power, signal, and data lines within single structural housings. Electric transport units in Germany and China specify these for 400-800 volt battery pack internal routing where dimensional tolerance prevents arc faults.
- Looms:Braided or woven textile assemblies bundle conductors while allowing flexibility in confined engine bay architectures. Japanese OEM programs favor loom-based solutions for hybrid powertrain harness organization where thermal cycling demands abrasion resistance.
- Grommets:Molded sealing elements prevent fluid ingress at panel penetration points.
- Cable Ties:Fastening devices secure harness topology against vibration-induced fatigue.
- Clips:Mounting hardware anchors routing paths to structural vehicle members.
- Sleeves:Flexible tubular coverings shield conductor bundles from environmental degradation.
Conduits lead volumes today; looms are gaining share fastest.
Material:
Selection criteria center on thermal endurance and regulatory compliance documentation.
- Polyamide (Nylon):Engineering thermoplastics withstand sustained 150°C exposure near inverters and battery management units. EPA tailpipe standards compel US OEMs to specify polyamide for high-voltage routing zones where PVC fails.
- Thermoplastic Elastomers:Flexible compounds maintain performance across minus 40°C to 135°C operating windows. EU F-Gas Regulation restrictions on halogenated compounds accelerate TPE adoption for REACH-compliant German OEM programs.
- Polyethylene:Cost-effective commodity resin serves low-temperature signal routing applications.
- Polyvinyl Chloride:Legacy formulations face phasedown under RoHS amendments and REACH substance restrictions.
- Rubber:Vulcanized compounds seal against fluid ingress in underbody environments.
- Metal:Metallic braids satisfy China's MIIT-enforced GB standards for high-voltage harness electromagnetic shielding.
Polyamide dominates revenue today; thermoplastic elastomers show the steepest expansion trajectory.
Application:
Voltage architecture and thermal load separate addressable component specifications.
- Electric Transport Units:Battery electric and hybrid platforms demand shielded routing for 400-800 volt systems. China's MIIT mandates metallic braid specifications that expand component demand for domestic OEM electrification programs.
- Passenger Cars:High-volume production amortizes custom extrusion tooling across million-unit platforms. German premium OEMs specify multi-lumen conduit architectures to reduce assembly labor and part count.
- Commercial Trucks:Severe-duty thermal and vibration environments require reinforced sealing grades.
- Two-Wheelers:Cost-constrained architectures favor simplified cable tie and clip fastening systems.
- Off-road Vehicles:Fluid ingress protection prioritizes grommet and sleeve specifications.
- Specialty Vehicles:Low-volume custom programs tolerate higher per-unit tooling amortization.
Passenger cars anchor current procurement volumes; electric transport units are expanding most quickly.
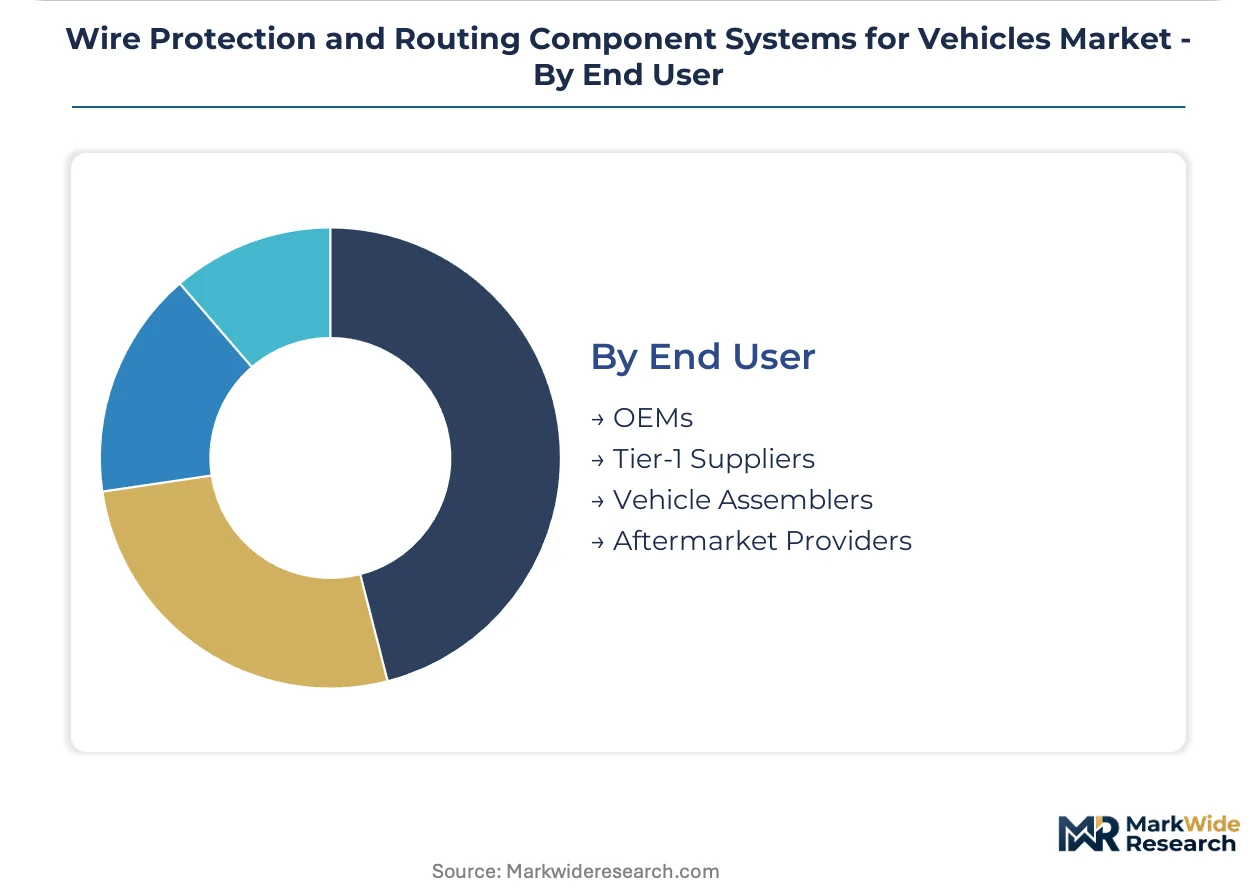
End User:
Integration depth and certification burden determine supplier relationship structures.
- OEMs:Vehicle manufacturers specify platform-level harness architectures and qualify component suppliers directly. European OEMs embedded carbon thresholds under EU Green Deal protocols favor suppliers with regional manufacturing footprints.
- Tier-1 Suppliers:Harness assemblers consolidate procurement across multiple OEM programs to secure volume pricing. North American last-mile delivery fleet operators concentrate buying power through Tier-1 channels.
- Vehicle Assemblers:Contract manufacturers execute build-to-print harness integration.
- Aftermarket Providers:Service channels demand standardized maintenance protocols and repair part availability.
Tier-1 suppliers capture the deepest procurement volumes today; OEM direct sourcing is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive harness manufacturing during the 1980s platform consolidation era, establishing the technical standards that now govern high-voltage routing architectures worldwide. Production expertise subsequently diffused to Japan, the United States, and China as electrification programs multiplied regional procurement volumes.
Germany
Volkswagen Group and BMW electrification roadmaps drive specification intensity for 800-volt battery pack routing systems. EU Green Deal embedded carbon thresholds compel suppliers to document lifecycle emissions for polyamide conduit assemblies. Stuttgart and Munich engineering clusters host development centers where LEONI and Schlemmer refine multi-lumen extrusion tolerances.
China
BYD and CATL battery platform expansion creates procurement pull for metallic braid shielding components. MIIT-enforced GB standards mandate electromagnetic compatibility grades that exceed legacy automotive specifications. Shanghai and Shenzhen manufacturing corridors concentrate high-volume extrusion capacity serving domestic OEM electrification programs.
United States
Ford and General Motors battery electric truck architectures multiply high-voltage cable protection demand across Michigan and Tennessee assembly plants. EPA tailpipe standards tighten through 2030, accelerating powertrain electrification timelines. Detroit-area Tier-1 harness assemblers qualify polyamide formulations for thermal-critical zones near inverters.
Japan
Toyota and Honda hybrid platform persistence sustains loom-based harness demand for thermal-cycling powertrain environments. METI carbon neutrality roadmaps align procurement specifications with EU lifecycle documentation requirements. Nagoya and Tokyo industrial clusters anchor Sumitomo Electric Industries and Yazaki production footprints.
India
Tata Motors and Mahindra electric vehicle programs expand addressable demand for cost-optimized routing component specifications. PLI scheme incentives for battery electric manufacturing draw harness protection procurement volumes from underpenetrated supplier bases. Tamil Nadu and Gujarat automotive corridors concentrate new assembly capacity targeting export markets.
Wire Protection and Routing Component Systems for Vehicles Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material sophistication and thermal tolerance certification tiers. The supplier base organizes into three structural layers: integrated resin compounders with captive extrusion capacity, specialized conduit fabricators dependent on external polymer supply, and commodity fastening component producers. Consolidation pressure intensifies as OEMs reduce qualified supplier lists for 800-volt platform programs. Two dominant competitive moves define current positioning: backward integration into high-temperature resin compounding and geographic co-location with battery assembly plants.
Within the integrated compounder-extruder tier, LEONI and Yazaki exemplify European and Japanese archetypes respectively. LEONI leverages its regional manufacturing footprint to satisfy EU Green Deal lifecycle documentation requirements. Yazaki anchors its positioning through in-house production of resin formulations for thermal-critical routing channels. Sumitomo Electric Industries occupies a scale-driven position across Japanese and Southeast Asian OEM supply bases. These three entities represent distinct strategic postures: European regulatory compliance, Japanese backward integration, and pan-Asian volume leadership.
| Leading Market Players |
|---|
| HellermannTyton |
| Aptiv |
| LEONI |
| Yazaki |
| Sumitomo Electric Industries |
| Furukawa Electric |
| Coroplast Fritz Müller |
| Schlemmer |
| Delphi Technologies |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between 800-volt thermal-rated assemblies and commodity 12-volt fastening components manifests in pricing power concentration at integrated compounder-extruders and margin compression at generic clip and tie suppliers. This bifurcation feeds back into supply chain configuration as OEMs consolidate qualified supplier lists around Tier-1 harness assemblers with direct resin compounding relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates polyamide conduit assemblies certified for 150°C inverter proximity from TPE-based mid-tier solutions and PVC legacy formulations facing REACH phaseout. Price differentiation hinges on thermal certification tier and OEM platform qualification status. Cost compression in commodity fastening tiers is intensifying because Indian and Southeast Asian suppliers are scaling volume capacity. Fleet procurement managers at North American last-mile operators exhibit highest price sensitivity; German premium OEM platform engineers show least.
Supply Chain Analysis
Polyamide resin feedstock rests on German and Japanese specialty chemical producers with captive caprolactam conversion capacity. Raw material dependencies center on crude oil derivatives, thermoplastic elastomer base polymers, and metallic braid copper alloys. Single-source vulnerability concentrates in high-temperature resin compounding where qualification timelines extend 12-18 months. Distribution runs through Tier-1 harness assemblers consolidating procurement across multiple OEM programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wire protection procurement has entered a late-cycle quality phase where 800-volt thermal certification and embedded carbon documentation separate viable suppliers from margin-trapped commodity players. OEM electrification roadmaps are pulling specification intensity upward.
For Market Incumbents: Extend qualification capabilities into 800-volt isolation testing protocols before IEC 60664 certification scarcity hardens competitive moats. Consolidate resin compounding relationships in Germany and Japan to defend against geographic single-source vulnerability. Backward integration into halogen-free TPE formulation protects margin pools as EU F-Gas restrictions accelerate. For New Entrants and Emerging Players: Multi-lumen extrusion equipment leasing models offer a technology-first wedge into Indian PLI-subsidized electric vehicle programs where specialized conduit supply remains underpenetrated. Target cost-optimized routing specifications for two-wheeler and commercial truck segments. Qualify through Tier-1 harness assemblers rather than direct OEM engagement to bypass platform-level certification barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where 800-volt safety certification scarcity and tooling capex intensity strand mid-scale fabricators without resin compounding integration. Long-term viability favors integrated compounder-extruders with European manufacturing footprints satisfying EU Green Deal lifecycle documentation. Watch MIIT enforcement patterns on GB standard metallic braid specifications as inflection indicator for shielded component demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Yazaki's captive polyamide production anchors margin control against feedstock volatility. |
| Geographic Co-location with Battery Assembly | LEONI's Stuttgart proximity to BMW and Volkswagen reduces logistics cost and carbon documentation burden. |
| Multi-lumen Extrusion Technology Investment | Schlemmer's dimensional tolerance capabilities secure premium OEM battery pack internal routing specifications. |
| Halogen-free Formulation Qualification | REACH-compliant TPE adoption opens German OEM procurement channels closed to legacy PVC suppliers. |
| Metallic Braid Shielding Certification | Sumitomo Electric's GB standard compliance captures BYD and CATL high-voltage harness demand in China. |
Research Methodology
Multiple input streams — primary interviews with Tier-1 supplier procurement leads, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, SEC filings, and customs/trade records; plus patent and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations covered thermal certification requirements, resin formulation roadmaps, and electrification platform content per vehicle estimates.
Historical volume trajectories were cross-referenced against expert panel inputs on 800-volt adoption curves and MIIT enforcement intensity. The analytical framework modeled segmentation across component type, material chemistry, application voltage architecture, and end-user integration depth throughout the forecast period. CAGRs were derived from platform-level content forecasts and regional electrification policy trajectories. Key inputs included polyamide substitution rates for PVC and metallic braid penetration in Chinese battery electric programs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to resin feedstock volatility, EU-REACH regulatory amendment timing, and OEM 800-volt platform consolidation patterns. Material deviation in caprolactam supply disruptions or MIIT GB standard enforcement acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Germany Automotive Camera Market
Automotive Electronics & Wiring
Vehicle Intercom System Market
Automotive Electronics & Wiring
Traffic Sign Recognition System Market
Automotive Electronics & Wiring
Global Vehicle Camera Market
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market
Automotive Electronics & Wiring
North America Automotive Camera Market
Automotive Electronics & Wiring
Automotive Micro Switch Market
Automotive Electronics & Wiring
Automotive Communication Technology Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
Steering Roll Connector Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Automotive Fuse Block Market