
 Automotive Smart Key Market | 2026-2036
Automotive Smart Key Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Smart Key Market Intelligence
China is reshaping competitive dynamics in automotive smart key manufacturing through expanded domestic semiconductor packaging and antenna module capacity. Continental AG leverages its integrated electronics portfolio to supply complete keyless entry systems directly to German and Chinese OEMs. TOKAI RIKA CO LTD anchors Asian supply relationships through specialized manufacturing of high-frequency resonant circuits and mechanical key blanks. Robert Bosch GmbH competes on software-defined key architectures that merge digital key credentials with vehicle immobilizer functions.
An automotive smart key is an electronic access device that replaces mechanical ignition keys with encrypted radio-frequency or ultra-wideband communication between a portable fob or smartphone and vehicle-mounted transceivers, typically operating at 125 kHz low-frequency for wake-up and 433 MHz or 2.4 GHz for data exchange. Its primary purpose is to enable passive entry, push-button start, and remote authorization while integrating theft-deterrent immobilizer functions. Smart proximity keys lead volume shipments across passenger vehicle applications where hands-free entry has become standard fitment in mid-range trims and above. Digital keys represent the fastest-expanding technology segment as smartphone-based NFC and Bluetooth credentials displace dedicated hardware fobs in electric vehicle platforms. RFID-based systems still occupy the aftermarket channel where retrofit compatibility with legacy immobilizer architectures sustains replacement demand.
FCC Part 15 rules govern radio transmission power and spectrum allocation for smart key fobs sold in the United States, while UNECE R155 and R156 regulations in Europe mandate cybersecurity management systems and software update capabilities that directly affect digital key architecture design. These frameworks force suppliers to embed hardware security modules and over-the-air credential provisioning from the component level upward. Stakeholders must decide whether to pursue platform-agnostic digital key standards or align with Apple CarKey and Google Wallet ecosystems as smartphone OEMs encroach on traditional supplier territory.
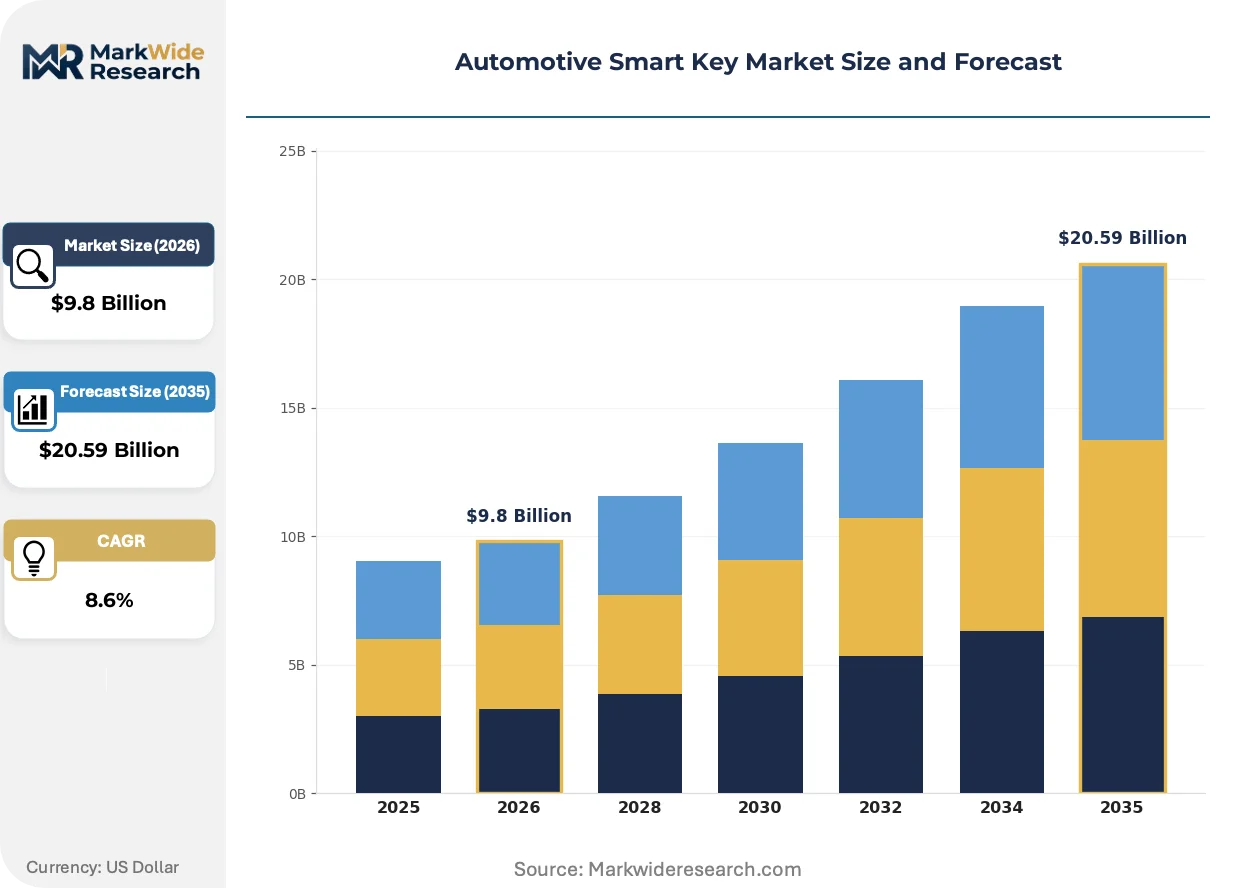
Market Dynamics
Ultra-wideband (UWB) positioning technology is compressing the competitive window for automotive entry system suppliers, forcing simultaneous hardware redesign and cybersecurity recertification across European and North American supply chains.
Growth Catalysts
- UNECE R155 mandate:European vehicle cybersecurity regulations now require hardware security modules in all connected entry systems, creating mandatory upgrade cycles across OEM fleets.
- Electric vehicle platforms:Battery-electric architectures prioritize smartphone-native digital key integration, eliminating mechanical backup keys and expanding addressable component value per vehicle.
- German premium OEM specification-setting:Technical requirements defined by Stuttgart and Munich headquarters propagate through global supplier contracts, standardizing proximity-based access across price tiers.
Market Restraints
- Lithium niobate and RF substrate cost volatility:Specialized piezoelectric materials for resonant circuit manufacturing face concentrated supply from Japanese and Chinese specialty chemical producers.
- Antenna module foundry concentration:High-frequency substrate packaging capacity clusters in Taiwan and South Korea, exposing tier-one suppliers to single-source geographic risk.
- FCC Part 15 transmission power limits:United States spectrum allocation rules constrain UWB signal strength, degrading passive entry accuracy versus European and Asian implementations.
Strategic Opportunities
- India automotive electrification:Domestic EV production incentives under the PLI scheme create first-mover advantage for digital key credential providers establishing local software development centers.
- Car-sharing and subscription fleet integration:Time-bound cryptographic key provisioning enables revenue-per-vehicle-hour models distinct from traditional ownership economics.
- Bluetooth Low Energy and NFC convergence:Dual-protocol smartphone credentialing merges convenience-driven passive entry with backup authentication when primary wireless fails.
Industry Challenges
- Embedded cryptography engineering scarcity:Automotive-grade secure element design requires expertise spanning hardware tamper resistance and over-the-air key lifecycle management.
- Legacy immobilizer backward compatibility:Mechanical key blank retention for 10+ year vehicle service life complicates pure-digital architecture transitions.
- Multi-stakeholder certification timelines:Smartphone OEM ecosystem approval processes add 12-18 month validation gates beyond traditional automotive component qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Smart Key Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.59 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Keyless Entry, Smart Proximity Key, Digital Key, Key Fob End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Technology: RFID, Bluetooth, NFC, Infrared Application: Passenger Vehicles, Commercial Vehicles, Luxury Cars, Electric Vehicles |
| Companies Covered | Valeo SA, ZF Friedrichshafen AG, TOKAI RIKA CO LTD, HELLA GmbH & Co KGaA, Huf Hulsbeck & Furst GmbH & Co KG, Continental AG, Robert Bosch GmbH, Alps Alpine Co Ltd, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Smart Key Market Strategic Shifts & Innovations
Automotive access systems are converging on software-defined architectures where credential storage migrates from dedicated silicon to trusted execution environments inside consumer mobile devices.
Ultra-wideband ranging technology is migrating from high-frequency resonant circuits to software-calibrated antenna arrays. German and Chinese electric vehicle manufacturers have accelerated UWB adoption across 2024-2025 model year launches. This shift is compressing the addressable market for discrete LF wake-up coil suppliers while expanding software licensing revenue pools for semiconductor platform vendors.
The EU Cyber Resilience Act imposes mandatory vulnerability disclosure and patch availability requirements on all connected vehicle components. Tier-one suppliers must now maintain 15-year software support infrastructure for entry system firmware. Digital key architectures with over-the-air update capabilities capture specification preference in Stuttgart and Wolfsburg procurement committees.
Fleet operators and mobility service providers now specify API-first key credentialing that unbundles physical hardware from authorization logic. Car-sharing platforms in Berlin and Paris have displaced traditional fleet management key distribution with time-bound smartphone credentials. This procurement pattern is most visible in European urban mobility contracts where vehicle utilization rates exceed 40 percent daily.
Automotive Smart Key Market Segmentation
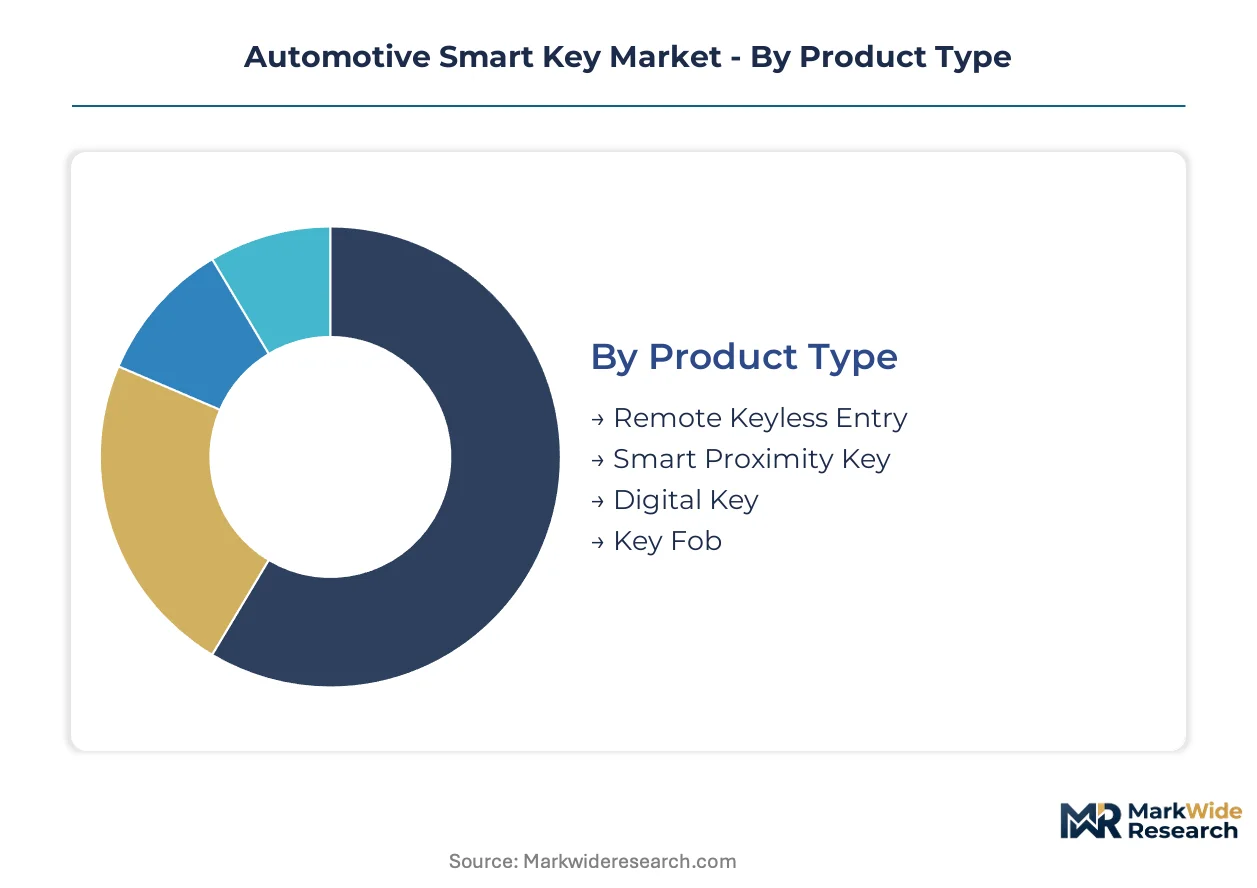
Segmentation in automotive smart keys reveals divergent replacement cycles across hardware and software-based systems. Hardware fobs operate on 5-7 year vehicle platform cycles, while smartphone credentials refresh annually with OS updates. Understanding these temporal mismatches helps suppliers allocate R&D resources between durable component engineering and agile software iteration.
Product Type:
Replacement velocity varies dramatically across this category, with smartphone-dependent credentials turning over fastest and mechanical-electronic hybrids slowest.
- Smart Proximity Key:Combines passive entry transponders with push-button start authorization through encrypted LF-UWB handshakes. German premium OEMs in Stuttgart and Munich specify these systems across mid-range trims and above, sustaining volume despite digital displacement pressure from UNECE R155 cybersecurity mandates.
- Digital Key:Smartphone-native credentialing using NFC and Bluetooth Low Energy protocols eliminates dedicated hardware entirely. Electric vehicle platforms in China prioritize this architecture, expanding component value per vehicle through secure element licensing and over-the-air provisioning infrastructure.
- Remote Keyless Entry:Conventional radio-frequency fobs operating at 433 MHz provide lock-unlock functions without passive entry capability. Aftermarket channels in India sustain replacement demand for legacy vehicle parc compatibility.
- Key Fob:Basic mechanical-electronic hybrid units with integrated immobilizer transponders serve entry-level vehicle segments and emerging market price tiers.
Smart Proximity Key anchors the volume base while Digital Key gains share at the steepest rate.
End User:
Procurement authority concentrates differently across this dimension, with direct vehicle manufacturers wielding specification power while fleet operators drive credential-as-a-service models.
- OEMs:Original equipment manufacturers in Germany and China define technical specifications that cascade through tiered supply contracts. Their procurement committees mandate hardware security modules and UWB ranging accuracy thresholds that filter component supplier eligibility.
- Fleet Operators:Car-sharing platforms in Berlin and Paris specify API-first credentialing with time-bound cryptographic provisioning. Their utilization-based economics favor smartphone-native authorization over physical key distribution logistics.
- Aftermarket Providers:Independent distributors serve replacement demand for lost or damaged fobs, requiring backward compatibility with legacy immobilizer architectures spanning 10+ year vehicle service lives.
- Vehicle Assemblers:Contract manufacturing facilities execute build-to-print assembly of keyless entry systems against OEM-provided specifications and quality protocols.
OEMs dominate absolute procurement value while Fleet Operators are expanding most quickly as mobility-as-a-service penetration deepens.
Technology:
Technology selection in this category tracks directly against electromagnetic spectrum allocation and cybersecurity certification requirements across target markets.
- UWB (Ultra-Wideband):Centimeter-precision ranging enables spatial authentication that resists relay attacks. German and Chinese electric vehicle manufacturers accelerated adoption across recent model year launches, compressing competitive windows for legacy LF-RF suppliers.
- Bluetooth Low Energy:Widely deployed smartphone-native protocol supports passive entry with lower power consumption than classic Bluetooth. FCC Part 15 transmission power limits in the United States constrain implementation accuracy versus European deployments.
- RFID:125 kHz low-frequency wake-up coils initiate vehicle-side transponder communication. Concentrated supply from Japanese and Chinese specialty chemical producers for lithium niobate substrates creates input cost volatility.
- NFC:Near-field communication provides backup authentication when primary wireless fails, particularly in smartphone credential architectures.
- Infrared:Legacy directional communication persists in aftermarket remote entry systems for cost-sensitive applications.
UWB commands premium positioning while Bluetooth Low Energy delivers the broadest installed base expansion.
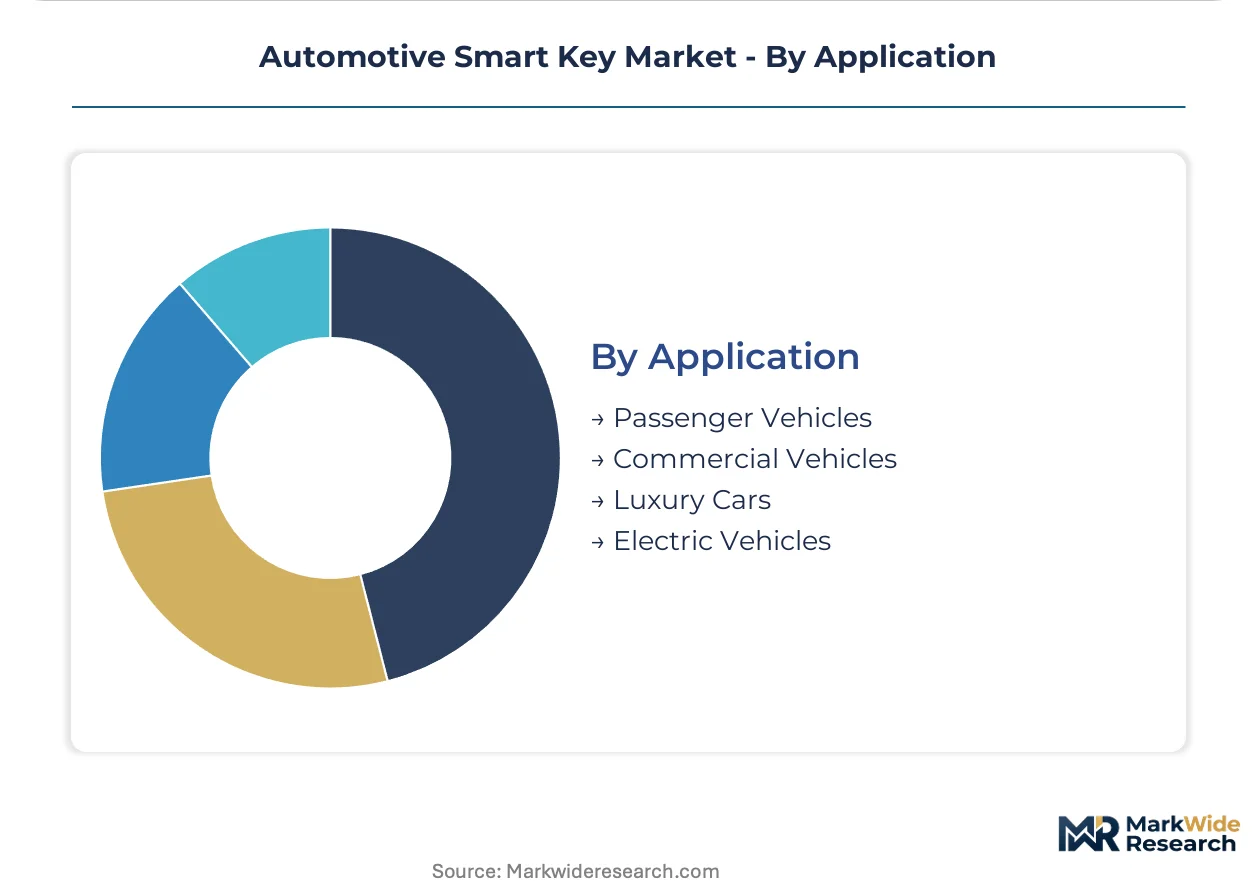
Application:
Application segmentation reflects divergent electrification timelines and theft-risk profiles across vehicle categories.
- Electric Vehicles:Battery-electric architectures eliminate mechanical ignition cylinders entirely, mandating pure-digital credentialing. Chinese domestic EV production incentives under the PLI scheme create first-mover advantage for digital key providers establishing local software development.
- Luxury Cars:Premium price tolerance funds multi-protocol redundancy and biometric secondary authentication. Stuttgart and Munich headquarters propagate technical requirements through global supplier contracts.
- Passenger Vehicles:Mid-range trims standardize proximity entry across German, Japanese, and South Korean OEM lineups, sustaining volume for discrete LF wake-up coil suppliers.
- Commercial Vehicles:Fleet management requirements prioritize centralized credential revocation and driver accountability logging over consumer convenience features.
Passenger Vehicles provide the volume foundation while Electric Vehicles are climbing the fastest as powertrain electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antenna module foundry capacity clusters heavily in Taiwan and South Korea, exposing tier-one suppliers to single-source geographic risk while German premium OEMs propagate technical specifications through global contracts.
Germany
Stuttgart and Munich headquarters define UWB ranging accuracy thresholds that cascade through tiered supplier contracts. The KBA enforces UNECE R155 cybersecurity mandates that mandate hardware security modules in all connected entry systems. Bavaria hosts concentrated R&D facilities where Continental AG and Robert Bosch GmbH develop software-defined key architectures.
China
Domestic EV production incentives under the PLI scheme accelerate smartphone-native digital key adoption across battery-electric platforms. MIIT regulates radio transmission standards that shape LF-UWB handshake protocols for local vehicle programs. The Yangtze River Delta anchors expanded semiconductor packaging capacity that reshapes competitive dynamics in antenna module supply.
United States
FCC Part 15 rules constrain UWB signal strength below European and Asian implementation levels, degrading passive entry accuracy for domestic fleet specifications. NHTSA coordinates with cybersecurity agencies on connected vehicle component standards. Michigan-based OEM procurement committees balance backward compatibility requirements against pure-digital architecture transitions.
Japan
METI oversees industrial standards for high-frequency resonant circuits where lithium niobate substrate supply concentrates among specialty chemical producers. TOKAI RIKA CO LTD anchors Asian supply relationships through mechanical key blank and resonant circuit manufacturing. The Chubu region maintains precision component fabrication clusters serving both domestic OEMs and export contracts.
India
PLI scheme incentives for domestic EV production create first-mover positioning for digital key credential providers establishing local software development centers. BIS certification requirements shape component qualification timelines for entry system suppliers. Maharashtra and Tamil Nadu host emerging vehicle assembly clusters where fleet operators specify API-first credentialing for mobility-as-a-service deployment.
Automotive Smart Key Market Key Industry Players
Integrated electronics conglomerates and specialized component fabricators split the market along capability depth versus portfolio breadth lines. The vendor base organizes into three strategic archetypes: full-system integrators supplying complete keyless entry architectures, discrete component specialists dominating resonant circuit and antenna niches, and software-platform vendors licensing secure element credentials. Dominant competitive moves include strategic partnerships with smartphone OEM ecosystems and backward integration into high-frequency substrate packaging.
Within the full-system integrator tier, Continental AG and Robert Bosch GmbH exemplify platform-agnostic engineering capabilities that span hardware security modules through over-the-air provisioning infrastructure. TOKAI RIKA CO LTD occupies a specialized position among discrete component fabricators, representing the resonant circuit and mechanical key blank segment where concentrated supply relationships sustain margin structures. These three anchors illustrate the market's bifurcation between consolidated system supply and niche component expertise.
| Leading Market Players |
|---|
| Valeo SA |
| ZF Friedrichshafen AG |
| TOKAI RIKA CO LTD |
| HELLA GmbH & Co KGaA |
| Huf Hulsbeck & Furst GmbH & Co KG |
| Continental AG |
| Robert Bosch GmbH |
| Alps Alpine Co Ltd |
| DENSO Corporation |
| Others |
Cost & Logistics Intelligence
Lithium niobate substrate supply from Japanese and Chinese specialty chemical producers concentrates pricing power in the resonant circuit tier, forcing tier-one suppliers to absorb volatility or pass through costs to German and Chinese OEM procurement committees.
Pricing Analysis
UNECE R155 dictates the pricing tier structure across European vehicle cybersecurity mandates, separating hardware security module-integrated systems from legacy LF-RF architectures. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and UWB ranging accuracy. Cost compression in the economy tier intensifies because aftermarket providers compete on backward compatibility with 10+ year vehicle parc. Fleet operators exhibit lowest price sensitivity due to utilization-based economics, while independent aftermarket distributors face acute margin pressure.
Supply Chain Analysis
Export control regimes on high-frequency substrate packaging technology limit flows from Taiwan and South Korea, constraining antenna module availability for European and North American tier-one suppliers. The supply chain draws from Japan for lithium niobate resonant circuits, Taiwan and South Korea for semiconductor packaging, and Germany for software-defined key architectures. Single-source geographic vulnerability in high-frequency substrate foundries exposes suppliers to disruption. Distribution runs through OEM direct procurement for original fitment and specialized aftermarket channels for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: UNECE R155 and FCC Part 15 certification requirements create multi-year validation barriers that protect incumbent positions from rapid displacement.
For Market Incumbents: Entrench through backward integration into high-frequency substrate packaging in Taiwan and South Korea, reducing single-source exposure while capturing margin pools upstream. Deepen certification investment in hardware security module architectures to maintain specification-setting influence with Stuttgart and Munich procurement committees against emerging smartphone OEM ecosystem encroachment.
For New Entrants and Emerging Players: Establish a beachhead in Indian digital key software development under PLI scheme incentives, where domestic EV production creates first-mover positioning absent entrenched supplier relationships. Target fleet operator API-first credentialing contracts in European urban mobility markets, leveraging time-bound cryptographic provisioning as a service differentiation against hardware-centric incumbents.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive electronics specialists holding UWB platform licenses and OEM qualification relationships. Long-term viability hinges on 15-year software support infrastructure mandated by EU Cyber Resilience Act compliance. Watch for inflection in smartphone OEM ecosystem approval timelines, where 12-18 month validation gates beyond traditional automotive qualification signal competitive pressure intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| UWB Platform Standardization | German premium OEMs propagate centimeter-precision ranging requirements through global supplier contracts. |
| Secure Element Licensing Agreement | Digital key credential providers capture recurring revenue through over-the-air provisioning infrastructure. |
| Software-Defined Vehicle Investment | Credential storage migration to trusted execution environments reduces hardware fob dependency. |
| Geographic Manufacturing Footprint | Yangtze River Delta semiconductor packaging expansion reshapes antenna module competitive dynamics. |
| Charging Infrastructure Partnership | Electric vehicle platform integration eliminates mechanical ignition cylinders, mandating pure-digital architectures. |
Research Approach
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet operator mobility specialists and refined through secondary validation against vehicle production databases, IHS Markit registration data, FCC equipment authorization filings, and UNECE regulatory submissions. Bottom-up component demand modeling triangulated against top-down OEM platform deployment schedules.
Demand-supply balance framing anchored the forecast framework across the analysis window, with segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from fitted growth curves applied to technology transition rates and regulatory mandate compliance timelines. Industry-specific inputs included UWB adoption curves in German and Chinese electric vehicle launches and digital key credential refresh cycles tied to smartphone OS updates.
Stress conditions across lithium niobate price volatility, Taiwan semiconductor packaging capacity utilization, and UWB cybersecurity recertification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding UNECE R155 fleet penetration and FCC Part 15 regulatory stability. Material shifts in smartphone OEM ecosystem certification requirements or export control expansion on high-frequency substrates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market
Automotive Electronics & Wiring
India Automotive Lighting Market
Automotive Electronics & Wiring
Automotive HMI Market
Automotive Electronics & Wiring
Traffic Sign Recognition System Market
Automotive Electronics & Wiring
Automotive Smart Camera Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Micro Switch Market
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
Automotive Split-View Camera Module Market
Automotive Electronics & Wiring
Automotive Relay Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market