
 Automotive Starting System Market | 2026-2036
Automotive Starting System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Starting System Market Outlook
Over-the-air software updates for starter motor calibration and predictive maintenance subscriptions is realigning how suppliers monetize starting system lifecycles. Robert Bosch GmbH leverages its embedded software stack to extend service revenue beyond hardware sales. Denso Corporation anchors its position through R&D intensity in integrated starter-generator architectures. Mitsubishi Electric Corporation specializes in high-torque compact motors for hybrid powertrains.
An automotive starting system comprises the starter motor, ignition switch, relay, and battery that crank the internal combustion engine to initiate operation, typically requiring 12V or 48V electrical supply and delivering 1.5–3.5 kW of cranking power depending on engine displacement. Starter motor assemblies represent the largest value pool within product type segments, though smart systems technology is gaining share as vehicle electrification advances. OEM end users command the highest volume commitments, while aftermarket providers capture margin from aging vehicle parc replacement cycles. Electronic ignition technology dominates new vehicle fitment, with hybrid solutions emerging fastest in premium deployment segments.
EPA tailpipe standards, NHTSA corporate average fuel economy rules, and China's MIIT dual carbon goals collectively mandate lighter, more efficient starting components that reduce parasitic engine load. These frameworks compel suppliers to redesign solenoids and pinion gears for stop-start compatibility and regenerative integration. Stakeholders must monitor how 48V mild-hybrid proliferation reshapes component specifications and supplier qualification timelines.
Market Dynamics
The transition from 12V to 48V mild-hybrid architectures is compressing supplier qualification timelines and forcing solenoid redesigns for stop-start compatibility across OEM programs.
Growth Catalysts
- EPA tailpipe standards:NHTSA corporate average fuel economy rules mandate lighter starting components that reduce parasitic engine load, accelerating demand for integrated starter-generator systems in US light-duty vehicles.
- Commercial vehicle fleet electrification:Fleet operators in China are expanding adoption of integrated starting solutions to meet MIIT dual carbon goals while maintaining cold-crank reliability.
- Shanghai-Chongqing manufacturing corridor:Automotive production concentration in these Chinese industrial clusters creates localized demand density for smart starter motor assemblies.
Market Restraints
- Copper and rare-earth magnet cost volatility:Starter motor assemblies depend on neodymium and copper windings, with price swings compressing component margins unpredictably.
- Supply concentration in East Asian electronics:Power semiconductor sourcing for 48V systems clusters among limited foundry capacity, creating single-source vulnerability.
- ICE vehicle phase-out timelines:EU Green Deal transport decarbonization mandates threaten long-term addressable market for pure starting systems without hybrid integration.
Strategic Opportunities
- India BIS efficiency mandates:Stricter Bharat Stage VI implementation creates regulatory tailwind for stop-start system penetration in sub-4-meter vehicle segments.
- Over-the-air calibration services:Predictive maintenance subscriptions represent new recurring revenue streams beyond hardware replacement cycles.
- Aftermarket smart retrofit kits:Aging vehicle parc in Brazil and Mexico offers underpenetrated geography for electronic ignition upgrade modules.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety compliance for starter motor control algorithms extends development timelines by 8-14 months.
- Legacy 12V-48V integration:Dual-voltage electrical architecture deployment requires reconciling incompatible component specifications across model generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Starting System Market |
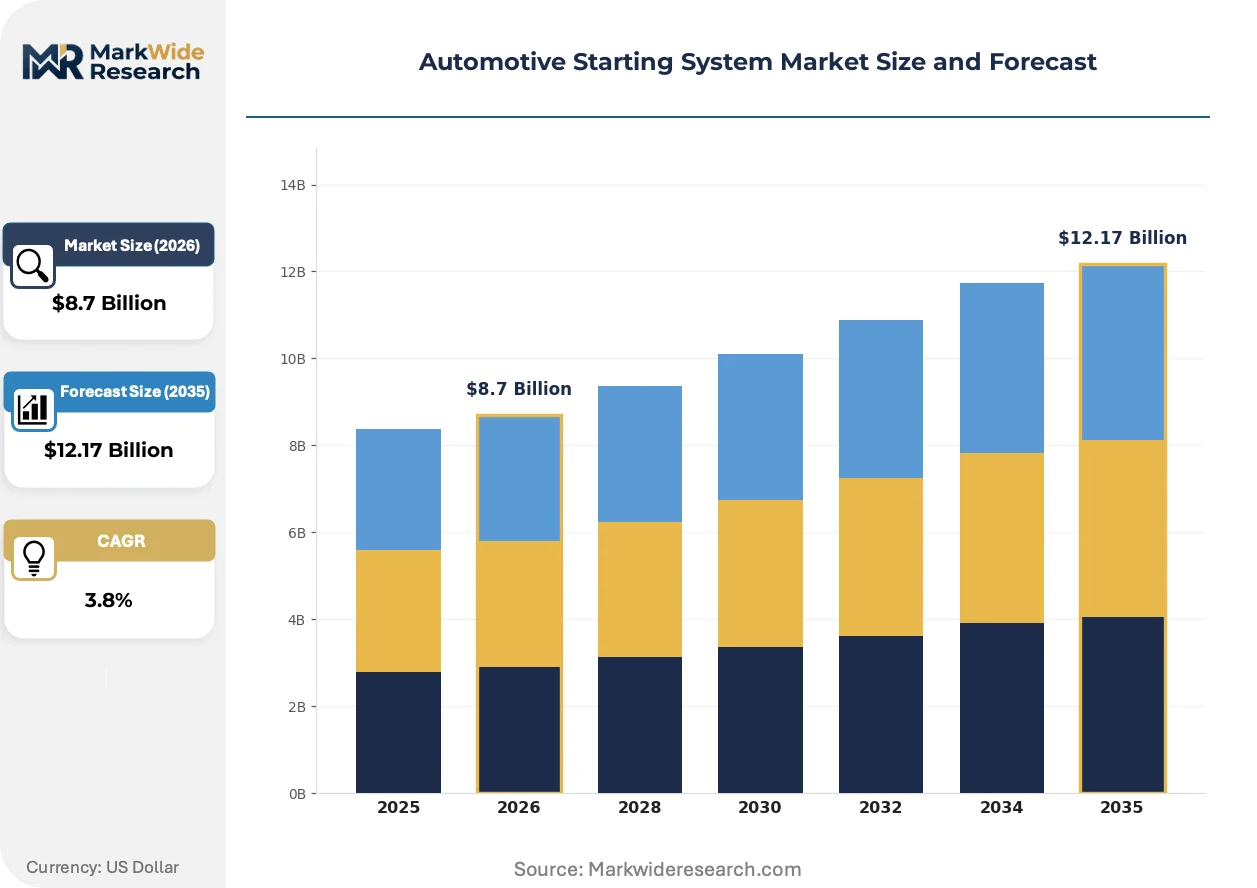
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starter Motor, Ignition Switch, Relay, Battery End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Technology: Electronic Ignition, Mechanical Ignition, Smart Systems, Hybrid Solutions Deployment: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Machinery |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Mitsubishi Electric Corporation, Valeo Group, Mitsuba Corporation, Hitachi Automotive Systems Ltd., BorgWarner Inc., Lucas Electrical Limited, Mahle GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Starting System Market Strategic Shifts
Software-defined functionality is displacing mechanical redundancy in starting systems, while regulatory pressure and procurement evolution reshape how value is captured across the product lifecycle.
Integrated starter-generator (ISG) technology combines cranking and generation functions in a single compact motor, eliminating separate alternator hardware. Premium OEMs in Germany and Japan are adopting ISG architectures at accelerated pace for 48V mild-hybrid platforms. This convergence is decentralizing component sourcing decisions from discrete starter motor suppliers toward powertrain integration specialists.
EU F-Gas Regulation phase-down schedules are pressuring refrigerant circuit electrification, which indirectly tightens thermal management demands on starting systems in stop-start configurations. The regulation compels suppliers to redesign pinion engagement mechanisms for high-cycle durability. European premium passenger car segments are responding with belt-driven starter-generator adoption to spread thermal load.
Fleet procurement departments are unbundling hardware acquisition from predictive maintenance subscriptions, treating starting system lifecycle value as operational expenditure rather than capital investment. Tier-1 suppliers face channel disruption as direct OEM software contracts bypass traditional component distribution. This behavioral shift is most visible in North American commercial vehicle leasing programs.
Automotive Starting System Market Segmentation
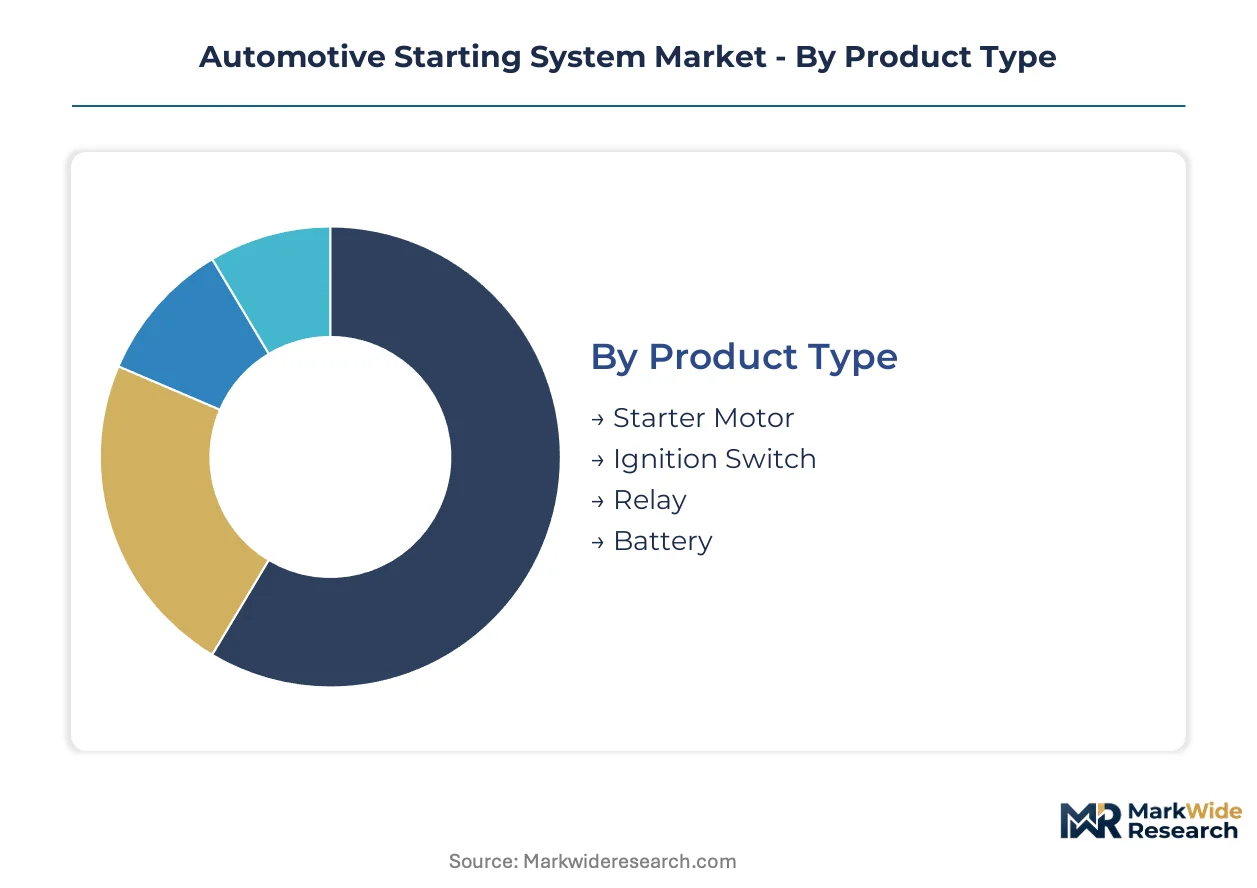
Starting system architectures vary sharply across voltage classes, thermal envelopes, and duty cycles. Segmentation reveals where component margins concentrate and which technical specifications determine supplier qualification timelines.
Product Type:
Voltage architecture and torque density specifications define value capture across mechanical and electromechanical subsystems.
- Starter Motor:Assemblies deliver 1.5–3.5 kW cranking power through 12V or 48V electrical supply, with integrated starter-generator configurations commanding premium positioning. Demand concentrates in China's Shanghai-Chongqing manufacturing corridor, where stop-start system adoption accelerates solenoid redesign cycles.
- Ignition Switch:Electronic modules with embedded control algorithms now dominate new vehicle fitment, displacing mechanical redundancy. OEMs in Germany and Japan are adopting smart ignition architectures that interface with 48V mild-hybrid power management systems.
- Relay:High-current switching components bridge battery and starter motor circuits, with solid-state variants gaining share in premium deployment segments.
- Battery:Lead-acid and lithium-ion configurations supply cranking current, with absorbed glass mat technology extending cycle life for stop-start applications.
Starter motor assemblies lead on scale; smart systems technology leads on momentum.
End User:
Procurement authority and lifecycle value recognition vary dramatically across direct OEM relationships versus aftermarket channels.
- OEMs:Direct vehicle manufacturers command highest volume commitments and longest qualification timelines, integrating starting systems at powertrain design freeze. EPA emissions standards and NHTSA fuel economy rules in the United States are tightening cranking performance requirements for light-duty vehicle programs.
- Aftermarket Providers:Independent distributors capture margin from aging vehicle parc replacement cycles, particularly in Brazil and Mexico where electronic ignition upgrade modules show underpenetrated demand.
- Tier-1 Suppliers:System integrators manage subsystem validation and embedded software certification for ISO 26262 functional safety compliance.
- Dealerships:Authorized service networks handle warranty repairs and factory-authorized retrofit programs for stop-start system upgrades.
OEMs dominate absolute volume; aftermarket providers show the steepest expansion trajectory in subscription-based predictive maintenance.
Technology:
Control methodology and power electronics integration determine thermal management requirements and cycle durability.
- Electronic Ignition:Microprocessor-controlled spark timing and fuel injection synchronization dominate new vehicle fitment. India's BIS efficiency mandates under Bharat Stage VI implementation create regulatory tailwind for electronic system penetration in sub-4-meter vehicle segments.
- Smart Systems:Over-the-air calibration capability and predictive maintenance algorithms are realigning supplier monetization models beyond hardware replacement cycles. Robert Bosch GmbH leverages embedded software stacks to extend service revenue in this segment.
- Mechanical Ignition:Conventional distributor-based systems persist in legacy vehicle parc and certain commercial vehicle applications with minimal electronics content.
- Hybrid Solutions:Integrated starter-generator architectures combine cranking and generation functions, eliminating separate alternator hardware. Denso Corporation anchors position through R&D intensity in this technology.
Electronic ignition leads on installed base; smart systems lead on recurring revenue potential.
Deployment:
Engine displacement, duty cycle severity, and electrification roadmap stage dictate component specification requirements.
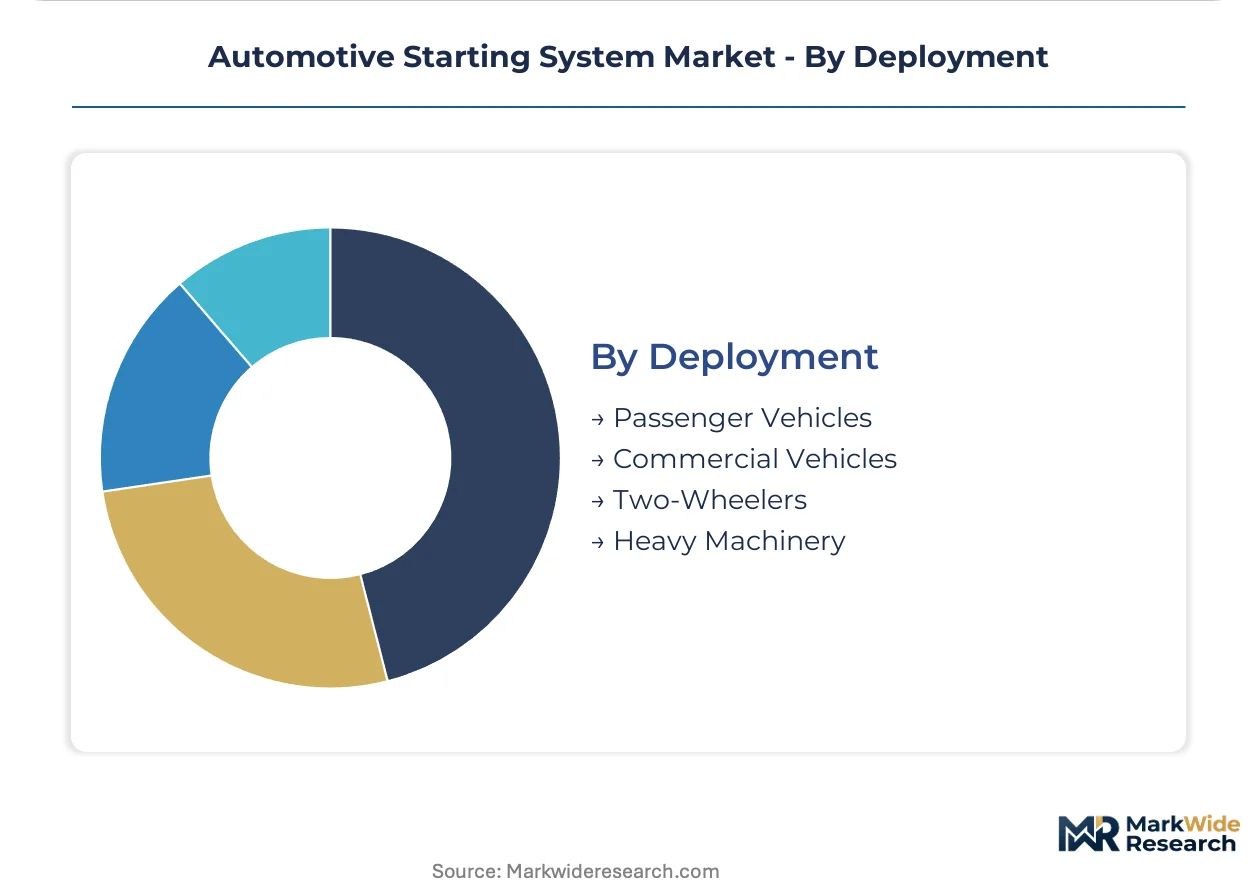
- Passenger Vehicles:Light-duty applications drive volume for 12V and 48V systems, with EU F-Gas Regulation phase-down schedules pressuring thermal management demands on stop-start configurations.
- Commercial Vehicles:Fleet operators in China are expanding adoption of integrated starting solutions to meet MIIT dual carbon goals while maintaining cold-crank reliability for heavy-duty cycles.
- Two-Wheelers:Compact starting systems with reduced weight and cost targets serve high-volume emerging market segments.
- Heavy Machinery:High-torque compact motors from suppliers like Mitsubishi Electric Corporation specialize in hybrid powertrain applications for construction and agricultural equipment.
Passenger vehicles lead on unit volume; commercial vehicles lead on technology upgrade intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns reflect divergent cost-of-compliance trajectories across major automotive manufacturing jurisdictions. Suppliers relocate capacity toward regions with lighter regulatory burdens on 48V system certification. China, Germany, the United States, Japan, and India concentrate divergent strategic responses to electrification mandates.
China
Shanghai-Chongqing manufacturing corridors generate concentrated demand for smart starter motor assemblies serving domestic OEM programs. MIIT dual carbon goals compel fleet operators toward integrated starting solutions with stop-start compatibility. Chongqing's automotive cluster anchors heavy-duty commercial vehicle electrification trials.
Germany
Premium passenger car segments accelerate belt-driven starter-generator adoption under EU F-Gas Regulation thermal management pressures. KBA type-approval processes for 48V mild-hybrid architectures compress supplier qualification timelines. Bavaria's powertrain engineering centers drive ISG architecture standardization.
United States
EPA tailpipe standards and NHTSA fuel economy rules tighten cranking performance specifications for light-duty vehicle programs. Commercial vehicle leasing programs unbundle hardware from predictive maintenance subscriptions. Michigan's supplier corridor manages embedded software certification for ISO 26262 compliance.
Japan
METI industrial policy supports R&D intensity in integrated starter-generator architectures for hybrid powertrain exports. Domestic OEMs consolidate solenoid redesign cycles around 48V stop-start proliferation. Nagoya's automotive supplier ecosystem specializes in high-torque compact motor production.
India
BIS efficiency mandates under Bharat Stage VI implementation create regulatory tailwind for electronic ignition penetration in sub-4-meter segments. Cost-optimized starting system demand concentrates in Tamil Nadu and Maharashtra manufacturing zones. Chennai's automotive corridor anchors localization programs for 12V smart starter assemblies.
Automotive Starting System Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with full-system integrators commanding premium positioning in 48V architectures while component suppliers serve cost-sensitive replacement cycles. The vendor base organizes around three strategic archetypes: diversified automotive electronics conglomerates, powertrain-focused Tier-1 system integrators, and regional electrical component specialists. Consolidation pressure intensifies as software-defined functionality raises R&D minimums. Dominant competitive moves include strategic partnerships for 48V semiconductor sourcing and backward integration into rare-earth magnet supply.
Within the diversified electronics tier, Robert Bosch GmbH and Denso Corporation occupy positions exemplifying embedded software stack monetization beyond hardware replacement cycles. Mitsubishi Electric Corporation anchors the high-torque compact motor specialization segment. These three entities represent divergent strategic responses to integrated starter-generator architecture proliferation.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Valeo Group |
| Mitsuba Corporation |
| Hitachi Automotive Systems Ltd. |
| BorgWarner Inc. |
| Lucas Electrical Limited |
| Mahle GmbH |
| Others |
Value Chain & Pricing Dynamics
Captive magnet sourcing from Chinese rare-earth processors anchors supplier pricing power in integrated starter-generator architectures. Tier 1 system integrators leveraging in-house neodymium procurement command margin insulation against commodity volatility that squeezes component specialists dependent on spot-market magnet purchases.
Pricing Analysis
Distributor margins for aftermarket starter motor assemblies compress under price erosion from Chinese export competition, while direct-to-OEM contracts for 48V systems retain pricing power through embedded software bundling. Three-tier pricing structure across premium ISG configurations, standard stop-start modules, and economy 12V replacements reflects certification grade and thermal-cycle durability specifications. Fleet procurement departments exhibit lowest price sensitivity due to total-cost-of-ownership framing, whereas independent repair shops in Brazil and Mexico drive aggressive discounting on electronic ignition modules.
Supply Chain Analysis
India's phased domestic-content mandates under the PLI scheme for automotive components are reshaping sourcing patterns for solenoid and relay suppliers. Magnet procurement draws from Chinese rare-earth separation facilities, Japanese sintering operations, and Vietnamese downstream processing. Copper winding supply rests on Chilean concentrate and Indonesian smelter output. Single-source vulnerability concentrates in East Asian power semiconductor foundries serving 48V control electronics. Distribution runs through regional Tier 1 integrators with direct OEM relationships, bypassing traditional wholesale channels for smart system deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's MIIT carbon-compliance corridors and India's BIS efficiency-mandate zones offers cost-differential capture for suppliers qualifying architectures across both regulatory frameworks.
For Market Incumbents: Deepen backward integration into rare-earth magnet supply to defend margin position against commodity volatility threatening solenoid assembly profitability. Accelerate ISO 26262 functional safety certification investment to extend qualification timelines that disadvantage emerging competitors lacking embedded software validation infrastructure. For New Entrants and Emerging Players: Launch via direct aftermarket distributor partnerships in Brazil and Mexico where electronic ignition retrofit demand outpaces established supplier coverage. Target underpenetrated commercial vehicle fleet segments in India's sub-4-meter vehicle categories with cost-optimized stop-start modules engineered for Bharat Stage VI compliance. For Investors and Strategic Acquirers: Roll-up economics work for regional electrical component specialists because fragmented aftermarket distribution in Latin America and Southeast Asia lacks scale-efficient procurement consolidation. Monitor 48V mild-hybrid platform proliferation as inflection indicator for integrated starter-generator architecture substitution timelines threatening pure-play starter motor addressable market viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive neodymium sourcing insulates Tier 1 suppliers from Chinese export quota volatility affecting motor torque density specifications. |
| ISO 26262 Functional Safety Certification Investment | Eighteen-month validation timelines for starter control algorithms create qualification barriers protecting incumbent software stacks. |
| Platform Standardization for 48V Architectures | OEM adoption of belt-driven starter-generator modules consolidates sourcing decisions toward powertrain integration specialists. |
| Geographic Manufacturing Footprint Expansion | Tamil Nadu and Maharashtra localization captures India's BIS regulatory tailwind for electronic ignition penetration. |
| Software-Defined Vehicle Investment | Over-the-air calibration capability transforms hardware suppliers into recurring revenue service providers. |
Study Parameters
Coverage spans China, Germany, the United States, Japan, and India, with primary inputs from each market cluster through structured interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers. Secondary validation draws from vehicle production databases, EPA and NHTSA regulatory filings, MIIT policy circulars, and IHS Markit registration data. Bottom-up component demand modeling triangulates against top-down vehicle production forecasts.
Granularity-level framing applies vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions at the SKU level across the projection horizon. CAGRs derive from segment-specific volume trajectories weighted by voltage-class technology substitution curves. Forecast inputs incorporate stop-start system penetration rates by OEM program and thermal-management specification evolution under EU F-Gas Regulation phase-down schedules.
Several conditions sit outside the modeled scope, including speculative solid-state battery commercialization timelines and autonomous vehicle deployment rates that could alter vehicle utilization patterns. Forecasts reflect assumptions regarding ICE vehicle phase-out cadence and rare-earth supply chain stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Rain Sensor Market
Automotive Electrical & Electronics
Canada Automotive Electric Actuators Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
On-Board Charger Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Europe Automotive Pressure Sensor Market
Automotive Electrical & Electronics
Global Automotive on Board AC-DC Power Inverters Market
Automotive Electrical & Electronics
Middle East and Africa Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
Automotive Magnetic Sensor Market
Automotive Electrical & Electronics
Automotive Electronic Expansion Valve Market
Automotive Electrical & Electronics
Automotive Electronic Suspension System (ESS) Market
Automotive Electrical & Electronics
Automotive Digital Market