
 Automotive Lighting Actuators Market | 2026-2036
Automotive Lighting Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Lighting Actuators Market Analysis
The OEM-direct supply channel is rewriting how automotive lighting actuator contracts are awarded and fulfilled. HELLA GmbH & Co. KGaA leverages its vertical integration into lamp and electronics assembly to control specification-setting with German premium vehicle manufacturers. Continental AG anchors large-volume electromechanical actuator production across multiple European assembly plants. BOSCH GmbH competes on mechatronics integration density, bundling actuator control with broader chassis electronics architectures.
Automotive lighting actuators are precision electromechanical or hydraulic devices that convert electrical signals into mechanical displacement to adjust beam direction, intensity, or distribution in vehicle lighting systems, typically operating at voltages between 12V and 48V with response times under 100 milliseconds for adaptive functions. These components serve the primary industrial purpose of enabling dynamic light pattern adjustment to comply with road safety regulations and enhance driver visibility without dazzling oncoming traffic. Adaptive Actuators and Smart Actuators command the most attractive margin pools as OEMs specify self-leveling and matrix-beam functionality for premium vehicle segments, while Static Actuators remain the high-volume, price-competitive baseline across economy and mid-range platforms. Electromechanical technology dominates the technology dimension due to its compatibility with vehicle electrical architectures, though Optical actuation is gaining traction in next-generation digital light processing systems where micromirror arrays replace conventional mechanical movement.
NHTSA in the United States and ECE regulations in Europe mandate specific headlight beam patterns and adaptive capabilities that directly shape actuator performance specifications and validation protocols. The EU's General Safety Regulation intensifies these requirements by mandating automatic headlamp levelling and advanced front-lighting systems on new vehicle types. Stakeholders must monitor how cybersecurity standards for connected lighting systems, particularly UN R155 and ISO/SAE 21434, will expand compliance burdens for actuator control software and over-the-air update capabilities.
Market Dynamics
OEM procurement of adaptive headlight systems is intensifying as automakers chase NHTSA and ECE regulatory alignment for pedestrian safety, compressing actuator specification cycles from 36 months to 18 months.
Growth Catalysts
- ECE Regulation 48:Mandates for adaptive front-lighting systems in Europe are forcing actuator performance upgrades across German and Swedish vehicle platforms.
- Electromechanical platform compatibility:48V vehicle electrical architectures are expanding addressable actuator functions beyond legacy 12V limitations.
- German manufacturing clusters:Dense tier-1 supplier ecosystems in Baden-Württemberg and Lower Saxony are accelerating prototype-to-production timelines for smart actuator validation.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings are compressing margins on high-torque electromechanical actuator motors.
- Supply concentration in East Asian semiconductor foundries:MCU and driver IC dependency creates single-source vulnerability for actuator control modules.
- Hydraulic fluid thermal degradation:Temperature cycling limits below minus 40 degrees Celsius restrict optical actuator deployment in Nordic and Canadian markets.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives are attracting electromechanical actuator assembly investments for domestic OEM supply.
- Software-defined light distribution:Convergence of digital micromirror devices with solid-state lighting is opening specification control to semiconductor suppliers.
- Aftermarket retrofit channels:Independent service networks in the United States are sourcing adaptive leveling kits for legacy vehicle fleet upgrades.
Industry Challenges
- Mechatronics systems integration:Actuator control software must validate against UN R155 cybersecurity protocols, extending homologation timelines.
- Legacy 12V electrical architecture lock-in:Economy vehicle platforms resist 48V migration, fragmenting actuator voltage specification portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Lighting Actuators Market |
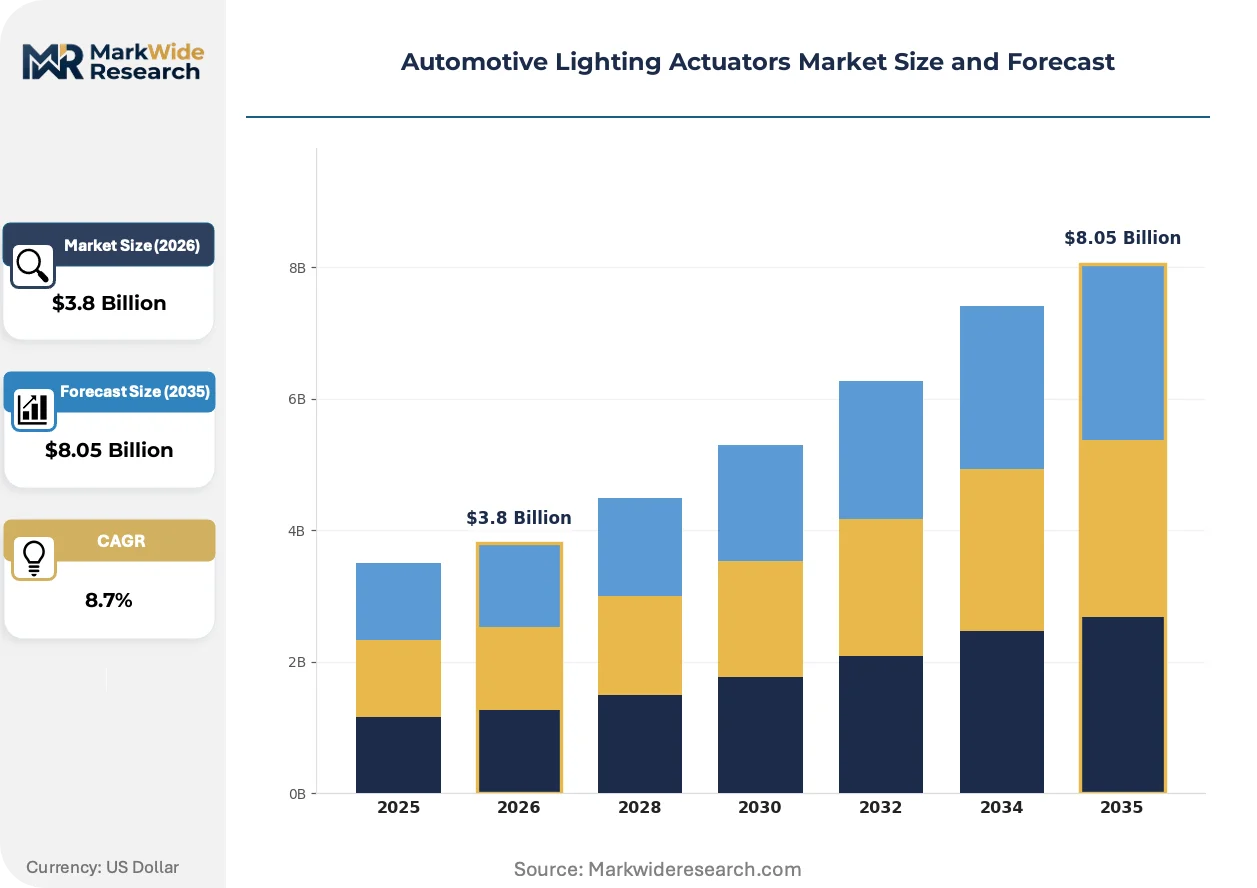
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Actuators, Dynamic Actuators, Adaptive Actuators, Smart Actuators Technology: Electromechanical, Hydraulic, Pneumatic, Optical Application: Headlights, Taillights, Turn Signals, Fog Lights End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators |
| Companies Covered | HELLA GmbH & Co. KGaA, Stanley Electric Co., Ltd., Continental AG, ZF Friedrichshafen AG, Magneti Marelli S.p.A, BOSCH GmbH, Valeo S.A., Osram Licht AG, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Lighting Actuators Market Emerging Trajectories
Digital light processing architectures are collapsing the mechanical complexity of beam steering, transferring specification power from electromechanical suppliers to semiconductor and software vendors.
Micromirror array technology converts electrical signals directly into optical beam modulation without mechanical displacement. Premium German and Japanese OEMs are specifying these systems for matrix-beam headlamps on 2026 model year vehicles. Solid-state optical actuation is rendering obsolete conventional stepper-motor and servo-motor platforms in high-resolution adaptive lighting applications.
NHTSA's 2023 final rule permitting adaptive driving beam systems in the United States eliminates the historical regulatory divergence with ECE markets. This harmonization reduces dual-validation burdens for suppliers serving both geographies. The United States market is accelerating ADB specification adoption, compressing the technology lag that previously separated American and European headlight performance tiers.
Fleet procurement of lighting systems is unbundling from complete vehicle contracts, with leasing companies and mobility operators negotiating direct actuator service agreements. This channel bypasses traditional tier-1 supply hierarchies. Germany and Japan are witnessing the strongest penetration of this procurement model, driven by premium electric vehicle subscription services requiring guaranteed headlight performance over contract terms.
Automotive Lighting Actuators Market Segmentation
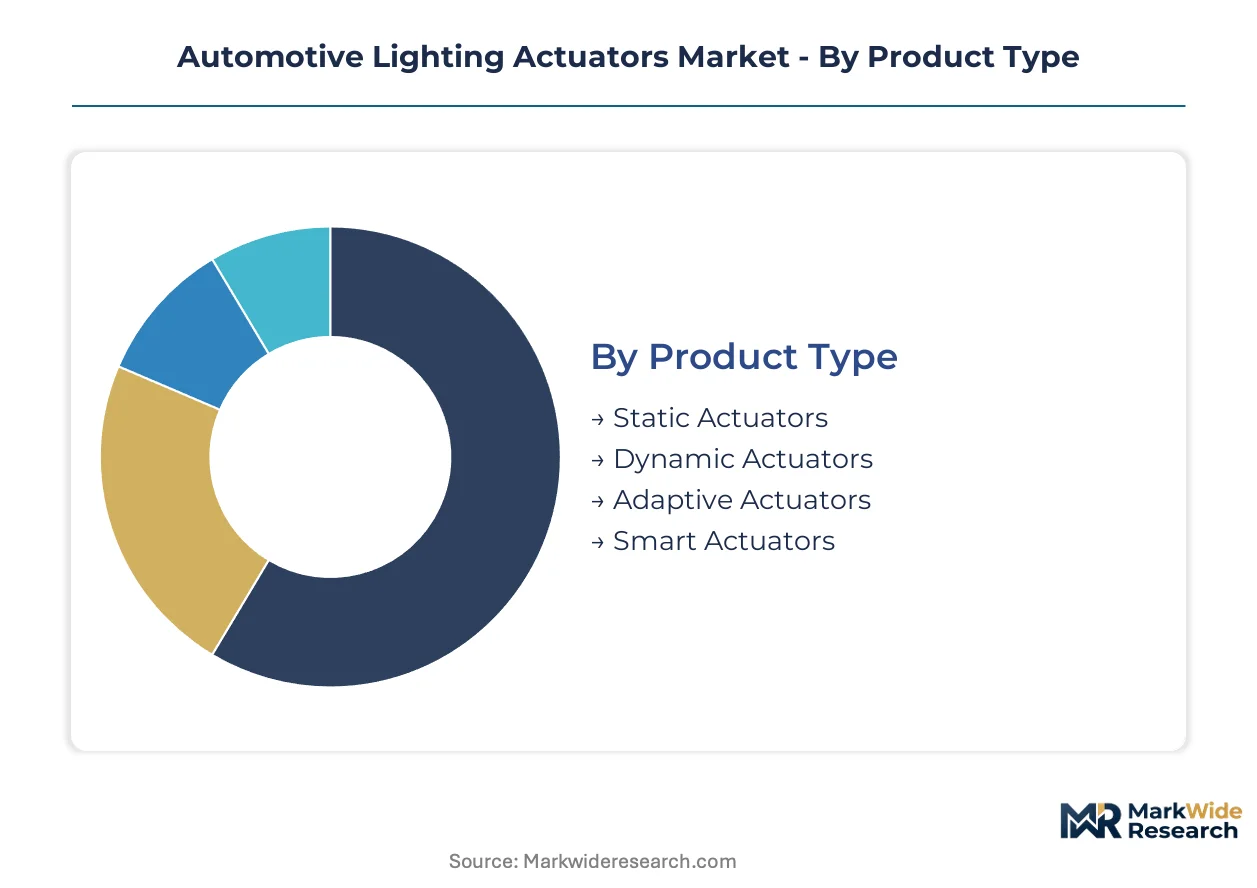
Segmentation in automotive lighting actuators determines service protocol complexity, spare parts inventory depth, and technical training requirements for aftermarket channels. Product type and technology dimensions dictate diagnostic equipment investment and warranty exposure for distributors.
Product Type:
After-sales service intensity varies sharply across actuator complexity tiers, with smart platforms requiring software-enabled calibration tools and static variants needing only mechanical replacement.
- Static Actuators:Fixed-position electromechanical devices with no real-time adjustment capability, specified for economy vehicle headlamp leveling. Demand concentrates in India's domestic OEM segment where cost minimization overrides adaptive functionality requirements.
- Dynamic Actuators:Motor-driven platforms enabling beam height adjustment based on vehicle load sensors. German premium manufacturers specify these for SUV platforms with variable cargo configurations, driven by ECE Regulation 48 automatic levelling mandates.
- Adaptive Actuators:Multi-axis electromechanical systems executing real-time beam pattern modification for curve illumination. Matrix-beam applications in Japanese luxury sedans are driving specification upgrades.
- Smart Actuators:Integrated sensor-actuator-control modules with CAN bus connectivity and over-the-air update capability. Fleet operators in the United States are negotiating direct service agreements for predictive maintenance coverage.
By volume, Static Actuators leads. By growth pace, Smart Actuators is expanding most quickly.
Technology:
Technology selection determines thermal management requirements, electromagnetic compatibility testing scope, and semiconductor content for actuator control modules.
- Electromechanical:Dominant platform using DC motors, stepper motors, and servo drives with rare earth magnet rotors. Baden-Württemberg manufacturing clusters in Germany anchor high-volume production for 12V and 48V vehicle architectures.
- Hydraulic:Fluid-powered actuation for high-torque headlamp adjustment in heavy commercial vehicles. Deployment faces thermal degradation constraints below minus 40 degrees Celsius in Nordic markets.
- Pneumatic:Compressed-air driven systems with limited precision, specified primarily for legacy truck platforms where electrical infrastructure is constrained. Replacement demand concentrates in North American aftermarket channels.
- Optical:Micromirror array technology eliminating mechanical displacement through solid-state beam modulation. Premium German and Japanese OEMs are specifying these for matrix-beam headlamps.
Electromechanical commands installed base dominance. Optical is gaining share fastest in premium platform specifications.
Application:
Application segmentation governs regulatory validation burden, with headlamp systems facing NHTSA and ECE homologation requirements absent for auxiliary lighting categories.
- Headlights:Primary adaptive lighting function requiring beam direction, intensity, and distribution control. NHTSA's adaptive driving beam rule harmonization is accelerating ADB specification adoption in the United States.
- Taillights:Sequential and dynamic signaling actuators with lower precision requirements than forward lighting. European OEMs are specifying animated turn indicators for brand differentiation.
- Turn Signals:Directional indicator actuation with standardized flash rates. Regulatory convergence across ECE and NHTSA jurisdictions reduces dual-validation costs.
- Fog Lights:Supplementary beam adjustment for weather-condition visibility enhancement. Specification concentration in German and Japanese premium platforms with all-weather driving mode integration.
Headlights absorb the majority of R&D investment. Taillights are climbing fastest on dynamic lighting feature penetration.
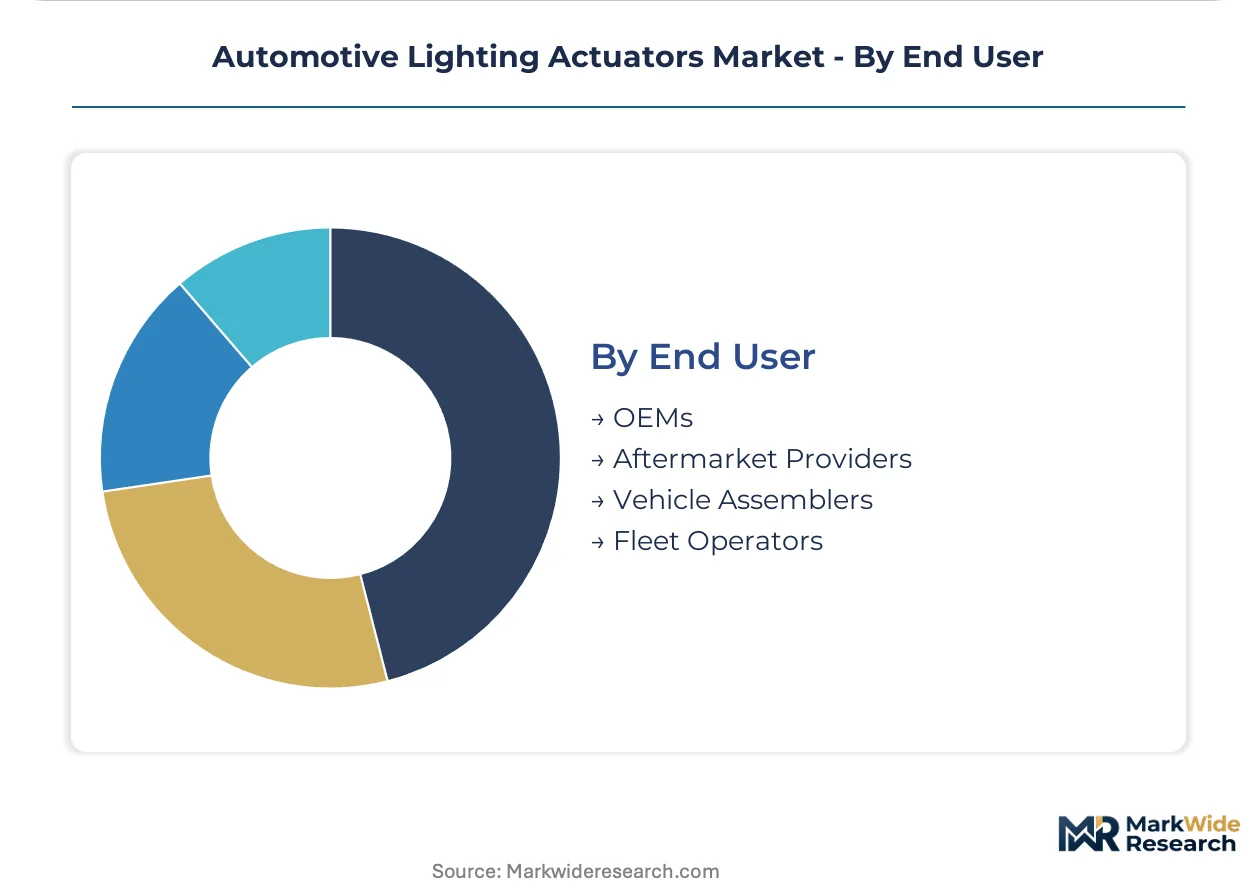
End User:
End user structure determines contract terms, volume commitment visibility, and technical support depth, with fleet operators demanding outcome-based performance guarantees.
- OEMs:Direct tier-1 supply relationships with 36-to-18-month specification cycles compressing under regulatory alignment pressure. German and Japanese vehicle manufacturers are consolidating actuator sourcing with vertically integrated lamp suppliers.
- Aftermarket Providers:Independent distribution channels for replacement actuators and retrofit kits. United States service networks are sourcing adaptive leveling kits for legacy fleet upgrades.
- Vehicle Assemblers:Contract manufacturing arrangements where lighting system integration is outsourced. India's PLI scheme for auto components is attracting electromechanical actuator assembly investments.
- Fleet Operators:Direct procurement bypassing tier-1 hierarchies with guaranteed performance contracts. Premium electric vehicle subscription services in Germany and Japan are driving this channel.
OEMs command volume leadership. Fleet Operators are expanding most quickly on unbundled procurement model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European logistics for electromechanical actuator components, while Japan's Nagoya port complex facilitates just-in-time delivery to Toyota City assembly plants. These infrastructure nodes underpin regional manufacturing density for automotive lighting systems.
Germany
ECE Regulation 48 mandates adaptive front-lighting systems across premium vehicle platforms, compressing supplier validation timelines. Baden-Württemberg manufacturing clusters in Stuttgart and Heilbronn concentrate electromechanical actuator production for 48V architectures. HELLA GmbH & Co. KGaA maintains specification-setting relationships with BMW and Mercedes-Benz through captive lamp assembly integration.
United States
NHTSA's 2023 adaptive driving beam final rule eliminates historical regulatory divergence with European markets, accelerating ADB adoption. Michigan's automotive corridor around Detroit anchors tier-1 supplier engineering centers for smart actuator development. Fleet operators in California and Texas are negotiating direct service agreements bypassing traditional supply hierarchies.
Japan
METI industrial policy supports solid-state lighting technology migration, shifting specification power toward semiconductor vendors. Toyota City and Nagoya manufacturing belts concentrate precision actuator assembly for matrix-beam headlamps. Stanley Electric Co., Ltd. and Denso Corporation occupy positions within the domestic keiretsu supply structure.
India
The PLI scheme for auto components attracts electromechanical actuator assembly investments from European and Japanese suppliers. Tamil Nadu and Gujarat state industrial corridors host domestic OEM supply contracts for static actuator platforms. Cost minimization requirements in the Maruti Suzuki and Tata Motors supply chains favor fixed-position devices over adaptive systems.
China
GB standards for vehicle lighting align gradually with ECE technical prescriptions, reducing dual-validation burdens for export-oriented suppliers. Yangtze River Delta manufacturing zones around Shanghai concentrate optical actuator prototyping for digital micromirror applications. Domestic EV manufacturers specify smart actuator modules with CAN bus connectivity for software-defined light distribution.
Automotive Lighting Actuators Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the electromechanical and optical supply base. The vendor structure concentrates around lamp-electronics-actuator bundled offerings from vertically integrated tier-1 suppliers, with independent actuator specialists occupying niche retrofit and commercial vehicle segments. Two strategic archetypes dominate: full-system providers controlling specification-setting with OEMs, and precision motor specialists supplying standardized platforms across multiple lamp integrators. Competitive moves center on backward integration into rare earth magnet supply chains and geographic expansion into India's PLI-subsidized assembly zones.
Among German-based platform integrators, HELLA GmbH & Co. KGaA, Continental AG, and BOSCH GmbH exemplify the system-tier archetype through their positions within lamp and electronics assembly ecosystems. These GmbH-structured entities represent the vertically integrated model that dominates premium vehicle specification cycles. Japanese Co., Ltd. structures including Stanley Electric Co., Ltd. and Denso Corporation occupy parallel positions within the keiretsu supply framework, while Valeo S.A. and Magneti Marelli S.p.A. represent European S.p.A. and S.A. formats with comparable integration depth.
| Leading Market Players |
|---|
| HELLA GmbH & Co. KGaA |
| Stanley Electric Co., Ltd. |
| Continental AG |
| ZF Friedrichshafen AG |
| Magneti Marelli S.p.A |
| BOSCH GmbH |
| Valeo S.A. |
| Osram Licht AG |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in optical actuator prototyping facilities across the Yangtze River Delta is compressing lead times for premium German and Japanese OEMs while simultaneously inflating spot pricing for matrix-beam validation slots. This utilization squeeze cascades into contract renegotiations where tier-1 suppliers extract volume commitments in exchange for fixed pricing on electromechanical platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract structures. Premium tiers command certification-grade validation against UN R155 cybersecurity protocols and ECE Regulation 48 homologation, while economy tiers strip out adaptive functionality for India's cost-minimized domestic OEM segment. Cost compression in static actuator categories is intensifying because Maruti Suzuki and Tata Motors procurement teams are consolidating supplier panels. Fleet operators in Germany and Japan exhibit the least price sensitivity due to outcome-based performance guarantees, whereas Indian vehicle assemblers maximize fixed-position device volumes.
Supply Chain Analysis
Rare earth magnet feedstock from Chinese processing facilities and Malaysian separation plants anchors motor rotor production for high-torque electromechanical actuators. MCU and driver IC sourcing draws from Taiwanese and South Korean semiconductor foundries, creating single-source vulnerability for actuator control modules. Tariff exposure on neodymium shipments is amplifying cost volatility for European tier-1 suppliers. Distribution runs through captive tier-1 logistics networks from Baden-Württemberg assembly plants to OEM sequencing centers, bypassing independent distributors for smart actuator platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM procurement consolidation is shifting buyer power toward vertically integrated lamp-electronics-actuator bundlers, fragmenting standalone actuator specialists into price-taker positions. Three stakeholder archetypes require distinct positioning responses.
For Market Incumbents: Insulate specification-setting relationships with BMW and Mercedes-Benz by deepening backward integration into rare earth magnet supply chains and accelerating 48V platform validation cycles. Emerging semiconductor vendors threaten electromechanical actuator margins through digital micromirror displacement. Priority levers include captive lamp assembly integration and cybersecurity certification investment against UN R155 protocols. For New Entrants and Emerging Players: India's PLI-subsidized assembly corridors in Tamil Nadu and Gujarat represent the most penetrable entry point for static actuator production serving Maruti Suzuki and Tata Motors supply chains. Aftermarket adaptive leveling kits for legacy United States fleets offer a second white-space channel. A direct OEM bypass model through fleet operator service agreements avoids tier-1 supply hierarchy lock-in. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across optical actuator sub-segments as solid-state beam modulation displaces mechanical platforms. Long-term viability over a multi-year horizon favors precision motor specialists with semiconductor packaging capabilities. Acquisition targets should demonstrate keiretsu or GmbH-structured supply relationships. The signal to watch is NHTSA enforcement patterns on adaptive driving beam compliance timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Secures rotor material cost stability against Chinese export quota volatility. |
| 48V Platform Validation Acceleration | Aligns electromechanical actuator portfolios with premium German OEM electrical architectures. |
| Cybersecurity Certification Investment | UN R155 compliance unlocks smart actuator contracts with fleet operators requiring OTA update capability. |
| Optical Actuator Prototyping Capacity Expansion | Captures matrix-beam specification power as digital micromirror technology displaces servo-motor platforms. |
| India PLI Corridor Manufacturing Footprint | Accesses cost-minimized static actuator demand from domestic OEM consolidation in Tamil Nadu and Gujarat. |
Methodological Framework
Cross-validation between primary interviews with tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations anchors the qualitative findings. Secondary validation draws from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive component suppliers, and ECE regulatory submission records. Bottom-up actuator shipment estimates triangulate against top-down vehicle production forecasts across the analysis window.
Calibration against historical adoption curves for adaptive front-lighting systems in European and Japanese premium segments shapes the projection framework. Segmentation dimensions span product type complexity tiers, electromechanical versus optical technology migration, headlamp versus auxiliary lighting applications, and OEM versus fleet operator end-use structures. CAGRs derive from fitted penetration curves for matrix-beam and smart actuator specifications, with vehicle class and propulsion architecture serving as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, rare earth commodity pricing, or semiconductor foundry utilization would shift the trajectory. Forecasts reflect documented assumptions on regulatory harmonization timing and technology substitution rates. Cross-checking against NHTSA enforcement data and ECE homologation throughput is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Battery Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Germany X by Wire Systems Market
Automotive Electrical & Electronics
On-Board Charger Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
Automotive Thermoelectric Generator Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market