
 Middle East and Africa Automotive DC-DC Converters Market | 2026-2036
Middle East and Africa Automotive DC-DC Converters Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Automotive DC-DC Converters Market Foresight
Electric vehicle fleets across commercial logistics are consolidating demand for high-efficiency DC-DC converters in the Middle East and Africa. Robert Bosch GmbH leverages its power electronics portfolio to anchor supply relationships with regional bus and truck electrification programs. Denso Corporation sustains manufacturing scale advantages through its existing thermal and electrical systems footprint in South Africa. Infineon Technologies AG differentiates through silicon carbide semiconductor expertise that supports higher switching frequencies in harsh ambient temperatures common across Gulf markets.
Automotive DC-DC converters are power electronic devices that transform one direct-current voltage level to another, typically stepping down high-voltage battery outputs to 12V or 48V rails for auxiliary systems, with switching frequencies commonly ranging from 100 kHz to over 500 kHz in modern designs. These converters regulate power delivery to lighting, infotainment, and battery management subsystems while maintaining isolation between high-voltage and low-voltage domains for safety compliance. Isolated converter architectures lead the product mix where galvanic separation is mandatory for passenger safety, while non-isolated buck topologies represent the fastest-growing category in cost-sensitive commercial vehicle retrofits. Switching technology dominates the technology landscape due to superior efficiency over linear alternatives, though resonant designs are capturing margin pools in premium electric vehicle platforms where reduced electromagnetic interference is critical.
The UAE's Ministry of Industry and Advanced Technology, South Africa's National Regulator for Compulsory Specifications, and Saudi Standards, Metrology and Quality Organization collectively shape product certification requirements for electromagnetic compatibility and thermal performance in automotive power electronics. These frameworks compel converter manufacturers to validate designs across wider temperature ranges and voltage transient conditions than specifications common in temperate markets. Stakeholders must monitor how Gulf Cooperation Council harmonization of EV charging infrastructure standards will cascade into DC-DC converter input voltage range and efficiency requirements for vehicles sold across the trade bloc.
Market Dynamics
Commercial logistics electrification across Gulf Cooperation Council member states is consolidating procurement power around high-efficiency power electronics, compressing supplier margins while accelerating technical specification upgrades for thermal performance and electromagnetic compatibility.
Growth Catalysts
- UAE EV Assembly Clusters:Dubai's industrial corridor is attracting converter manufacturers through proximity to bus and truck electrification programs, creating localized demand density that justifies dedicated production lines.
- Saudi Standards, Metrology and Quality Organization Certification Harmonization:Unified electromagnetic compatibility requirements across the Gulf Cooperation Council are reducing duplicate testing costs for suppliers serving multiple member economies.
- Silicon Carbide Semiconductor Adoption:Wide-bandgap materials enable switching frequencies above 500 kHz, reducing converter size and thermal management burden for vehicles operating in ambient temperatures exceeding 50°C.
Market Restraints
- Semiconductor Input Concentration:Silicon carbide wafer supply remains concentrated among East Asian foundries, exposing converter assemblers to allocation risk during capacity constraints.
- South Africa's National Regulator for Compulsory Specifications Compliance Costs:Extended validation timelines for electromagnetic compatibility certification delay product launches by 8-14 months relative to temperate-market equivalents.
- Linear Regulator Substitution in Cost-Sensitive Retrofits:Non-isolated buck topologies face price competition from simplified linear designs in commercial vehicle electrification programs prioritizing capital expenditure minimization over efficiency.
Strategic Opportunities
- Morocco's Emerging EV Component Ecosystem:Automotive manufacturing investments near Tangier-Med port infrastructure create geographic diversification options for suppliers seeking proximity to European export markets.
- Resonant Topology Convergence with Premium Platforms:Reduced electromagnetic interference requirements in luxury electric vehicles are opening margin pools for soft-switching converter architectures.
- UAE Ministry of Industry and Advanced Technology Incentive Frameworks:Domestic value-add requirements for government fleet electrification contracts are creating captive demand for local converter assembly operations.
Industry Challenges
- Power Electronics Talent Scarcity:Gulf markets lack sufficient analog design engineers with thermal management expertise for high-frequency magnetics optimization.
- Legacy 12V System Integration Complexity:Dual-voltage architectures requiring simultaneous 12V and 48V regulation increase control loop design complexity and fault-mode analysis burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Automotive DC-DC Converters Market |
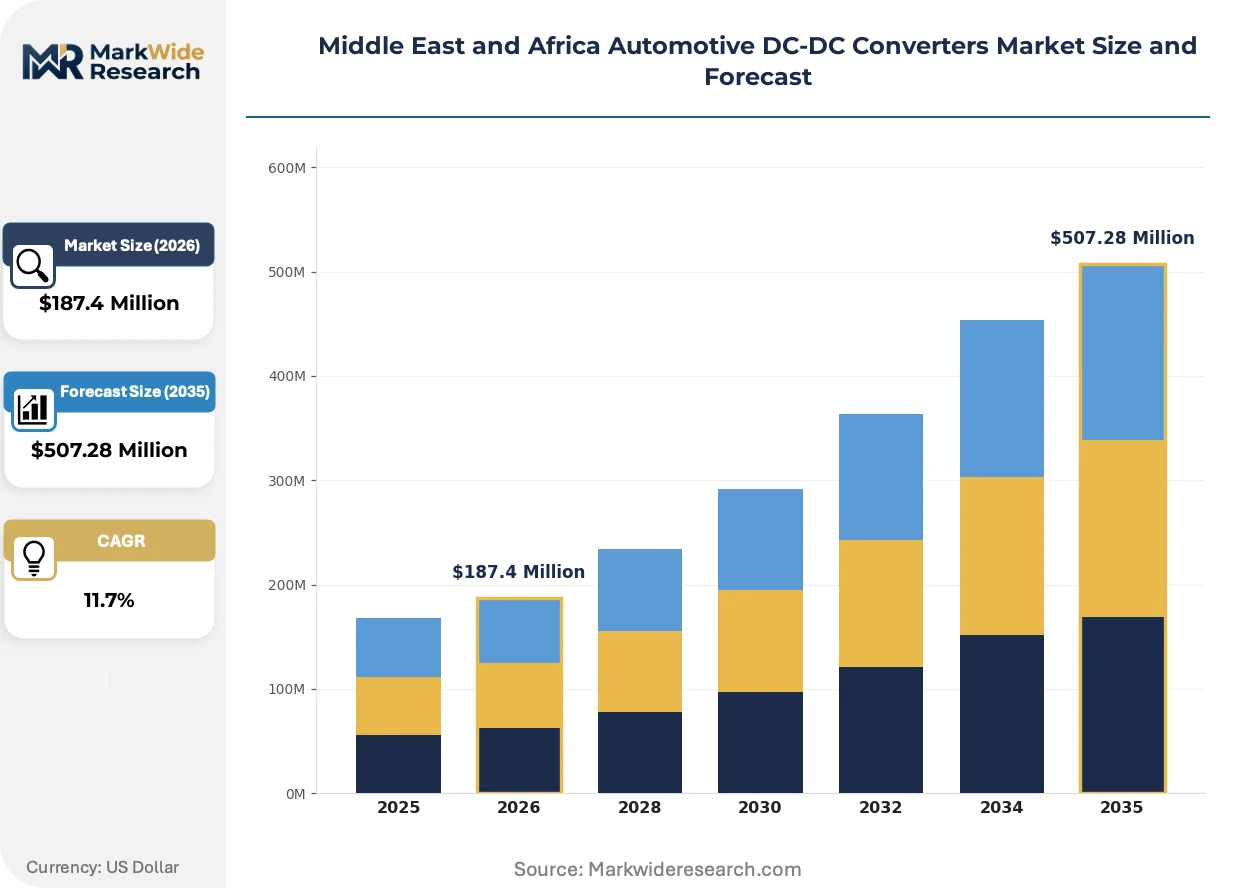
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolated, Non-Isolated, Buck, Boost Technology: Linear, Switching, Hybrid, Resonant End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Two-Wheelers Application: Power Supply, Lighting, Infotainment, Battery Management |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Infineon Technologies AG, STMicroelectronics, Texas Instruments Incorporated, BorgWarner Inc., Toyota Industries Corporation, Valeo, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Automotive DC-DC Converters Market Shifts & Advancements
Power semiconductor material transitions and procurement consolidation are restructuring competitive positioning in Middle East and Africa automotive DC-DC converters, with thermal performance emerging as the primary technical differentiator.
Silicon carbide MOSFETs are replacing silicon IGBTs in high-voltage input stages, enabling switching frequencies above 500 kHz while reducing switching losses by two-thirds. Regional bus electrification programs in the UAE and Saudi Arabia are adopting these devices aggressively to minimize cooling system mass. This frequency elevation is integrating magnetics miniaturization with thermal management system simplification, compressing converter package volumes by 30-40% relative to silicon-based designs.
South Africa's National Regulator for Compulsory Specifications is tightening electromagnetic compatibility test severity for conducted emissions above 150 kHz, exceeding baseline United Nations ECE R10 requirements. Converter manufacturers must now validate designs across wider temperature cycling ranges and voltage transient conditions. Commercial vehicle segments serving cross-border Southern African Development Community trade routes face the steepest compliance cost escalation.
Fleet operators in Dubai's logistics corridor are consolidating converter procurement through multi-year framework agreements with technical performance guarantees replacing transactional spot purchasing. Tier-1 suppliers are responding with dedicated aftermarket service networks and predictive maintenance telemetry integration. This contractual concentration is most visible in temperature-controlled freight electrification programs where downtime costs exceed converter replacement values.
Middle East and Africa Automotive DC-DC Converters Market Segmentation
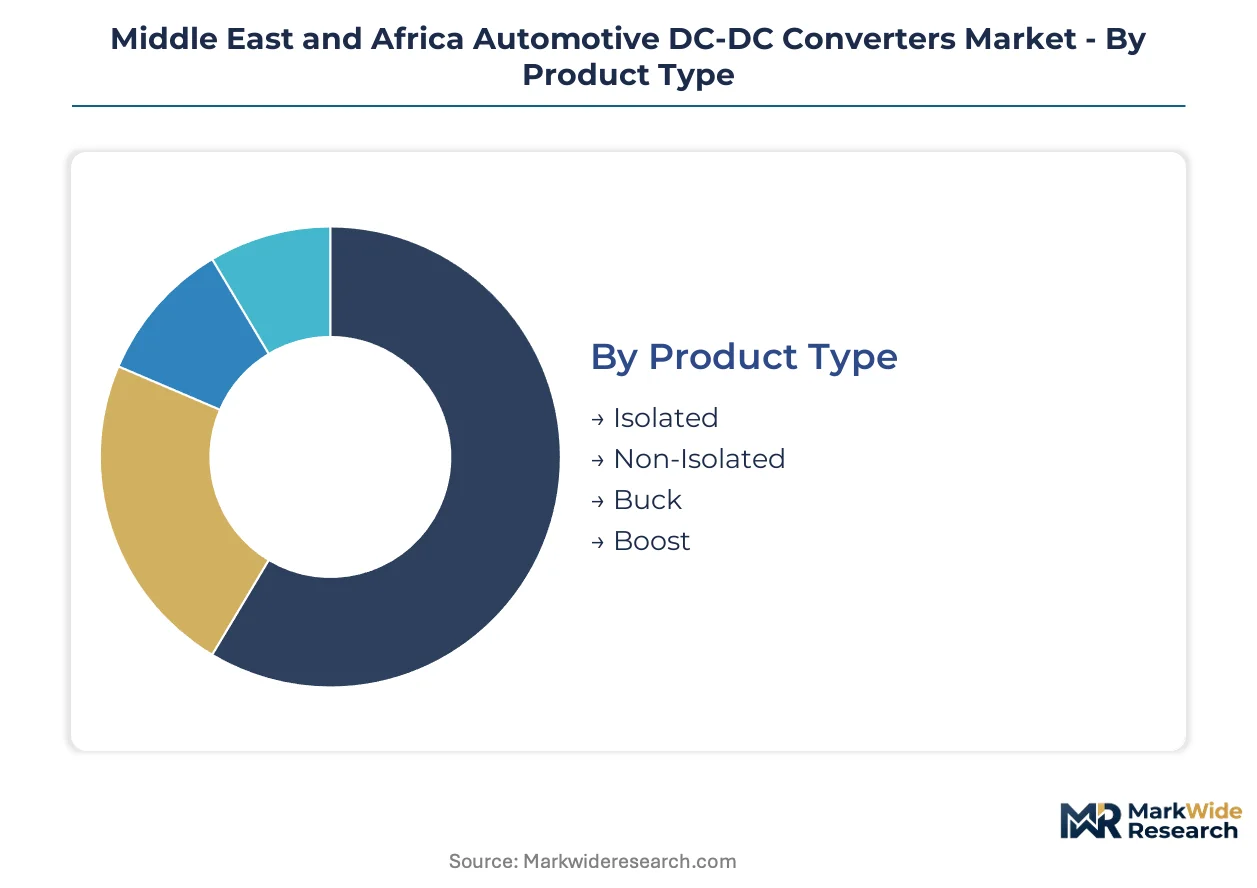
Converter procurement patterns in the Middle East and Africa diver sharply across voltage isolation requirements and thermal operating envelopes. Fleet operators prioritize electromagnetic compatibility certification levels over unit cost in high-ambient-temperature deployments.
Product Type:
Buyers differentiate primarily by safety isolation mandates versus retrofit cost constraints.
- Isolated:Galvanic separation between high-voltage battery domains and low-voltage auxiliary rails remains mandatory for passenger safety in OEM electric vehicle platforms. UAE bus electrification programs specify reinforced isolation for desert operating conditions where thermal cycling stresses dielectric barriers.
- Non-Isolated:Buck topologies without transformer coupling dominate commercial vehicle retrofit programs across Saudi Arabia's logistics corridors. Fleet operators accept reduced safety margins to minimize capital expenditure in temperature-controlled freight conversions where downtime costs exceed component replacement values.
- Buck:Step-down architectures stepping 400V or 800V battery outputs to 12V or 48V rails serve legacy auxiliary systems in hybrid platforms.
- Boost:Voltage elevation circuits support 48V mild-hybrid architectures requiring upward conversion from standard 12V reserves during transient load spikes.
Isolated converters lead volumes today; non-isolated architectures are gaining share fastest in commercial retrofit programs.
Technology:
Efficiency thresholds and electromagnetic interference tolerances segment procurement across fleet types.
- Switching:Pulse-width modulation designs operating above 100 kHz deliver superior efficiency over linear alternatives in high-power automotive applications. Dubai's electric bus operators specify switching frequencies above 500 kHz to reduce magnetics mass in cooling-constrained underhood installations.
- Resonant:Soft-switching topologies exploiting zero-voltage or zero-current transitions minimize switching losses and electromagnetic emissions. Premium electric vehicle platforms in the UAE's luxury segment adopt these architectures where reduced interference preserves infotainment system integrity.
- Linear:Series-pass regulators persist in cost-sensitive 12V auxiliary applications where efficiency penalties are acceptable for design simplicity.
- Hybrid:Combined linear-switching architectures optimize noise performance in sensitive measurement circuits within battery management subsystems.
Switching technology dominates installed base; resonant designs are climbing the fastest in premium platform specifications.
End User:
Vehicle electrification maturity and duty cycle intensity determine converter specification stringency.
- Electric Vehicles:Battery-dominant platforms require multiple DC-DC stages for high-voltage to low-voltage conversion, 48V mild-hybrid support, and auxiliary rail generation. South Africa's National Regulator for Compulsory Specifications mandates extended electromagnetic compatibility validation for these vehicles relative to temperate-market equivalents.
- Commercial Vehicles:Bus and truck electrification programs across the Gulf Cooperation Council consolidate procurement through multi-year framework agreements with technical performance guarantees.
- Passenger Vehicles:Internal combustion and hybrid platforms sustain demand for conventional 12V alternator replacement converters.
- Two-Wheelers:Low-power electric motorcycles and scooters utilize simplified non-isolated buck converters in price-sensitive urban mobility applications.
Commercial vehicles lead procurement volumes today; electric vehicle platforms are expanding most quickly across the analysis window.
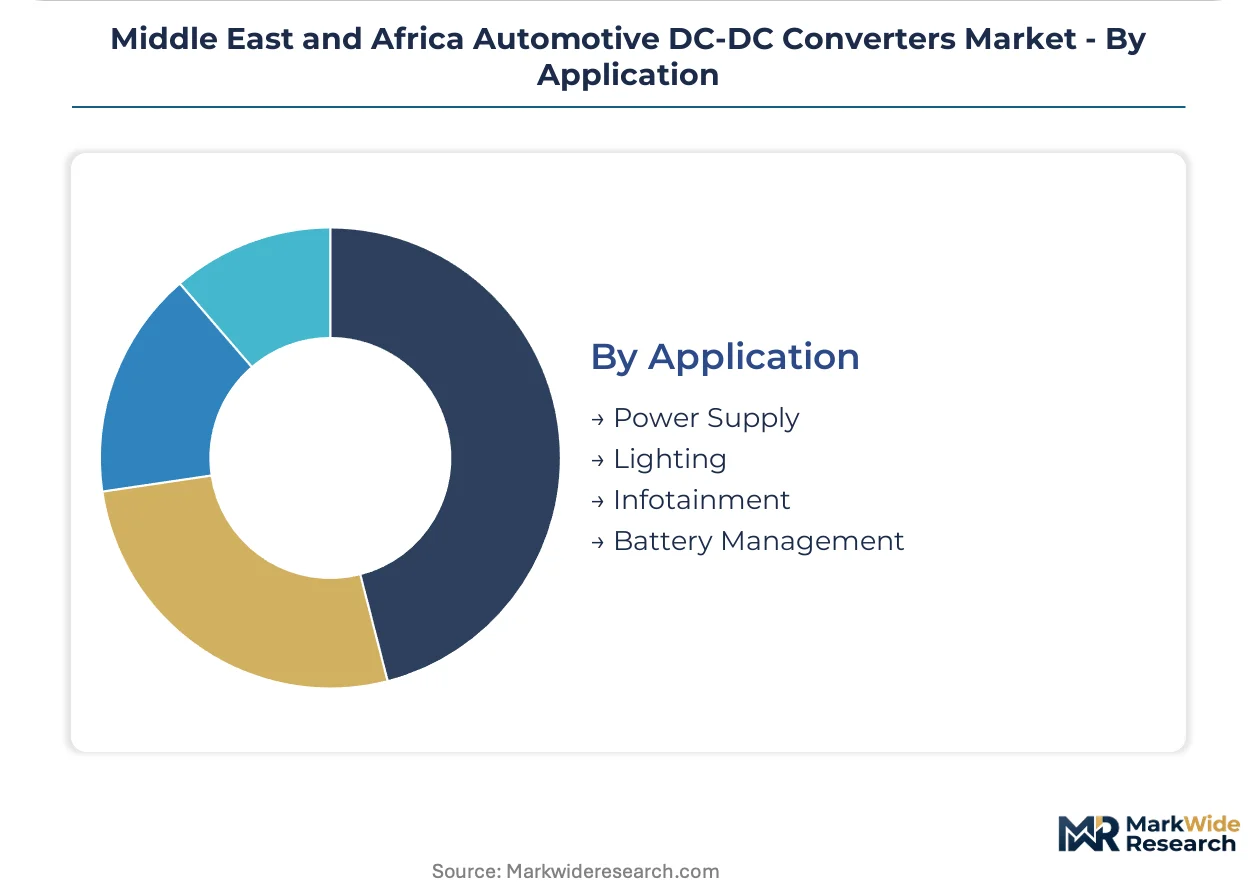
Application:
Power quality requirements and fault-tolerance needs stratify converter selection.
- Battery Management:Precision voltage regulation and isolation are critical for cell balancing and state-of-charge monitoring circuits where measurement accuracy directly impacts pack longevity and safety.
- Power Supply:Centralized conversion stages feeding multiple auxiliary subsystems prioritize efficiency and thermal management in high-temperature Gulf operating environments.
- Infotainment:Low-noise power delivery preserves signal integrity in touchscreen, audio, and navigation systems where switching ripple degrades user experience.
- Lighting:LED driver applications require stable current regulation across wide input voltage variations during engine cranking or regenerative braking transients.
Power supply applications lead volumes today; battery management systems are gaining share fastest with electric vehicle platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter manufacturers are relocating assembly operations toward jurisdictions with streamlined electromagnetic compatibility certification pathways, exploiting cost-of-compliance gaps between South Africa's extended validation timelines and Gulf Cooperation Council harmonized standards.
United Arab Emirates
Dubai's industrial corridor concentrates bus and truck electrification programs demanding high-frequency switching converters for desert operating conditions. The UAE Ministry of Industry and Advanced Technology mandates domestic value-add requirements for government fleet contracts, compelling suppliers to establish local assembly operations. Jebel Ali manufacturing zones host dedicated production lines serving GCC-wide procurement frameworks.
Saudi Arabia
Saudi Standards, Metrology and Quality Organization certification harmonization reduces duplicate testing costs for suppliers serving multiple GCC economies. Riyadh's logistics corridor electrification programs consolidate multi-year framework agreements with technical performance guarantees. The Eastern Province industrial cities attract power electronics investments through proximity to Red Sea export infrastructure.
South Africa
The National Regulator for Compulsory Specifications imposes extended electromagnetic compatibility validation timelines exceeding temperate-market equivalents by 8-14 months. Gauteng's automotive supplier cluster sustains manufacturing scale for thermal and electrical systems serving Southern African Development Community trade routes. Cross-border commercial vehicle segments face steepest compliance cost escalation.
Morocco
Tangier-Med port infrastructure anchors emerging EV component ecosystem investments targeting European export market proximity. The country's automotive manufacturing incentives attract geographic diversification from suppliers seeking alternative production bases. Casablanca-Settat region concentrates magnetics and power semiconductor assembly operations.
Israel
Technology development centers in Tel Aviv and Haifa specialize in wide-bandgap semiconductor design for high-temperature automotive applications. The country's national innovation authority funds power electronics research addressing Gulf market thermal management requirements. Defense-aerospace electronics expertise migrates toward commercial automotive converter architectures.
Middle East and Africa Automotive DC-DC Converters Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers establish dedicated production lines in Dubai industrial zones and Tangier-Med corridors to satisfy domestic content requirements. The vendor base concentrates around three strategic tiers: diversified automotive electronics conglomerates with full powertrain portfolios, semiconductor specialists leveraging silicon carbide expertise, and regional assemblers serving cost-sensitive retrofit segments. Competitive positioning hardens through backward integration into magnetics manufacturing and captive supply of wide-bandgap wafers.
Among diversified automotive suppliers, Robert Bosch GmbH and Continental AG exemplify scale-driven archetypes with established thermal systems footprints across multiple production geographies. Denso Corporation occupies a position within the integrated power electronics tier, while Infineon Technologies AG represents the semiconductor-specialist vector with wide-bandgap material expertise. STMicroelectronics and Texas Instruments Incorporated sit within the component supply tier feeding converter assembly operations. BorgWarner Inc. and Valeo exemplify tier-one automotive suppliers expanding power electronics portfolios through electrification program participation.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Infineon Technologies AG |
| STMicroelectronics |
| Texas Instruments Incorporated |
| BorgWarner Inc. |
| Toyota Industries Corporation |
| Valeo |
| Others |
Supply & Pricing Matrix
Fleet procurement consolidation across Dubai's logistics corridor is compressing converter margins while forcing suppliers to absorb extended electromagnetic compatibility validation costs. This demand-side pressure is restructuring supply relationships toward multi-year framework agreements with technical performance guarantees replacing spot purchasing.
Pricing Analysis
Distributor margins of 12-18% separate converter assemblers from direct OEM relationships in the Gulf Cooperation Council. Pricing stratifies across premium resonant topologies, standard switching architectures, and economy linear regulators based on certification grade and thermal performance tier. Cost compression in non-isolated buck segments is intensifying because fleet operators prioritize capital expenditure minimization over efficiency in retrofit programs. Commercial vehicle buyers exhibit highest price sensitivity; luxury electric vehicle platforms demonstrate lowest sensitivity due to electromagnetic interference tolerance requirements.
Supply Chain Analysis
Silicon carbide wafer supply rests on Japanese and Taiwanese specialty semiconductor foundries with limited alternative sourcing. Magnetics manufacturing draws from Chinese ferrite core producers and German winding equipment suppliers. Single-source vulnerability in wide-bandgap substrates exposes converter assemblers to allocation risk during capacity constraints. Distribution runs through Jebel Ali free zone hubs serving GCC-wide procurement frameworks with consolidated customs clearance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Saudi Standards, Metrology and Quality Organization certification harmonization is accelerating demand consolidation across the Gulf Cooperation Council trade bloc.
For Market Incumbents: Anticipate margin compression from silicon carbide supply allocation constraints by securing long-term wafer offtake agreements with East Asian foundries. Deepen backward integration into magnetics manufacturing to defend cost position against emerging Moroccan assemblers targeting European export markets. For New Entrants and Emerging Players: Capture white-space in South Africa's extended validation timeline gap by offering pre-certified converter platforms that reduce time-to-market for regional commercial vehicle retrofits. Target Morocco's Tangier-Med corridor with modular assembly operations serving EU-bound EV component demand. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor-specialist converter designers possessing captive silicon carbide expertise and established Gulf thermal validation capabilities. Monitor silicon carbide foundry capacity expansion announcements as the critical inflection signal for supply constraint easing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Long-term wafer offtake with Japanese foundries secures switching frequency leadership in 50°C ambient conditions. |
| GCC Certification Pre-Validation | Unified electromagnetic compatibility testing reduces duplicate compliance costs across Saudi, UAE, and Kuwait markets. |
| Morocco Manufacturing Footprint | Tangier-Med proximity enables European EV export access while diversifying beyond South African regulatory timelines. |
| Resonant Topology R&D Investment | Soft-switching expertise captures premium luxury vehicle margins where electromagnetic interference tolerance is critical. |
| Predictive Maintenance Telemetry Integration | Fleet operator data partnerships differentiate aftermarket service offerings in Dubai's temperature-controlled freight corridor. |
Research Methodology
Coverage spans the Middle East and Africa, with primary inputs from each major production cluster. The analysis combines structured interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and thermal systems specialists with secondary validation against vehicle production databases, IHS Markit registration data, customs trade records, and Gulf Cooperation Council regulatory filings. Bottom-up converter shipment estimates triangulate against top-down electric vehicle platform production forecasts.
Rate-of-change decomposition separates volume expansion from content-per-vehicle growth across propulsion architecture, vehicle class, isolation requirement, and regional production cluster dimensions. CAGRs derive from modeled unit economics and technology transition curves throughout the forecast period. Industry-specific inputs include silicon carbide adoption rates, electromagnetic compatibility test severity escalations, and fleet electrification procurement timelines.
Semiconductor supply disruptions, regulatory timeline extensions, and fleet electrification program delays are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about sustained Gulf Cooperation Council demand concentration and Moroccan manufacturing cost competitiveness. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market
Automotive Electrical & Electronics
Automotive Electric Actuator Market
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market
Automotive Electrical & Electronics
Stair Lift Motors Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Wireline Trucks Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Automotive EMI Shielding Market
Automotive Electrical & Electronics
Automotive E-Compressor Market