
 South America Passenger Vehicles Lubricants Market | 2026-2036
South America Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
South America Passenger Vehicles Lubricants Market Analytics
Aftermarket service revenue is narrowing toward synthetic and semi-synthetic formulations as passenger vehicle owners extend drain intervals. Petrobras leverages its integrated refinery network across Brazil to anchor supply security for domestic blenders. ExxonMobil Corporation competes through specialized high-mileage formulations tailored to Latin America's aging fleet profile. Chevron Corporation sustains regional presence via strategic bulk supply agreements with independent workshop chains.
Passenger vehicle lubricants comprise refined base oils blended with performance additives to reduce friction, dissipate heat, and prevent wear in internal combustion engines operating across varied altitude and temperature conditions. These formulations typically contain viscosity index improvers, detergents, and anti-wear compounds measured against SAE J300 and API SP specifications to ensure compatibility with modern engine architectures. Engine oil commands the dominant value share given universal application and frequent replacement cycles, while transmission fluid generates premium margins as dual-clutch and CVT penetration rises in Brazil and Argentina. Distribution through specialty stores and direct sales channels captures higher-margin synthetic grades, whereas supermarkets and online retail increasingly standardize conventional product access for price-sensitive consumers.
Brazil's ANVISA oversees chemical substance registration affecting additive package composition, while PROCONVE emission tiers align lubricant specifications with particulate filter protection requirements in newer vehicles. Argentina's national chemical regulator enforces import compliance standards that shape multinational formulation strategies for Mercosur trade bloc consistency. Stakeholders must monitor regulatory divergence between Brazilian biofuel blending mandates and Chilean carbon intensity benchmarks as these frameworks increasingly dictate base oil sourcing and additive chemistry decisions.
Market Dynamics
PROCONVE emission tiers and ANVISA chemical registration protocols are compressing formulation cycles across Brazil's lubricant value chain, forcing blenders to requalify additive packages against tighter particulate filter compatibility standards.
Growth Catalysts
- Synthetic formulation penetration:Fleet operators in Brazil's ride-hailing sector are extending drain intervals beyond conventional limits, creating pull for higher-grade base stocks and premium additive chemistries.
- PROCONVE P-8 alignment:Brazil's emission tier progression mandates enhanced after-treatment system protection, directly expanding demand for low-ash, low-SAPS engine oil specifications in newer vehicle cohorts.
- São Paulo corridor density:Vehicle concentration in Brazil's southeastern industrial belt sustains aftermarket service throughput that outstrips Andean market infrastructure by an order of magnitude.
Market Restraints
- Group II/III base oil import dependency:South American refiners lack hydrocracker capacity for high-quality base stock production, exposing blenders to freight and currency volatility from US Gulf Coast and Asian suppliers.
- ANVISA registration timelines:Chemical substance approval cycles for novel additive components extend 18-24 months, freezing formulation innovation windows and locking blenders into legacy package designs.
- Argentina import licensing friction:Mercosur trade bloc regulatory divergence forces multinational suppliers to maintain parallel inventory streams, elevating working capital requirements for cross-border distribution.
Strategic Opportunities
- Colombian Andean aftermarket:Bogotá and Medellín vehicle fleets operate under severe altitude stress that accelerates lubricant degradation, creating unmet demand for high-oxidation-stability formulations currently undersupplied by domestic blenders.
- Dual-clutch transmission fluid premiumization:Volkswagen Group and Stellantis assembly plants in Brazil are expanding DCT-equipped vehicle output, opening margin capture in a fluid category with limited qualified supplier bases.
- Workshop chain direct distribution:Independent service networks across Chile and Peru are consolidating purchasing through cooperative procurement platforms, bypassing traditional distributor markups for volume synthetic grades.
Industry Challenges
- Formulation chemist scarcity:Brazilian universities produce limited graduates with tribology and lubricant engineering specialization, forcing blenders to recruit from petrochemical process backgrounds and retrain for additive-package design.
- API SP/ILSAC GF-6 certification costs:Sequence engine test fees and hardware amortization for new specification qualification exceed mid-tier blender annual R&D budgets, consolidating innovation capacity among integrated majors.
- Legacy fleet service complexity:Argentina's aging vehicle parc spans API SJ through SN-plus requirements, forcing workshop inventory proliferation and elevating misapplication risk that drives warranty claims and customer churn.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Passenger Vehicles Lubricants Market |
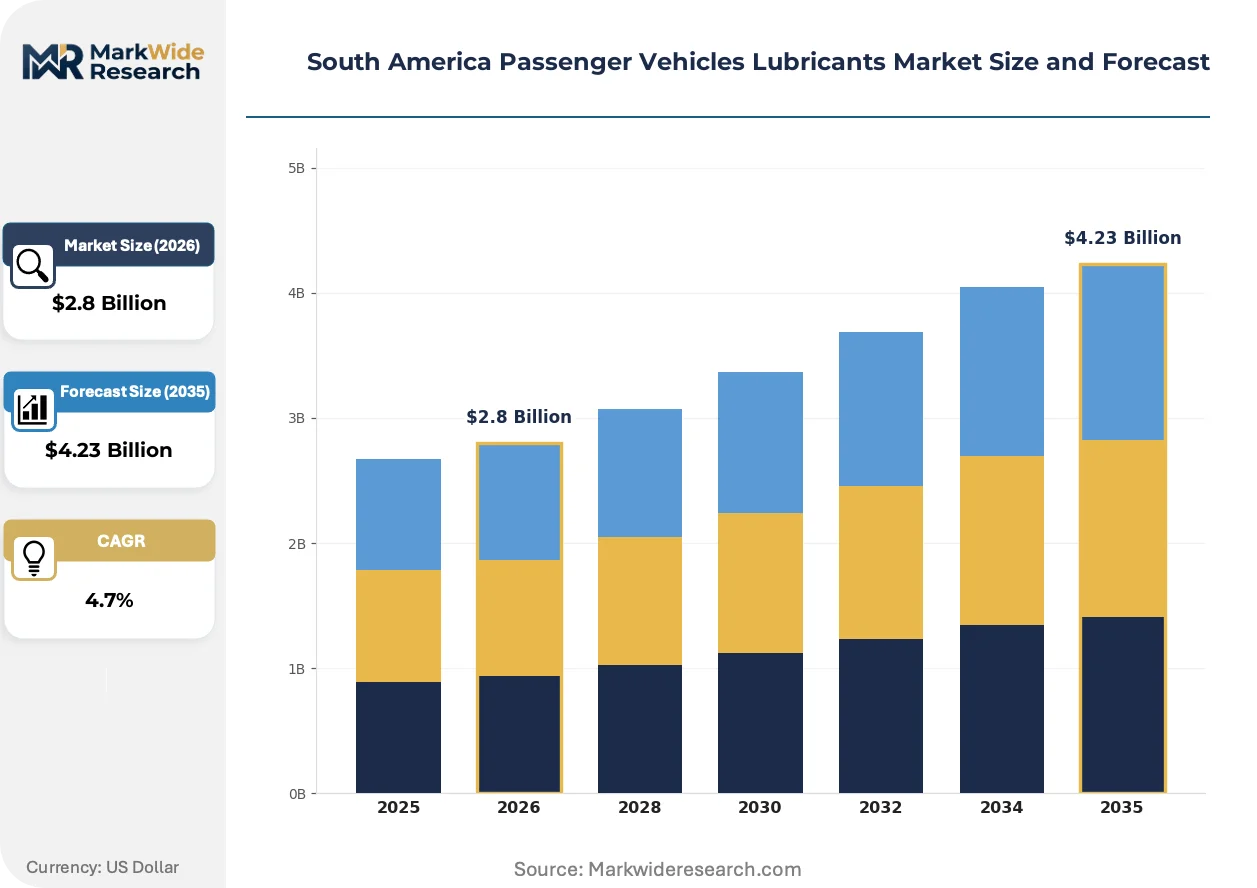
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Gear Oil End User: OEMs, Workshops, Retail Consumers, Aftermarket Providers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Application: Commercial Vehicles, Personal Cars, Light Trucks, SUVs |
| Companies Covered | Chevron Corporation, Petrobras, BP Plc (Castrol), PETRONAS Lubricants International, Iconic Lubrificantes, ExxonMobil Corporation, TotalEnergies, Gulf Oil International, Royal Dutch Shell Plc, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Passenger Vehicles Lubricants Market Evolving Landscape
Formulation chemistry and distribution architecture are diverging sharply across the region, with regulatory stringency in Brazil pulling ahead of Andean compliance baselines and procurement digitization compressing traditional channel economics.
Polyalkylene glycol (PAG) and ester-based synthetic base stocks are migrating from niche high-performance applications toward mainstream passenger vehicle service fills. Brazilian taxi fleet managers operating Toyota Corolla and Honda Civic hybrids above 150,000 kilometers are adopting these chemistries to mitigate thermal breakdown in stop-start urban duty cycles. The shift is migrating from premium synthetic positioning toward standard-service menu pricing, compressing margin structures for conventional mineral oil blenders.
ANVISA's alignment with OECD chemical hazard assessment protocols is accelerating additive package re-registration requirements for zinc dialkyldithiophosphate (ZDDP) variants and friction modifier chemistries. Brazilian blenders face 2025-2026 deadlines for dossier resubmission on legacy engine oil formulations, forcing portfolio rationalization toward fewer, higher-volume SKUs. The regulatory pressure falls most heavily on independent regional blenders lacking dedicated regulatory affairs staff, advantaging integrated suppliers with São Paulo-based compliance infrastructure.
Workshop procurement patterns are fragmenting across channel types, with consolidated fleet operators in Chile's Santiago-Valparaíso corridor negotiating direct supply contracts that bypass traditional lubricant distributors. Independent service bays respond through cooperative buying groups that aggregate synthetic volume for manufacturer-direct pricing. The behavioral shift is most visible in Brazil's Minas Gerais and Rio Grande do Sul states, where regional workshop associations have launched digital procurement platforms linking members to refinery-direct bulk supply.
South America Passenger Vehicles Lubricants Market Segmentation
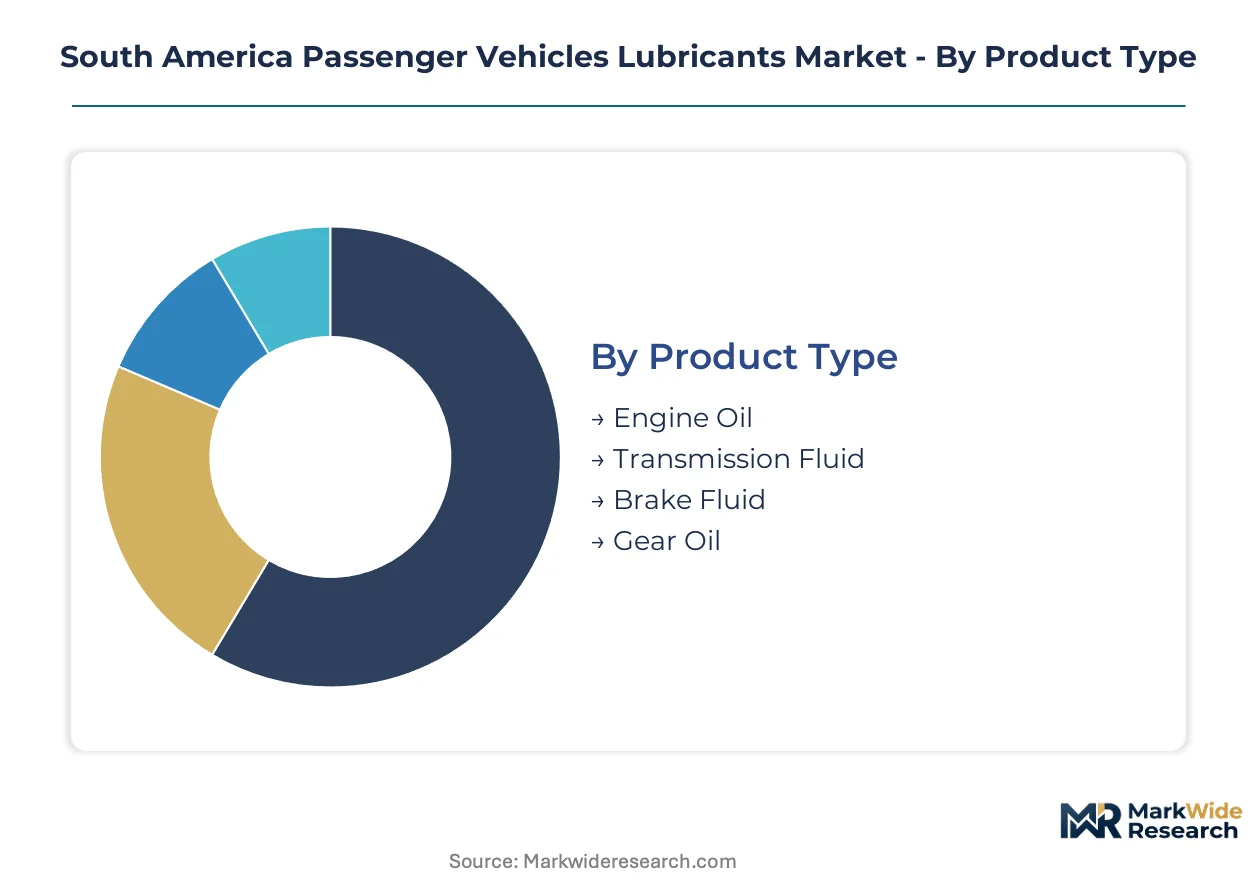
Segmentation in South American passenger vehicle lubricants reveals how formulation specifications, procurement authority, and channel economics fragment demand across distinct commercial pockets. Each dimension exposes different margin structures and competitive access points for suppliers navigating Brazil's regulatory complexity against Andean market heterogeneity.
Product Type:
Cost tier differentiation separates commodity mineral formulations from premium synthetics commanding three-to-four-fold price multiples in São Paulo service bays.
- Engine Oil:Formulations blend Group II/III base stocks with detergent-dispersant and anti-wear additive packages calibrated to API SP and ILSAC GF-6 specifications. Demand concentrates in Brazil's Minas Gerais and Rio Grande do Sul states, where independent workshop density sustains high-frequency drain interval turnover for conventional grades.
- Transmission Fluid:Dual-clutch and CVT-specific chemistries incorporate friction modifiers and shear-stable viscosity index improvers for wet-clutch compatibility. Volkswagen Group and Stellantis assembly plants in Brazil's ABC Paulista industrial corridor are pulling specialized ATF volumes as DCT-equipped vehicle output expands.
- Brake Fluid:Glycol-ether and silicone-based formulations meet DOT 3/4/5.1 boiling point specifications for hydraulic system integrity.
- Gear Oil:Hypoid gear lubricants with extreme-pressure additives protect differential and manual transmission components.
Engine oil holds installed capacity. Transmission fluid is rotating up the share rankings.
End User:
Procurement authority determines whether lubricant selection follows OEM engineering specifications or workshop inventory economics.
- OEMs:Factory-fill agreements require lubricant suppliers to meet exacting viscosity and volatility specifications for new vehicle warranty coverage. Brazil's São Paulo state corridor hosts the dominant share of assembly plant volume, with Petrobras and multinational suppliers competing through technical service contracts.
- Workshops:Independent service bays across Chile's Santiago-Valparaíso corridor and Peru's Lima-Callao metro area aggregate purchasing through cooperative procurement platforms. These buyers prioritize bulk synthetic pricing over brand loyalty, compressing distributor margins.
- Retail Consumers:Individual vehicle owners purchasing through supermarkets and auto parts chains for DIY maintenance.
- Aftermarket Providers:Fleet management companies and lease operators specifying lubricants for multi-vehicle service programs.
OEMs anchor specification authority. Workshops are gaining procurement leverage fastest.
Distribution Channel:
Channel selection locks in margin capture or sacrifices it to intermediaries depending on customer scale and geographic reach.
- Online Retail:E-commerce platforms aggregate price-transparent synthetic grades for comparison shopping. Brazil's Mercado Libre and specialized lubricant marketplaces are standardizing access to premium formulations for consumers outside major metro service infrastructure.
- Supermarkets:Hypermarket chains stock high-velocity conventional SKUs for emergency top-off purchases.
- Specialty Stores:Dedicated auto parts retailers capture enthusiast and high-mileage vehicle segments with technical consultation.
- Direct Sales:Refinery-direct bulk supply bypasses distributor markups for cooperative workshop networks.
Specialty stores hold technical credibility. Direct sales is climbing the fastest.
Application:
Vehicle duty cycle severity drives formulation durability requirements across altitude and temperature extremes.
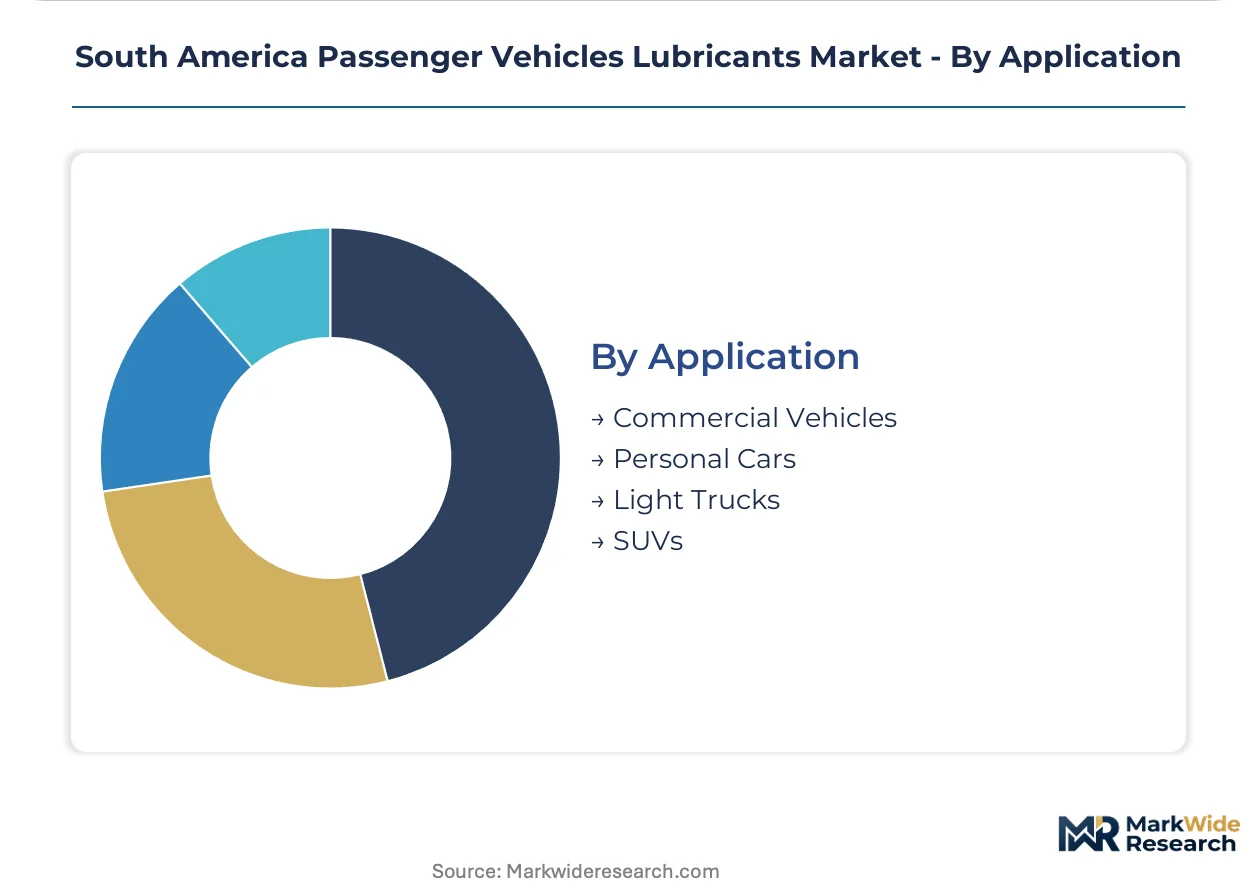
- Commercial Vehicles:Taxi and ride-hailing fleets in Bogotá's high-altitude basin subject lubricants to accelerated oxidation from stop-start thermal cycling. These operators are extending drain intervals through synthetic adoption, creating pull for high-TBN formulations.
- Personal Cars:Private passenger vehicles dominate volume but fragment across API specification generations from legacy SJ-rated holdouts to modern SP-compliant models. Argentina's aging parc spans this entire requirement spectrum.
- Light Trucks:Utility vehicle applications in Brazil's agricultural interior demand enhanced soot-handling capacity for diesel-electric hybrid powertrains.
- SUVs:All-wheel-drive transfer case and differential lubrication adds fluid complexity beyond standard engine service.
Personal cars hold volume concentration. Commercial vehicles is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's synthetic lubricant consumption patterns diverge sharply from Andean markets, where altitude stress and import dependency sustain mineral formulation dominance. Fleet operators in São Paulo extend drain intervals through premium base stocks, while Colombian taxi operators prioritize oxidation stability over interval length.
Brazil
Ride-hailing fleet managers operating Toyota Corolla hybrids above 150,000 kilometers are adopting PAG and ester-based synthetics for stop-start thermal cycling. ANVISA's 2025-2026 additive re-registration deadlines for ZDDP variants are forcing portfolio rationalization toward fewer, higher-volume SKUs. São Paulo state's ABC Paulista industrial corridor hosts Volkswagen Group and Stellantis assembly plants pulling specialized ATF volumes as DCT-equipped vehicle output expands.
Argentina
The national chemical regulator enforces import compliance standards that shape multinational formulation strategies for Mercosur trade bloc consistency. Aging vehicle parc spanning API SJ through SN-plus requirements forces workshop inventory proliferation and elevates misapplication risk. Buenos Aires and Córdoba metro areas concentrate aftermarket service infrastructure for legacy fleet complexity.
Chile
Independent service networks across the Santiago-Valparaíso corridor are consolidating purchasing through cooperative procurement platforms, bypassing traditional distributor markups for volume synthetic grades. Carbon intensity benchmarks increasingly dictate base oil sourcing decisions distinct from Brazilian biofuel mandates. Antofagasta mining logistics fleets create secondary demand for heavy-duty passenger vehicle lubricants in remote northern territories.
Colombia
Bogotá and Medellín vehicle fleets operate under severe altitude stress that accelerates lubricant degradation, creating unmet demand for high-oxidation-stability formulations currently undersupplied by domestic blenders. Stop-start thermal cycling in high-altitude basins degrades conventional mineral oils faster than coastal equivalents. Cali's emerging automotive service cluster is attracting refinery-direct bulk supply arrangements from Ecuadorian blenders.
Peru
Lima-Callao metro area workshop associations have launched digital procurement platforms linking members to regional bulk supply, fragmenting traditional distributor channels. Import licensing friction elevates working capital requirements for cross-border distribution from Ecuador and Chile. Arequipa's southern industrial corridor sustains lower synthetic penetration due to price-sensitive personal vehicle ownership patterns.
South America Passenger Vehicles Lubricants Market Competitive Landscape
Capability concentration sits with integrated majors possessing São Paulo-based compliance infrastructure; scale advantage sits with national oil companies leveraging captive refinery networks. The market structures around three tiers: integrated petrochemical majors with full additive package design capacity, national oil companies with backward integration into base stock supply, and independent blenders dependent on imported Group II/III feedstocks. Dominant competitive moves include direct sales channel expansion bypassing traditional distributors and portfolio rationalization toward fewer, higher-volume SKUs under regulatory pressure.
Within the integrated major tier, ExxonMobil Corporation and Chevron Corporation occupy positions defined by specialized formulation expertise and bulk supply agreements respectively. Petrobras anchors the national oil company segment through its integrated Brazilian refinery network. Among multinational lubricant specialists, BP Plc (Castrol) and Royal Dutch Shell Plc exemplify archetypes competing through technical service contracts and high-mileage portfolio positioning.
| Leading Market Players |
|---|
| Chevron Corporation |
| Petrobras |
| BP Plc (Castrol) |
| PETRONAS Lubricants International |
| Iconic Lubrificantes |
| ExxonMobil Corporation |
| TotalEnergies |
| Gulf Oil International |
| Royal Dutch Shell Plc |
| Others |
Value Network & Pricing Analysis
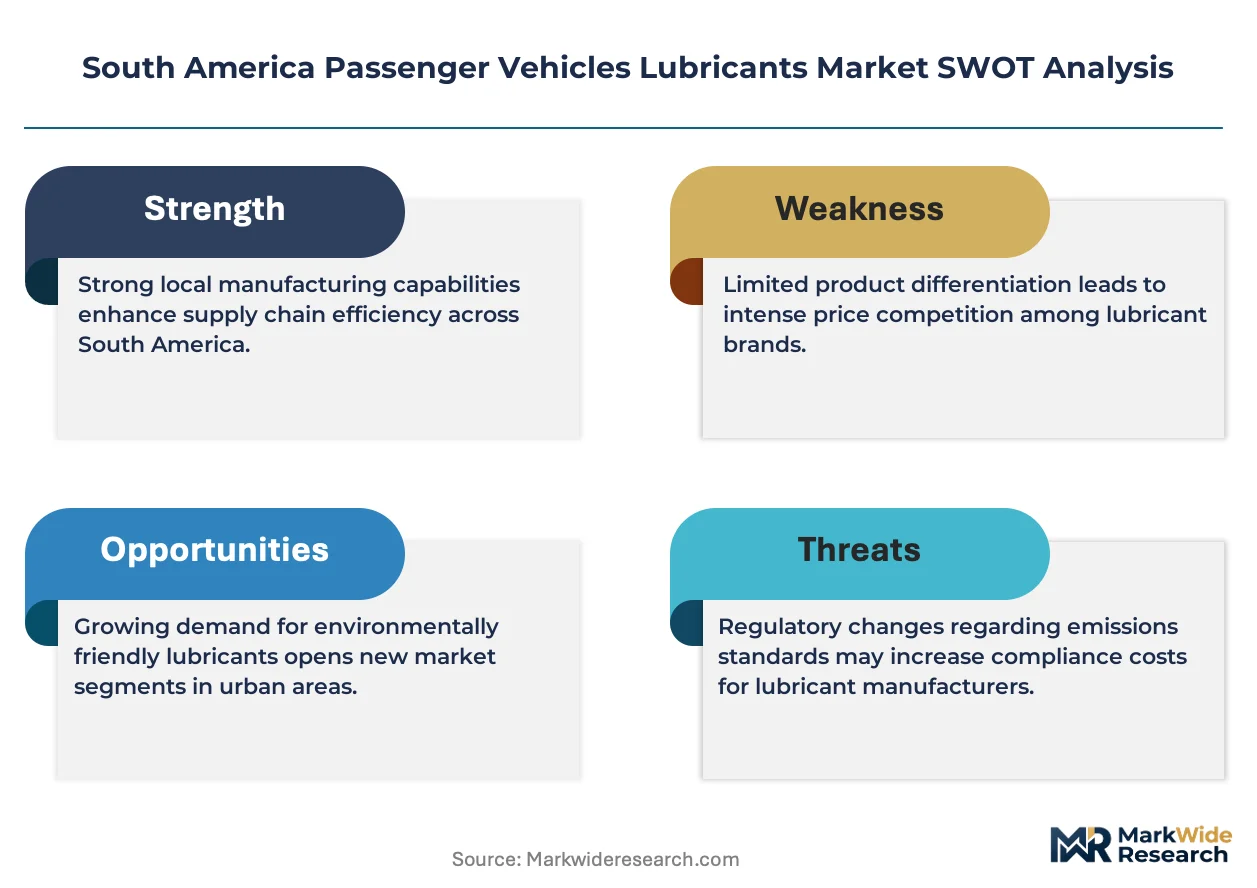
ANVISA registration timelines for novel additive components compress formulation innovation windows while simultaneously locking blenders into legacy package designs that determine both margin tier spreads and supply chain configuration. This regulatory chokepoint forces portfolio rationalization toward fewer, higher-volume SKUs that reshape procurement patterns across Brazilian and Andean markets.
Pricing Analysis
Long-term offtake contracts dominate synthetic grade procurement for São Paulo fleet operators extending drain intervals beyond conventional limits. Three-tier pricing structure across premium synthetics, semi-synthetic mid-grade, and mineral economy levels separates formulations by API certification tier and base stock quality. Cost compression in conventional mineral tiers intensifies because supermarket and online retail channels standardize price-transparent access for price-sensitive consumers. Individual DIY vehicle owners exhibit highest price sensitivity, whereas ride-hailing fleet managers prioritize total cost of ownership over per-liter pricing.
Supply Chain Analysis
Group II/III base stock feedstock draws from US Gulf Coast, South Korean, and Singaporean hydrocracker capacity that South American refiners lack domestically. Additive package components, viscosity index improvers, and friction modifier chemistries rest on Asian and European specialty chemical production. Single-source vulnerability concentrates in high-quality base oil import channels exposed to freight and currency volatility. Distribution runs through refinery-direct bulk supply for cooperative workshop networks, traditional distributor tiers for independent service bays, and digital procurement platforms fragmenting channel economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery electric vehicle powertrain substitution threatens long-term lubricant demand as OEM electrification roadmaps in Brazil and Chile accelerate zero-emission vehicle deployment. Incumbents must navigate this transition while defending core internal combustion engine service revenue.
For Market Incumbents: Entrench synthetic formulation leadership through backward integration into captive base stock supply and ANVISA-aligned compliance infrastructure that independent blenders cannot replicate. Accelerate high-mileage portfolio positioning for Latin America's aging fleet profile while building technical service contracts with Volkswagen Group and Stellantis assembly plants. Channel control through direct sales agreements with consolidating workshop cooperatives protects margin capture against distributor disintermediation.
For New Entrants and Emerging Players: Establish a beachhead in Colombia's high-altitude aftermarket where Bogotá and Medellín fleet operators face unmet demand for oxidation-stability formulations currently undersupplied by domestic blenders. Target Peru's Lima-Callao digital procurement platforms as entry vectors bypassing traditional distributor relationships. Dual-clutch transmission fluid qualification offers margin-rich positioning with limited qualified supplier bases serving Brazilian OEM factory-fill requirements.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated suppliers with São Paulo-based regulatory affairs capabilities and captive refinery networks. Long-term viability hinges on electrification transition speed and synthetic penetration ceiling in commercial vehicle segments. Acquisition target archetype: mid-tier blenders possessing ANVISA registration dossiers and established workshop channel relationships. Watch DCT-equipped vehicle production volumes at ABC Paulista assembly plants as inflection indicator for specialized fluid demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stock Supply | Captive hydrocracker capacity insulates blenders from US Gulf Coast freight volatility and currency exposure. |
| ANVISA Compliance Infrastructure Investment | Dedicated regulatory affairs teams compress additive re-registration timelines that freeze competitor innovation. |
| Direct Sales Channel Expansion | Refinery-direct bulk supply bypasses distributor markups for cooperative workshop networks in Minas Gerais. |
| Dual-Clutch Transmission Fluid Qualification | Limited qualified supplier bases serving Stellantis and Volkswagen Group factory-fill agreements capture premium margins. |
| High-Altitude Formulation Development | Oxidation-stability chemistries address Bogotá fleet degradation rates undersupplied by Colombian domestic blenders. |
Research Methodology
Operator-level perspectives from lubricant blending plant managers, fleet procurement officers at ride-hailing operators, ANVISA regulatory affairs specialists, and aftermarket workshop cooperative directors anchored the qualitative base. Secondary validation drew from ANVISA chemical registration databases, PROCONVE emission tier documentation, Brazilian customs trade statistics, and SEC filings of integrated petrochemical majors. Bottom-up triangulation across formulation volume estimates and top-down reconciliation against refinery capacity disclosures ensured analytical coherence.
Scenario-bracketing framed projections across regulatory acceleration, electrification penetration, and base oil import cost volatility scenarios. Segmentation dimensions modeled include product type tier, end-user procurement authority, distribution channel structure, and vehicle duty cycle severity across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by formulation value per liter and regional price point differentials. Industry-specific inputs encompassed PROCONVE P-8 alignment timelines and synthetic adoption rates in São Paulo commercial fleets.
Stress conditions across Brazilian real volatility, Group II/III base oil freight rates, and ANVISA registration approval delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OEM electrification roadmaps and fleet operator drain interval extension behavior. Cross-checking against vehicle parc age distribution data and aftermarket service bay density metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Brake Shoe Market
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Tire Mold Market
Automotive Parts
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Automotive Battery Frames Market
Automotive Parts
Air Filter for Automotive Market
Automotive Parts
Rammer Market
Automotive Parts
Egypt Passenger Vehicles Lubricants Market