
 Automotive Speed Sensor Market | 2026-2036
Automotive Speed Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Speed Sensor Market Outlook
The EU Green Deal is expanding compliance obligations across European automotive supply chains, forcing sensor suppliers to requalify materials and manufacturing footprints. Robert Bosch GmbH leverages its integrated semiconductor and sensor assembly operations to sustain cost positions in Hall Effect modules. Continental AG anchors European OEM programs through captive foundry partnerships and in-house magnetic sensing expertise.
An automotive speed sensor measures rotational velocity of wheels, transmission shafts, or electric motor rotors using magnetic, Hall Effect, optical, or inductive detection principles, typically outputting pulse-frequency signals processed by vehicle control modules for anti-lock braking and traction management. Hall Effect variants dominate volume shipments due to contactless operation and immunity to particulate contamination in wheel-hub environments. Digital technology segments capture widening margin pools as OEMs mandate SENT-protocol outputs and embedded diagnostic capabilities over legacy analog interfaces.
NHTSA stability-control mandates, ECE R13 braking regulations, and China's GB/T standards collectively dictate sensor accuracy thresholds, environmental testing protocols, and electromagnetic compatibility requirements that determine market access. EPA fuel-economy benchmarking and Euro 7 emission frameworks indirectly amplify sensor demand through powertrain electrification and precision driveline control. Stakeholders must monitor evolving functional-safety classifications under ISO 26262 as autonomous driving architectures impose ASIL-rated redundancy on speed sensing channels.
Market Dynamics
Electric vehicle powertrain architectures are multiplying sensor nodes per vehicle, forcing Hall Effect and magnetic encoder suppliers to recalibrate accuracy specifications for motor-speed feedback loops while managing thermal drift in high-voltage environments.
Growth Catalysts
- ECE R13 Braking Mandates:European braking-system regulations tighten wheel-speed sensor accuracy thresholds, compelling OEMs to upgrade from analog to SENT-protocol digital outputs across vehicle platforms.
- Powertrain Electrification:Battery electric vehicles deploy redundant speed sensing on each axle for torque-vectoring control, doubling sensor count compared to internal combustion architectures.
- Germany-Japan-China Clusters:Concentrated tier-1 supplier engineering centers in Stuttgart, Toyota City, and Shanghai synchronize specification roadmaps, accelerating platform-standard adoption.
Market Restraints
- Rare Earth Magnet Dependency:Neodymium and dysprosium supply chains concentrate in Chinese processing facilities, exposing Hall Effect sensor producers to input cost volatility and export restriction risk.
- ISO 26262 Certification Burden:Functional-safety documentation requirements for ASIL-rated speed channels extend qualification timelines by 18-24 months, freezing out mid-tier suppliers lacking dedicated safety engineering teams.
- Optical Encoder Substitution:High-resolution optical speed sensing is displacing magnetic solutions in premium EV motor applications where electromagnetic immunity requirements are less severe.
Strategic Opportunities
- India Automotive Manufacturing:PLI scheme incentives for electric vehicle production are drawing sensor suppliers to establish local calibration facilities serving Maruti Suzuki and Tata Motors programs.
- Autonomous Redundancy Architectures:SAE Level 3+ driving systems mandate dual-channel speed validation, creating incremental demand for physically separated sensor installations per wheel hub.
- EU Green Deal Compliance:Carbon-border adjustment mechanisms reward suppliers with renewable-powered semiconductor foundries, favoring European magnetic-sensing assembly operations.
Industry Challenges
- Embedded Software Competency Gap:SENT-protocol implementation and diagnostic algorithm development require firmware engineering capabilities scarce among legacy mechanical sensor houses.
- Legacy Platform Integration Friction:Analog-output speed sensors in existing vehicle architectures resist retrofit to digital bus systems without controller hardware redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Speed Sensor Market |
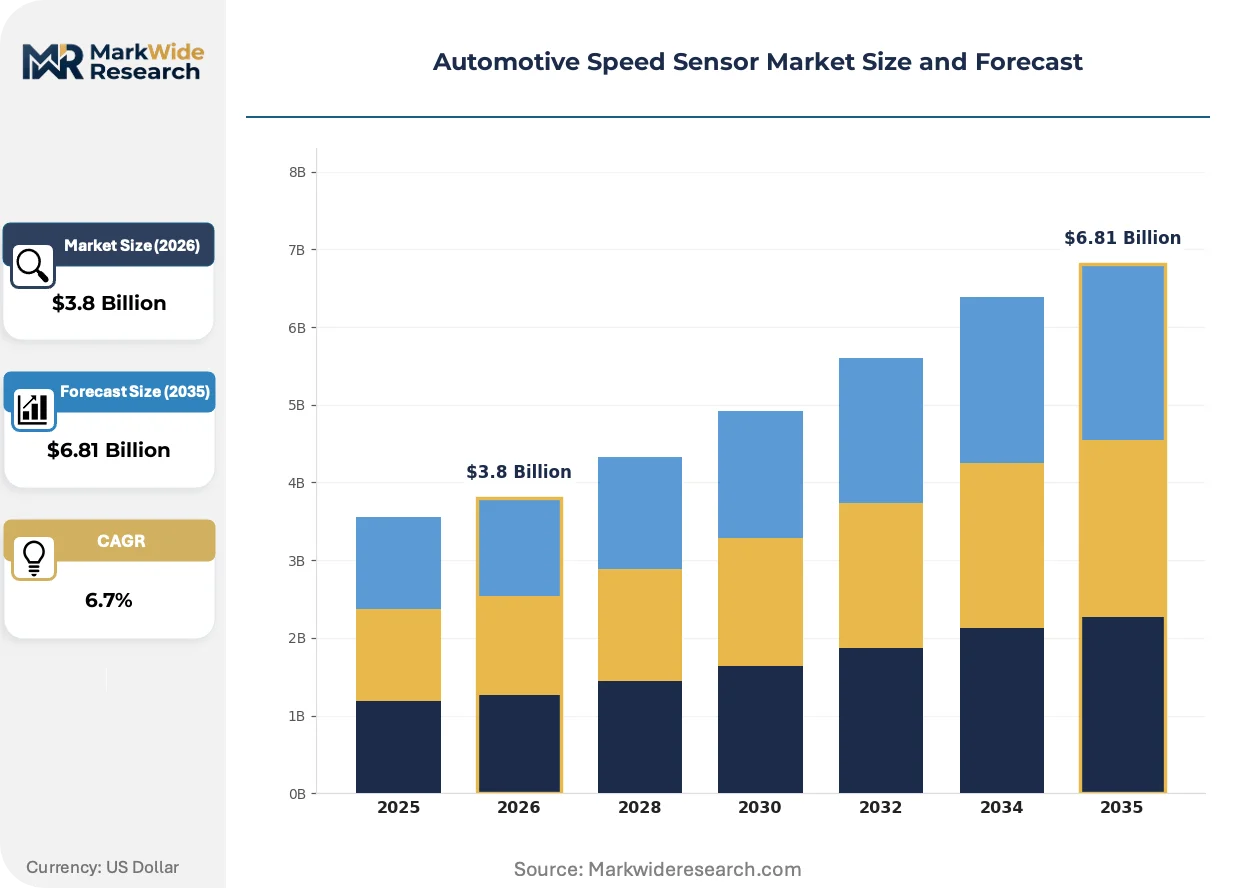
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic, Hall Effect, Optical, Inductive Technology: Analog, Digital, Wireless, Embedded End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Suppliers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles |
| Companies Covered | HELLA GmbH & Co. KGaA, NXP Semiconductors NV, Robert Bosch GmbH, Hitachi Metals Ltd., Allegro MicroSystems Inc., Continental AG, ZF Friedrichshafen AG, Melexis NV, DENSO CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Speed Sensor Market Strategic Shifts
Magnetic sensing architectures are bifurcating between cost-optimized Hall Effect modules for mass-market braking systems and high-fidelity inductive encoders for precision motor control, with interface standardization emerging as the decisive competitive variable.
TMR (tunnel magnetoresistance) sensing is electrifying wheel-speed detection by delivering microsecond response times and superior temperature stability compared to conventional Hall elements. Tier-1 brake system suppliers in Germany and Japan are adopting TMR for next-generation ESC platforms. This transition is compressing margin structures for legacy Hall Effect producers unable to fund thin-film magnetic stack investments.
NHTSA's updated FMVSS 126 stability-control standards are mandating degraded-mode performance verification, requiring speed sensors to maintain calibrated output during partial magnetic interference. Brake system integrators must now submit extended environmental test matrices. Heavy-duty truck applications face the steepest compliance cost increases due to wider operating temperature ranges.
Consolidated procurement by platform engineering teams is replacing discrete component sourcing, with OEMs specifying complete wheel-hub sensor modules rather than standalone sensing elements. Tier-1 suppliers in China are capturing this value shift through integrated bearing-sensor assemblies. This pattern is most pronounced in Volkswagen Group and Geely Holding vehicle programs.
Automotive Speed Sensor Market Segmentation
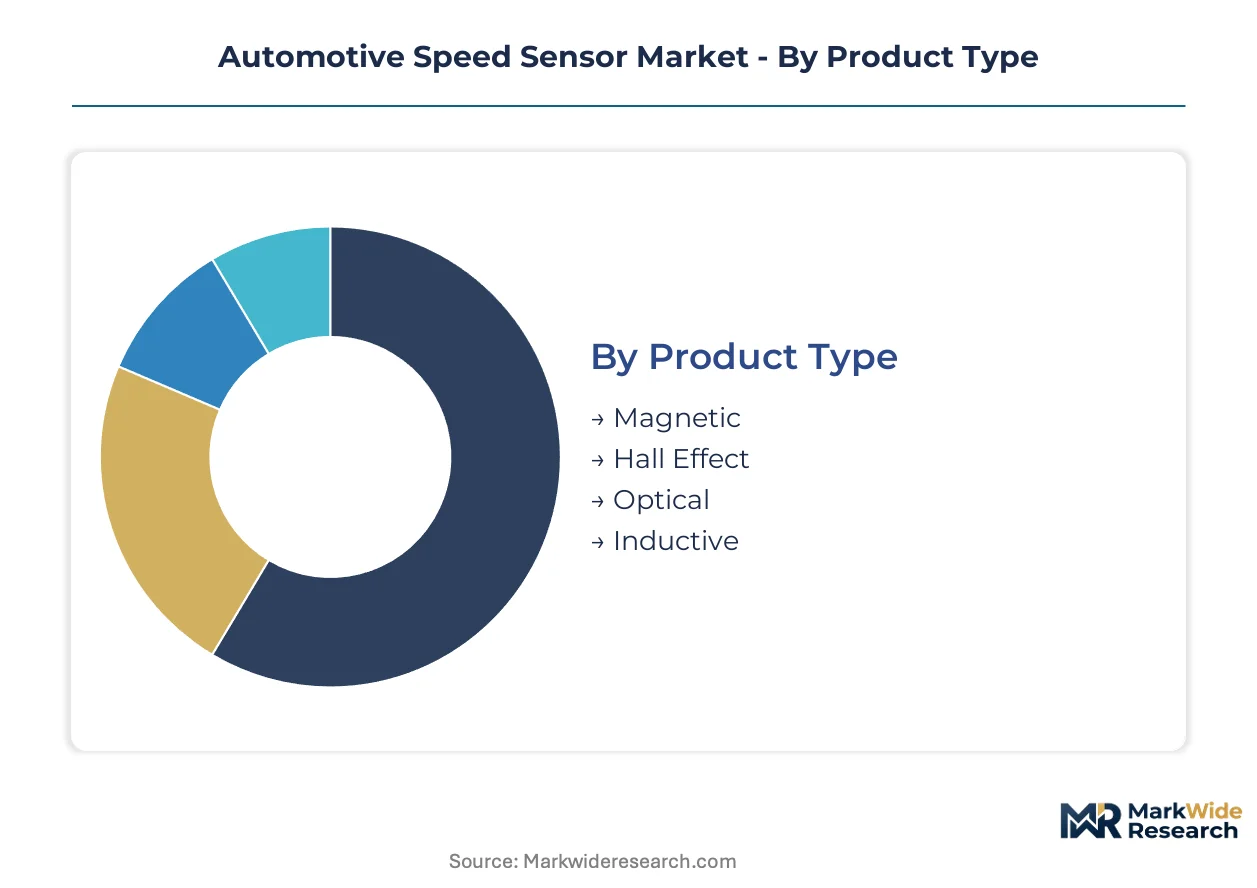
Automotive speed sensor segmentation reflects divergent technical requirements across braking, powertrain, and autonomous driving architectures. Procurement patterns split between cost-optimized wheel-speed modules for mass-market platforms and precision motor encoders for electrified drivetrains. Understanding these divides enables suppliers to align R&D spending with margin concentration zones.
Product Type:
Hall Effect variants dominate unit shipments while magnetic and optical solutions capture premium positioning in distinct application tiers.
- Hall Effect:Contactless magnetic field detection delivers particulate immunity in wheel-hub environments where debris exposure is constant. NHTSA-mandated electronic stability control programs in the United States and ECE R13 braking regulations across Germany, France, and Italy sustain procurement volumes for these modules. Thermal drift challenges intensify as electrified powertrates push operating temperatures higher.
- Magnetic:Variable reluctance architectures leverage toothed target wheels and coil windings for cost-sensitive ABS applications. Demand concentrates in commercial vehicle platforms serving Indian and Brazilian markets where durability requirements exceed precision needs. Rare earth magnet supply exposure through Chinese processing facilities creates input cost volatility.
- Optical:Photoelectric detection achieves sub-arcminute resolution for precision motor feedback in premium EV drivetrains.
- Inductive:Eddy-current principles enable high-temperature operation without magnetic materials in heavy-duty transmission applications.
Mature deployment sits with Hall Effect. Newer deployment is concentrated in Optical.
Technology:
Interface standardization separates legacy analog installations from digital protocol adoption mandated by functional safety requirements.
- Digital:SENT-protocol outputs with embedded diagnostic capabilities satisfy ISO 26262 ASIL-rated redundancy requirements for autonomous driving architectures. OEM specification roadmaps from Stuttgart, Toyota City, and Shanghai engineering clusters are synchronizing on digital bus integration. Firmware competency gaps among legacy mechanical sensor houses constrain supplier participation.
- Analog:Pulse-frequency voltage outputs persist in existing vehicle architectures resisting controller hardware redesign for digital retrofit. Cost optimization priorities in emerging market vehicle platforms sustain procurement volumes. Margin compression accelerates as digital alternatives achieve cost parity at scale.
- Wireless:RF-based transmission eliminates wiring harness complexity in rotating assemblies and sealed enclosures.
- Embedded:Integrated microcontroller units enable edge processing of diagnostic algorithms and self-calibration routines.
Volume concentration favors Analog. Capability investment flows to Digital.
End User:
Procurement authority is consolidating toward platform engineering teams specifying complete module assemblies rather than discrete sensing elements.
- Tier-1 Suppliers:Brake system integrators and driveline module manufacturers capture value shift through integrated bearing-sensor assemblies. Volkswagen Group and Geely Holding programs in Germany and China exemplify consolidated sourcing patterns. Calibration facility proximity to OEM headquarters determines competitive positioning.
- OEMs:Direct specification of speed sensing channels occurs in proprietary electric motor and battery management system development. Vertical integration into semiconductor and magnetic sensing operations at Robert Bosch GmbH illustrates captive supply strategies. Functional safety documentation burdens favor established safety engineering organizations.
- Aftermarket Suppliers:Replacement demand for failed wheel-speed sensors serves vehicle parc maintenance in high-mileage operating environments.
- Vehicle Assemblers:Final integration responsibility includes sensor mounting verification and signal validation during production line testing.
Specification authority concentrates with Tier-1 Suppliers. Direct OEM engagement expands in electrified powertrain domains.
Application:
Sensor count per vehicle diverges sharply between internal combustion architectures and battery electric platforms with redundant axle monitoring.
- Electric Vehicles:Torque-vectoring control and motor-speed feedback loops demand redundant sensing on each axle, doubling node count versus conventional drivetrains. China's GB/T standards and EPA fuel-economy benchmarking indirectly amplify demand through powertrain electrification mandates. High-voltage electromagnetic environments stress conventional magnetic sensing architectures.
- Passenger Vehicles:Electronic stability control and anti-lock braking systems represent baseline sensor penetration across all volume segments. ECE R13 accuracy thresholds compel analog-to-digital upgrades in European markets. Platform standardization across Germany-Japan-China engineering clusters accelerates specification convergence.
- Commercial Vehicles:Wide operating temperature ranges and severe-duty cycles impose extended environmental test matrices for FMVSS 126 compliance.
- Two-Wheelers:Cost-constrained ABS implementations in emerging markets drive demand for simplified Hall Effect modules.
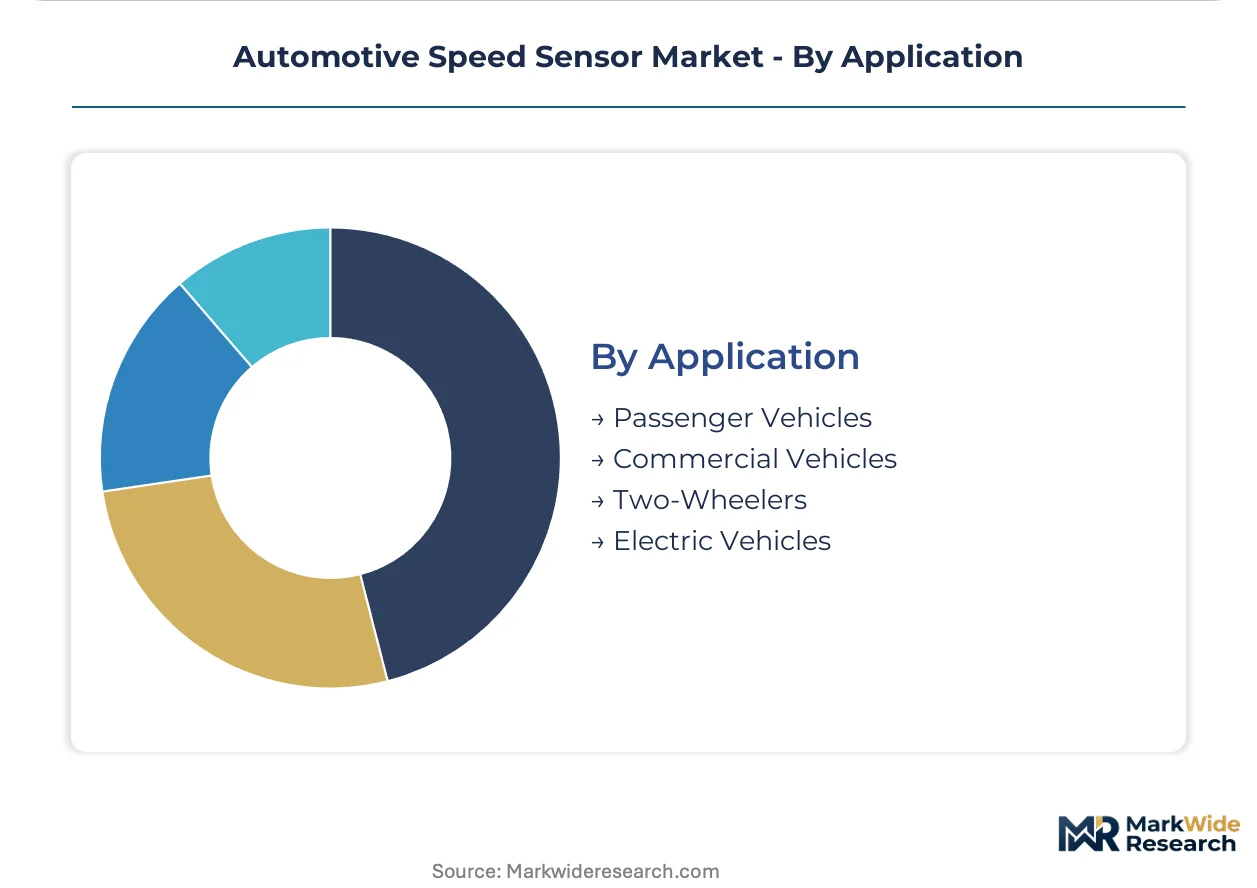
Steepest expansion trajectory belongs to Electric Vehicles. Installed base depth remains with Passenger Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors sensor specification authority through concentrated OEM headquarters and tier-1 engineering centers. The city's supplier ecosystem synchronizes Hall Effect module roadmaps with Volkswagen Group and Mercedes-Benz platform requirements. Proximity to captive semiconductor foundries compresses qualification cycles for next-generation magnetic sensing architectures.
Germany
KBA vehicle-type approval mandates enforce ECE R13 braking accuracy thresholds that compel analog-to-digital sensor upgrades. The EU Green Deal carbon-border adjustment mechanism rewards suppliers operating renewable-powered semiconductor foundries. Continental AG and Robert Bosch GmbH anchor production in Baden-Württemberg and Lower Saxony, consolidating wheel-hub module assembly for European OEM programs.
China
GB/T standards for electric vehicle safety systems mandate redundant speed sensing on each axle, doubling node count per battery electric platform. MIIT production quotas for new energy vehicles amplify procurement volumes for motor-speed feedback loops. Shanghai and Shenzhen engineering clusters coordinate specification roadmaps with Geely Holding and BYD platform teams, accelerating SENT-protocol adoption.
United States
NHTSA FMVSS 126 stability-control standards mandate degraded-mode performance verification under partial magnetic interference conditions. EPA fuel-economy benchmarking indirectly amplifies sensor demand through powertrain electrification mandates. Detroit-area brake system integrators face extended environmental test matrices for heavy-duty truck compliance, widening cost differentials versus passenger vehicle applications.
Japan
METI industrial policy directs automotive semiconductor supply chain resilience investments toward magnetic sensing operations. JIS standards for vehicle electronics synchronize with ISO 26262 functional-safety classifications for autonomous driving architectures. Toyota City and Nagoya engineering centers coordinate Hall Effect specification roadmaps with Denso and Aisin driveline module programs, reinforcing captive procurement patterns.
India
PLI scheme incentives for electric vehicle production draw sensor suppliers to establish local calibration facilities serving Maruti Suzuki and Tata Motors programs. BIS automotive component standards are converging with UN ECE technical regulations to facilitate export market access. Tamil Nadu and Gujarat manufacturing corridors concentrate assembly operations for cost-optimized ABS modules targeting two-wheeler and entry-level passenger vehicle segments.
Automotive Speed Sensor Market Competitive Environment
The competitive structure tilts toward integrated tier-1 suppliers with captive magnetic sensing and semiconductor operations. Hall Effect module producers face margin compression from TMR technology transitions and consolidated procurement by platform engineering teams. Two strategic archetypes dominate: diversified automotive electronics conglomerates with backward integration into sensor fabrication, and specialized magnetic sensing houses with firmware competency for SENT-protocol implementation. M&A activity targets firmware engineering capabilities, while capacity expansion concentrates in China and India to serve localized OEM programs.
Among German diversified suppliers, Robert Bosch GmbH and Continental AG exemplify integrated tier-1 archetypes with in-house semiconductor and magnetic sensing operations. Allegro MicroSystems Inc. represents the specialized magnetic sensing house positioned for digital protocol transitions. These three anchors illustrate the capability divide between conglomerates funding thin-film magnetic stack investments and mid-tier suppliers constrained by ISO 26262 certification burdens.
| Leading Market Players |
|---|
| HELLA GmbH & Co. KGaA |
| NXP Semiconductors NV |
| Robert Bosch GmbH |
| Hitachi Metals Ltd. |
| Allegro MicroSystems Inc. |
| Continental AG |
| ZF Friedrichshafen AG |
| Melexis NV |
| DENSO CORPORATION |
| Others |
Value Chain & Pricing Dynamics
OEM platform engineering teams in Stuttgart and Shanghai are consolidating procurement around complete wheel-hub sensor modules rather than discrete sensing elements, forcing suppliers to absorb bearing integration costs and compressing margins for standalone Hall Effect producers lacking captive assembly operations.
Pricing Analysis
ASIL-rated functional safety certification anchors value-based pricing tiers, with ISO 26262-compliant SENT-protocol modules commanding premium positioning over legacy analog alternatives. Three-tier pricing structure separates ASIL-D certified motor encoders from standard ABS-grade Hall Effect units and economy magnetic reluctance sensors for commercial vehicles. Cost compression in mass-market braking applications is intensifying because Geely and Volkswagen platform teams are awarding sole-source contracts to integrated tier-1 suppliers. Aftermarket distributors serving high-mileage vehicle parcs exhibit highest price sensitivity, while OEM direct procurement for electrified powertrains prioritizes technical performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing facilities supplying neodymium and dysprosium for Hall Effect magnetic stacks. Semiconductor fabrication concentrates in Taiwan, South Korea, and Germany, while precision magnetic sensing assembly clusters in Baden-Württemberg, Toyota City, and Shanghai. Raw material dependencies span rare earth magnets, silicon wafers, and specialized magnetic thin-film substrates. Tariff exposure on Chinese-processed rare earth compounds threatens input cost stability for European and North American sensor producers. Distribution runs through tier-1 brake system integrators and driveline module manufacturers serving OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around suppliers with captive semiconductor operations and ISO 26262 certification capabilities, with TMR technology transitions and SENT-protocol mandates freezing out mid-tier competitors lacking firmware engineering depth.
For Market Incumbents: Deepen backward integration into thin-film magnetic stack fabrication to defend margin positions against TMR technology disruption from German and Japanese tier-1 brake suppliers. Add calibration capacity in Tamil Nadu and Gujarat to capture PLI scheme incentives serving Maruti Suzuki and Tata Motors electric vehicle programs. Reinforce SENT-protocol firmware competency through targeted acquisition of embedded diagnostic algorithm developers. For New Entrants and Emerging Players: Indian two-wheeler ABS retrofit programs represent the most penetrable white-space segment, with BIS standards converging toward UN ECE technical regulations and local assembly requirements favoring new domestic entrants. Target cost-optimized Hall Effect modules for entry-level passenger vehicles where analog outputs persist and digital retrofit friction limits incumbent switching advantages. Establish partnerships with Tamil Nadu manufacturing corridor operators to bypass tier-1 supplier qualification barriers. For Investors and Strategic Acquirers: The window for entry favors specialized magnetic sensing houses with SENT-protocol implementation capabilities and existing relationships with Denso or Aisin driveline programs. Long-term viability hinges on positioning for autonomous driving redundancy architectures requiring dual-channel speed validation per wheel hub. Monitor NHTSA FMVSS 126 compliance timeline extensions for heavy-duty truck applications as the signal indicating tier-1 supplier margin pressure and potential distress acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| TMR Technology Transition | Microsecond response times enable next-generation ESC platforms for Volkswagen and Mercedes-Benz programs. |
| India Calibration Facility Expansion | PLI scheme incentives anchor local production for Maruti Suzuki electric vehicle sensor requirements. |
| SENT-Protocol Firmware Acquisition | Embedded diagnostic capabilities satisfy ISO 26262 ASIL ratings for autonomous driving architectures. |
| Captive Rare Earth Magnet Processing | Upstream control over neodymium supply chains mitigates Chinese export restriction exposure. |
| Integrated Bearing-Sensor Module Development | Complete wheel-hub assemblies capture procurement consolidation by Geely and Volkswagen platform teams. |
Study Parameters
SEC filings from Allegro MicroSystems and NXP Semiconductors, IHS Markit vehicle production databases, and KBA type-approval records formed the secondary backbone, cross-referenced with primary interviews involving tier-1 brake system procurement managers, OEM platform engineers in Stuttgart and Shanghai, and aftermarket distributors serving high-mileage commercial vehicle operators. Bottom-up unit shipment estimates by vehicle class and propulsion architecture were triangulated against top-down market value reconstructions from supplier revenue disclosures and customs trade data.
Historical trendline analysis of Hall Effect and magnetic encoder shipments across passenger, commercial, and electric vehicle segments informed the projection framework. Segmentation dimensions modeled include sensor technology, interface protocol, application architecture, and regional production cluster. CAGRs were derived from regression analysis of content-per-vehicle trajectories and electrification penetration curves. Key forecast inputs encompass NHTSA FMVSS 126 implementation timelines and MIIT new energy vehicle production quota trajectories.
Revisions become necessary when rare earth export restrictions materialize, TMR adoption accelerates beyond brake system supplier roadmaps, or autonomous driving redundancy mandates expand beyond SAE Level 3 architectures. Forecasts reflect documented assumptions regarding platform standardization patterns and tier-1 supplier consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Automotive Alternator and Starter Motor Market
Automotive Electrical & Electronics
Wireline Trucks Market
Automotive Electrical & Electronics
India Automotive Camera Market
Automotive Electrical & Electronics
Europe Automotive LED Lighting Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
On-Board Charger Market
Automotive Electrical & Electronics
Motor Vehicle Sensor Market
Automotive Electrical & Electronics
Automotive Battery Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market