
 Automotive Camera Market | 2026-2036
Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Camera Market Analysis
Buyer concentration among OEMs is shifting as vehicle assemblers consolidate camera sourcing around vertically integrated Tier-1 partners. Robert Bosch GmbH leverages its manufacturing scale to dominate digital camera supply chains for European premium brands. Mobileye anchors autonomous perception stacks through proprietary image-processing silicon. Valeo SA competes on thermal camera specialization for night-vision applications in luxury segments.
An automotive camera is an electro-optical sensor module integrating CMOS image sensors, lens assemblies, and signal-processing units to capture real-time visual data for vehicle perception systems. Resolution thresholds now exceed two megapixels for digital variants, with Ethernet-based data transmission replacing legacy coaxial analog links to support fused sensor architectures. Rearview camera applications command stable volume pools across mass-market OEM fitments, while 360-degree camera systems capture expanding margin pools as surround-view upgrades penetrate mid-tier vehicle segments. Thermal camera technology leads in premium collision-avoidance configurations where low-light performance commands specification premiums.
NHTSA mandates rear-visibility standards for light vehicles sold in the United States, while Euro NCAP ratings penalize models lacking camera-based active safety systems. ECE R79 and ECE R46 frame European technical requirements for driver-assistance and indirect-vision camera installations. Stakeholders must monitor how UN harmonized vehicle regulations reshape cross-border certification burdens for multi-platform camera programs.
Market Dynamics
Euro NCAP safety mandates are compressing camera specification timelines as OEMs scramble to secure collision-avoidance ratings ahead of model refresh cycles. This regulatory pressure is redrawing procurement relationships around vertically integrated Tier-1 suppliers capable of delivering fused sensor architectures at scale.
Growth Catalysts
- Euro NCAP rating requirements:Camera-based active safety systems now determine star ratings, forcing mass-market OEMs to standardize surround-view configurations across vehicle lineups.
- CMOS resolution thresholds:Two-megapixel digital variants are displacing legacy analog rearview modules as Ethernet transmission becomes standard for fused perception stacks.
- German production clustering:Tier-1 suppliers anchor 360-degree and thermal camera manufacturing in Baden-Württemberg and Bavaria, concentrating engineering talent and sub-tier component access.
Market Restraints
- Silicon supply concentration:Advanced image-processing SoCs depend on concentrated foundry capacity in Taiwan, exposing camera module lead times to geopolitical friction.
- Thermal sensor cost structure:Vanadium oxide microbolometer arrays command premium pricing that limits night-vision penetration to luxury vehicle segments.
- ECE R46 compliance burden:European technical requirements for indirect-vision camera installations impose lengthy homologation cycles that delay platform launches.
Strategic Opportunities
- India vehicle safety mandates:Bharat NCAP adoption is creating first-fit demand for rearview and surround-view cameras in a market historically dependent on aftermarket fitments.
- Thermal-visible fusion:Combining SWIR sensors with conventional CMOS arrays enables all-weather perception for autonomous trucking corridors in Nordic markets.
- OTA calibration channels:Remote software updates for camera alignment and distortion correction are opening recurring revenue streams alongside hardware sales.
Industry Challenges
- Optical engineering scarcity:Lens design expertise for automotive-grade thermal expansion tolerance concentrates among aging specialist workforces in Germany and Japan.
- Legacy coaxial integration:Platform engineers face wiring harness reconfiguration costs when upgrading from analog to Ethernet-based camera architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Camera Market |
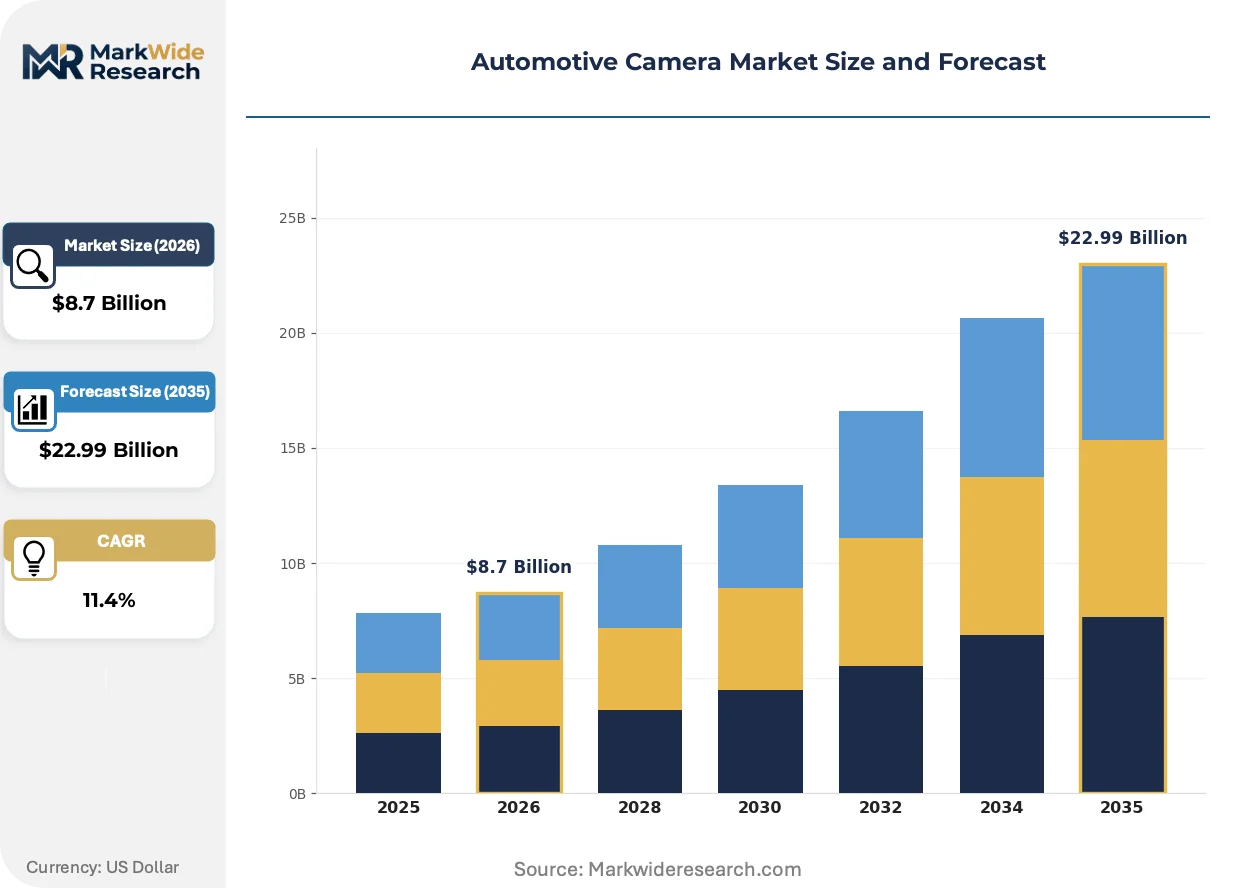
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rearview Camera, 360-Degree Camera, Infrared Camera, Night Vision Camera Technology: Analog Camera, Digital Camera, Thermal Camera, 3D Camera Application: Driver Assistance, Collision Avoidance, Parking Assistance, Surveillance End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers |
| Companies Covered | Robert Bosch GmbH, Magna International Inc., Valeo SA, Continental AG, Denso Corporation, ZF Friedrichshafen AG, Aptiv PLC, Mobileye, Hyundai Mobis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Camera Market Emerging Trajectories
Sensor fusion architectures are collapsing discrete camera, radar, and lidar data streams into unified perception stacks. This convergence is compressing the value chain as module suppliers compete to deliver pre-processed object detection rather than raw image feeds.
Ethernet-based data transmission is unifying camera connectivity across vehicle domains. Premium OEMs in Germany and California are mandating automotive-grade Ethernet for all new surround-view programs. This standardization is unifying Tier-1 engineering roadmaps around single-pair cabling and reducing variant complexity for platform teams.
NHTSA rear-visibility standards are hardening compliance requirements for light vehicle camera systems sold in the United States. The regulation now specifies field-of-view angles and image persistence metrics that exceed baseline UN ECE provisions. Pickup truck and SUV segments face the steepest redesign costs as their larger dimensions demand wider-angle lens assemblies.
Fleet procurement patterns are fragmenting camera sourcing decisions between OEM captive finance arms and independent leasing operators. Commercial vehicle lessors in the Netherlands and Texas are specifying camera-based driver monitoring as standard equipment to reduce insurance premiums. This specification authority shift is forcing module suppliers to develop direct fleet sales channels alongside traditional OEM relationships.
Automotive Camera Market Segmentation
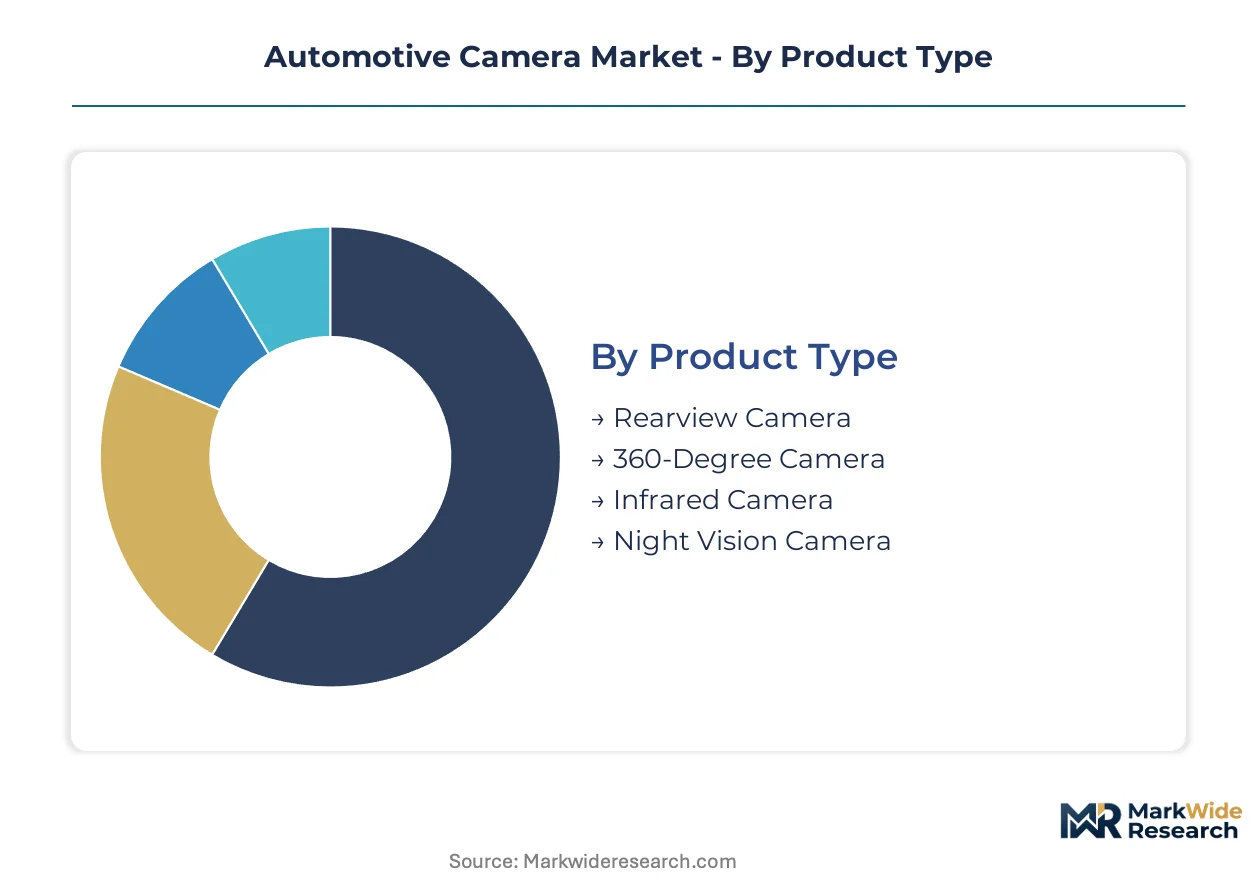
Automotive camera procurement divides sharply between standardized mass-market configurations mandated by safety regulations and specialized variants commanding technology premiums. Tier-1 suppliers structure manufacturing lines around these divergent margin profiles.
Product Type:
Standardization pressure from Euro NCAP ratings compresses specification ranges for entry-level variants, while premium segments retain customization latitude for thermal and night-vision modules.
- Rearview Camera:CMOS-based modules with wide-angle lens assemblies dominate mass-market fitments. NHTSA mandates drive baseline volume through US light vehicle platforms, with module costs amortized across high production runs.
- 360-Degree Camera:Multi-camera fusion architectures stitch four to six discrete feeds into unified surround-view displays. German premium OEMs specify these for mid-tier vehicle upgrades, expanding margin pools beyond flagship segments.
- Infrared Camera:Near-infrared illumination paired with enhanced CMOS sensitivity supports low-light parking assistance.
- Night Vision Camera:Thermal imaging cores using vanadium oxide microbolometers penetrate luxury configurations where pedestrian detection commands specification premiums.
Most installed capacity flows through Rearview Camera. Expansion is steepest in 360-Degree Camera.
Technology:
Cost tiers separate legacy analog architectures from digital and thermal variants requiring specialized signal processing and calibration protocols.
- Analog Camera:Coaxial transmission and composite video signaling persist in cost-optimized emerging market platforms. Bharat NCAP adoption is accelerating replacement timelines in India.
- Digital Camera:Two-megapixel CMOS sensors with Ethernet-based data transmission anchor fused perception stacks. Baden-Württemberg production clusters concentrate engineering talent for these modules.
- Thermal Camera:Uncooled microbolometer arrays detect infrared radiation independent of visible illumination.
- 3D Camera:Time-of-flight and stereo vision architectures enable depth mapping for autonomous navigation.
Digital Camera captures the dominant share of new program awards. Thermal Camera is climbing the fastest as night-vision penetration deepens in premium segments.
Application:
Functional requirements diverge between active safety systems demanding real-time processing and passive monitoring applications with relaxed latency tolerances.
- Driver Assistance:Lane-keeping and traffic-sign recognition algorithms process monocular camera feeds. Euro NCAP rating protocols weight these capabilities heavily in star assessments.
- Collision Avoidance:Forward-facing digital cameras with object-detection neural networks anchor automatic emergency braking. OEMs consolidate sourcing around Tier-1 partners with fused sensor integration capabilities.
- Parking Assistance:Ultrasonic fusion with rearview camera feeds enables automated maneuvering in confined spaces.
- Surveillance:Cabin-facing cameras monitor driver attention for Level 2+ hands-free systems.
Collision Avoidance commands the largest share of module shipments. Driver Assistance is gaining share fastest as regulatory mandates broaden.
End User:
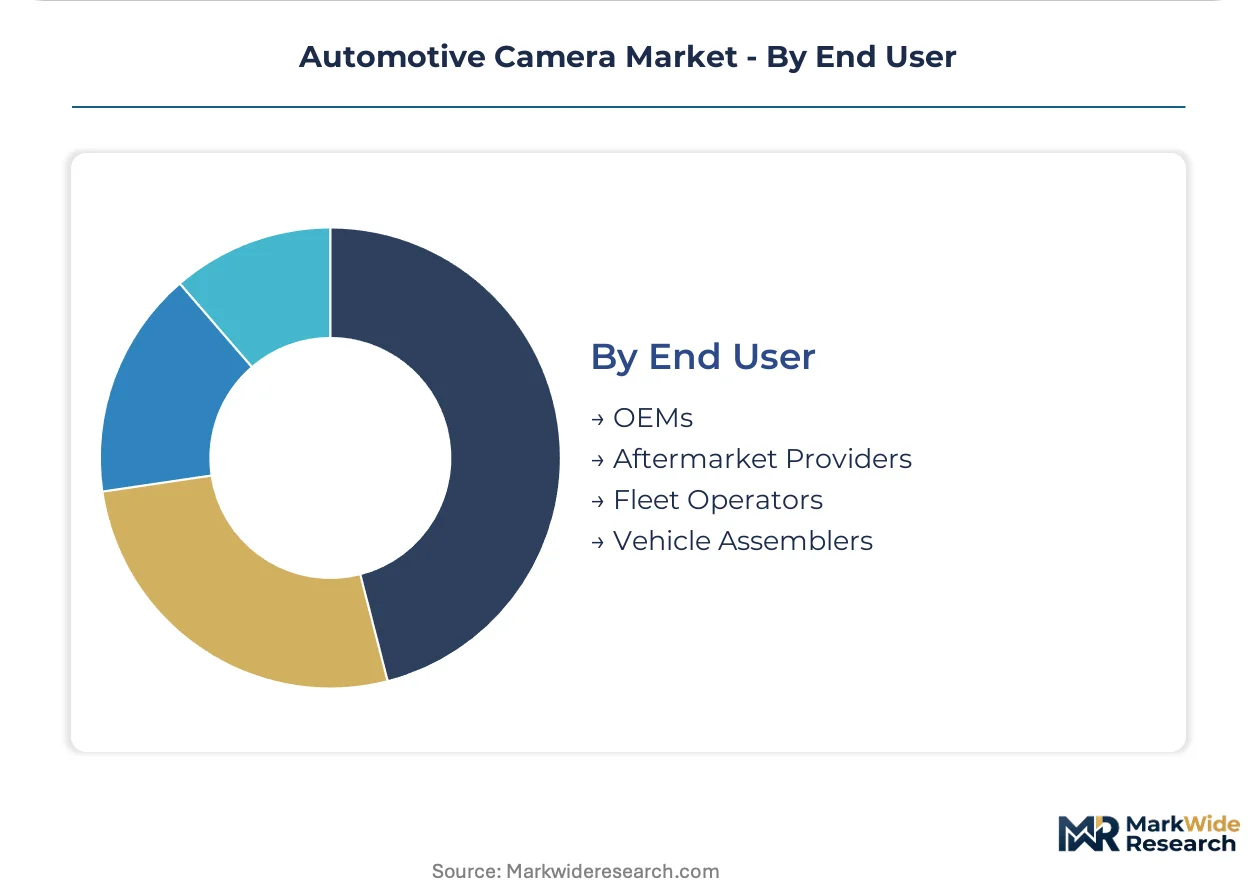
Procurement authority concentrates differently across captive OEM supply chains, independent aftermarket channels, and emerging fleet specification models.
- OEMs:Volkswagen Group and BMW specify camera modules through long-term Tier-1 partnerships. Vertical integration into image-processing software differentiates competitive positioning.
- Aftermarket Providers:Retrofit rearview camera kits serve vehicle parc lacking factory fitment. Indian and Brazilian distributors dominate this channel.
- Fleet Operators:Commercial lessors in Texas and the Netherlands specify driver-monitoring cameras to reduce insurance premiums.
- Vehicle Assemblers:Contract manufacturers for emerging EV brands procure camera modules through open supplier competition.
OEMs channel the majority of module volume. Fleet Operators are expanding most quickly as specification authority shifts from vehicle assemblers to lessors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates engineering talent for 360-degree camera systems while the United States drives volume through NHTSA-mandated rearview fitments. China scales CMOS sensor production for cost-optimized digital modules. India and Japan represent diverging demand profiles shaped by regulatory adoption timelines and premium segment specialization.
United States
NHTSA rear-visibility mandates sustain baseline demand across light truck and SUV platforms. The regulation specifies field-of-view angles exceeding UN ECE baseline requirements. Michigan-based engineering centers coordinate Tier-1 validation programs for pickup truck camera redesigns.
Germany
Baden-Württemberg and Bavaria anchor 360-degree and thermal camera manufacturing clusters. Euro NCAP rating protocols weight camera-based active safety heavily in star assessments. Stuttgart engineering teams concentrate lens design expertise for automotive-grade thermal expansion tolerance.
China
Domestic EV assemblers specify surround-view systems as standard equipment across mid-tier vehicle lineups. MIIT vehicle safety regulations accelerate camera adoption timelines. Yangtze River Delta production bases scale CMOS module assembly for export and domestic consumption.
India
Bharat NCAP adoption creates first-fit demand for rearview and surround-view cameras in a market historically dependent on aftermarket channels. The Ministry of Road Transport and Highways mandates crash-test rating disclosure. Tamil Nadu and Gujarat vehicle assembly corridors integrate camera modules into compact car platforms.
Japan
Premium OEMs specify night-vision thermal systems for domestic flagship sedans. METI industrial policy supports sensor fusion R&D consortia. Nagoya-area Tier-1 engineering centers specialize in optical calibration protocols for stereo vision architectures.
Automotive Camera Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across module supply and image-processing software layers. The vendor base structures around three tiers: vertically integrated Tier-1 system suppliers, semiconductor-focused perception stack providers, and regional module assemblers. Dominant competitive moves include strategic partnerships for fused sensor architectures and capacity expansion in German and Chinese production clusters.
Within the diversified conglomerate tier, Robert Bosch GmbH, Continental AG, and Denso Corporation exemplify scale-driven positioning across European, North American, and Asian OEM supply chains respectively. These entities anchor procurement relationships through captive manufacturing footprints and long-term platform engineering contracts.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Magna International Inc. |
| Valeo SA |
| Continental AG |
| Denso Corporation |
| ZF Friedrichshafen AG |
| Aptiv PLC |
| Mobileye |
| Hyundai Mobis |
| Others |
Supply Flow & Price Mechanics
Resolution-performance bifurcation between two-megapixel digital modules and legacy analog rearview units manifests in divergent margin structures and supply chain configurations across German engineering clusters and cost-optimized Asian assembly lines. Tier-1 suppliers capture premium pricing through in-house image-processing software while commodity rearview volumes amortize tooling costs across NHTSA-mandated US light vehicle programs.
Pricing Analysis
Capacity additions in China and Taiwan are reshaping price floors for CMOS sensor modules as Yangtze River Delta fabs scale two-megapixel output for domestic EV assemblers. Three-tier pricing structure across premium thermal, standard digital, and economy analog levels separates night-vision configurations commanding specification premiums from mass-market rearview fitments. Cost compression in entry-level digital variants is intensifying because Ethernet transmission standardization erodes coaxial legacy differentiation. Fleet operators in Texas and the Netherlands exhibit lowest price sensitivity as insurance premium reductions justify driver-monitoring camera investments, while Indian aftermarket distributors face acute margin pressure from Bharat NCAP first-fit mandates.
Supply Chain Analysis
Optical engineering scarcity in Stuttgart and Nagoya constrains lens design throughput for thermal expansion-tolerant automotive-grade modules. Manufacturing concentrates in Germany, China, and Japan, with Baden-Württemberg anchoring 360-degree system assembly and Yangtze River Delta scaling CMOS module production. Raw material dependencies include silicon wafers from Taiwan foundries, vanadium oxide microbolometer arrays for thermal cores, and specialized glass substrates from Japanese suppliers. Single-source vulnerability in advanced image-processing SoC fabrication exposes camera module lead times to geopolitical friction. Distribution runs through captive OEM supply chains for Volkswagen Group and BMW, alongside direct fleet procurement channels emerging in commercial vehicle leasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive camera economics favor margin expansion as CMOS resolution standardization concentrates procurement authority among vertically integrated Tier-1 partners capable of software-defined differentiation. Ethernet-based architecture transitions create premium-tier separation between fused perception stacks and legacy analog replacement cycles.
For Market Incumbents: Deepen software-layer control over image-processing algorithms to defend against Mobileye's proprietary silicon lock-in. Secure long-term foundry allocation agreements for advanced SoC capacity in Taiwan to mitigate geopolitical supply disruption. Expand thermal camera specialization through Nagoya-area optical engineering partnerships, leveraging aging workforce scarcity as a competitive moat against modular assembly entrants.
For New Entrants and Emerging Players: Bharat NCAP in India opens a window for first-fit rearview and surround-view camera penetration in a market historically dependent on aftermarket channels. Target compact car platforms in Tamil Nadu and Gujarat assembly corridors where OEM procurement relationships remain unconsolidated. Pursue direct fleet sales channels in Texas and Netherlands commercial leasing markets, bypassing captive OEM supply chains through insurance-premium value propositions.
For Investors and Strategic Acquirers: Consolidation pressure builds where Tier-1 engineering roadmaps fragment around Ethernet standardization versus legacy coaxial platform support. Focus acquisition screening on mid-cap module assemblers with Baden-Württemberg manufacturing footprints and existing OEM validation relationships. Watch for inflection in OTA calibration adoption rates as recurring revenue models displace pure hardware monetization.
| Strategic Initiative | Industry Significance |
|---|---|
| Ethernet Architecture Standardization | Unifies Tier-1 engineering roadmaps around single-pair cabling for surround-view programs. |
| Thermal-Visible Sensor Fusion | Combines SWIR arrays with CMOS for all-weather perception in Nordic autonomous trucking corridors. |
| OTA Calibration Channel Development | Opens recurring revenue streams through remote camera alignment and distortion correction updates. |
| German Production Cluster Expansion | Concentrates 360-degree and thermal camera engineering talent in Baden-Württemberg and Bavaria. |
| Fleet Direct Procurement Relationships | Bypasses OEM captive supply chains for commercial lessors specifying driver-monitoring systems. |
Methodological Framework
Bottom-up vehicle production modeling reconciled against top-down Tier-1 supplier shipment tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier-1 procurement directors, aftermarket distributors, and fleet leasing operators in Germany, the United States, China, and India informed demand-side assumptions. Secondary validation drew from NHTSA regulatory filings, Euro NCAP test protocols, vehicle registration databases, and MIIT safety standard disclosures. Supply-side calibration incorporated customs trade data for CMOS sensor imports and foundry capacity reports from Taiwan.
Input-output matrices map camera content per vehicle across propulsion architecture, vehicle class, and OEM tier dimensions throughout the forecast period. Segmentation modeling captures product type, technology tier, application function, and end-user procurement authority. CAGRs derive from regression analysis against Euro NCAP adoption timelines and NHTSA mandate compliance schedules, with cross-referencing to Bharat NCAP phase-in assumptions for India volume projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Taiwan semiconductor export restriction scenarios or accelerated Euro NCAP protocol revisions. Forecasts reflect documented assumptions regarding Ethernet adoption curves and thermal sensor cost-down trajectories. Material deviation in Bharat NCAP enforcement intensity or MIIT surround-view mandate timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
India Automotive Camera Market
Automotive Electrical & Electronics
Automotive Electronic Expansion Valve Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Mexico Automotive EPS Market
Automotive Electrical & Electronics
Global Automotive on Board AC-DC Power Inverters Market
Automotive Electrical & Electronics
Germany X by Wire Systems Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
UK Automotive Eps Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market
Automotive Electrical & Electronics
Electric Vehicle HV Cables Market
Automotive Electrical & Electronics
India Automotive Sensors Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
India Automotive LED Lighting Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market