
 Automotive Retread Tires Market | 2026-2036
Automotive Retread Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Retread Tires Market Analysis
ISO 9001 certification is rotating as the baseline qualification gating which retread manufacturers qualify for OEM supply contracts and fleet procurement tenders. Bridgestone Corporation leverages its captive casing supply network to dominate premium retread output for heavy truck fleets. Michelin sustains technology leadership through proprietary rubber compound formulations that extend casing life across multiple retread cycles. Goodyear Tire & Rubber Company competes on manufacturing scale, operating high-volume retread plants that serve national fleet accounts with consistent turnaround times.
Automotive retread tires are used tires whose worn tread is removed and replaced with new rubber through hot or cold curing processes, typically requiring casings with 80% or more of original structural integrity to ensure safety and performance parity with new tires. Their primary purpose is to deliver equivalent mileage at 30-50% lower cost per kilometer for commercial vehicle operators managing large rolling stock inventories. Heavy truck applications anchor volume demand due to predictable highway wear patterns and standardized casing pools that simplify retread economics. Fleet operators represent the fastest-growing end user segment as enterprise procurement teams integrate lifecycle cost analytics into tire replacement decisions. Rubber formulations command the most intensive R&D investment among material categories, with compound innovations directly determining heat resistance and retread adhesion quality.
The U.S. EPA SmartWay program and NHTSA fuel efficiency standards shape retread demand by rewarding verified low-rolling-resistance products with preferential fleet procurement status. ECHA REACH compliance and EU F-Gas Regulation indirectly pressure tire manufacturers toward retread models by elevating the environmental cost of virgin rubber production and disposal. The EU Green Deal's circular economy action plan further embeds retreading within sustainability frameworks by establishing extended producer responsibility metrics for tire lifecycles. Stakeholders must monitor how evolving carbon border adjustment mechanisms and regional sustainability certification schemes will restructure competitive access across integrated North American and European supply chains.
Market Dynamics
Fleet procurement teams now embed total cost of ownership calculators into tire replacement decisions, compressing replacement cycles and elevating retread economics over virgin tire purchases across North American long-haul operations.
Growth Catalysts
- EPA SmartWay Verification:The U.S. EPA SmartWay program grants preferential procurement status to low-rolling-resistance retreads, compelling fleet operators to specify certified products in national tenders.
- Casing Pool Standardization:Heavy truck operators with standardized wheel positions generate predictable casing flows, enabling retread plants to achieve batch economies and reduce turnaround variability.
- EU Circular Economy Mandates:The EU Green Deal's extended producer responsibility metrics embed retreading within sustainability frameworks, rewarding manufacturers with favorable carbon accounting.
Market Restraints
- Natural Rubber Price Volatility:Compound formulations depend on natural rubber feedstocks subject to Southeast Asian weather disruptions and currency fluctuations, compressing margin predictability for independent retreaders.
- Casing Quality Scarcity:Premium casings capable of supporting multiple retread cycles concentrate with captive fleet networks, leaving independent operators with structurally degraded input stock.
- Technical Limitation on Speed Ratings:Retread adhesion chemistry currently limits maximum speed certification below premium virgin tire thresholds, excluding high-performance commercial vehicle segments.
Strategic Opportunities
- Brazilian Fleet Formalization:Underpenetrated long-haul trucking in Brazil presents white space as national logistics operators consolidate from fragmented owner-operator models toward managed fleet structures.
- Sensor-Enabled Predictive Retreading:Integration of tire pressure monitoring systems with casing integrity algorithms enables just-in-time retread scheduling, reducing downtime for refrigerated transport fleets.
- Carbon Border Adjustment Positioning:Early alignment with emerging EU carbon border mechanisms allows retread manufacturers to document lifecycle emissions advantages versus virgin tire imports.
Industry Challenges
- ISO 9001 Certification Timeline:The 12-18 month accreditation process gates OEM supply contracts, straining mid-cap retreaders seeking fleet procurement qualification.
- Hot-Cure Process Skill Transfer:Veteran curing press operators are retiring faster than vocational programs replenish specialized rubber bonding expertise, constraining plant expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Retread Tires Market |
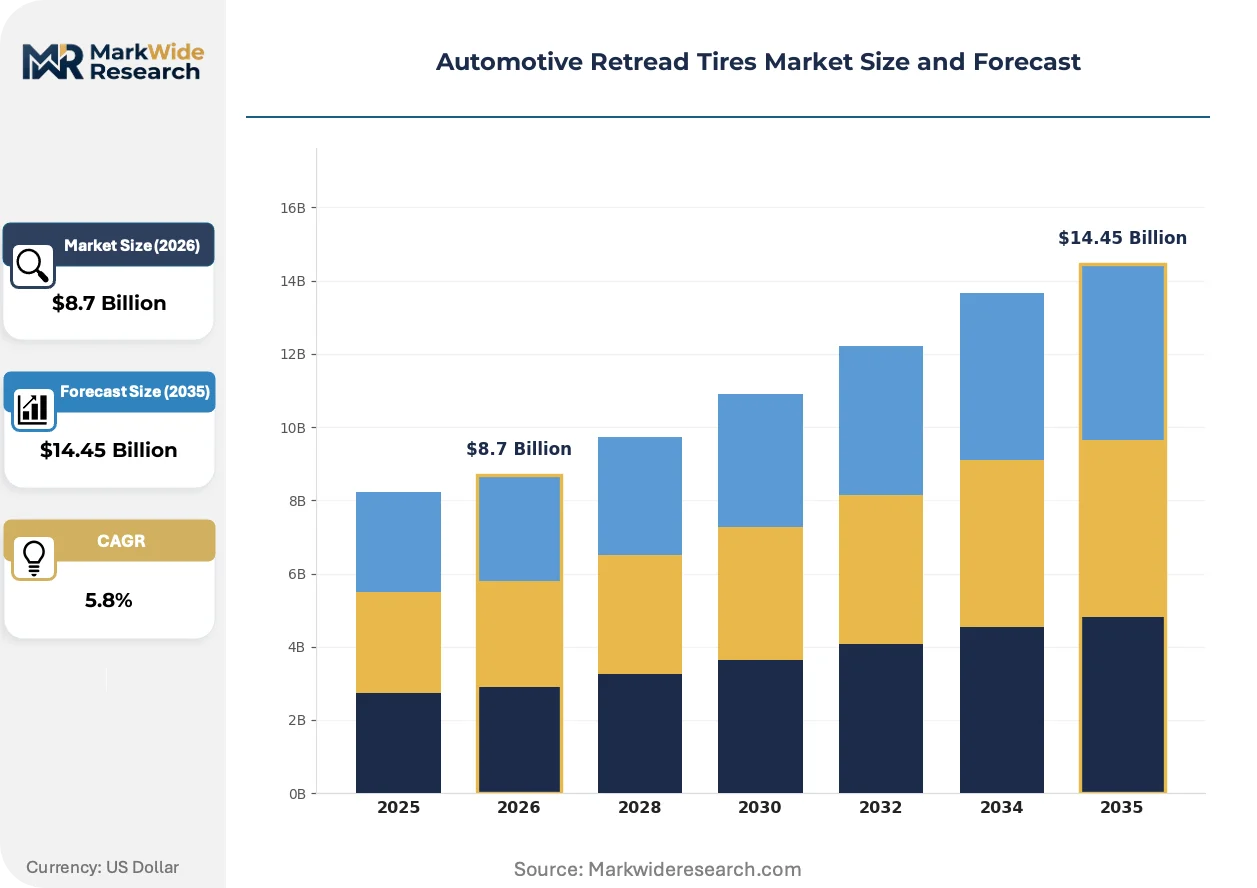
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Vehicle, Light Truck, Heavy Truck, Bus End User: Fleet Operators, Individual Consumers, Rental Services, Government Agencies Material: Rubber, Fabric, Steel, Other Composites Application: Road Transport, Off-Road Use, Emergency Services, Military Use |
| Companies Covered | Bridgestone Corporation, Michelin, Goodyear Tire & Rubber Company, Continental AG, Marangoni S.p.A., Southern Tire Mart, Sumitomo Rubber Industries, Pirelli, Vipal Rubber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Retread Tires Market Emerging Trajectories
Digital inspection systems and advanced compound chemistry are compressing quality variance and enabling predictive maintenance integration, reshaping how fleet operators manage rolling stock lifecycles.
Thermal imaging cameras coupled with laser profilometry now automate casing integrity assessment, replacing manual visual inspection protocols. Large fleet maintenance depots in the United States are adopting these systems at replacement cycle points. The technology is miniaturizing inspection hardware to portable units, enabling roadside casing triage and expanding retread-qualified casing recovery rates.
REACH compliance deadlines for microplastic emissions from tire wear are elevating environmental scrutiny across European supply chains. Retread manufacturers with verified lower particulate output per kilometer gain preferential status in sustainability-weighted tenders. Heavy truck fleet operators in Germany and the Netherlands are now specifying retread products in procurement frameworks to preempt regulatory liability.
Enterprise buyers are consolidating tire spend under national service contracts with guaranteed casing recovery terms. Independent dealers and regional retreaders face disintermediation as direct manufacturer-fleet arrangements capture casing pools and service revenue. This pattern concentrates most visibly among United States-based refrigerated transport operators with centralized procurement functions.
Automotive Retread Tires Market Segmentation
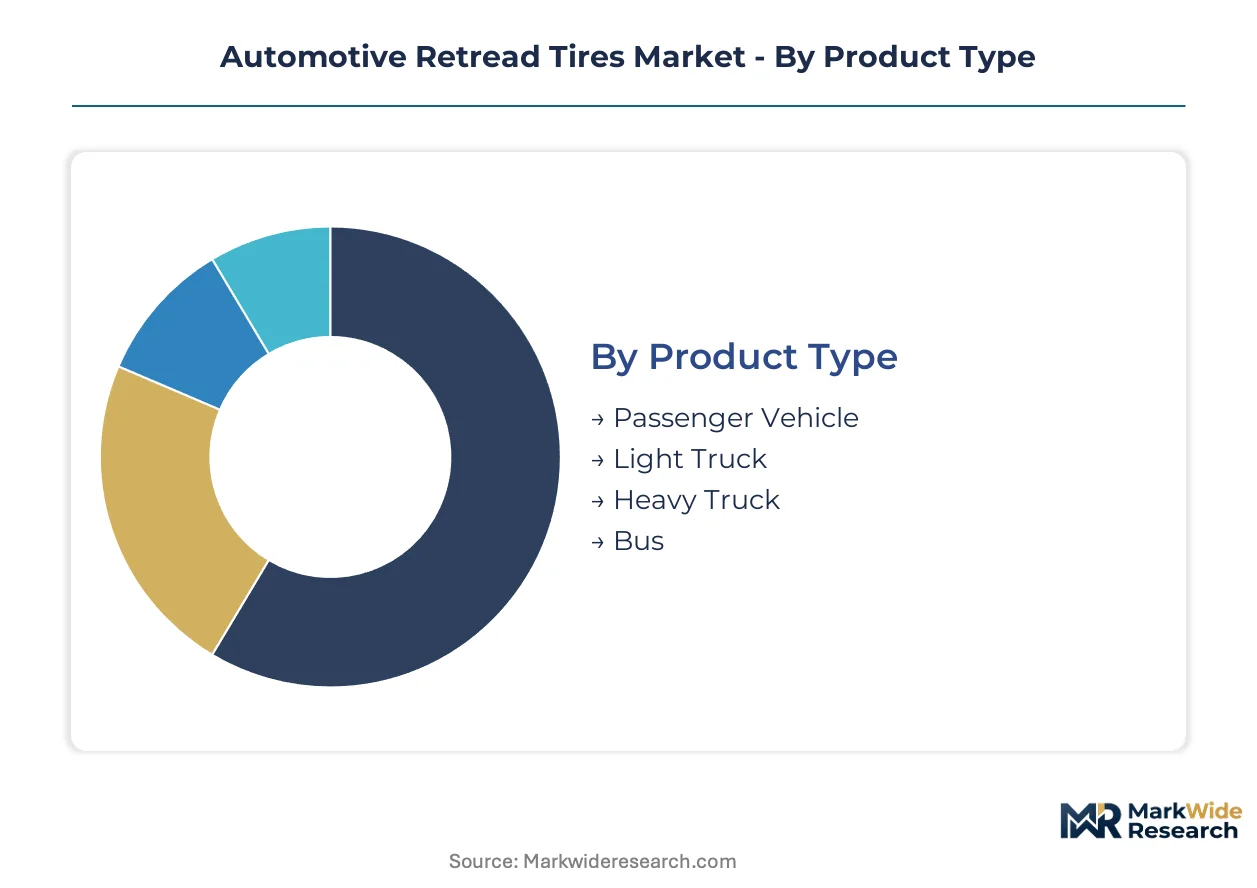
Retread tire procurement patterns diverge sharply across vehicle classes and operational models, with fleet-scale buyers driving standardization while fragmented end-users sustain price-sensitive tiers. Material composition and application severity further stratify supplier capabilities, determining which manufacturers capture premium casing flows versus commodity replacement cycles.
Product Type:
Domestic fleet demand concentrates in heavy-duty categories with standardized wheel positions, while export-oriented production serves lighter vehicle segments where casing recovery rates remain unpredictable.
- Heavy Truck:Casings from long-haul tractors and trailers undergo multiple retread cycles due to predictable highway wear patterns and controlled maintenance intervals. United States-based refrigerated transport fleets now specify these products in national procurement frameworks to optimize total cost of ownership calculations.
- Bus:Urban transit operators generate steady casing volumes through fixed-route operations with centralized depots, though stop-and-go duty cycles limit retreadability versus highway applications. Municipal procurement in Germany and the Netherlands increasingly favors verified low-rolling-resistance retreads under EU Green Deal extended producer responsibility metrics.
- Passenger Vehicle:Limited adoption outside commercial taxi fleets due to consumer perception barriers and irregular maintenance histories degrading casing quality.
- Light Truck:Regional delivery services and last-mile logistics sustain modest volumes, with demand clustering among independent contractors seeking cost reduction without fleet-scale casing pools.
Heavy Truck commands the established base. The steepest expansion runs through Bus as municipal sustainability mandates tighten.
End User:
Procurement sophistication separates enterprise buyers with lifecycle cost analytics from price-driven segments where retread economics struggle against low-cost virgin imports.
- Fleet Operators:Enterprise procurement teams integrate tire pressure monitoring systems with casing integrity algorithms, enabling just-in-time retread scheduling that minimizes refrigerated transport downtime. These buyers negotiate direct manufacturer contracts with guaranteed casing recovery terms, bypassing independent dealer networks.
- Government Agencies:Defense and postal services generate stable demand through multi-year supply agreements, though bureaucratic qualification timelines strain smaller retreaders seeking contract access. United States Postal Service vehicle pools represent a concentrated casing source with standardized maintenance protocols.
- Rental Services:Vehicle lessors prioritize rapid turnaround over retread cycles, limiting adoption to premium fleet segments with dedicated maintenance infrastructure.
- Individual Consumers:Price sensitivity dominates, but casing quality uncertainty and limited retail availability suppress penetration outside agricultural and commercial owner-operator niches.
Fleet Operators anchor volume procurement. Government Agencies provide the most stable contract visibility for qualified suppliers.
Material:
Compound formulation investments determine heat resistance and adhesion quality, with natural rubber dependency exposing margin structures to Southeast Asian supply volatility.
- Rubber:Proprietary compound chemistry from manufacturers like Michelin extends casing life across multiple retread cycles through advanced polymer blends. R&D intensity concentrates here, with REACH compliance deadlines for microplastic emissions elevating scrutiny of wear particle output per kilometer.
- Steel:Bead wire and belt reinforcement structures preserve casing integrity between retread cycles, with quality variance directly impacting maximum speed certification thresholds.
- Fabric:Polyester and nylon casing plies provide structural foundation, though degradation rates limit multi-cycle retreadability in severe duty applications.
- Other Composites:Emerging reinforcement materials target weight reduction and heat dissipation, currently niche but attracting development investment from tier-one suppliers.
Rubber formulations absorb the dominant R&D share. Steel quality variance most directly constrains premium segment expansion.
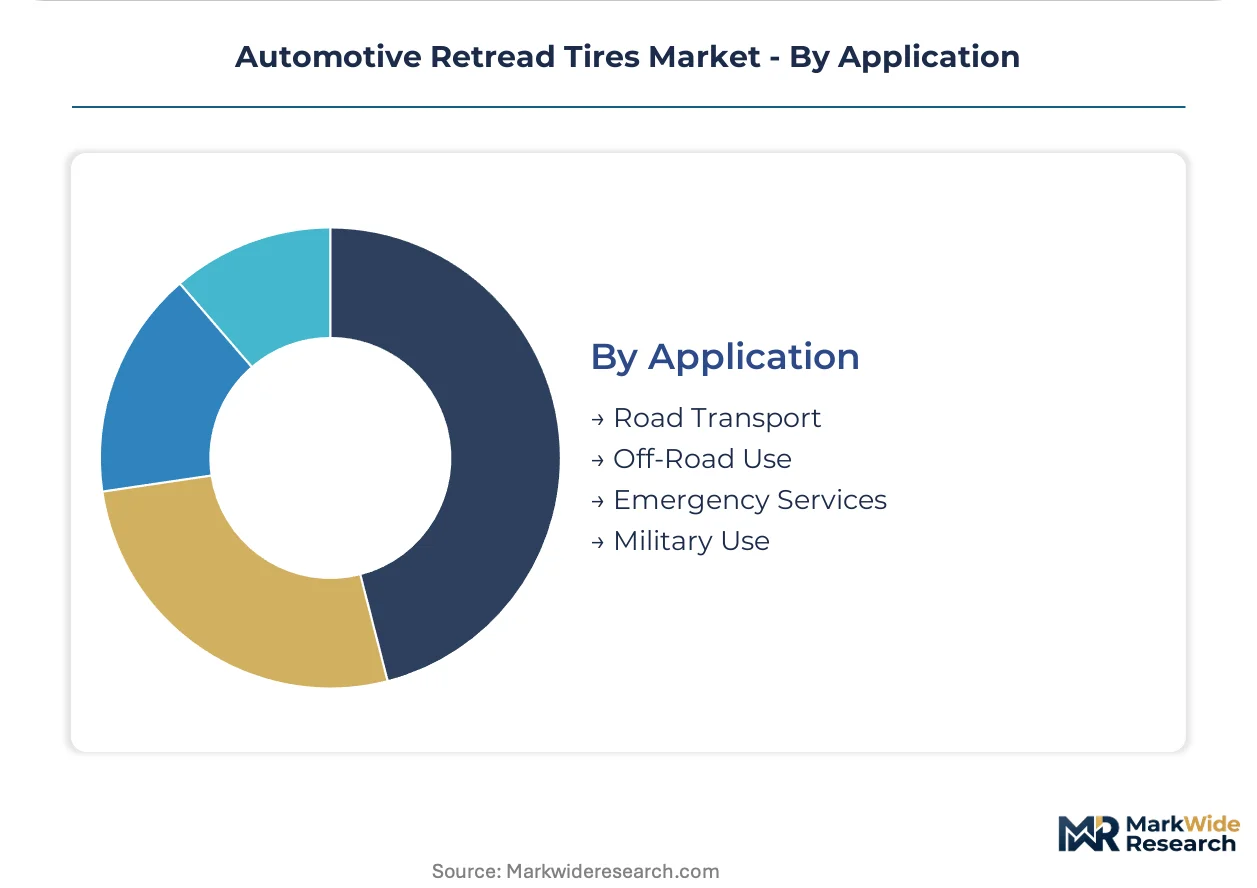
Application:
Operating environment severity dictates casing recovery economics, with controlled highway duty sustaining predictable retread cycles versus abrasive or intermittent use patterns.
- Road Transport:Interstate trucking and urban freight generate the core retread volume, with consistent speeds and maintained surfaces preserving casing integrity for multiple cycles. United States long-haul operators achieve optimal economics through standardized wheel positions and centralized maintenance depots.
- Off-Road Use:Mining and construction applications degrade casings through abrasive terrain and heavy loading, limiting retreadability despite high virgin tire replacement costs. Brazilian agricultural operations present emerging demand as fleet formalization consolidates owner-operator structures.
- Emergency Services:Police and ambulance fleets prioritize reliability over cost optimization, suppressing retread adoption despite predictable urban duty cycles.
- Military Use:Tactical vehicle specifications emphasize performance under extreme conditions, with retread chemistry currently unable to match premium virgin tire speed and load ratings.
Road Transport sustains the volume foundation. Off-Road Use offers the largest unrealized potential as emerging market fleet structures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA SmartWay verification and EU Green Deal circular economy mandates are redirecting fleet procurement toward certified low-rolling-resistance retreads across major commercial vehicle markets.
United States
Long-haul refrigerated transport fleets dominate retread demand through centralized procurement frameworks. NHTSA fuel efficiency standards reward verified low-rolling-resistance products with preferential fleet tender status. The I-80 corridor through Illinois and Ohio concentrates retread plant capacity serving national distribution networks.
Germany
Municipal transit operators generate steady casing volumes through fixed-route bus operations with centralized maintenance depots. ECHA REACH compliance deadlines for microplastic emissions elevate scrutiny of wear particle output per kilometer. The Ruhr industrial cluster hosts compound formulation facilities supplying retreaders across the Benelux region.
Brazil
National logistics operators are consolidating from fragmented owner-operator models toward managed fleet structures, expanding addressable retread demand. ANVISA and national environmental regulators are embedding extended producer responsibility metrics into commercial vehicle standards. São Paulo state anchors formalized fleet operations with standardized maintenance protocols.
Netherlands
Heavy truck fleet operators specify retread products in procurement frameworks to preempt regulatory liability from EU sustainability labeling requirements. The EU F-Gas Regulation indirectly pressures tire manufacturers toward retread models by elevating environmental cost of virgin rubber production. Rotterdam's port logistics cluster generates predictable casing flows from container haulage operations.
Canada
Cross-border trucking operations with standardized wheel positions achieve optimal retread economics through centralized maintenance depots. Health Canada and Transport Canada align commercial vehicle standards with EPA SmartWay verification protocols. The Ontario-Quebec corridor sustains retread plant capacity serving integrated North American supply chains.
Automotive Retread Tires Market Vendor Landscape
Listed leaders compete with private specialists across casing supply networks and compound formulation capabilities. The market structures around three tiers: integrated tire manufacturers with captive casing pools, independent retreaders serving regional fleet accounts, and specialty compound suppliers licensing proprietary rubber formulations. Strategic moves concentrate on backward integration into casing recovery networks and technology licensing partnerships for hot-cure process automation.
Within the integrated manufacturer tier, Bridgestone Corporation, Michelin, and Goodyear Tire & Rubber Company exemplify archetypes differentiated by supply chain configuration. Bridgestone leverages captive casing networks to dominate premium retread output. Michelin occupies a position anchored in proprietary rubber compound formulations extending casing life across multiple retread cycles. Goodyear sits within the scale-driven segment, operating high-volume retread plants serving national fleet accounts with consistent turnaround times.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin |
| Goodyear Tire & Rubber Company |
| Continental AG |
| Marangoni S.p.A. |
| Southern Tire Mart |
| Sumitomo Rubber Industries |
| Pirelli |
| Vipal Rubber |
| Others |
Supply Flow & Price Mechanics
ISO 9001 certification gates both supply qualification and price differentiation simultaneously, with accredited retreaders commanding premium positioning in fleet procurement tenders while non-certified operators compete on commodity spot pricing for fragmented owner-operator demand.
Pricing Analysis
Certification level creates the primary spread across pricing tiers, with ISO 9001-accredited retreaders capturing fleet service contracts at premium-mid-economy pricing differentiation while independent plants compete on per-unit transactional spot pricing for degraded casing stock. Brand premium from captive casing networks like Bridgestone's adds further price separation from regional independents. Pricing pressure stems from natural rubber feedstock volatility compressing margin predictability for compound-dependent operators. Fleet operators with national accounts show least price sensitivity due to total cost of ownership analytics, while individual owner-operators drive commodity tier competition.
Supply Chain Analysis
Container availability on Southeast Asian trade lanes directly impacts natural rubber compound costs, with port congestion at Singapore and Port Klang feeding into margin structures for formulation-dependent retreaders. Supply concentrates in Thailand, Indonesia, and Malaysia for natural rubber feedstocks, with secondary concentration in Germany and the United States for steel belt reinforcement and curing equipment. Raw material dependencies rest on natural rubber latex, synthetic polymer blends, and steel bead wire. Single-source vulnerability runs through Southeast Asian rubber plantations exposed to climate disruption. Distribution runs through captive fleet recovery networks for premium tiers and independent dealer channels for price-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a commercial vehicle replacement cycle recovery, with fleet utilization rates and highway freight volumes serving as the cyclical driver justifying medium-term positioning.
For Market Incumbents: Compound defensive positioning through backward integration into casing recovery networks, locking in premium fleet supply contracts before independent retreaders achieve ISO 9001 accreditation. Expand hot-cure automation capacity in the I-80 corridor to compress turnaround times for refrigerated transport national accounts. Certification investment represents the critical lever for maintaining procurement access against emerging compound specialists.
For New Entrants and Emerging Players: ANVISA fast-track certification in Brazil opens white-space access as national logistics operators consolidate from fragmented owner-operator structures toward managed fleet models. Target São Paulo state fleet formalization with sensor-enabled predictive retreading bundled into maintenance service contracts. Municipal bus procurement in Germany and the Netherlands offers secondary penetration through EU Green Deal sustainability-weighted tenders.
For Investors and Strategic Acquirers: EU carbon border adjustment implementation reshapes the acquisition landscape, favoring retread manufacturers with documented lifecycle emissions advantages over virgin tire imports. Mid-cap specialists with captive casing pools and compound formulation capabilities present viable targets within a five-to-ten year circular economy transition window. Monitor EPA SmartWay verification expansion into additional vehicle classes as the inflection signal for demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Casing Recovery Networks | Captive casing supply locks in premium fleet procurement contracts against independent competitors. |
| Hot-Cure Process Automation Investment | Automated curing press deployment compresses turnaround variability for national refrigerated transport accounts. |
| EU Carbon Border Adjustment Alignment | Lifecycle emissions documentation secures preferential positioning against virgin tire imports under emerging regulations. |
| Sensor-Enabled Predictive Retreading Partnership | Tire pressure monitoring integration enables just-in-time scheduling for cold chain logistics operators. |
| Brazilian Fleet Formalization Joint Venture | São Paulo logistics consolidation creates addressable demand from fragmented owner-operator conversion. |
Methodological Framework
The analysis maps heavy truck, bus, passenger vehicle, and light truck retread segments, each validated through fleet procurement directors, retread plant operations managers, compound formulation chemists, and aftermarket distribution channel heads. Primary fieldwork combined with secondary validation from U.S. EPA SmartWay verification databases, ECHA REACH compliance filings, ANVISA commercial vehicle standards, and customs trade data for natural rubber imports. Bottom-up casing flow modeling and top-down fleet spend aggregation provided cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by vehicle class, end-user procurement sophistication, material composition tier, and operating environment severity. CAGRs derived from replacement cycle compression rates, fleet formalization trajectories, and regulatory adoption curves. Industry-specific inputs included commercial vehicle mileage data, casing recovery rate assumptions, and compound R&D intensity by manufacturer tier.
Decision-makers should treat outputs as directional under sustained EPA SmartWay verification expansion and EU extended producer responsibility implementation; material deviation in regulatory timelines or natural rubber supply disruption would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Alloy Wheels Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Global High Performance Tires Market
Tires and Wheels
Construction Machinery Tires Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Global Advanced Tires Market
Tires and Wheels
Automotive Airless Tire Market