
 Europe 2-Wheeler Replacement Tire Market | 2026-2036
Europe 2-Wheeler Replacement Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Europe 2-Wheeler Replacement Tire Market Foresight
Qualified tire technician availability across Southern Europe is collapsing, forcing service networks to compress training pipelines and automate mounting procedures. Bridgestone leverages its European technical center network to sustain certified installer programs in Spain and Portugal. Michelin anchors premium replacement demand through its Road tire portfolio, which dominates touring segments across Alpine corridors. Continental competes on integrated sensor-ready tire architectures that align with connected motorcycle platforms from German OEMs.
Europe 2-Wheeler Replacement Tire denotes pneumatic tires engineered for motorcycles, scooters, and mopeds operating on European road and trail surfaces, typically constructed from natural and synthetic rubber compounds with steel or aramid belt reinforcement, designed to deliver wet-grip performance, load-bearing capacity, and wear resistance under variable continental climate conditions. The product serves commercial mobility, recreational touring, and urban commuting applications where road safety regulations mandate minimum tread depth and speed rating compliance. Sport and Touring categories command the dominant share of replacement value, with Sport tires capturing margin pools from performance-oriented motorcyclists while Touring products sustain volume through multi-season durability claims. Radial construction is displacing bias-ply in mid-to-high displacement segments as manufacturers optimize contact patch stability for heavier European touring bikes.
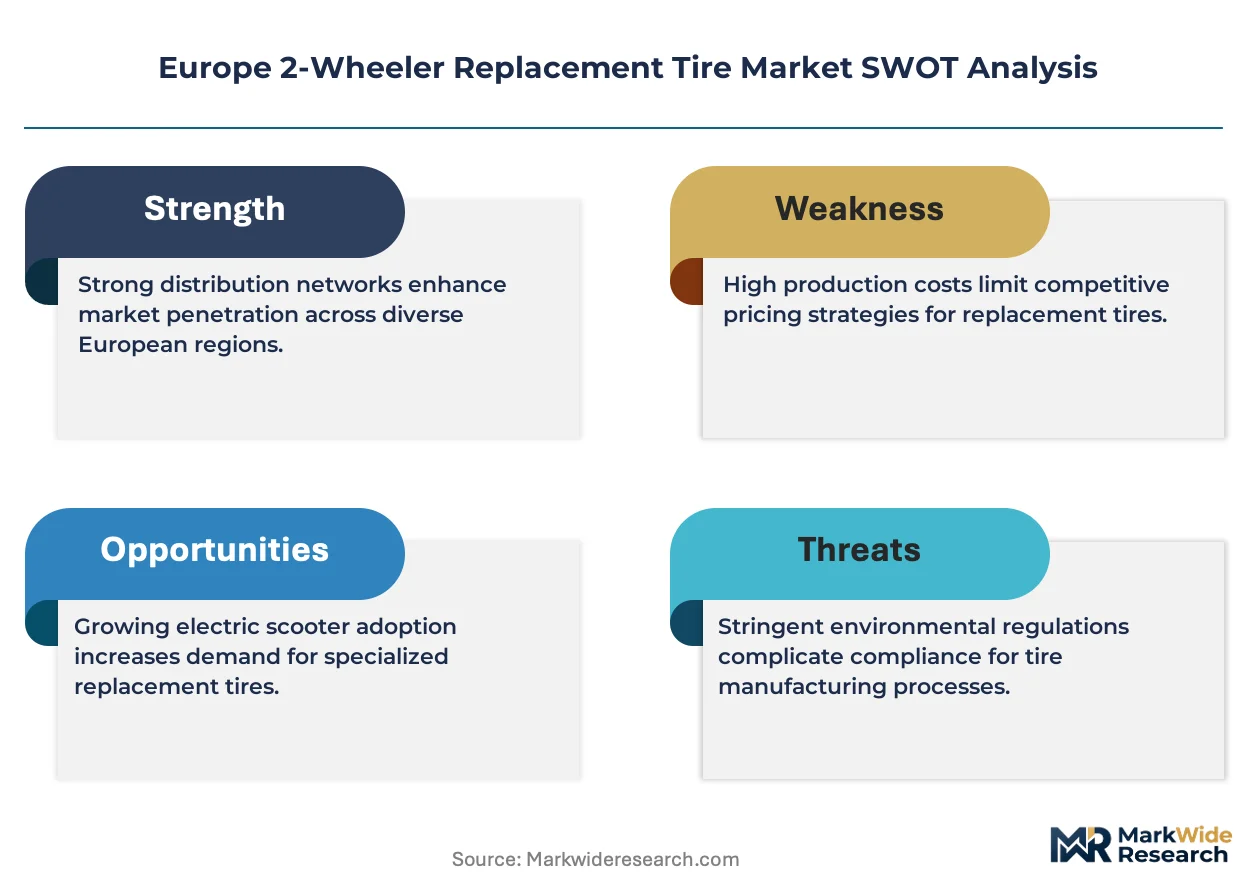
EMA chemical safety standards, REACH substance restrictions, and EU tire labeling requirements collectively dictate compound formulation choices, rolling resistance thresholds, and wet-braking performance claims across the European replacement channel. National type-approval frameworks in Germany, Italy, and France layer additional testing protocols that filter non-compliant imports from lower-cost manufacturing origins. Stakeholders must monitor regulatory alignment between EU sustainability mandates and the pace of retreading infrastructure investment as circular economy pressures intensify.
Market Dynamics
Courier and last-mile delivery fleets across urban Europe are compressing replacement cycles as commercial operators prioritize uptime over tire longevity, fundamentally altering volume distribution between consumer and fleet channels.
Growth Catalysts
- EU F-Gas Regulation:REACH-compliant rubber compound formulations are opening certified supplier status to manufacturers investing in sustainable chemistry, redirecting procurement toward compliant producers.
- Connected motorcycle platforms:German OEM sensor architectures are mandating tire-integrated telemetry, creating pull-through demand for sensor-ready replacement products.
- Alpine touring corridors:Multi-season durability claims from premium road tire portfolios are sustaining above-average replacement frequency among recreational motorcyclists in Switzerland, Austria, and northern Italy.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply concentration exposes European compounders to input cost swings that compress margin pools on economy-tier products.
- REACH substance restrictions:ECHA candidate list updates are forcing reformulation cycles that extend R&D timelines and raise certification costs for smaller importers.
- Retreading infrastructure underinvestment:Circular economy mandates from the EU Green Deal lack matching capital deployment, leaving commercial fleets without cost-competitive remanufacturing options.
Strategic Opportunities
- Portugal and Spain service networks:Collapsing qualified technician availability creates whitespace for automated mounting equipment and compressed training pipelines.
- CSRD-aligned sustainability reporting:Corporate sustainability disclosure requirements are creating procurement preference for tire suppliers with verified lifecycle carbon data.
- Radial-bias hybrid architectures:Convergence of aramid belt stability with bias-ply compliance is enabling new product categories for mid-displacement urban commuters.
Industry Challenges
- Certified installer pipeline compression:Bridgestone's technical center network is absorbing training capacity strain that independent distributors cannot replicate.
- EU tire labeling compliance timelines:Wet-grip and rolling resistance retesting protocols are delaying product launches and fragmenting inventory across national type-approval frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe 2-Wheeler Replacement Tire Market |
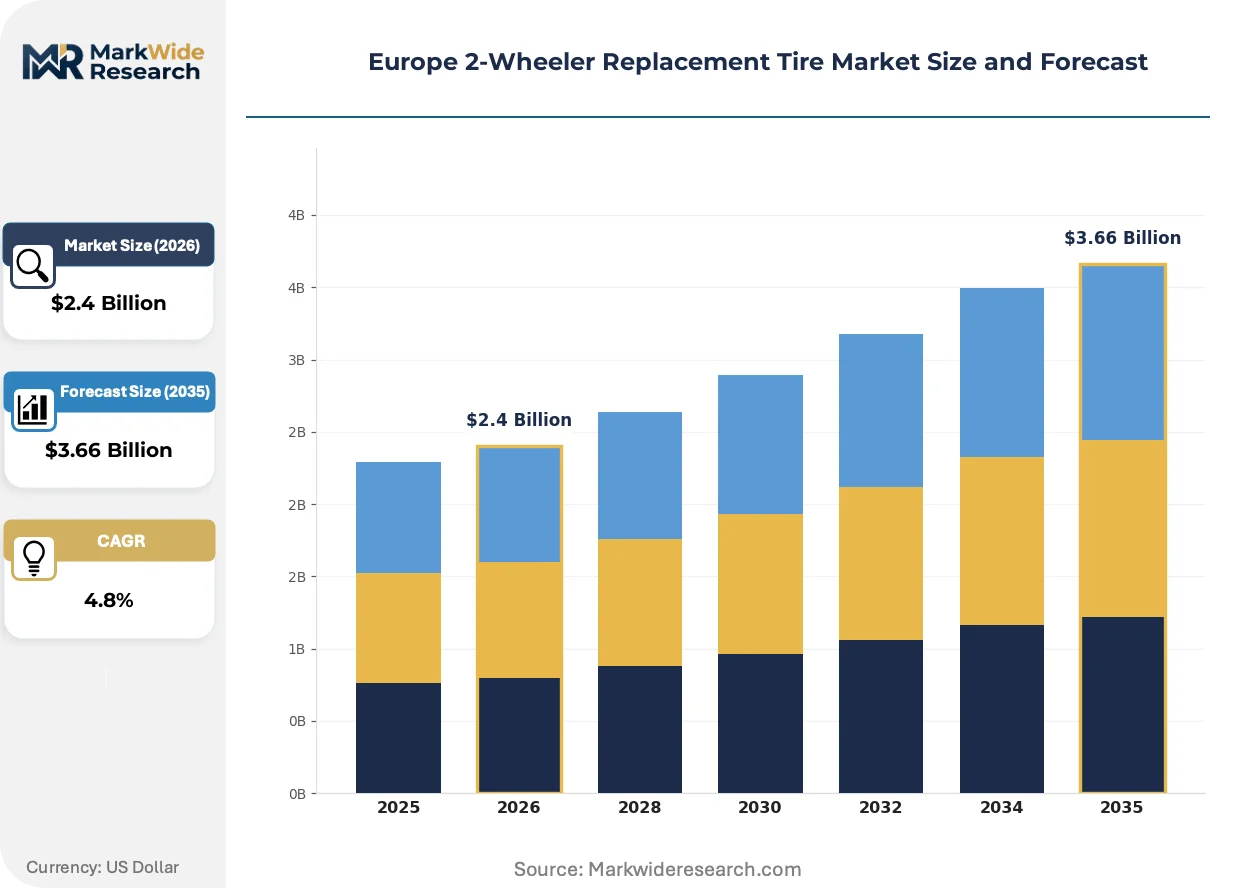
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cruiser, Sport, Touring, Off-Road Material: Rubber, Tubeless, Bias-Ply, Radial End User: Motorcyclists, Delivery Services, Rental Services, Recreational Users Distribution Channel: Online Retail, Specialty Stores, Service Centers, Wholesale |
| Companies Covered | Bridgestone, Metzeler, Michelin, Apollo Tyres, Dunlop, Pirelli, Goodyear, Yokohama, Continental, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe 2-Wheeler Replacement Tire Market Shifts & Advancements
European replacement tire architecture is pivoting toward sensor integration and sustainable chemistry as regulatory thresholds harden and fleet telematics mature.
Aramid-reinforced radial constructions are displacing traditional bias-ply designs in mid-to-high displacement segments. Alpine touring motorcyclists operating heavier European bikes are adopting these architectures for contact patch stability under variable load conditions. The shift is compressing the addressable market for conventional cross-ply products below 400cc displacement categories.
REACH substance restrictions are forcing rubber compounders to eliminate polycyclic aromatic hydrocarbons from tread formulations. ECHA enforcement of SVHC thresholds is raising manufacturing costs for non-compliant imports from lower-cost origins. German KBA type-approval protocols are filtering non-compliant products from the replacement channel faster than southern European frameworks.
Fleet procurement teams are consolidating supplier relationships around integrated service contracts that bundle tire supply with mounting and pressure monitoring. Commercial courier operators in Paris and Berlin are displacing transactional spot purchases with annual framework agreements. This concentration is squeezing independent distributors that lack national coverage or digital fleet management interfaces.
Europe 2-Wheeler Replacement Tire Market Segmentation
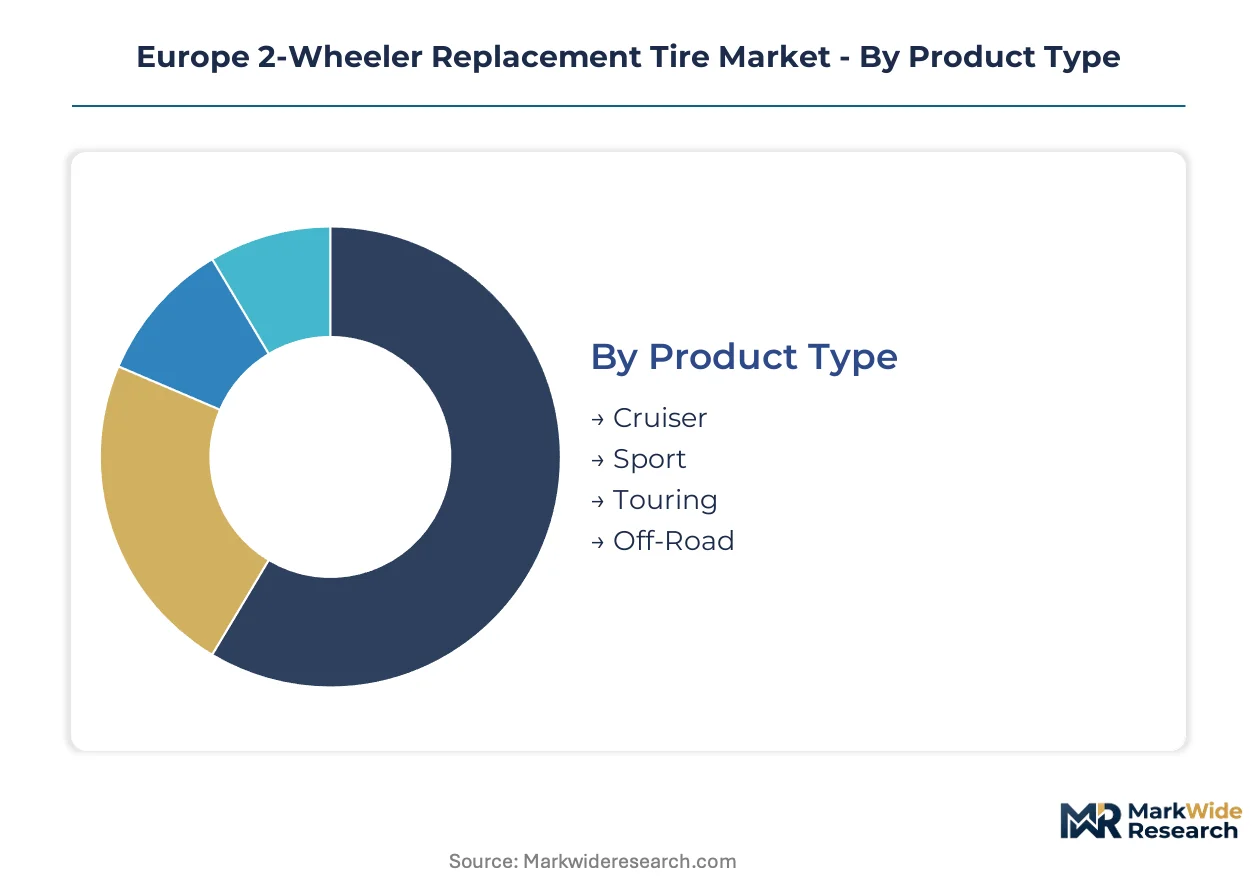
Replacement tire demand fragments across distinct performance tiers and user profiles. European regulatory frameworks compound this complexity by filtering non-compliant products from specific channels. Understanding segment boundaries reveals where procurement power concentrates and where margin pools shift.
Product Type:
REACH-compliant rubber formulations and wet-grip labeling thresholds favor architectures engineered for multi-season durability.
- Sport:Aramid-belted radial constructions optimize contact patch stability for high-displacement machines. German and Italian performance motorcyclists sustain premium replacement cycles through shorter wear intervals. REACH SVHC thresholds raise compound costs, compressing margin pools on economy-tier sport products.
- Touring:Multi-compound tread designs balance highway mileage with wet-weather safety across Alpine corridors. Swiss and Austrian recreational riders generate above-average replacement frequency through extended seasonal use. ECHA enforcement of rolling resistance claims filters non-compliant imports from southern European distribution.
- Cruiser:Bias-ply bias dominates displacement categories below 400cc through compliance cost advantages.
- Off-Road:Knobby tread patterns face fragmented type-approval across German KBA and French ANSM frameworks.
Touring handles the majority of throughput; Sport is the fastest mover on share.
Material:
Construction method determines compliance pathway and margin capture potential across the replacement channel.
- Radial:Steel and aramid belt reinforcement enables heavier European touring bike compatibility. German OEM sensor architectures mandate integrated telemetry compatibility, pulling demand toward sensor-ready radial products. Alpine corridor dealers report radial displacement of bias-ply above 400cc categories.
- Tubeless:Puncture-sealing formulations reduce roadside failure rates for commercial courier fleets. Paris and Berlin last-mile operators compress replacement cycles through uptime prioritization. EU F-Gas Regulation compliance adds certification overhead for tubeless sealant chemistry.
- Rubber:Natural and synthetic compound blends face Southeast Asian supply concentration risks.
- Bias-Ply:Cross-ply construction retains cost advantages in sub-400cc urban commuter segments.
Radial handles the majority of throughput; Tubeless is climbing the fastest on share.
End User:
Procurement behavior diverges sharply between transactional consumers and contract-consolidated fleet operators.
- Delivery Services:Commercial courier fleets in urban France and Germany displace spot purchases with annual framework agreements. Integrated service contracts bundle tire supply with mounting and pressure monitoring, squeezing independent distributors lacking digital fleet interfaces. Compressed replacement cycles prioritize uptime over longevity.
- Motorcyclists:Individual owners exhibit price sensitivity toward economy-tier products while premium segments sustain brand loyalty. Italian and German commuter density generates above-average replacement frequency through year-round riding.
- Recreational Users:Seasonal Alpine touring concentrates demand in Switzerland, Austria, and northern Italy.
- Rental Services:Fleet standardization pressures drive consolidation around multi-season durability claims.
Delivery Services handles the majority of throughput; Motorcyclists is gaining share fastest.
Distribution Channel:
Channel structure reflects technician availability constraints and fleet digitalization requirements.
- Service Centers:Automated mounting equipment addresses collapsing qualified technician availability across Spain and Portugal. Bridgestone's technical center network absorbs training capacity strain that independents cannot replicate. CSRD-aligned sustainability reporting creates procurement preference for suppliers with verified lifecycle carbon data.
- Specialty Stores:Premium road tire portfolios dominate touring segments through face-to-face durability claims. Alpine corridor presence determines market access for performance-oriented products.
- Online Retail:Digital platforms fragment inventory across national type-approval frameworks.
- Wholesale:Bulk procurement consolidates around integrated sensor-ready tire architectures.
Service Centers handles the majority of throughput; Specialty Stores is expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German motorcyclists replace tires more frequently than French or Italian riders due to year-round commuting patterns and stricter KBA inspection protocols, while Spanish and Portuguese markets lag in technician availability and automated service infrastructure.
Germany
KBA type-approval frameworks enforce faster replacement cycles among safety-conscious touring motorcyclists. The EU F-Gas Regulation drives reformulation investments by compounders serving the replacement channel. Bavaria's Alpine corridor concentrates premium radial demand from multi-season recreational riders.
Italy
Performance motorcyclists in Lombardy and Emilia-Romagna sustain above-average sport tire turnover through shorter wear intervals. REACH SVHC thresholds raise import barriers for non-compliant Asian manufacturers. Milan's courier fleets compress replacement cycles through uptime-focused procurement.
France
Paris last-mile delivery operators displace spot purchases with annual framework agreements bundling supply and mounting. ANSM enforcement of wet-grip labeling filters economy-tier imports from southern European distribution. Lyon and Marseille service networks face technician pipeline constraints.
Spain
Collapsing qualified technician availability forces service centers toward automated mounting equipment. ECHA candidate list updates extend R&D timelines for compounders reformulating tread formulations. Madrid and Barcelona commercial fleets drive tubeless adoption for puncture-sealing uptime benefits.
Switzerland
Alpine touring culture generates premium replacement frequency through extended seasonal riding across mountain corridors. Swissmedic-aligned chemical safety standards exceed baseline EU thresholds for imported compounds. Zurich and Geneva dealers report radial displacement of bias-ply above 400cc categories.
Europe 2-Wheeler Replacement Tire Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium positioning through certified installer networks and sensor-ready architectures while specialists compete on compound formulation agility and regional service density. The structure rewards backward integration into sustainable chemistry and digital fleet interfaces. Three archetypes dominate: integrated multinational compounders, regional specialists with Alpine corridor presence, and sensor-technology integrators aligned with German OEM platforms. Competitive moves concentrate on technical center expansion and automated service equipment deployment.
Among the integrated multinational tier, Bridgestone, Michelin, and Continental occupy positions reflecting distinct strategic anchors. Bridgestone exemplifies the technical center network archetype with certified installer programs absorbing training capacity strain. Michelin represents premium portfolio positioning through multi-season durability claims. Continental sits within the sensor-ready architecture vector aligned with connected motorcycle platforms.
| Leading Market Players |
|---|
| Bridgestone |
| Metzeler |
| Michelin |
| Apollo Tyres |
| Dunlop |
| Pirelli |
| Goodyear |
| Yokohama |
| Continental |
| Others |
Supply & Pricing Matrix
Annual framework agreements between Paris courier fleets and tire distributors lock in supply access while dampening spot-price volatility across the replacement channel. These contracts bundle mounting services with pressure monitoring, compressing margins for independents lacking national coverage.
Pricing Analysis
Long-term offtake contracts dominate fleet procurement, while individual motorcyclists transact on spot markets. Three-tier pricing structure across premium, standard, and economy levels separates sensor-ready radial products from bias-ply alternatives. Cost compression in economy-tier sport tires stems from REACH SVHC compliance overhead. Fleet operators exhibit lowest price sensitivity due to uptime prioritization, while recreational riders in Alpine corridors absorb premium durability claims.
Supply Chain Analysis
Inventory lead times for aramid belt reinforcement stretch from Southeast Asian rubber plantations through German compounding facilities. Natural rubber draws from Thailand and Indonesia, with synthetic polymer feedstocks anchored in German petrochemical corridors. Single-source vulnerability concentrates in Southeast Asian latex supply. Distribution runs through Bridgestone's technical center network and independent service centers across Iberia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected motorcycle platforms from German OEMs are disrupting replacement tire specifications, mandating sensor-integrated architectures that filter non-compliant suppliers from the channel.
For Market Incumbents: Fortify certified installer networks across Spain and Portugal where technician scarcity threatens service capacity. Absorb training pipeline strain through automated mounting equipment deployment. Defend margin pools by deepening backward integration into REACH-compliant rubber chemistry before ECHA candidate list updates force second reformulation cycles. For New Entrants and Emerging Players: KBA type-approval fast-track positions unlock German market access faster than southern European frameworks. Target Portugal's collapsing qualified technician availability with automated service equipment partnerships. Penetrate through digital fleet management interfaces that Paris and Berlin courier operators now require. For Investors and Strategic Acquirers: Regional specialists with Alpine corridor service density represent consolidation targets as procurement consolidates around integrated contracts. Five-to-ten year viability hinges on circular economy infrastructure deployment matching EU Green Deal mandates. Monitor retreading capital allocation as the inflection signal for cost-competitive remanufacturing options.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Ready Tire Architecture Development | Aligns replacement products with BMW and KTM connected motorcycle platforms. |
| REACH-Compliant Compound Reformulation | Eliminates polycyclic aromatic hydrocarbons before ECHA enforcement hardens. |
| Automated Mounting Equipment Deployment | Addresses technician scarcity across Madrid and Barcelona service networks. |
| Technical Center Network Expansion | Replicates Bridgestone's certified installer model in Portugal and Spain. |
| Digital Fleet Management Interface Launch | Captures Paris and Berlin courier procurement shifting to annual frameworks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tire R&D directors, fleet procurement managers at Paris and Berlin courier operators, Alpine corridor dealership owners, and ECHA regulatory affairs specialists; and secondary validation against EU tire labeling databases, KBA type-approval registries, customs import records, and ECHA SVHC candidate list updates. Bottom-up volume estimates triangulated against top-down replacement cycle assumptions.
Across the projection horizon, the analytical framework modeled demand by product architecture, displacement category, end-user procurement behavior, and national regulatory cluster. CAGRs derived from replacement frequency variations between commercial fleet uptime prioritization and recreational seasonal use patterns. Inputs included Southeast Asian natural rubber supply forecasts and German OEM sensor platform rollout timelines.
Underlying assumptions cover REACH compliance timelines and fleet telematics adoption curves, with deviation risk concentrated in ECHA substance restriction updates and retreading infrastructure investment pacing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Wheel Market
Tires and Wheels
North America Tire Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
Tire Cord Market
Tires and Wheels
Europe Agricultural Tires Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Elastic Polyurethane Wheels Market
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
E-Bike Tire Market