
 Truck and Bus Radial (TBR) Tire Market | 2026-2036
Truck and Bus Radial (TBR) Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Truck and Bus Radial (TBR) Tire Market Analysis
Fleet buyer concentration is hardening across North American and European logistics networks, with large freight carriers consolidating procurement through direct OEM partnerships and national service contracts. Michelin leverages its integrated fleet solutions business to sustain long-term supply agreements with major hauliers. Bridgestone Corporation anchors its position through Bandag retreading operations that extend tire life cycles for cost-sensitive operators. Continental AG competes via its ContiConnect digital tire monitoring platform, which controls replacement timing and reduces unplanned downtime for concentrated buyer bases.
Truck and Bus Radial tires are steel-belted pneumatic tires engineered with multiple cord plies arranged at 90 degrees to the direction of travel, enabling superior load distribution, heat dissipation, and tread wear characteristics under sustained highway speeds exceeding 100 km/h. Their primary commercial purpose is to reduce rolling resistance and improve fuel economy for heavy-duty vehicles operating at maximum gross vehicle weight ratings across extended duty cycles. The drive axle segment dominates value capture due to higher torque transfer demands and accelerated tread wear rates, while specialty configurations for mining and logging applications command premium positioning through reinforced sidewall compounds and deeper tread patterns. Long-distance haul applications concentrate the largest volume pools, though urban transport segments are gaining structural importance as last-mile electrification and bus fleet renewals accelerate replacement frequencies.
The US Department of Transportation enforces Federal Motor Vehicle Safety Standard 119 for truck tire performance, while the EPA's SmartWay program certifies low-rolling-resistance radials for fuel efficiency compliance in commercial fleets. Europe's REACH regulation restricts aromatic oils in tire compounds, compelling reformulation investments that reshape supplier competitiveness across the value chain. China's GB/T 4502 standard mandates uniform tire labeling for rolling resistance and wet grip, directly influencing product development priorities for manufacturers serving Asian markets. Stakeholders must monitor how impending EU tire wear particle regulations and California's advancing per- and polyfluoroalkyl substance restrictions will force material transitions and testing protocol overhauls.
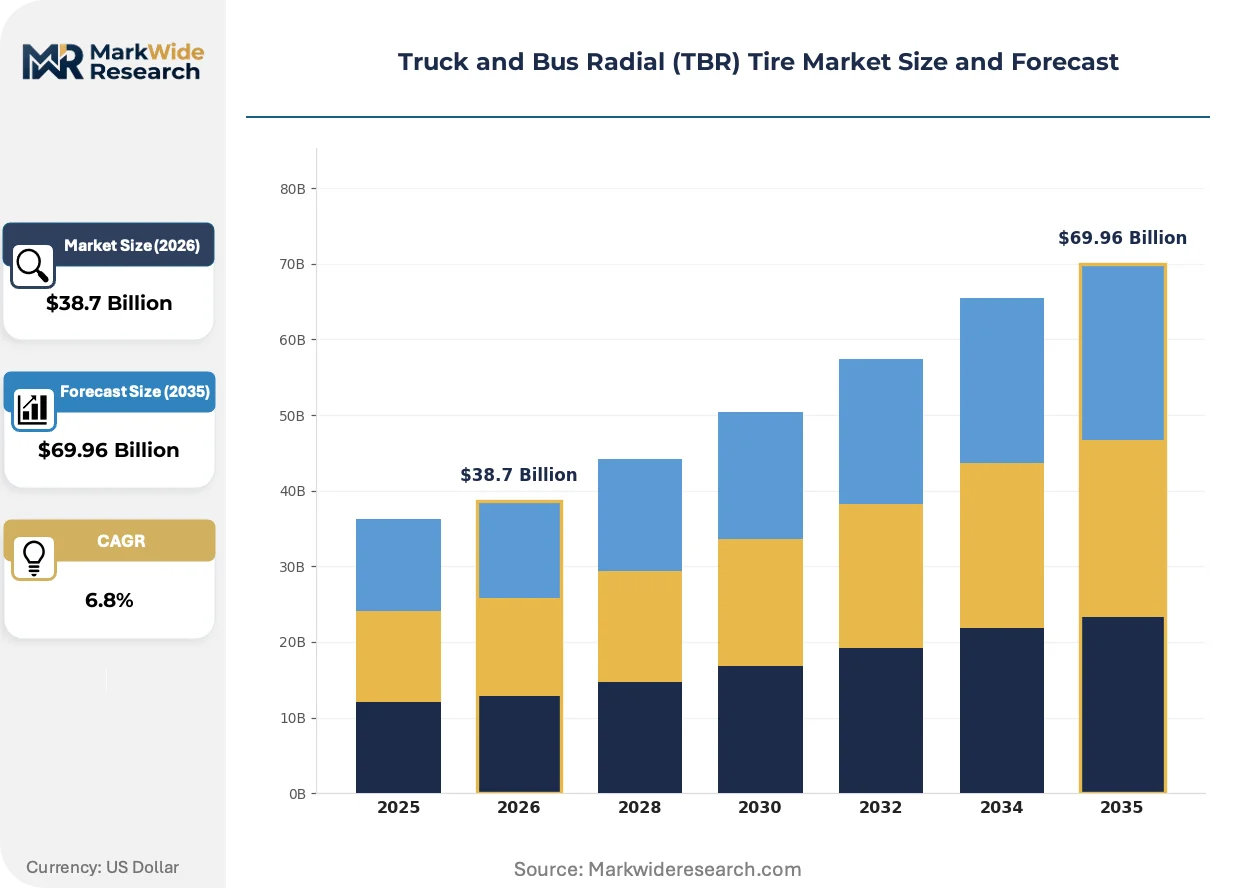
Market Dynamics
Fuel efficiency mandates and rolling resistance labeling regimes are forcing simultaneous reformulation of tire compounds and restructuring of supply contracts across heavy-duty freight networks.
Growth Catalysts
- EPA SmartWay certification:Low-rolling-resistance radials qualify for preferential fleet procurement in US long-haul corridors, locking in replacement demand from compliance-focused operators.
- China's dual carbon goals:MIIT enforcement of GB/T 4502 labeling accelerates domestic scrappage of bias-ply inventories and redirects fleet procurement toward certified radial products.
- Last-mile electrification:Urban bus fleet renewals in India and Southeast Asia generate incremental replacement frequencies as electric drivetrains impose distinct torque and wear profiles on drive axle configurations.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply concentration exposes compounders to input cost swings that compress margin buffers on standard-duty product lines.
- REACH aromatic oil restrictions:ECHA-mandated reformulation of tire compounds forces European manufacturers to absorb R&D transition costs without immediate pass-through mechanisms.
- Retread substitution economics:Bandag and independent retreading operations extend casing life cycles, displacing one-in-five new tire purchases among cost-sensitive regional hauliers.
Strategic Opportunities
- Delhi-Mumbai Industrial Corridor freight density:Apollo Tires and Bridgestone Corporation production scale-up positions suppliers to capture volume from India's projected commercial vehicle fleet expansion.
- ContiConnect digital monitoring convergence:Integration of tire pressure sensors with fleet telematics platforms enables predictive replacement scheduling and service contract bundling.
- EU tire wear particle regulations:Impending ECHA limits on microplastic emissions create first-mover advantage for manufacturers with advanced tread compound formulations already in validation.
Industry Challenges
- Compound engineering talent scarcity:Formulation chemists with simultaneous expertise in silica-silane coupling and sustainable filler integration command premium compensation that strains mid-tier R&D budgets.
- Homologation timeline compression:Accelerated GB standard revisions in China force simultaneous re-testing of wet grip and rolling resistance performance, extending product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck and Bus Radial (TBR) Tire Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Position, Drive, Trailer, Specialty End User: Freight Carriers, Public Transport, Construction, Logistics Application: Long-Distance Haul, Urban Transport, Off-Road, Mixed Use Distribution Channel: Direct Sales, Retail, Online, Wholesaler |
| Companies Covered | Continental AG, Apollo Tires, Michelin, Pirelli, Sumitomo Rubber Industries, Ltd., Bridgestone Corporation, Yokohama Rubber Corporation, Giti Tire, Goodyear Tire & Rubber Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck and Bus Radial (TBR) Tire Market Emerging Trajectories
Active tread compound engineering and embedded sensor architectures are restructuring how tire performance is validated, monetized, and integrated into fleet operating systems.
Silica-reinforced tread formulations with advanced silane coupling agents are overtaking carbon-black-dominant compounds in drive axle applications across European and North American highway fleets. Premium hauliers specify these compounds for 15-20 percent rolling resistance reduction under full load conditions. The shift is compressing competitive differentiation around laboratory-certified fuel economy metrics rather than historical brand loyalty.
REACH regulation extension to tire wear particles is compelling European compounders to accelerate bio-based oil and alternative filler validation programs before 2027 enforcement windows. Manufacturers serving EU markets are reconfiguring supply contracts to lock in sustainable natural rubber traceability from Indonesian and Malaysian plantations. The regulatory pressure is most acute for high-volume standard-duty lines where reformulation cost absorption is least transferable to fleet buyers.
Fleet procurement consolidation through direct OEM partnerships is displacing fragmented distributor relationships in North American long-haul networks. Large carriers now negotiate national service contracts bundling tire supply, mounting, and roadside assistance through single-source agreements. This concentration is most visible among refrigerated and dry van operators running dedicated lanes between Chicago, Dallas, and Southern California distribution hubs.
Truck and Bus Radial (TBR) Tire Market Segmentation
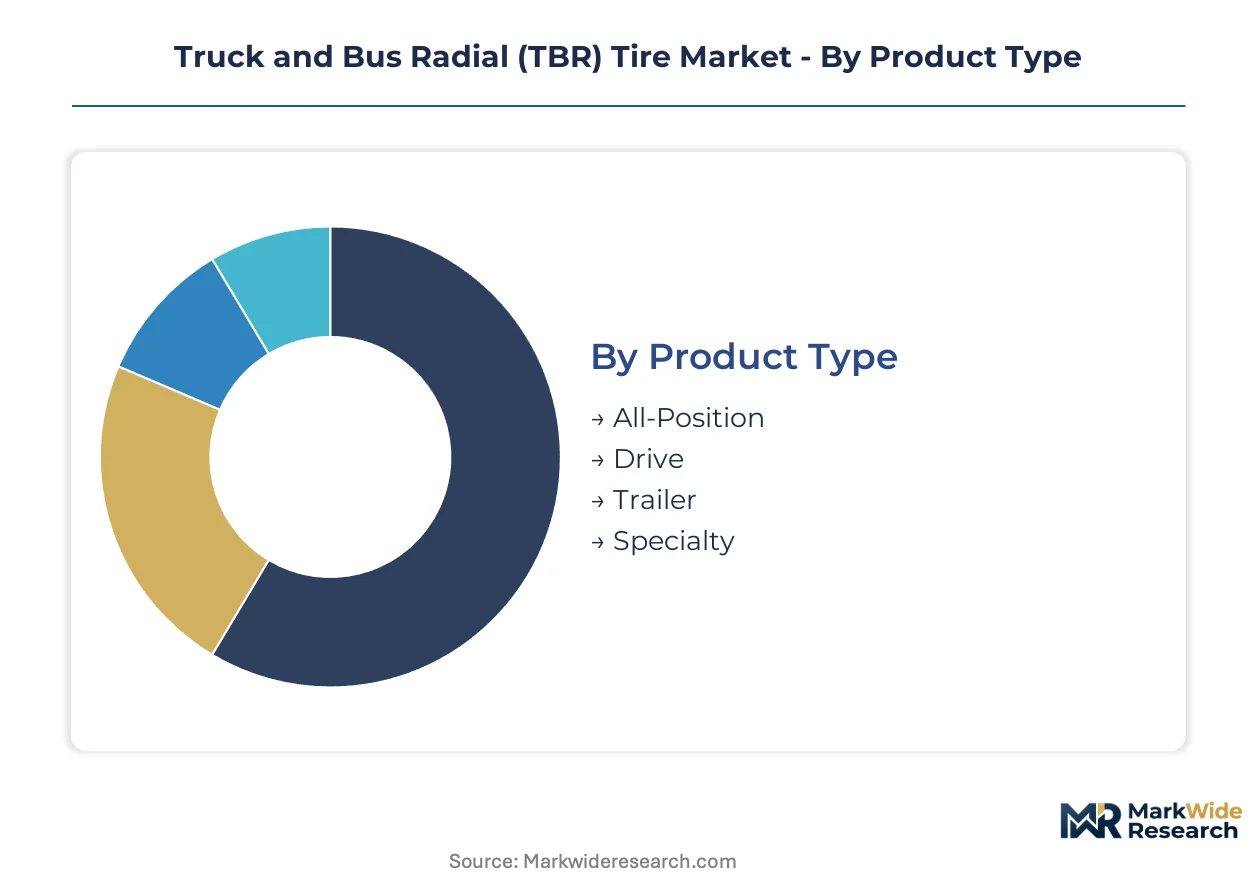
TBR tire procurement patterns diverge sharply across duty cycles and buyer types, with axle-specific engineering requirements and fleet consolidation trends reshaping how manufacturers configure product portfolios and channel strategies.
Product Type:
Supply concentration among integrated manufacturers favors multi-position product families that share casing architectures across axle configurations.
- Drive:Multi-ply steel-belted construction with reinforced shoulder compounds withstands sustained torque transfer and heat buildup under maximum gross vehicle weight. Demand concentrates in North American long-haul fleets where EPA SmartWay certification mandates drive replacement cycles for fuel efficiency compliance.
- Trailer:Free-rolling axle position enables shallower tread depths and lighter carcass designs optimized for irregular wear resistance rather than traction. European freight corridors exhibit strongest procurement volumes as REACH-regulated compounds penetrate fleet specifications ahead of wear particle enforcement.
- All-Position:Versatile tread patterns and carcass designs accommodate mixed fleet inventories where axle-specific stocking is uneconomical.
- Specialty:Reinforced sidewalls and cut-resistant compounds serve mining and logging applications with severe service requirements.
Drive configurations absorb the bulk of installed capacity; Specialty is expanding most quickly as extractive industries upgrade equipment specifications.
End User:
Buyer scale and procurement sophistication create distinct service requirements that segment supplier relationships.
- Freight Carriers:Large fleet operators negotiate national service contracts bundling tire supply, mounting, and roadside assistance through direct OEM partnerships. India's Delhi-Mumbai Industrial Corridor freight density is accelerating procurement volumes as Apollo Tires and Bridgestone scale production to serve corridor expansion.
- Public Transport:Municipal and state bus authorities specify low-floor and electric bus configurations with distinct load distribution and torque profiles that accelerate replacement frequencies.
- Construction:Project-based demand cycles and mixed on-off highway duty require durable all-position products with damage resistance.
- Logistics:Third-party fulfillment operators prioritize rapid turnaround and national coverage over unit economics.
Freight Carriers command the deepest supplier integration; Public Transport is climbing the fastest as electrification reshapes fleet specifications.
Application:
Duty cycle intensity and operating environment determine compound formulation priorities and replacement intervals.
- Long-Distance Haul:Sustained highway speeds exceeding 100 km/h maximize rolling resistance sensitivity and fuel economy returns on premium silica-reinforced compounds.
- Urban Transport:Stop-start duty cycles and curbside damage exposure favor reinforced sidewall designs with scrub-resistant tread patterns. Last-mile electrification in India and Southeast Asia is generating incremental replacement demand as electric drivetrains impose distinct torque and wear profiles.
- Off-Road:Severe service conditions demand maximum tread depth and cut-resistant compounds with reduced speed ratings.
- Mixed Use:Variable duty cycles require compromise tread designs that sacrifice peak highway efficiency for damage tolerance.
Long-Distance Haul retains the largest volume base; Urban Transport is gaining share fastest as fleet electrification accelerates replacement frequencies.
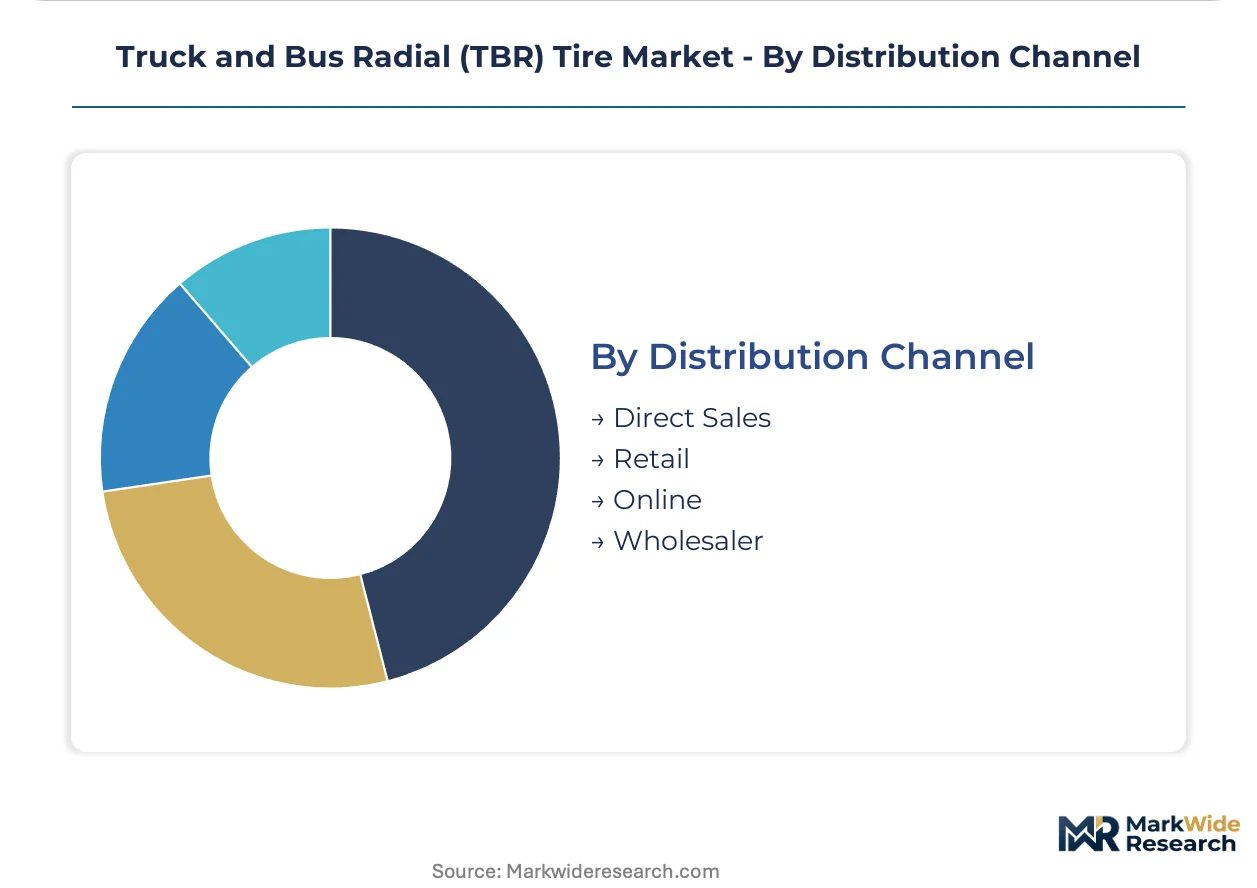
Distribution Channel:
Channel economics reflect fleet size and geographic concentration of buyer bases.
- Direct Sales:National account teams serve large carriers with integrated fleet solutions bundling tires, monitoring, and maintenance.
- Retail:Independent dealers and company-owned stores capture owner-operator and small fleet demand requiring immediate availability.
- Online:Digital procurement platforms emerge for standardized specifications with predictable replacement timing.
- Wholesaler:Regional distributors stock breadth for fragmented buyer bases in secondary markets.
Direct Sales captures the highest value per transaction; Online is expanding most quickly as fleet telematics integration enables predictive procurement workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural rubber plantations in southern Thailand and Indonesia anchor feedstock supply for Asian tire manufacturing. Thai processing facilities supply compounders across Southeast Asia. Indonesian smallholder cooperatives feed regional mixing operations.
United States
Long-haul freight corridors between Chicago, Dallas, and Southern California drive replacement demand from refrigerated and dry van operators. EPA SmartWay certification mandates low-rolling-resistance radials for fleet compliance. The I-35 corridor through Texas concentrates procurement volume from dedicated lane operators.
China
Domestic commercial vehicle fleet expansion and dual carbon policy enforcement redirect procurement from bias-ply to certified radial products. NMPA enforcement of GB/T 4502 labeling standards accelerates scrappage of non-compliant inventories. Shandong Province hosts the densest concentration of tire manufacturing capacity serving both domestic and export markets.
India
Freight density on the Delhi-Mumbai Industrial Corridor generates concentrated demand from heavy-duty hauliers. BIS alignment with rolling resistance labeling protocols shapes procurement specifications for fleet operators. Gujarat and Maharashtra host scaled production facilities from Apollo Tires and Bridgestone Corporation serving corridor expansion.
Germany
REACH regulation enforcement restricts aromatic oils in tire compounds, compelling reformulation investments across European supply chains. ECHA-mandated transitions toward bio-based oils and alternative fillers reshape compound engineering priorities. The Baden-Württemberg industrial cluster anchors Continental AG's integrated tire and digital monitoring operations.
Brazil
Agricultural and mining freight growth drives demand for severe-service specialty configurations with reinforced sidewall compounds. ANVISA-aligned product registration requirements govern import and domestic manufacturing compliance. São Paulo state's industrial corridor concentrates distribution infrastructure serving the Mercosur heavy-duty vehicle market.
Truck and Bus Radial (TBR) Tire Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital service integration and sustainable compound validation. The vendor base stratifies around integrated manufacturers with captive R&D facilities, regional specialists with cost-optimized standard-duty lines, and technology-focused entrants embedding sensor architectures. Three archetypes dominate: full-line integrators bundling tires with fleet monitoring, retreading specialists extending casing life cycles, and compound innovators targeting regulatory-driven material transitions. Capacity expansion and strategic partnerships represent the dominant competitive moves reshaping supply relationships.
Among integrated European manufacturers, Continental AG exemplifies the full-line archetype through its digital monitoring convergence. Apollo Tires anchors the Asia-Pacific production scale-up serving corridor freight density. Bridgestone Corporation occupies a position spanning manufacturing integration and retreading operations through Bandag. Michelin represents the premium-tier positioning sustained through long-term fleet solutions contracting. Yokohama Rubber Corporation and Sumitomo Rubber Industries, Ltd. sit within the Japanese specialist tier with regional manufacturing footprints.
| Leading Market Players |
|---|
| Continental AG |
| Apollo Tires |
| Michelin |
| Pirelli |
| Sumitomo Rubber Industries, Ltd. |
| Bridgestone Corporation |
| Yokohama Rubber Corporation |
| Giti Tire |
| Goodyear Tire & Rubber Company |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap compounders in Southeast Asia anchor feedstock procurement through long-term plantation contracts, translating raw material cost stability into pricing discipline that multinational integrators struggle to match. Sovereign-backed Thai producers leverage state financing for capacity expansion, compressing margin buffers for independent European manufacturers facing REACH-mandated reformulation costs without comparable balance-sheet support.
Pricing Analysis
Volume capture concentrates in standard-duty lines where procurement consolidation among North American fleet operators compresses unit economics, while margin retention favors specialty mining configurations with reinforced sidewall compounds. Three-tier pricing structure across premium, standard, and economy levels reflects EPA SmartWay certification tiers and silica-silane compound grades. Cost compression in standard-duty segments is intensifying because retread substitution economics displace one-in-five new tire purchases among regional hauliers. Small owner-operators exhibit highest price sensitivity; large refrigerated carriers running dedicated I-35 lanes prioritize fuel economy certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian smallholder cooperatives feeding natural rubber processing facilities across Southeast Asia. Manufacturing gravity centers on Thailand, Indonesia, and China, with Thai processing facilities supplying compounders regionally. Compound engineering draws from natural rubber, synthetic rubber, and silica filler inputs. Tariff exposure on steel cord imports from China threatens carcass production economics for European manufacturers. Distribution runs through direct national account teams for large carriers, supplemented by independent dealer networks capturing fragmented owner-operator demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TBR tire market functions as a vertical-integration race where control over sustainable natural rubber traceability from Indonesian and Malaysian plantations determines long-term cost positioning and regulatory compliance capacity.
For Market Incumbents: Extend digital monitoring convergence through ContiConnect-style sensor architectures that lock in predictive replacement contracts with concentrated fleet buyers. Deepen backward integration into plantation traceability programs before EU tire wear particle enforcement accelerates sustainable filler requirements. Retread specialists like Bandag operations represent the primary substitution threat; vertical control over casing recovery networks defends replacement volume capture. For New Entrants and Emerging Players: Enter via specialty mining and logging configurations where reinforced sidewall compounds command premium positioning and incumbent R&D budgets are absorbed by standard-duty regulatory compliance. Target India's Delhi-Mumbai Industrial Corridor freight density where Apollo Tires and Bridgestone production scale-up has not yet saturated severe-service demand. Position through bio-based oil formulation partnerships with European compounders facing REACH-mandated aromatic oil restrictions. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European manufacturers with validated silica-silane coupling expertise but strained working capital from REACH reformulation investments. Long-term viability over a five-to-ten-year window hinges on securing plantation offtake agreements before sustainable natural rubber traceability becomes a procurement gate. Monitor GB/T 4502 standard revision timelines in China as inflection indicator for accelerated scrappage-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Traceability | Secures sustainable natural rubber supply chains for EU tire wear particle compliance ahead of ECHA enforcement. |
| Digital Monitoring Platform Deployment | Enables ContiConnect-style predictive replacement scheduling that bundles tire supply with fleet telematics contracts. |
| Specialty Compound Capacity Expansion | Captures premium positioning in mining applications where reinforced sidewall designs resist cut damage. |
| Retreading Network Consolidation | Extends casing life cycles through Bandag-style operations that displace new tire purchases among cost-sensitive operators. |
| SmartWay Certification Investment | Qualifies low-rolling-resistance radials for preferential procurement by EPA-compliant North American long-haul fleets. |
Methodological Framework
Multi-period observation of fleet procurement consolidation patterns, retread substitution rates, and GB standard enforcement timelines anchored the trend analysis, supplemented by interviews with fleet procurement directors, tire plant managers, compound R&D directors, and aftermarket service heads. Primary fieldwork triangulated against customs trade data, SEC filings from listed tire manufacturers, EPA SmartWay certification databases, and MIIT production statistics. Bottom-up volume builds across axle configurations and duty cycles converged with top-down macroeconomic freight projections.
Segment-weighting approaches distributed value capture across drive, trailer, all-position, and specialty product families, with additional modeling dimensions for long-distance haul versus urban transport duty cycles and electric bus torque profiles. CAGRs were derived from replacement frequency assumptions tied to fleet electrification penetration and regulatory scrappage incentives. Forecast inputs incorporated natural rubber price volatility scenarios and REACH reformulation cost absorption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under acute natural rubber supply disruption or accelerated EU tire wear particle enforcement ahead of validation timelines. Forecasts reflect assumptions documented across stakeholder interviews and secondary validation sources. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Steel Tire Cord Market
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Automotive Summer Tire Market
Tires and Wheels
Commercial Vehicles Tires Market
Tires and Wheels
Airless Tires Market
Tires and Wheels
Tire Protection Chains Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Wheel Market
Tires and Wheels
Global Aircraft Tire Market
Tires and Wheels
Wheel Cover Market