
 North America OTR Tire Market | 2026-2036
North America OTR Tire Market Size, Share, and Industry Trends Forecast 2026-2036
North America OTR Tire Market Intelligence
Multi-source procurement among fleet operators is rebalancing toward consolidated supplier relationships with fewer certified vendors. Bridgestone Corporation leverages its integrated manufacturing footprint across Tennessee and Mexico to anchor regional supply security. Michelin competes through premium radial technology leadership in ultra-large mining applications. The Goodyear Tire & Rubber Company sustains dealer network density across rural construction corridors.
North America OTR tires are engineered pneumatic or solid structures built with reinforced steel belts, specialized tread compounds, and sidewall designs rated for extreme load indices exceeding 100 tons, serving earthmoving, material transport, and heavy-lift operations in unimproved terrain. Radial constructions dominate high-value mining contracts due to superior heat dissipation and tread life, while bias configurations retain cost advantages in intermittent-use agricultural equipment. Solid tires command premium positioning in material handling and waste management where puncture elimination justifies higher acquisition costs.
EPA Tier 4 Final emission mandates and NHTSA commercial vehicle safety protocols shape equipment replacement cycles and tire performance specifications across US job sites. Transport Canada and provincial regulators enforce parallel standards that synchronize cross-border fleet compliance requirements. Stakeholders must monitor how state-level infrastructure appropriations and federal critical minerals strategies redirect fleet deployment patterns between construction and extraction applications.
Market Dynamics
Fleet operators across the Permian Basin and Southwest US copper corridors are consolidating supplier relationships as EPA Tier 4 Final mandates compress equipment replacement cycles and elevate tire performance specifications for emission-compliant machinery.
Growth Catalysts
- EPA Tier 4 Final Compliance:Off-road equipment renewal cycles in US mining and construction sectors are accelerating as emission mandates force fleet turnover, directly expanding replacement tire demand for compliant machinery configurations.
- Copper Corridor Expansion:Southwest US mining operations are extending haul road networks and expanding fleet sizes to meet federal critical minerals strategy targets, concentrating OTR tire consumption in Arizona and New Mexico extraction zones.
- Heat-Dissipating Radial Technology:Premium radial constructions with specialized steel belt packages and advanced tread compounds are capturing high-value mining contracts through superior thermal management and extended service intervals in continuous-duty applications.
Market Restraints
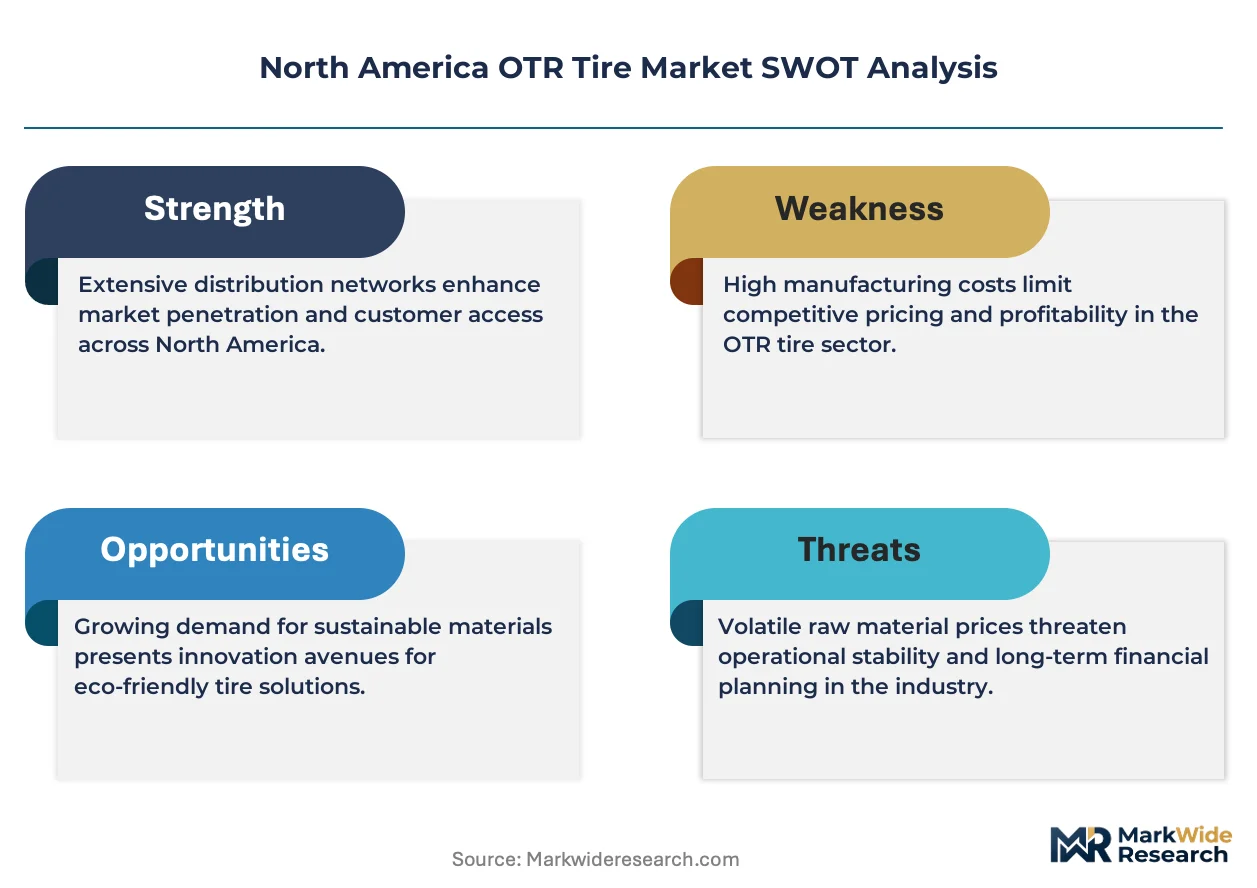
- Natural Rubber Price Volatility:Raw material input costs fluctuate with Southeast Asian supply disruptions and currency movements, compressing margin predictability for tire manufacturers serving price-sensitive construction segments.
- Specialized Compound Concentration:Production of extreme-duty tread formulations depends on limited domestic chemical suppliers, creating geographic supply risk concentrated in Gulf Coast petrochemical corridors.
- Bias Configuration Substitution Ceiling:Intermittent-use agricultural and light construction equipment retains cost-driven preference for bias-ply tires, limiting radial penetration in sub-50-ton load index categories.
Strategic Opportunities
- Canadian Mining Fleet Electrification:Teck Resources and other Alberta and British Columbia operators are piloting electric haul trucks, creating demand for next-generation tires engineered for torque characteristics and weight distribution of battery-electric platforms.
- US Infrastructure Investment and Jobs Act Deployment:Federal highway and bridge appropriations are redirecting earthmoving equipment toward civil construction corridors, expanding addressable tire demand beyond extraction applications.
- Predictive Maintenance Integration:Sensor-embedded tire systems transmitting pressure, temperature, and tread wear data to fleet management platforms are enabling outcome-based service models and premium pricing capture.
Industry Challenges
- Certified Technician Scarcity:Mounting and servicing ultra-large mining tires requires specialized training that outpaces vocational program output, constraining aftermarket service capacity in remote extraction sites.
- Cross-Border Regulatory Synchronization:Transport Canada and provincial regulators maintain parallel but non-identical standards to US EPA and NHTSA protocols, complicating fleet standardization for operators running equipment across the 49th parallel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America OTR Tire Market |
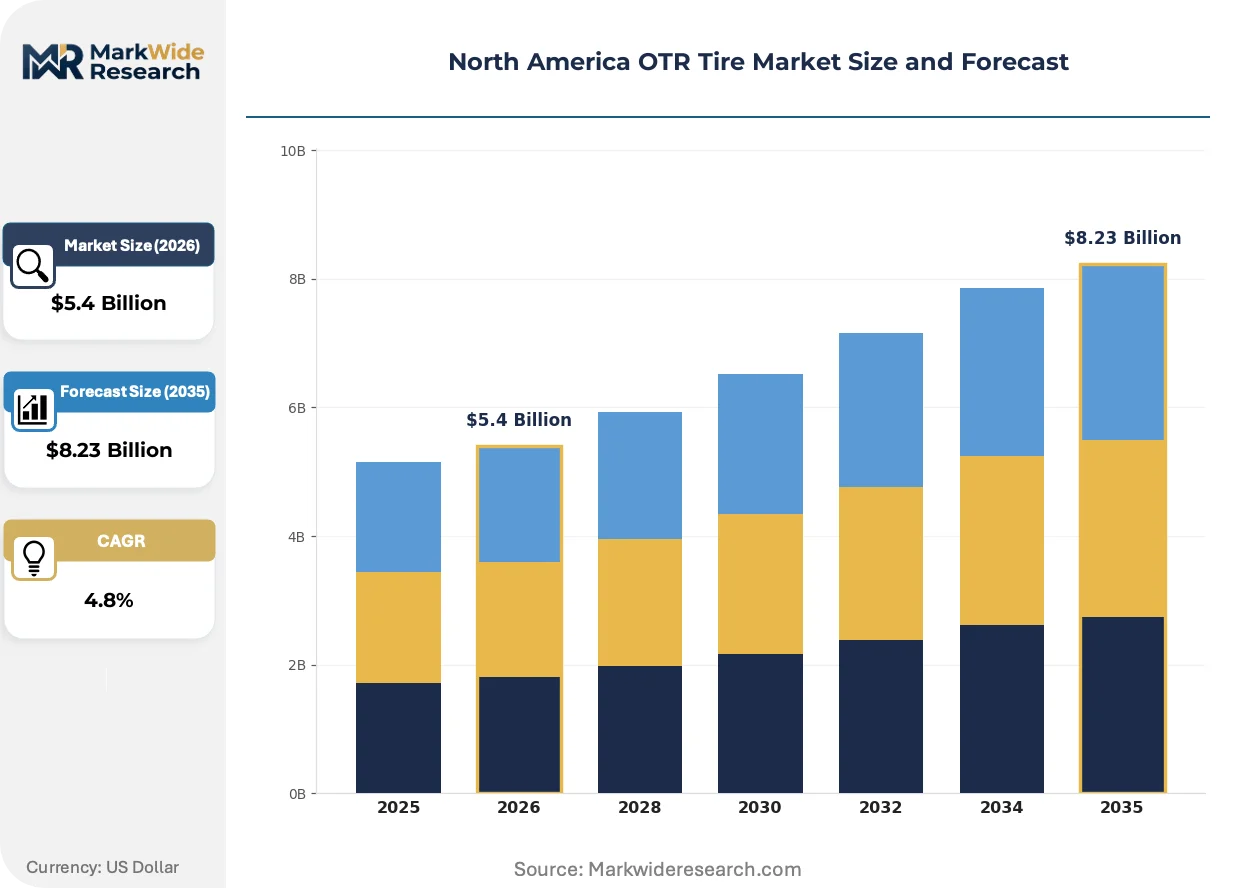
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial, Bias, Solid, Others End User: Construction, Mining, Agriculture, Industrial Application: Material Handling, Earthmoving, Agricultural Equipment, Forestry Distribution Channel: Online, Direct Sales, Retail, Dealers |
| Companies Covered | Yokohama Rubber Co., Titan International, Inc., Bridgestone Corporation, Toyo Tire Corporation, Trelleborg AB, Michelin, The Goodyear Tire & Rubber Company, Cooper Tire & Rubber Company, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America OTR Tire Market Strategic Shifts & Innovations
Material science advances and embedded sensor architectures are transforming tire performance benchmarks while regulatory pressure and procurement rationalization reshape competitive positioning across North American job sites.
Intelligent tire monitoring systems integrating pressure, temperature, and vibration sensors with cloud-based fleet analytics are electrifying aftermarket service models. Mining operators in Nevada and Arizona are deploying these platforms fastest, with tier-one contractors mandating real-time tire health visibility for ultra-class haul trucks. The technology is electrifying traditional time-based maintenance schedules toward condition-driven interventions that compress unplanned downtime and extend casing retread cycles.
NHTSA commercial vehicle safety protocols and parallel Transport Canada standards are tightening load rating verification and sidewall integrity testing requirements for off-road equipment. These mandates are forcing manufacturers to redesign certification processes and documentation systems. The construction segment, particularly in Texas and California infrastructure corridors, faces the steepest compliance timeline pressure as state-level procurement rules incorporate federal safety specifications.
Consolidated procurement among Permian Basin oilfield service companies and Southwest copper operators is displacing fragmented multi-source purchasing with framework agreements tied to performance guarantees and total cost-of-ownership metrics. Dealer networks in rural construction corridors are responding by unbundling tire supply from mounting and maintenance services. This behavioral shift is most visible in Oklahoma and Kansas agricultural equipment markets, where cooperative buying groups are capturing volume leverage previously held by independent fleet operators.
North America OTR Tire Market Segmentation
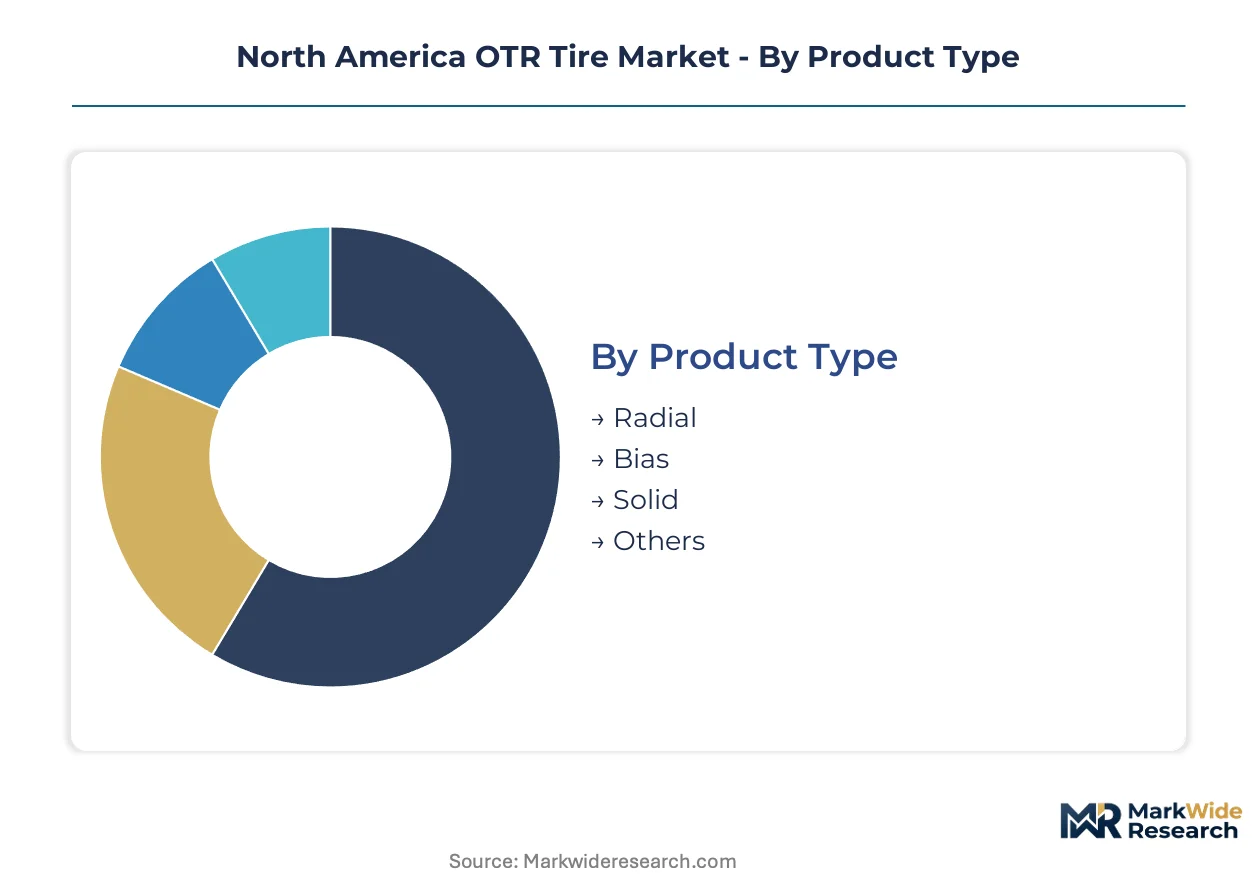
OTR tire procurement in North America hinges on load index requirements, duty cycle intensity, and terrain severity. Fleet engineers specify construction type based on heat dissipation needs, while end-use concentration in mining corridors and infrastructure corridors drives volume distribution patterns.
Product Type:
Equipment replacement cycles and total cost-of-ownership calculations determine construction selection across Permian Basin oilfield and Southwest copper mining operations.
- Radial:Steel-belted carcass construction with advanced tread compounds manages thermal loads in continuous-duty haul trucks. Arizona and Nevada ultra-class mining fleets mandate radial specifications for 100+ ton load indices where heat dissipation extends casing life and enables multiple retread cycles.
- Bias:Cross-ply nylon or polyester cord angles provide sidewall puncture resistance at lower acquisition cost. Intermittent-use agricultural equipment in Oklahoma and Kansas retains bias preference where duty cycles do not justify radial premium pricing.
- Solid:Molded rubber compounds eliminate pneumatic failure modes entirely. Waste management transfer stations and port material handling operations in California and Texas accept weight penalties for puncture immunity in debris-rich environments.
- Others:Foam-filled and polyurethane configurations serve specialized aerial lift and underground mining equipment where standard pneumatic or solid constructions prove inadequate.
Radial leads on scale; solid leads on momentum as electrified material handling fleets expand.
End User:
Capital expenditure intensity and fleet standardization requirements segment demand across extraction, earthmoving, and cultivation applications.
- Mining:Ultra-large haul truck and loader fleets in Arizona copper corridors and Alberta oil sands drive premium radial consumption. EPA Tier 4 Final compliance deadlines compress replacement cycles for emission-compliant machinery configurations.
- Construction:Earthmoving equipment deployment along US Infrastructure Investment and Jobs Act corridors concentrates tire demand in Texas, California, and Florida civil works zones. Wheel loaders and motor graders operate on varied substrates requiring versatile tread patterns.
- Agriculture:Tractor and combine harvester fleets across Midwest grain belts and California Central Valley vegetable operations favor bias configurations for seasonal use patterns. Cooperative buying groups in Kansas and Nebraska consolidate procurement volume.
- Industrial:Forklift and container handler fleets in port terminals and distribution centers specify solid or pneumatic industrial designs. California port electrification mandates reshape tire torque and weight distribution requirements.
Mining leads on scale; construction leads on momentum as federal infrastructure appropriations redirect fleet deployment.
Application:
Surface contact pressure and traction requirements govern tread compound selection and lug pattern geometry across material movement categories.
- Earthmoving:Dozer and scraper operations in unimproved terrain demand aggressive lug designs with cut-resistant compounds. Southwest US mining haul road construction concentrates consumption in Arizona and New Mexico.
- Material Handling:Container handlers and reach stackers in port and intermodal facilities require high-load solid or pneumatic designs with non-marking compounds. Texas Gulf Coast port expansion drives specification evolution.
- Agricultural Equipment:Tillage and harvest operations need flotation treads to minimize soil compaction. Midwest grain belt cooperatives standardize on specific R-1 and R-2 patterns.
- Forestry:Skidder and feller-buncher equipment in Pacific Northwest and Southeastern US timber operations demands extreme cut-and-chip resistant sidewalls. British Columbia and Washington State logging corridors concentrate specialized demand.
Earthmoving leads on scale; material handling leads on momentum as port automation accelerates.
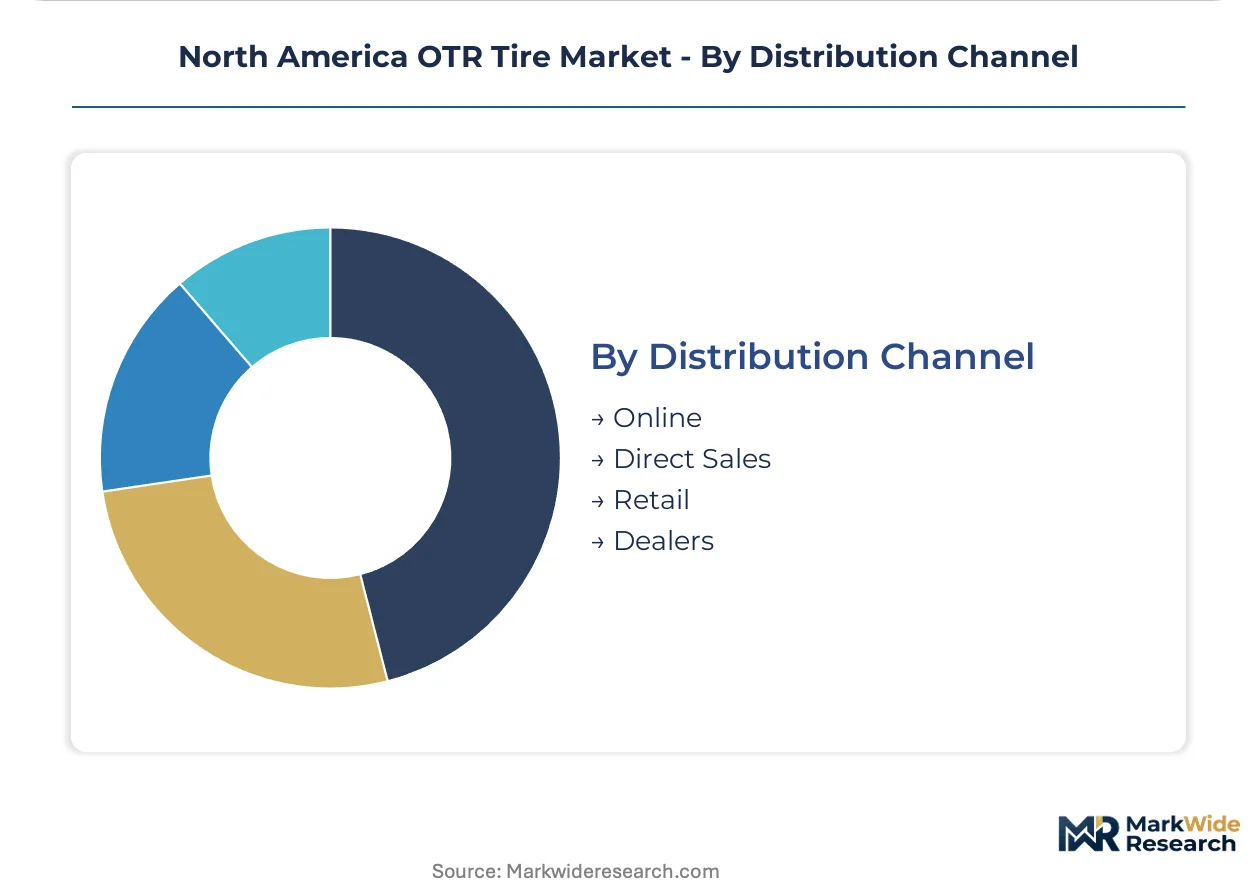
Distribution Channel:
Service integration requirements and procurement centralization trends reshape how fleets access mounting, maintenance, and tire supply.
- Direct Sales:Mining majors and national construction contractors negotiate framework agreements with manufacturers for ultra-large tire categories. Teck Resources and Permian Basin oilfield service companies consolidate supplier relationships through direct procurement.
- Dealers:Rural construction and agricultural corridors depend on independent dealer networks for mounting equipment and field service capability. Oklahoma and Kansas dealer density sustains bias-ply market access.
- Retail:Independent tire retailers serve light construction and homeowner rental equipment segments with limited service integration.
- Online:Digital procurement platforms capture standard-size agricultural and light industrial tire categories where specification complexity remains low.
Direct sales leads on scale; dealers lead on momentum as service bundling requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin oil patch anchors North American OTR tire demand through Permian Basin drilling intensity and Southwest copper corridor expansion. EPA Tier 4 Final mandates and federal critical minerals strategies redirect fleet deployment between extraction and construction applications. Transport Canada and provincial regulators enforce parallel standards that synchronize cross-border compliance requirements.
United States
Southwest copper corridors in Arizona and New Mexico concentrate ultra-class mining fleet renewals as EPA Tier 4 Final deadlines compress equipment replacement cycles. The Infrastructure Investment and Jobs Act redirects earthmoving capacity toward Texas and California civil construction zones. Permian Basin oilfield service companies consolidate supplier relationships through framework agreements with performance guarantees.
Canada
Alberta oil sands and British Columbia mining operations drive premium radial consumption for 100+ ton haul trucks. Transport Canada enforces emission standards parallel to EPA protocols, forcing fleet standardization across the 49th parallel. Teck Resources and other Alberta operators pilot electric haul trucks, creating demand for next-generation tire engineering.
Mexico
Cross-border manufacturing integration positions Sonora and Chihuahua as emerging OTR tire consumption zones for mining equipment serving US Southwest operations. Mexican federal environmental regulations adopt Tier 4 equivalent standards under PROAIRE programs. The Bajío Region automotive supplier base extends into OTR tire distribution networks serving Central Mexican construction corridors.
North America OTR Tire Market Key Industry Players
Global majors compete with regional champions across integrated manufacturing and distribution capabilities. The North America OTR tire structure concentrates around three tiers: integrated tire-to-rim suppliers with captive rubber processing, radial technology specialists commanding ultra-large mining contracts, and regional fabricators serving agricultural bias-ply segments. Consolidated procurement among Permian Basin and Southwest copper operators favors framework agreements with performance guarantees. Capacity expansion in Tennessee and Mexico reinforces supply security for emission-compliant machinery configurations.
Among Japanese-origin tire manufacturers, Yokohama Rubber Co. and Toyo Tire Corporation occupy positions within the radial technology specialist tier. Titan International, Inc. exemplifies the integrated tire-to-rim archetype through its Quincy, Illinois manufacturing heritage. Bridgestone Corporation anchors the premium mining segment with integrated production footprints across Tennessee and Mexico. The Goodyear Tire & Rubber Company and Michelin represent competing global majors differentiated by dealer network density versus ultra-large mining technology leadership. Continental AG and Cooper Tire & Rubber Company sit within the diversified automotive supplier tier extending commercial vehicle expertise into off-road applications.
| Leading Market Players |
|---|
| Yokohama Rubber Co. |
| Titan International, Inc. |
| Bridgestone Corporation |
| Toyo Tire Corporation |
| Trelleborg AB |
| Michelin |
| The Goodyear Tire & Rubber Company |
| Cooper Tire & Rubber Company |
| Continental AG |
| Others |
Cost & Logistics Intelligence
EPA Tier 4 Final emission mandates gate qualified supply for ultra-large mining tires, restricting premium-tier pricing access to manufacturers with integrated Tennessee and Mexico production footprints certified for compliant machinery configurations. Natural rubber cost pass-through and specialized compound availability further stratify pricing power across radial, bias, and solid construction categories.
Pricing Analysis
Input-cost pass-through from Southeast Asian natural rubber markets and Gulf Coast petrochemical corridors shapes contract-based long-term offtake structures for mining fleet procurement. Price differentiation separates premium radial specifications with heat-dissipating steel belt packages from standard bias configurations and economy solid tires for intermittent-use equipment. Pricing pressure stems from raw material volatility compressing margins in price-sensitive agricultural segments. Construction contractors in Texas and California infrastructure corridors exhibit highest price sensitivity due to competitive bidding environments, while Arizona copper mining majors prioritize total cost-of-ownership metrics over acquisition cost.
Supply Chain Analysis
Specialty synthetic rubber and carbon black supply rests on Gulf Coast petrochemical producers and Southeast Asian natural rubber processors, creating geographic concentration across Thailand, Indonesia, and domestic Texas-Louisiana chemical corridors. Steel cord for radial carcass construction draws from domestic mills and Japanese specialty metal suppliers. Single-source vulnerability in extreme-duty tread compound chemicals creates supply risk concentrated in limited domestic chemical suppliers. Distribution runs through integrated manufacturer-direct channels for ultra-large mining contracts and independent dealer networks serving rural construction and agricultural corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America OTR tire market functions as a geographic-arbitrage play between US Southwest mining corridors and Canadian oil sands operations, where EPA and Transport Canada emission standard differentials create fleet renewal timing advantages for cross-border suppliers.
For Market Incumbents: Acquire specialized mounting and field service capabilities in remote Arizona and Nevada extraction sites to defend against certified technician scarcity threatening aftermarket revenue capture. Deepen backward integration into captive natural rubber processing to offset Southeast Asian supply disruption risks. Prioritize certification investment for EPA Tier 4 Final compliant tire specifications to maintain framework agreement eligibility with Permian Basin oilfield consolidators.
For New Entrants and Emerging Players: Begin with sensor-embedded tire monitoring platforms serving Nevada and Arizona ultra-class haul truck fleets where real-time condition data commands premium service bundling opportunities. Target the Canadian electric haul truck pilot segment at Teck Resources and other Alberta operators where next-generation torque engineering requirements favor specialized entrants over legacy radial suppliers. Deploy predictive maintenance integration as the primary go-to-market angle, unbundling hardware supply from outcome-based uptime guarantees.
For Investors and Strategic Acquirers: Roll-up economics work for regional tire-to-rim fabricators with Quincy, Illinois heritage and established dealer density across Oklahoma and Kansas agricultural corridors because cooperative buying group consolidation is displacing fragmented independent procurement. Long-term viability hinges on electrification readiness and emission-compliant certification portfolios rather than commodity bias-ply volume. Watch Transport Canada-EPA regulatory synchronization progress as the signal indicating cross-border fleet standardization acceleration or continued arbitrage opportunity persistence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Rubber Processing | Captive supply from Southeast Asian plantation networks insulates margin compression from currency volatility and port congestion. |
| Sensor-Embedded Tire Platform Launch | Cloud-based fleet analytics integration with Arizona copper corridor haul truck operators enables condition-driven maintenance revenue capture. |
| Certified Technician Training Program Expansion | Vocational partnerships in Nevada and Alberta address mounting capacity constraints at remote ultra-large tire service sites. |
| Electric Haul Truck Tire Engineering Partnership | Collaboration with Teck Resources and Alberta operators positions specialized torque-optimized designs for battery-electric fleet conversion. |
| Cross-Border Distribution Network Consolidation | Unified Tennessee-Mexico manufacturing footprint synchronizes supply security for EPA and PROAIRE emission-compliant machinery configurations. |
Research Approach
Direct dialogue with fleet maintenance directors at Arizona copper operators, procurement leads at Permian Basin oilfield service companies, aftermarket service heads at rural construction dealers, and technical R&D directors at radial manufacturing facilities grounded qualitative findings. Secondary validation drew from EPA enforcement and compliance databases, Transport Canada emission standard filings, USGS mineral commodity summaries, and SEC 10-K disclosures from tire manufacturers. Bottom-up equipment fleet counts and top-down raw material consumption estimates were triangulated to anchor volume projections.
Bottom-up modeling aggregated haul truck and earthmoving equipment populations across Southwest US mining corridors and Canadian oil sands operations, while top-down analysis calibrated against synthetic rubber and carbon black consumption trends reported through chemical industry associations. Segmentation dimensions included construction type, end-use application, load index tier, and regional regulatory cluster. CAGRs were derived from replacement cycle compression under EPA Tier 4 Final mandates and infrastructure appropriation-driven fleet redeployment patterns. Forecast inputs incorporated copper price sensitivity for Arizona and New Mexico extraction expansion and federal highway obligation timelines for civil construction equipment demand.
Several conditions sit outside the modeled scope, including potential suspension of EPA enforcement timelines, abrupt natural rubber supply disruptions from Southeast Asian climate events, and accelerated electric haul truck adoption curves beyond current pilot phases. Forecasts reflect documented assumptions about emission compliance deadlines and infrastructure spending authorization continuity. A small set of named triggers warrants ongoing watch: Transport Canada-EPA regulatory divergence, Gulf Coast petrochemical corridor disruption, and copper corridor labor action affecting fleet utilization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Rail Road Wheels Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Specialty Tire Market
Tires and Wheels
Automotive Carbon Wheels Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
South Korea Automotive Carbon Wheels Market
Tires and Wheels
Europe Agricultural Tires Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Agricultural Tires Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Magnesium Wheel Market
Tires and Wheels
Global Advanced Tires Market
Tires and Wheels
North America Alloy Wheels Market