
 Construction Machinery Tires Market | 2026-2036
Construction Machinery Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Machinery Tires Market Outlook
Buyer concentration among mining conglomerates and large rental fleets is hardening across the construction machinery tire value chain. Michelin leverages its integrated R&D footprint in Clermont-Ferrand to sustain premium radial development for ultra-class haul trucks. Bridgestone Corporation anchors its position through captive supply of natural rubber from Southeast Asian plantations. Apollo Tyres Ltd competes aggressively on replacement cycles in India's domestic infrastructure sector.
Construction machinery tires are engineered elastomeric structures designed to withstand extreme static loads, puncture hazards, and thermal cycling in off-highway environments, typically incorporating steel-belted radial carcasses, cut-resistant tread compounds, and reinforced sidewalls for load ratings exceeding 100 tons per tire. Their primary purpose is to ensure operational continuity in earthmoving, material handling, and lifting equipment where downtime costs dwarf component prices. Radial tires now dominate the product type landscape due to superior heat dissipation and fuel efficiency in continuous-duty mining applications, while solid tires command niche margin pools in demolition and waste handling where puncture elimination justifies weight penalties. The application split shows excavators and loaders absorbing the largest volume share, though crane tires sustain higher per-unit pricing through specialized load-bearing certification requirements.
EPA emissions thresholds for non-road equipment in the United States, REACH chemical restrictions administered by ECHA in Europe, and China's GB standards on tire labeling and fuel efficiency collectively reshape material formulation priorities and market access conditions for manufacturers. The EU F-Gas Regulation indirectly pressures tire producers through supply-chain accountability for processing agents used in synthetic rubber polymerization. Stakeholders must monitor how regulatory divergence between Brussels and Beijing on aromatic oil content creates parallel certification burdens that favor regionally integrated producers over pure exporters.
Market Dynamics
Radial tire architectures are consolidating their dominance as mining operators in Australia and Chile prioritize thermal management and fuel efficiency for ultra-class haul trucks operating at depth. This technological transition concentrates procurement power among fleet operators capable of absorbing higher upfront costs for lifecycle gains.
Growth Catalysts
- EU F-Gas Regulation:REACH compliance mandates on aromatic oil content are accelerating formulation shifts toward low-aromatic alternatives, creating premium positioning for certified suppliers.
- Belt and Road infrastructure:China's western provinces require sustained heavy earthmoving capacity, anchoring replacement demand for loader and excavator tires.
- Deep ore extraction:Mining operators in Chile's copper districts and Australia's iron ore basins are renewing fleets to handle extended haul distances and elevated thermal loads.
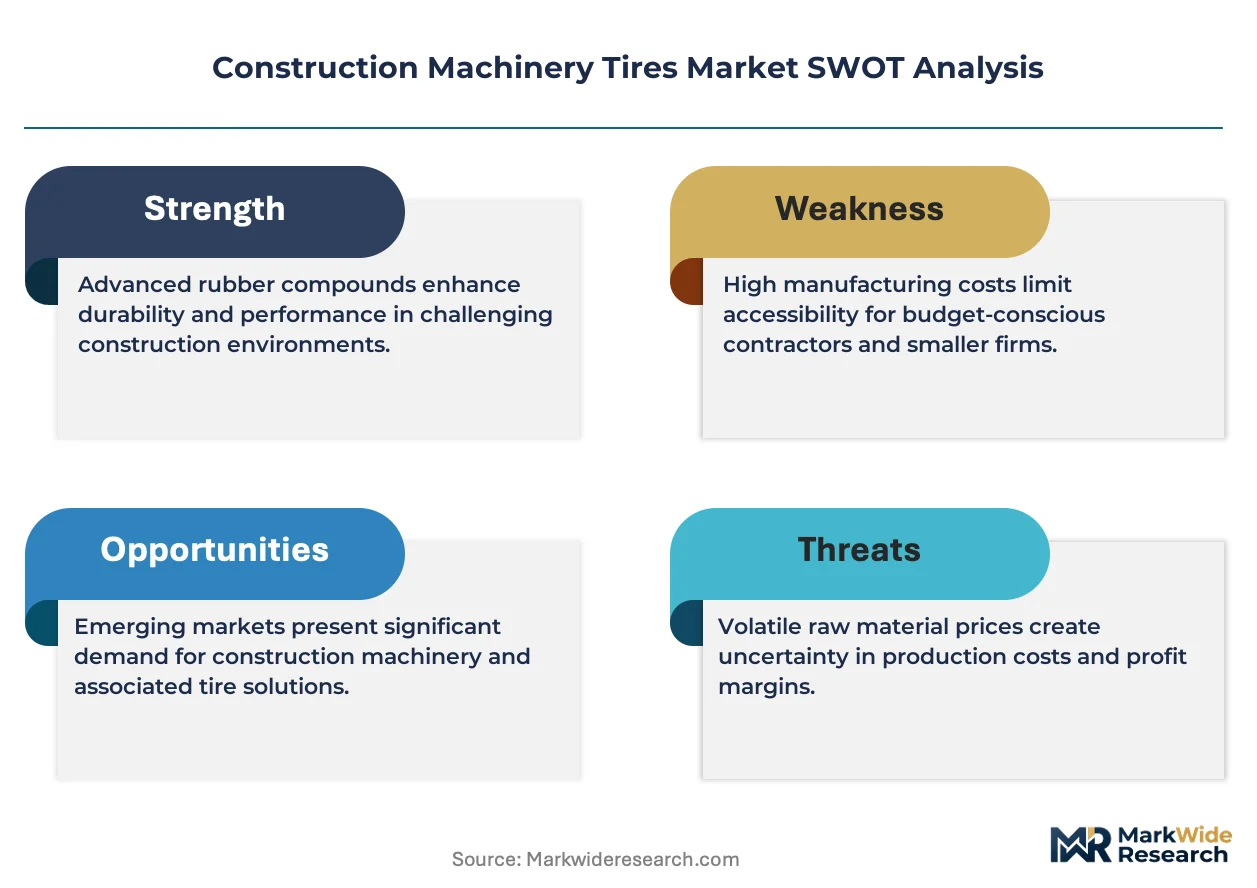
Market Restraints
- Natural rubber price volatility:Southeast Asian plantation output fluctuations transmit directly to compound costs, compressing margin predictability for non-integrated manufacturers.
- Synthetic rubber feedstock concentration:Petrochemical processing for styrene-butadiene and polybutadiene concentrates in Gulf Coast and Northeast Asian complexes, exposing supply to energy price shocks.
- Steel cord supply bottleneck:High-tensile bead wire and belt cord production capacity concentrates among Japanese and South Korean metallurgical specialists, limiting sourcing flexibility.
Strategic Opportunities
- India's domestic infrastructure build-out:Apollo Tyres and MRF are expanding radial capacity to capture replacement cycles in road construction and urban metro projects.
- Solid tire electrification compatibility:Electric wheel loaders and compact excavators in European demolition and waste handling favor puncture-proof configurations with regenerative braking tolerance.
- Retreading service integration:Mining conglomerates are consolidating casing management with tire suppliers, shifting revenue from unit sales to per-operating-hour contracts.
Industry Challenges
- Compound formulation expertise scarcity:Formulators capable of balancing cut resistance, heat dissipation, and REACH-compliant oil systems command premium compensation, constraining R&D scaling.
- Homologation timeline compression:China's GB standards on tire labeling and fuel efficiency require accelerated testing protocols, straining certification resources for multi-market launches.
- Legacy bias-ply inventory rationalization:Rental fleets in emerging markets retain mixed radial-bias configurations, complicating maintenance training and spare parts forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Machinery Tires Market |
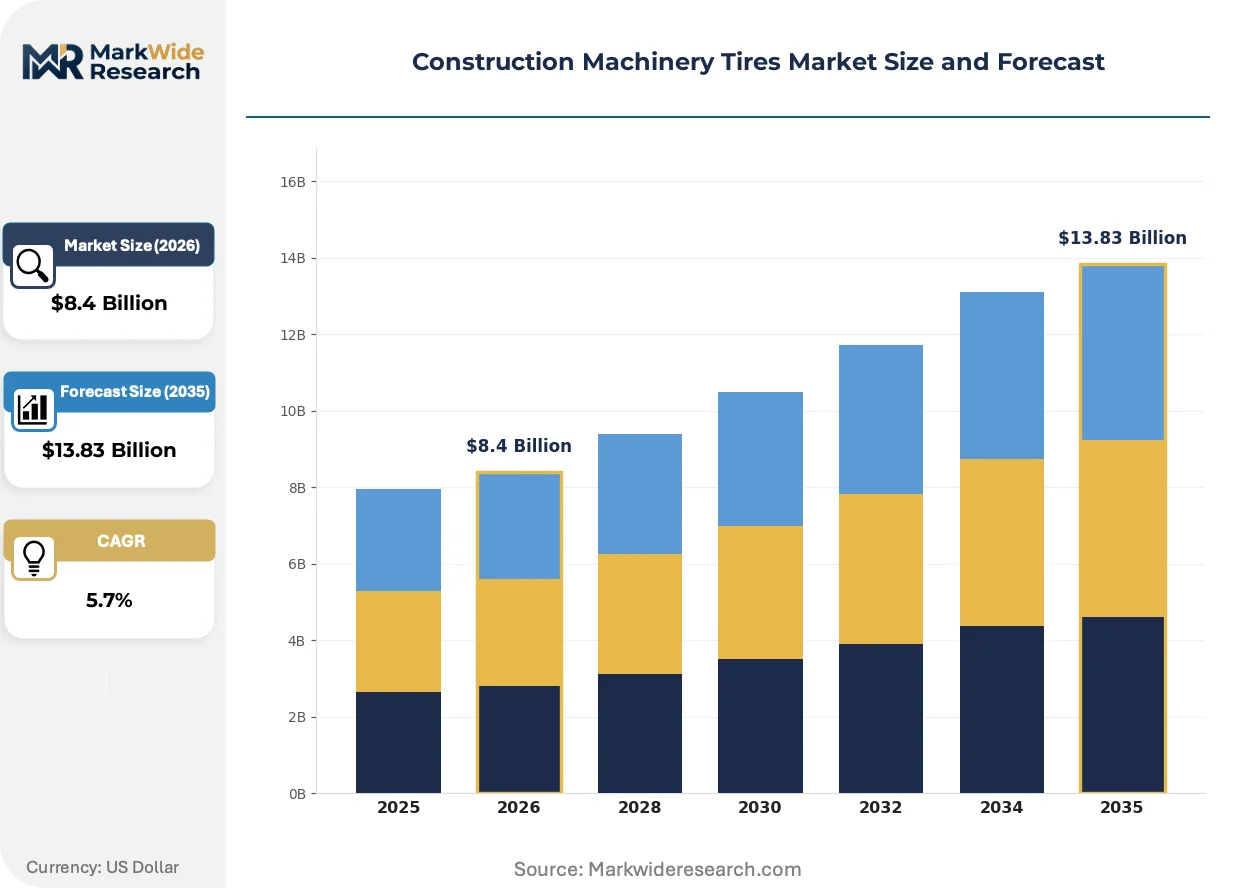
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Solid Tires, Open Shoulder Tires Application: Excavators, Loaders, Graders, Cranes Industry Vertical: Mining, Construction, Agriculture, Urban Development Customer Type: Equipment Dealers, Construction Firms, Rental Companies, Government Agencies |
| Companies Covered | Continental AG, Apollo Tyres Ltd, Bridgestone Corporation, Alliance Tire Group, Trelleborg AB, Michelin, Balkrishna Industries Limited, Sumitomo Rubber Industries Ltd, Goodyear Tire & Rubber Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Machinery Tires Market Strategic Shifts
Intelligent tire monitoring systems and sustainable material substitutions are converging to redefine performance benchmarking and procurement criteria across off-highway segments. These shifts favor suppliers capable of integrating hardware, data analytics, and circular service models.
Sensor-embedded tire architectures are integrating pressure, temperature, and tread-wear telemetry directly into radial carcass designs. Mining operators in Western Australia are adopting these systems for predictive maintenance of 400-ton haul trucks. The technology is integrating fleet management software with tire lifecycle data, compressing downtime windows and shifting supplier relationships toward performance-guarantee contracts.
REACH chemical restrictions administered by ECHA are prohibiting high-aromatic extender oils in tread compounds effective 2026. Tire manufacturers are reformulating with treated distillate aromatic extracts and residual aromatic extracts below regulatory thresholds. The EU F-Gas Regulation indirectly pressures synthetic rubber polymerization agents, forcing Clermont-Ferrand and Hanover R&D centers to validate alternative processing chemistries for export eligibility.
Procurement consolidation among mining conglomerates and large rental fleets is compressing distributor tiers and favoring direct manufacturer relationships. Tier-one suppliers are disintermediating regional wholesalers to capture service revenue and casing retread flows. This pattern is most visible in Chile's copper mining districts and Western Australia's Pilbara region, where BHP and Rio Tinto have centralized tire procurement under lifecycle cost-per-ton metrics rather than unit pricing.
Construction Machinery Tires Market Segmentation
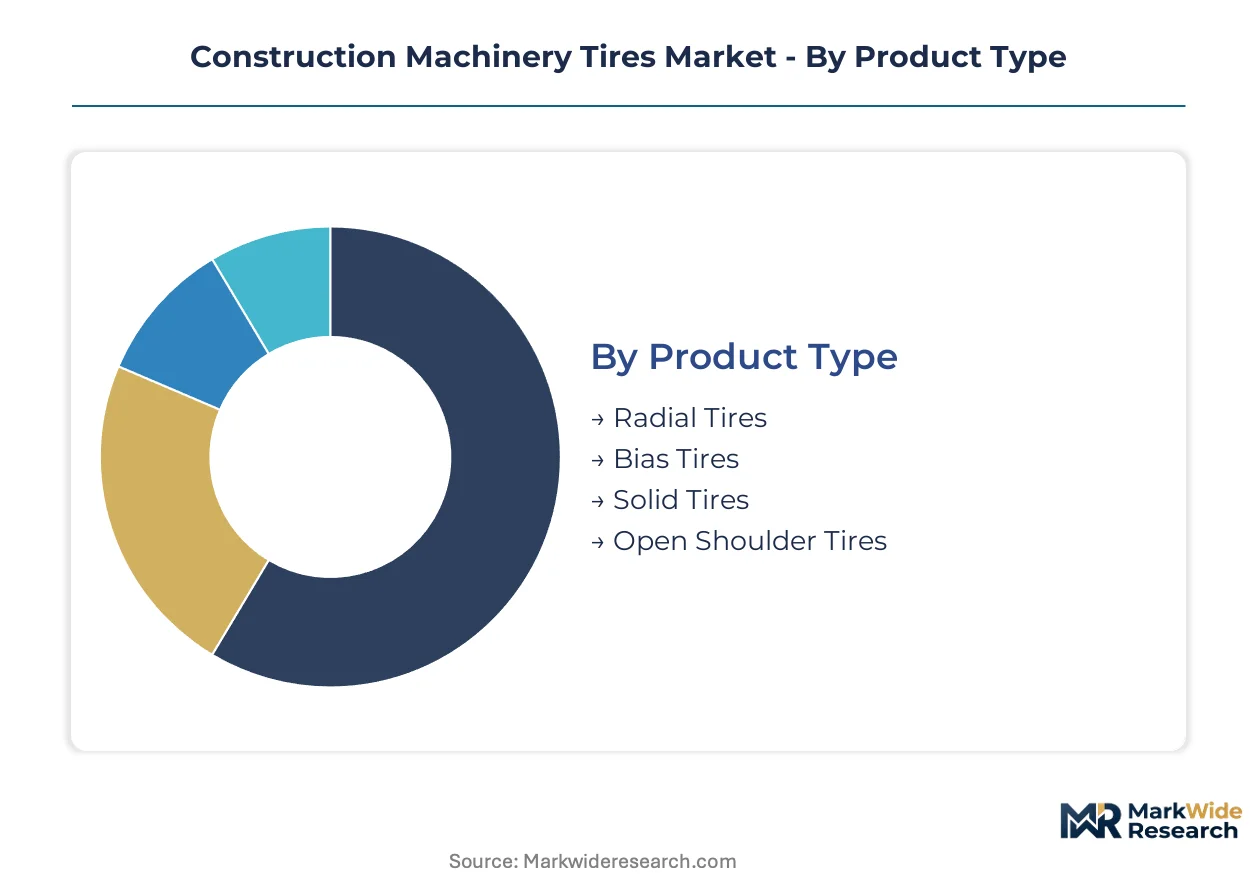
Construction machinery tire procurement splits across multiple axes that determine specification requirements, pricing tiers, and service intensity. Each segmentation dimension carries distinct margin profiles and technical barriers that reshape competitive positioning for suppliers.
Product Type:
Radial architectures command the steepest capital commitments due to steel-belted carcass complexity and specialized curing equipment requirements.
- Radial Tires:Steel-belted radial carcasses with reinforced sidewalls dissipate heat across continuous haul cycles in Western Australia's Pilbara iron ore operations. Mining conglomerates prioritize these configurations for ultra-class trucks where thermal management directly determines fleet availability and fuel burn rates.
- Solid Tires:Puncture-proof elastomeric masses eliminate downtime in demolition and waste handling applications across European urban centers. Electric wheel loaders with regenerative braking systems favor these configurations despite weight penalties that reduce transport efficiency.
- Bias Tires:Cross-ply nylon or polyester cord constructions retain cost advantages in emerging market rental fleets with mixed-age equipment.
- Open Shoulder Tires:Aggressive tread patterns with voided shoulder blocks enhance self-cleaning in muddy construction sites.
Radial tires absorb the bulk of installed capacity in mining applications; solid tires are expanding most quickly through electrification compatibility in European material handling.
Application:
Load-bearing certification requirements and duty cycle intensity create divergent margin structures across equipment categories.
- Excavators:Articulated boom machines impose asymmetric loading patterns that demand reinforced sidewall compounds and bead wire configurations. China's western provinces anchor replacement demand as Belt and Road infrastructure projects accelerate earthmoving intensity.
- Loaders:Continuous scoop-and-carry operations generate heat buildup that radial architectures manage more effectively than bias alternatives. Surface mining operations in Chile's copper districts prioritize thermal-resistant tread compounds for these machines.
- Graders:Precision grading applications require uniform ground pressure distribution across blade-mounted configurations.
- Cranes:Static load ratings exceeding 100 tons per tire necessitate specialized engineering and extended homologation timelines.
Excavators and loaders together dominate unit volume; crane tires sustain the highest per-unit pricing through certification complexity.
Industry Vertical:
Procurement consolidation patterns and lifecycle cost accounting vary sharply across end-use sectors.
- Mining:Deep ore extraction in Australia and Chile drives fleet renewal cycles with performance-guarantee contracts replacing unit sales. Thermal management and cut resistance dominate specification priorities as haul distances extend at depth.
- Construction:India's domestic infrastructure build-out generates replacement demand for road construction and urban metro projects with shorter procurement cycles than mining.
- Agriculture:Seasonal duty patterns and lower utilization rates favor cost-optimized bias configurations in emerging markets.
- Urban Development:Demolition and waste handling applications in European cities favor solid tire configurations for puncture elimination.
Mining concentrates the largest revenue pool; urban development is climbing the fastest through electrification mandates in European municipalities.
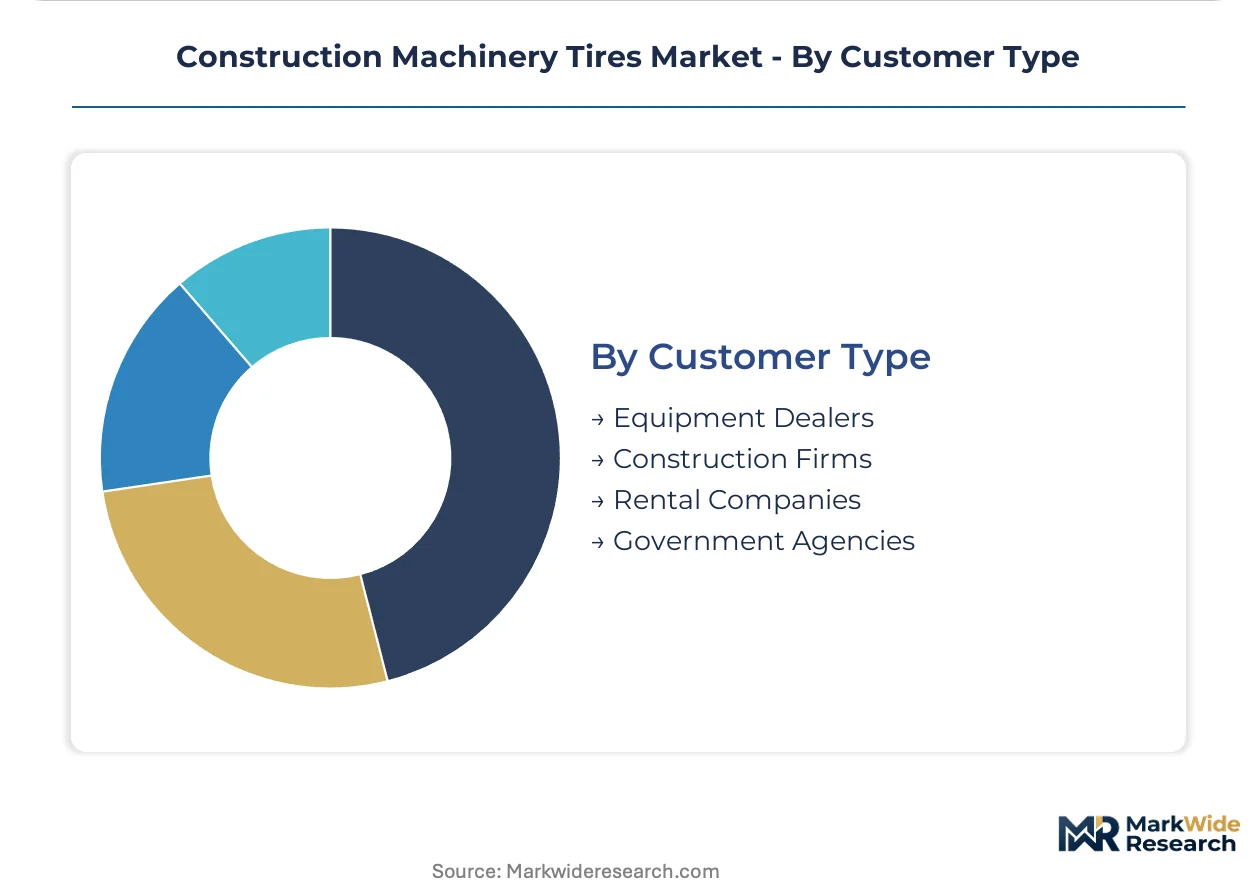
Customer Type:
Direct manufacturer relationships versus distributor intermediation reshape service revenue capture and casing retread economics.
- Equipment Dealers:Authorized distribution networks manage warranty claims and specification matching for OEM-fitment tires across multi-brand portfolios.
- Construction Firms:Project-based procurement with variable fleet utilization complicates predictive maintenance scheduling and inventory planning.
- Rental Companies:Mixed radial-bias fleet configurations in emerging markets strain maintenance training standardization and spare parts forecasting accuracy.
- Government Agencies:Public procurement protocols with lifecycle cost-per-ton metrics favor certified suppliers with integrated retreading capabilities.
Rental companies absorb the bulk of replacement volume through fleet aggregation; government agencies are gaining share fastest through centralized procurement reform.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural rubber plantations in Southeast Asia anchor raw-material flows for tire manufacturers serving mining and construction demand centers. Ore extraction depth in Australia and Chile drives fleet renewal cycles with thermal management specifications. Infrastructure build-out in China's western provinces sustains replacement volume for earthmoving equipment.
Australia
Iron ore operators in Western Australia's Pilbara region prioritize radial architectures for ultra-class haul trucks operating at extended depths. The country's national environmental regulator enforces strict mine rehabilitation standards that accelerate equipment turnover. Perth-based procurement hubs centralize tire logistics for BHP and Rio Tinto under lifecycle cost-per-ton contracts.
Chile
Copper extraction in the Atacama Desert generates concentrated demand for thermally resistant compounds in continuous-duty loaders. The national mining regulator imposes progressive closure obligations that compress fleet replacement timelines. Antofagasta and Calama form the primary consumption clusters where centralized procurement has eliminated regional distributor tiers.
China
Belt and Road infrastructure projects in Xinjiang and Sichuan provinces require sustained heavy earthmoving capacity for tunneling and roadbed preparation. GB standards on tire labeling and fuel efficiency mandate accelerated testing protocols for domestic and imported products. Chengdu and Urumqi serve as distribution nodes for western province construction fleets.
India
Domestic road construction and urban metro expansion generate replacement demand for loader and excavator tires with shorter procurement cycles than mining. The Bureau of Indian Standards enforces certification requirements for commercial vehicle tires that extend to off-highway segments. Gujarat and Maharashtra host manufacturing clusters serving infrastructure projects across the Delhi-Mumbai Industrial Corridor.
Germany
Demolition and waste handling applications in European urban centers favor solid tire configurations compatible with electric wheel loaders. REACH chemical restrictions administered by ECHA prohibit high-aromatic extender oils in tread compounds effective 2026. Hanover and Frankfurt concentrate R&D validation facilities for alternative processing chemistries.
Construction Machinery Tires Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electrification-compatible solid tire segments and retreading service integration. The market structure concentrates among integrated manufacturers with captive natural rubber supply and steel-cord sourcing relationships. Three archetypes dominate: premium radial specialists with embedded R&D footprints, scale-driven mass producers serving replacement cycles, and niche solid tire fabricators for material handling. Competitive moves center on backward integration into plantation assets and consolidation of casing management under per-operating-hour contracts.
Among integrated multinationals, Continental AG and Bridgestone Corporation exemplify archetypes with upstream control over feedstock supply chains. Michelin occupies a position within the premium-tier vector through specialized radial development. Apollo Tyres Ltd represents aggressive replacement-cycle competition in emerging market infrastructure segments. Balkrishna Industries Limited and Alliance Tire Group anchor mid-market positioning for agricultural and construction crossover applications. Trelleborg AB exemplifies the solid tire specialization archetype for industrial material handling environments.
| Leading Market Players |
|---|
| Continental AG |
| Apollo Tyres Ltd |
| Bridgestone Corporation |
| Alliance Tire Group |
| Trelleborg AB |
| Michelin |
| Balkrishna Industries Limited |
| Sumitomo Rubber Industries Ltd |
| Goodyear Tire & Rubber Company |
| Others |
Value Chain & Pricing Dynamics
Captive rubber plantation ownership in Southeast Asia anchors both feedstock security and margin insulation for integrated manufacturers serving mining and construction demand centers. This backward integration pattern concentrates pricing power among producers with in-house natural rubber supply, while non-integrated competitors absorb volatility through spot-market exposure.
Pricing Analysis
Warranty bundling with casing management services separates premium suppliers from transactional competitors in mining procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in the standard tier is intensifying because REACH-compliant formulation investments transmit to compound costs. Rental fleet operators exhibit highest price sensitivity due to mixed radial-bias configurations, while mining conglomerates prioritize lifecycle cost-per-ton metrics over unit pricing.
Supply Chain Analysis
Regional distribution centers in Perth, Antofagasta, and Chengdu enable hub-and-spoke patterns that compress lead times for construction and mining fleets. Manufacturing draws from Thailand, Indonesia, and Malaysia for natural rubber, Japan and South Korea for steel cord, and Gulf Coast petrochemical complexes for synthetic rubber feedstock. Single-source vulnerability in high-tensile bead wire production exposes supply continuity to metallurgical capacity constraints. Distribution runs through authorized dealer networks and direct manufacturer relationships, with tier-one suppliers disintermediating regional wholesalers to capture service revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH compliance costs and R&D scale requirements force sub-scale formulators toward exit or acquisition.
For Market Incumbents: Extend casing management contracts into per-operating-hour service models to lock in retread revenue streams. Deepen captive rubber supply through plantation asset acquisition in Indonesia and Thailand to defend margin position against feedstock volatility. Prioritize certification investment for EU F-Gas Regulation and GB standards compliance to maintain market access as regulatory divergence accelerates. For New Entrants and Emerging Players: Launch via solid tire specialization for electric wheel loaders in European demolition and waste handling segments where puncture-proof configurations command premium positioning. Target India's domestic infrastructure replacement cycles where shorter procurement cycles favor agile suppliers. Pursue retreading service integration as the primary go-to-market angle, shifting revenue from unit sales to lifecycle management contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated multinationals seeking regional manufacturing footprints. Five-to-ten-year viability hinges on backward integration into feedstock supply and certification compliance capabilities. Monitor regulatory divergence between Brussels and Beijing on aromatic oil content as the critical inflection indicator for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive natural rubber supply from Southeast Asian plantations insulates margin predictability against commodity volatility. |
| Retreading Service Network Expansion | Per-operating-hour contracts with BHP and Rio Tinto shift revenue from transactional unit sales to recurring service streams. |
| REACH-Compliant Formulation Investment | Low-aromatic oil validation at Clermont-Ferrand and Hanover R&D centers secures EU market access under ECHA restrictions. |
| Intelligent Tire System Integration | Sensor-embedded architectures for Western Australian haul trucks enable predictive maintenance and performance-guarantee positioning. |
| Radial Capacity Expansion in India | Domestic manufacturing clusters in Gujarat and Maharashtra capture replacement demand from Delhi-Mumbai Industrial Corridor projects. |
Study Parameters
Multi-period observation of fleet renewal cycles, regulatory implementation timelines, and raw material price movements anchored the trend analysis, supplemented by interviews with maintenance directors at mining operations, OEM procurement teams, aftermarket service heads, and plant managers at tire manufacturing facilities. Secondary validation drew from customs and trade data, SEC 10-K filings of listed manufacturers, ECHA regulatory guidance documents, and production databases for steel cord and synthetic rubber. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices modeled volume and value trajectories across product type, application, industry vertical, and customer type dimensions throughout the forecast period. CAGRs were derived from elasticity modeling against mining capital expenditure patterns and infrastructure investment flows. Industry-specific forecast inputs incorporated ore extraction depth projections for Chilean copper districts and Belt and Road construction intensity in China's western provinces.
Regulatory implementation delays, natural rubber supply disruptions, and mining capital expenditure freezes are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Europe Tire Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Agricultural Tires Market
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Kuwait Tyres Market
Tires and Wheels
Elastic Polyurethane Wheels Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Ground Support Equipment Tires Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Commercial Vehicles Tires Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Global Ultra High Performance Tire Market