
 Automotive Tire Chains Market | 2026-2036
Automotive Tire Chains Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Tire Chains Market Intelligence
The Austrian Ö-Norm V 5117 standard for passenger vehicle snow chains is redrawing the competitive landscape by setting stringent performance benchmarks for European market access. KÖNIG Snow Chains leverages its compliance to sustain a premium position. Peerless Chain focuses on North America, specializing in heavy-duty chains for commercial trucks meeting US transport regulations. RUD Ketten Rieger & Dietz differentiates through material science, specifically in high-tensile alloy products.
Automotive tire chains are traction-enhancing devices fitted to vehicle tires to improve grip on snow or ice. They are typically constructed from hardened steel links with a specific case hardness to resist abrasion. While standard chains for passenger vehicles are a mature product category, heavy-duty chains for trucks command higher margins. The installation type segment shows a shift toward quick-release systems over traditional manual-fit chains for convenience.
State-level Departments of Transportation in the US mandate chain usage during specific weather events, creating seasonal demand. In Europe, frameworks like France's "Loi Montagne II" and German winter tire laws compel drivers to carry chains in mountainous areas. The strategic decision for manufacturers is whether to optimize production of regulation-driven steel chains or invest in emerging polymer and composite materials.
Market Dynamics
The automotive tire chain market's evolution is defined by a core tension between regulation-driven demand for traditional steel products and a material science push toward lightweight, user-friendly alternatives. This dynamic creates distinct pathways for growth in both mature and emerging product categories.
Growth Catalysts
- Regulatory Mandates:Frameworks like France's Loi Montagne II and seasonal requirements from US state Departments of Transportation compel drivers in designated mountain areas to carry chains, creating non-discretionary, recurring demand.
- Commercial Logistics Expansion:The growth of long-haul trucking in cold-weather regions, particularly across Nordic countries and North America, sustains demand for durable, heavy-duty chains which command higher margins.
- Material Science Innovation:The development of advanced polymer and composite materials creates new product segments that appeal to passenger vehicle owners seeking lighter weight and easier installation than traditional steel.
Market Restraints
- Raw Material Cost Fluctuation:The industry's reliance on hardened steel makes manufacturers vulnerable to price volatility in the global steel market, directly impacting production costs and profit margins.
- Substitution by Advanced Tires:The performance of modern all-weather and winter tires, featuring specialized compounds and tread designs, reduces the perceived need for chains among some passenger car drivers in moderate winter conditions.
- Demand Seasonality:Sales are heavily concentrated in the winter months, leading to significant forecasting challenges, inventory carrying costs, and production inefficiencies for manufacturers during the off-season.
Strategic Opportunities
- Electric Vehicle (EV) Specific Products:There is an opportunity to design and market chains optimized for EVs, addressing factors like instant torque delivery, component clearance, and lower weight to minimize impact on battery range.
- Smart Chain Integration:Incorporating sensor technology for automatic tensioning, wear indication, or connectivity with vehicle telematics presents a pathway to create a new premium product tier for commercial and high-end consumer markets.
- Expansion in New Geographies:Targeting logistics fleets and passenger vehicle owners in mountainous regions of China and Eastern Europe, where winter preparedness infrastructure is developing, opens new revenue streams.
Industry Challenges
- Fragmented Compliance Requirements:Manufacturers face significant operational complexity and testing costs to ensure products meet disparate standards, such as the European Ö-Norm V 5117 and various state-level regulations in the United States.
- Consumer Adoption Hurdles:A persistent perception of difficult installation for traditional chains remains a barrier for many passenger vehicle owners, limiting adoption outside of legally mandated areas despite the availability of quick-fit systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Tire Chains Market |
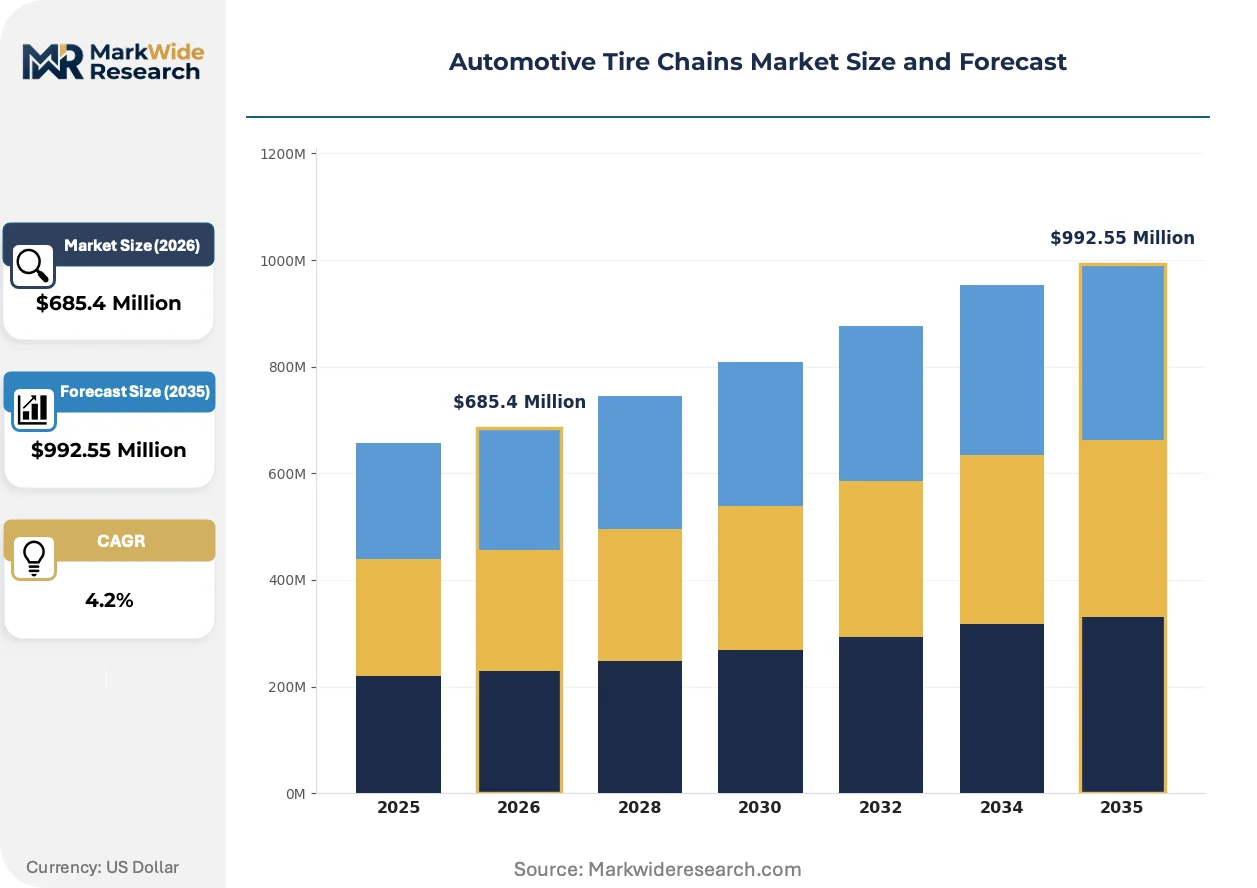
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Chains, Cable Chains, Heavy-Duty Chains, Snow Chains Material: Steel, Alloy, Composite, Polymer Application: Passenger Vehicles, SUVs, Trucks, Off-Road Vehicles Installation Type: Automatic, Manual, Semi-Automatic, Quick-Release |
| Companies Covered | Peerless Chain, Ottinger Schneeketten, KÖNIG Snow Chains, RUD Ketten Rieger & Dietz, Maggi Catene, Pewa, Laclede Chain, Veriga, Trygg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Tire Chains Market Strategic Shifts & Innovations
Material science advancements and a focus on user convenience are fundamentally altering product design and market expectations. Innovation is moving beyond the core function of traction to encompass ease of use, lighter weight, and compatibility with modern vehicle technologies, creating new value propositions.
Material Innovation in Passenger Vehicles
Advanced polymer composites and high-strength textiles are being engineered into lightweight traction aids. The passenger vehicle segment, particularly in Europe, is adopting these products for occasional emergency use. This trend toward easier-to-handle materials is displacing traditional, heavier steel chains for non-commercial drivers who prioritize convenience and simple storage over extreme durability.
Regulation as a Performance Benchmark
Europe's stringent Ö-Norm V 5117 standard from Austria is acting as a key differentiator in the market. This regulation forces manufacturers to meet high thresholds for traction, durability, and vehicle compatibility. Consequently, certified products are positioned as premium offerings, creating a clear performance and price differentiation from non-certified chains across the continent.
Shift Toward Convenient Installation
A clear preference for quick-release and self-tensioning systems is reshaping consumer purchasing decisions. The traditional manual-fit segment, requiring users to physically connect links behind the tire, is ceding market share to designs that can be installed without moving the vehicle. This demand-side shift is most pronounced in the North American and European passenger car markets.
Automotive Tire Chains Market Segmentation
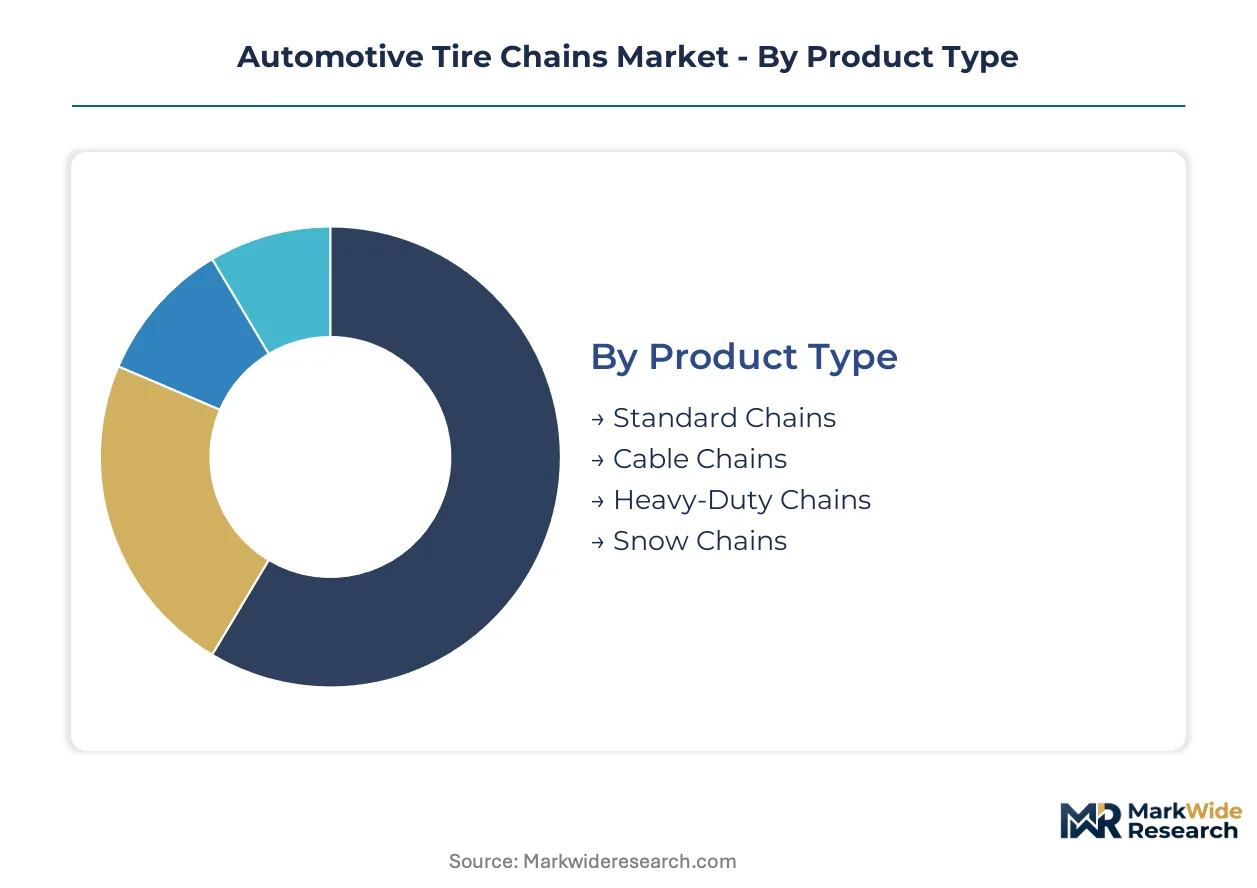
Market segmentation provides a granular view of the automotive tire chains industry, revealing distinct demand patterns and competitive dynamics. Understanding these segments allows manufacturers to tailor product development, pricing strategies, and distribution channels. This analysis highlights specific product attributes and end-user needs driving market evolution.
Product Type:
The product type segmentation highlights areas where traditional steel chains face the strongest substitution pressure from newer alternatives.
- Heavy-Duty Chains:These robust chains, typically made from hardened steel alloys, are engineered for commercial trucks and heavy equipment. Demand concentrates in long-haul logistics across cold climates like the Nordic countries, driven by stringent safety regulations and the need for reliable traction under extreme loads.
- Standard Chains:Comprising basic steel link designs, these chains serve the mass passenger vehicle market, offering essential traction for occasional snow and ice conditions. Their widespread adoption in Europe is often compelled by regional mandates like France's Loi Montagne II, making them a high-volume product.
- Cable Chains:Constructed from steel cables encased in plastic or rubber, these offer a lighter and quieter alternative to traditional chains for passenger cars. They primarily appeal to drivers seeking easier installation and smoother ride characteristics in moderate winter conditions.
- Snow Chains:This broad category encompasses various designs, including traditional steel link chains and newer composite solutions, specifically designed for enhanced grip on snowy surfaces. They are a mandatory safety accessory in many mountainous regions.
Standard Chains anchors the volume base while Heavy-Duty Chains gains share at the steepest rate.
Material:
Material segmentation reflects the industry's maturity curve, with established metallic options coexisting with innovative lightweight solutions.
- Steel:This material forms the backbone of the traditional tire chain market, valued for its durability, strength, and cost-effectiveness. Hardened steel chains are particularly prevalent in commercial trucking and passenger vehicle segments where robust performance is critical.
- Polymer:Advanced polymer compounds are increasingly utilized for lightweight, user-friendly traction devices, especially in the passenger vehicle segment. These materials offer easier installation and reduced vehicle impact compared to traditional metal chains, appealing to convenience-focused consumers.
- Alloy:High-tensile alloy steels provide superior strength-to-weight ratios and enhanced corrosion resistance compared to standard steel. Manufacturers like RUD Ketten Rieger & Dietz leverage these materials for premium, high-performance chains targeting demanding commercial applications and extreme conditions.
- Composite:These materials combine different substances, such as polymers and fibers, to achieve specific performance characteristics like reduced weight and improved flexibility. Composite chains are emerging as a niche for passenger vehicles, balancing traction with ease of handling.
Steel materials maintain market dominance, but polymer and composite offerings are expanding most quickly.
Application:
Application-based segmentation directly correlates with varying regulatory impacts and user priorities across vehicle types.
- Trucks:This segment represents a significant portion of market value, driven by the commercial logistics sector and strict transport regulations in cold regions. Heavy-duty chains are essential for long-haul freight operations, ensuring safety and compliance on icy roads in North America and Europe.
- Passenger Vehicles:The largest volume segment, passenger vehicles require chains for personal safety and regulatory compliance in winter conditions. Demand is influenced by convenience, ease of installation, and product compatibility with modern vehicle designs, particularly in the European and North American markets.
- SUVs:Sport Utility Vehicles often require more robust chain designs than standard passenger cars due to their weight and varying tire sizes. Owners seek reliable traction for adverse weather conditions, with a growing preference for quick-fit solutions.
- Off-Road Vehicles:Chains for off-road vehicles cater to specialized uses such as forestry, agriculture, and recreational activities in extreme terrain. These applications demand exceptionally durable and aggressive traction solutions.
Passenger Vehicles represent the largest installed base, while the Trucks segment concentrates the highest market value.
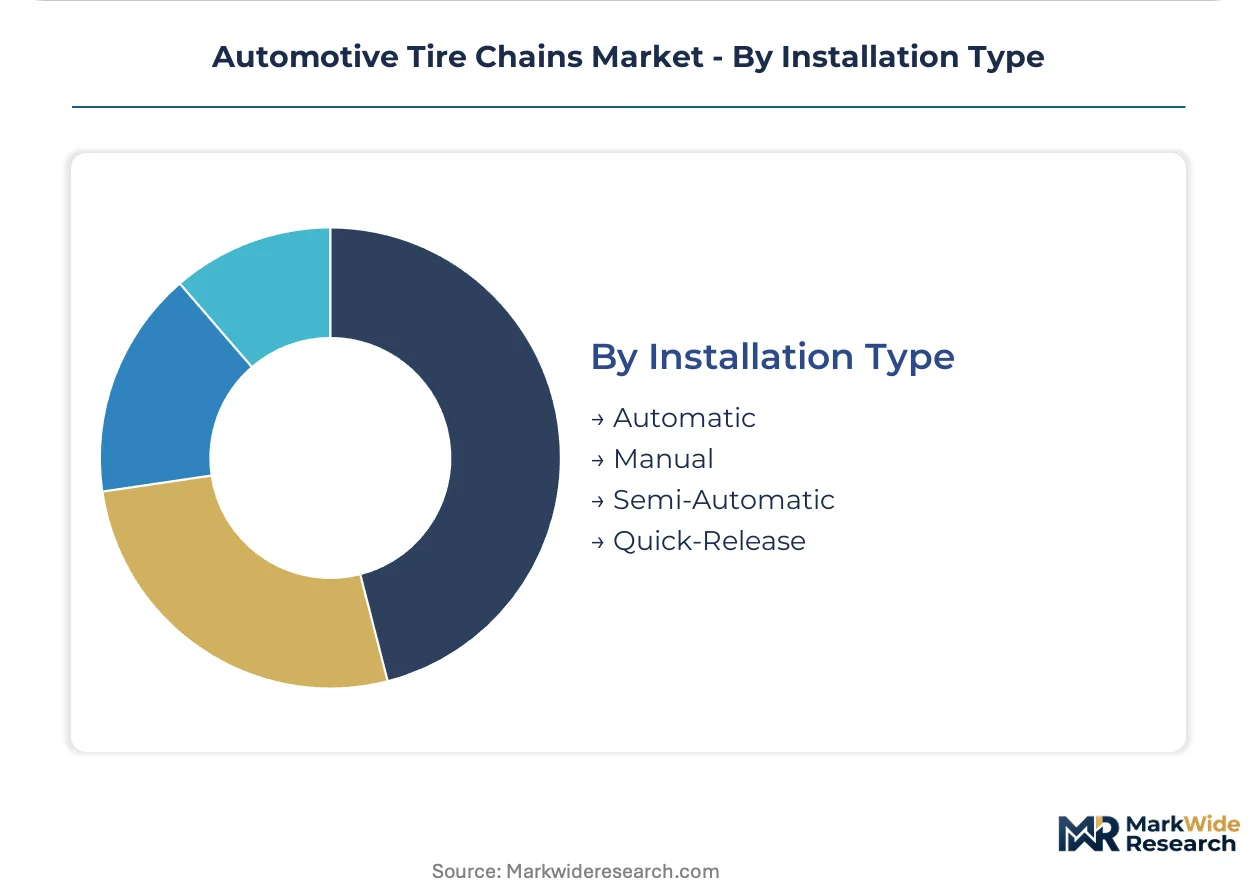
Installation Type:
Installation type segmentation underscores the market's evolving focus on user convenience and operational efficiency.
- Quick-Release:These systems allow for rapid and easy attachment and removal of chains, significantly reducing installation time and effort. The North American and European passenger car markets show a strong preference for quick-release designs, prioritizing user convenience.
- Manual:Traditional manual-fit chains require users to physically connect links behind the tire, often demanding more time and physical effort. This segment remains cost-effective and widely available, particularly for budget-conscious consumers and in regions with less stringent installation preferences.
- Automatic:Automatic chain systems are typically integrated into commercial vehicles, deploying traction devices with the push of a button from the cabin. These systems provide maximum convenience and safety for truck drivers, especially in frequently changing road conditions.
- Semi-Automatic:These systems offer a compromise between manual and fully automatic, often involving a simpler connection process than purely manual chains but still requiring some user interaction. They target consumers seeking improved ease of use without the higher cost of fully automatic solutions.
Manual installation remains prevalent due to cost, but quick-release systems are seeing the strongest demand-side shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive tire chains concentrates among commercial logistics operators and passenger vehicle owners navigating severe winter conditions. These buyers prioritize safety and regulatory compliance across diverse geographic terrains. The market's regional dynamics reflect varying climate patterns, infrastructure development, and specific legislative mandates impacting chain usage.
United States
Commercial trucking fleets and passenger vehicle owners in mountainous states drive significant demand for tire chains. US state Departments of Transportation mandate chain usage during specific weather events, particularly in regions like the Rocky Mountains. The Colorado Front Range and other high-altitude areas exhibit consistent demand for robust traction solutions.
Norway
Long-haul logistics operations and private vehicle owners generate high demand for durable tire chains due to harsh Nordic winters. Comprehensive road safety regulations across Scandinavia compel drivers to ensure adequate traction on snow and ice. Major transport corridors connecting cities like Oslo and Bergen demonstrate continuous need for heavy-duty chains.
France
Passenger vehicle owners represent a substantial volume segment, largely compelled by winter driving regulations. France's "Loi Montagne II" mandates carrying chains in designated mountainous areas, creating non-discretionary seasonal demand. The Alpine regions, including areas around Grenoble and Chamonix, are primary consumption hubs for these products.
Germany
Passenger vehicle demand is influenced by strict German winter tire laws, which often necessitate chains in extreme conditions. Specific regional mandates apply in mountainous areas like Bavaria and the Black Forest. Logistics operations also require reliable traction solutions for routes through these challenging terrains.
China
Emerging demand stems from expanding logistics fleets and a growing number of passenger vehicle owners in western and northern mountainous regions. Developing winter preparedness infrastructure and increasing awareness of road safety drive new market opportunities. Provinces such as Sichuan and Xinjiang are seeing increased adoption for heavy transport and personal use.
Automotive Tire Chains Market Key Industry Players
Player mix skews toward specialized manufacturers focusing on distinct market segments and material innovations. The automotive tire chains market exhibits a tiered structure, with premium brands leveraging regulatory compliance for market differentiation. Specialists often target either heavy-duty commercial applications or convenience-driven passenger vehicle segments, creating clear competitive vectors. Strategic moves include optimizing production for regulation-driven steel chains and investing in emerging polymer and composite materials for new product categories.
Specialists in high-performance materials and regulatory compliance include KÖNIG Snow Chains, which leverages its adherence to stringent European standards for a premium market position. Peerless Chain exemplifies a North American focus, anchoring its offerings in heavy-duty chains designed for commercial trucking and meeting specific US transport regulations. RUD Ketten Rieger & Dietz further differentiates through material science expertise, developing high-tensile alloy products tailored for demanding commercial applications and extreme conditions. These entities collectively represent distinct approaches to market penetration and value creation across different geographic and application segments within the automotive tire chains industry.
| Leading Market Players |
|---|
| Peerless Chain |
| Ottinger Schneeketten |
| KÖNIG Snow Chains |
| RUD Ketten Rieger & Dietz |
| Maggi Catene |
| Pewa |
| Laclede Chain |
| Veriga |
| Trygg |
| Others |
Cost & Logistics Intelligence
Inventory carrying costs, particularly during off-season periods, directly influence pricing strategies and production planning. This dynamic reflects the highly seasonal demand patterns inherent in the automotive tire chains market.
Pricing Analysis
Cost-plus contract pricing, often indexed to global steel prices, governs large commercial fleet procurements. Price differentiation stems from stringent certification levels like Ö-Norm V 5117 compliance and specialized material science in high-tensile alloys. Pricing softness stems from raw material cost fluctuations in hardened steel and substitution pressure from advanced winter tires. Passenger vehicle owners buying standard chains exhibit higher price sensitivity compared to commercial trucking operators prioritizing durability and regulatory adherence.
Supply Chain Analysis
Container availability for inbound raw materials, particularly hardened steel from major industrial hubs, impacts production schedules and costs. Manufacturing centers for automotive tire chains include Germany, Italy, and the United States, reflecting specialized production capabilities. The industry sources heavily from hardened steel, polymers, and composite materials. Raw material price volatility represents a significant structural risk. Downstream distribution channels include automotive aftermarket retailers for passenger vehicles and direct sales to commercial fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a robust substitution defense strategy from incumbents. Advanced all-weather and winter tires present a significant threat, displacing traditional chains for passenger car owners in moderate winter conditions.
For Market Incumbents:
Fortify market position by accelerating R&D into lightweight polymer and composite materials, directly addressing the threat from advanced winter tires. Invest in achieving European Ö-Norm V 5117 compliance to sustain premium pricing and market access. Consolidate fragmented compliance requirements through modular product designs adaptable to various US state regulations. Leverage existing distribution channels to promote quick-release systems, enhancing user convenience.
For New Entrants and Emerging Players:
Ö-Norm V 5117 certification fast-track programs offer a pathway to immediate European market credibility. Target the electric vehicle segment with optimized, lightweight polymer chains, addressing component clearance and range concerns. Focus on emerging geographies like mountainous regions of China, where winter preparedness infrastructure is developing. A go-to-market strategy emphasizing user convenience and smart chain integration, including automatic tensioning, can differentiate offerings.
For Investors and Strategic Acquirers:
Carve-out targets emerge from diversified automotive component suppliers seeking to divest non-core traditional manufacturing assets. The market maintains long-term viability due to non-discretionary regulatory mandates and commercial logistics expansion. Acquisition archetypes include specialist manufacturers excelling in advanced polymer composites or smart chain technology. A key signal to watch is the rate of new regulatory mandates for winter tire accessories in previously unaddressed mountainous regions.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Polymer Composites | Develops lighter, user-friendly products for passenger vehicles, countering substitution from advanced tires. |
| Ö-Norm V 5117 Certification | Secures premium market access and differentiation within the stringent European regulatory landscape. |
| EV-Specific Product Development | Addresses unique electric vehicle requirements like torque delivery and component clearance, opening new segments. |
| Expansion into China's Mountainous Regions | Captures emerging demand from growing logistics fleets and passenger vehicle owners in new geographies. |
| Investment in Quick-Release Systems | Meets consumer preference for convenient installation, expanding adoption beyond legally mandated areas. |
Research Approach
A spread of perspectives from commercial fleet managers, automotive aftermarket retailers, material science engineers, and regulatory compliance officers converged on the working assumptions. Primary interviews validated insights derived from extensive secondary research, including US Department of Transportation reports and European regulatory frameworks. This approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data triangulation.
Product type, material, application, installation type, and regional regulatory cluster formed the core segmentation dimensions modeled over the projection horizon. The analytical framework integrated historical growth patterns with anticipated shifts in consumer preferences and regulatory landscapes. Compound Annual Growth Rates were derived through regression analysis of historical data and projected future demand. Key forecast inputs included vehicle registration data and regional winter weather patterns.
Underlying assumptions cover stable regulatory enforcement and predictable raw material supply, with deviation risk concentrated in unforeseen shifts in climate patterns. Forecasts reflect these assumptions. Rapid advancements in alternative tire technologies could also revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Tire Building Machinery Market
Tires and Wheels
Automotive Winter Tire Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
United States Tire Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Racing Tires Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Truck and Bus Tires Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
Bias Tire Market