
 Automotive Smart Tire Market | 2026-2036
Automotive Smart Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Smart Tire Market Intelligence
Market Context
German automotive suppliers is pivoting toward embedded sensor production for next-generation tire platforms. Michelin Group leverages its R&D intensity in radio-frequency identification integration to sustain technology leadership. Continental AG anchors European OEM supply relationships through captive semiconductor partnerships. Bridgestone Corporation competes on manufacturing scale across Asia-Pacific assembly plants.
Technical Definition and Segments
Automotive Smart Tire refers to tire systems incorporating embedded sensors, microprocessors, and wireless communication modules to monitor pressure, temperature, tread depth, and road conditions in real time, typically operating at pressure ranges of 30-80 PSI depending on vehicle class. Pressure Monitoring Tires dominate current revenue pools due to regulatory mandates, while MEMS Sensors represent the fastest-expanding technology segment as unit costs decline and integration density improves. Fleet Operators command disproportionate margin capture among end users through volume contracting and predictive maintenance value propositions.
Regulatory Frame and Outlook
The European Union's F-Gas Regulation and General Safety Regulation framework shape product standards for sensor durability and data transmission protocols, while NHTSA in the United States enforces tire pressure monitoring system requirements under FMVSS 138. Japan's METI promotes connected mobility standards that indirectly accelerate smart tire testing protocols. Stakeholders must monitor evolving cybersecurity certification requirements for vehicle-to-infrastructure data streams as regulatory scope broadens beyond mechanical safety into information integrity.
Market Dynamics
MEMS sensor miniaturization is compressing unit economics while embedding intelligence deeper into tire architectures, forcing suppliers to recalibrate around semiconductor partnerships rather than rubber compounding alone.
Growth Catalysts
- F-Gas Regulation:The European Union's framework mandates sensor durability standards that accelerate OEM integration timelines for connected tire platforms.
- Fleet telematics convergence:Commercial vehicle operators in Germany and the United States are bundling tire data into predictive maintenance suites to capture fuel efficiency gains.
- MEMS cost curves:Semiconductor foundry scale in Taiwan and South Korea is driving sensor unit costs toward mass-market passenger vehicle thresholds.
Market Restraints
- Silicon supply concentration:Taiwan Semiconductor Manufacturing Company and Samsung Foundry control advanced MEMS fabrication nodes, creating single-source vulnerability for tier-two tire suppliers.
- Cybersecurity certification friction:NHTSA's evolving FMVSS guidance on vehicle-to-infrastructure data integrity is extending validation timelines without clear harmonization with EU protocols.
- RFID tag cost floors:Passive radio-frequency identification components face raw material volatility in copper and silver ink supply chains.
Strategic Opportunities
- India aftermarket penetration:Commercial fleet density in Maharashtra and Gujarat remains underserved by real-time tire monitoring despite rising highway freight volumes.
- Japan METI connected mobility standards:Government-funded testbeds in Kanagawa Prefecture are creating regulatory sandboxes for smart tire data monetization models.
- Edge-AI sensor fusion:Combining MEMS accelerometers with machine learning inference at the tire-rim interface enables road condition mapping without cloud dependency.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineering for ISO 26262 compliance competes with autonomous vehicle programs for limited firmware specialists.
- Legacy vehicle integration complexity:CAN bus protocol fragmentation across pre-2020 vehicle fleets forces expensive adapter hardware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Smart Tire Market |
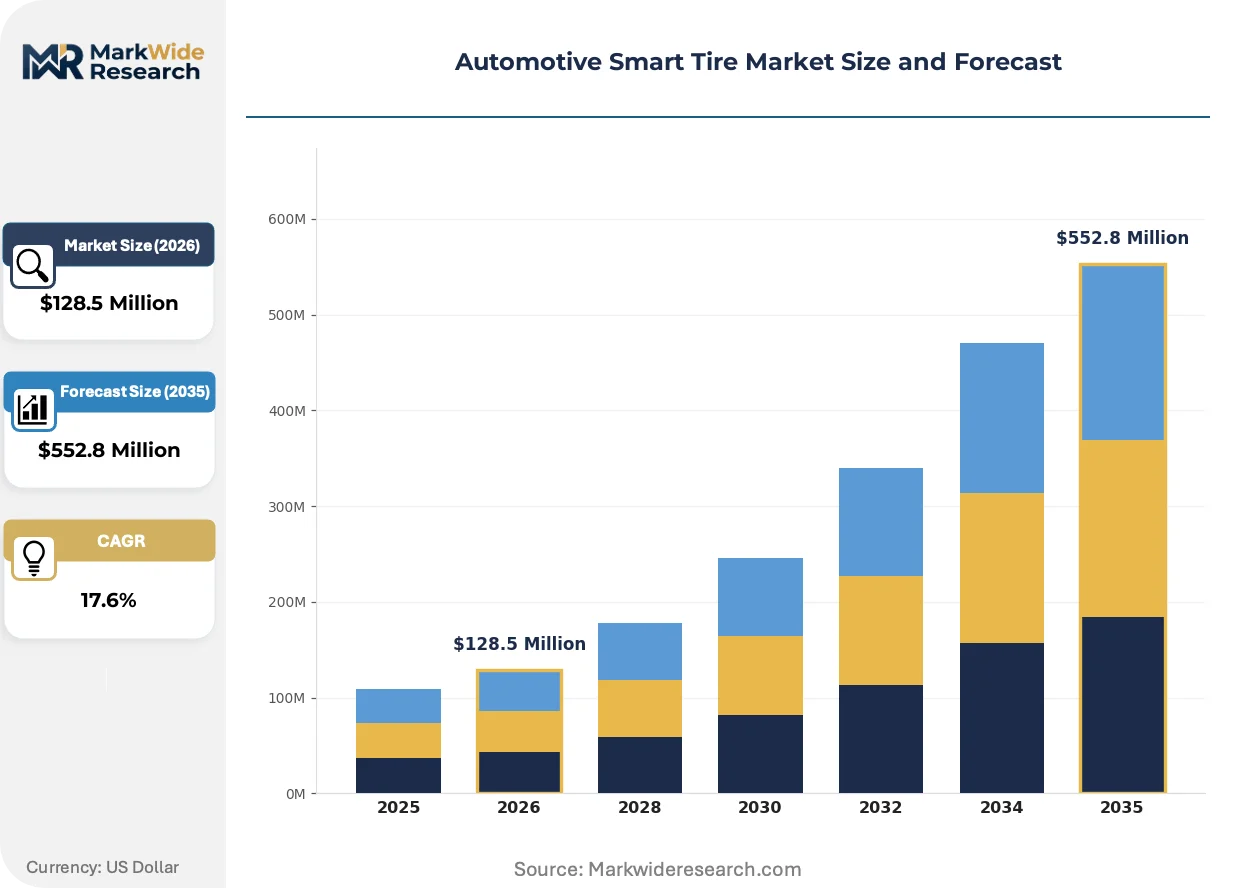
| Market Size in 2026 | $128.5 Million |
| Market Size in 2035 | $552.8 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Monitoring Tires, Temperature Sensing Tires, Tread Wear Detection Tires, Run-Flat Tires, Self-Inflating Tires Technology: RFID Sensors, Piezoelectric Sensors, Capacitive Sensors, MEMS Sensors, Bluetooth Connectivity Application: Personal Vehicles, Commercial Transport, Two-Wheelers, Construction Equipment, Agricultural Machinery End User: OEMs, Aftermarket Suppliers, Fleet Operators, Tire Retreaders, Specialty Vehicle Manufacturers |
| Companies Covered | The Goodyear Tire & Rubber Company, Sumitomo Rubber Industries, Michelin Group, Nokian Tyres, Hankook Tire & Technology, Continental AG, Pirelli & C. S.p.A., NXP Semiconductors, Bridgestone Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Smart Tire Market Strategic Shifts & Innovations
Intelligence migration toward the tire-rim boundary is redefining supplier value capture, compressing the traditional tiering between rubber manufacturers and electronics integrators.
Self-powered sensor architectures are modularizing around energy harvesting from tire deformation and thermal differentials. Commercial fleet operators in Germany are piloting these systems at scale to eliminate battery replacement cycles. This shift is modularizing maintenance schedules and compressing total cost of ownership calculations for long-haul operators.
CSRD disclosure requirements in the European Union are mandating tire lifecycle emissions tracking from raw material extraction through end-of-life recycling. OEM procurement teams are now requiring sensor-enabled traceability as a qualification criterion. Premium vehicle platforms in Stuttgart and Munich are the first to embed these reporting capabilities into standard specifications.
Leasing companies are unbundling tire monitoring from vehicle finance packages to offer standalone usage-based insurance products. Munich Re and Swiss Re are structuring parametric contracts around real-time tread depth and pressure data. This behavioral shift is most visible in German and Swiss commercial vehicle markets where fleet lessors command pricing power over owner-operators.
Automotive Smart Tire Market Segmentation
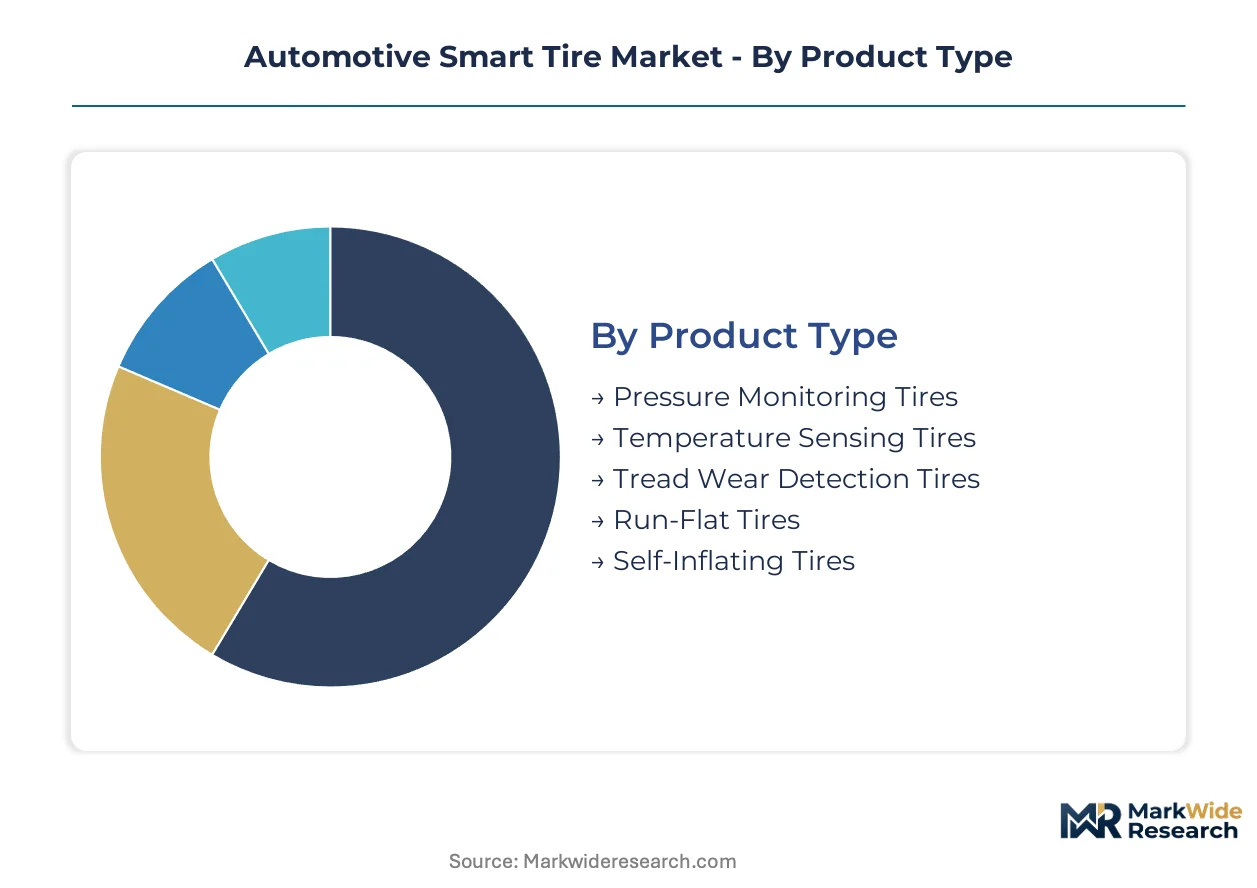
Smart tire architectures diverge sharply between regulatory-mandated baseline functions and premium predictive capabilities. Understanding these fault lines exposes where semiconductor integration creates margin capture versus commodity pressure.
Product Type:
Volume concentrates in pressure compliance systems, while premium capture flows toward predictive wear and autonomous maintenance functions.
- Pressure Monitoring Tires:Embedded piezoelectric or capacitive sensors transmit real-time PSI readings to vehicle ECUs. Fleet operators in Germany bundle these into telematics suites for fuel efficiency compliance under EU F-Gas Regulation durability standards.
- Tread Wear Detection Tires:Laser-etched groove patterns combined with accelerometer arrays measure remaining tread depth. Commercial transport operators in the United States pilot these for parametric insurance contracts with Munich Re and Swiss Re.
- Temperature Sensing Tires:Thermocouple grids track thermal buildup during high-speed operation.
- Run-Flat Tires:Reinforced sidewalls with integrated deflation alerts for passenger safety.
- Self-Inflating Tires:Peristaltic pumps activated by centrifugal force maintain optimal pressure.
Mature deployment sits with Pressure Monitoring Tires. Newer deployment is concentrated in Tread Wear Detection Tires.
Technology:
Passive RFID tags anchor low-cost traceability, while active MEMS arrays command pricing power through sensor fusion complexity.
- MEMS Sensors:Micro-electromechanical accelerometers and gyroscopes fabricated at Taiwan Semiconductor Manufacturing Company and Samsung Foundry nodes enable six-axis motion sensing. Automotive electronics clusters in Stuttgart and Munich integrate these for road condition mapping.
- RFID Sensors:Passive UHF tags with copper antennae provide unique tire identification across lifecycle tracking. CSRD disclosure requirements in the European Union mandate these for emissions traceability from raw material extraction through recycling.
- Piezoelectric Sensors:Ceramic elements generate voltage from mechanical deformation.
- Capacitive Sensors:Electrode pairs detect pressure changes through dielectric variation.
- Bluetooth Connectivity:Low-energy modules enable direct smartphone pairing for aftermarket diagnostics.
Supply security concerns cluster around MEMS Sensors. Fastest cost decline is occurring in RFID Sensors.
Application:
Passenger vehicle volumes dominate unit shipments, while commercial transport yields disproportionate revenue per tire through predictive maintenance contracts.
- Commercial Transport:Heavy-duty truck and bus fleets deploy multi-sensor arrays for axle load balancing and brake temperature correlation. Long-haul operators across Interstate highway corridors in the United States capture fuel efficiency gains through real-time pressure optimization.
- Personal Vehicles:Premium sedans and SUVs integrate pressure and temperature monitoring as standard equipment. OEM procurement teams in Japan's Kanagawa Prefecture testbeds require sensor-enabled traceability for connected mobility certification.
- Two-Wheelers:Motorcycle tires with embedded pressure alerts for sport and touring segments.
- Construction Equipment:Off-road tires with load-bearing sensors for earthmoving machinery.
- Agricultural Machinery:Tractor tires with soil compaction monitoring for precision farming.
Regulatory momentum is strongest in Commercial Transport. Technology experimentation is most active in Personal Vehicles.
End User:
OEM integration timelines determine technology validation cycles, while aftermarket channels fragment around legacy vehicle protocol adaptation.
- Fleet Operators:Volume contracting entities in Germany and the United States bundle tire data into predictive maintenance platforms. These operators command pricing power over owner-operators through usage-based insurance unbundling.
- OEMs:Vehicle manufacturers in Stuttgart, Munich, and Kanagawa Prefecture embed smart tire specifications into premium platform requirements. ISO 26262 functional safety compliance extends firmware validation timelines.
- Aftermarket Suppliers:Independent distributors serving pre-2020 vehicle fleets with CAN bus adapter hardware.
- Tire Retreaders:Remanufacturing specialists requiring sensor compatibility for second-life casings.
- Specialty Vehicle Manufacturers:Niche producers of emergency and military vehicles with custom pressure ranges.
Margin capture concentrates with Fleet Operators. Protocol fragmentation burdens Aftermarket Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rubber compounding feedstock from Southeast Asian plantations flows into sensor-embedded tire production clusters across three continents. Semiconductor foundry output from Taiwan and South Korea enables MEMS integration at scale. Fleet telematics adoption concentrates where fuel efficiency regulations bite hardest and commercial vehicle density supports predictive maintenance economics.
United States
Long-haul freight corridors along Interstate highways generate concentrated demand for real-time pressure optimization and axle load balancing. NHTSA enforces tire pressure monitoring requirements under FMVSS 138, accelerating OEM integration timelines for connected platforms. Detroit-area automotive electronics clusters embed smart tire specifications into heavy-duty truck procurement standards.
Germany
Commercial fleet operators in Bavaria and Baden-Württemberg bundle tire data into predictive maintenance suites for fuel efficiency compliance. The EU F-Gas Regulation mandates sensor durability standards that compress validation cycles for tier-one suppliers. Stuttgart's premium vehicle manufacturing ecosystem requires sensor-enabled traceability for CSRD emissions disclosure compliance.
Japan
Kanagawa Prefecture testbeds under METI connected mobility standards create regulatory sandboxes for smart tire data monetization models. Automotive electronics clusters in the Tokyo-Yokohama corridor integrate MEMS accelerometers for road condition mapping without cloud dependency. Domestic OEM procurement teams require ISO 26262 functional safety certification for firmware validation.
China
Yangtze River Delta automotive manufacturing hubs absorb MEMS sensor output from Taiwan Semiconductor Manufacturing Company nodes for domestic tire platform integration. The country's national automotive safety regulator advances connected vehicle standards that indirectly accelerate smart tire testing protocols. Shanghai-based fleet operators pilot edge-AI sensor fusion for commercial transport predictive maintenance.
India
Commercial fleet density in Maharashtra and Gujarat remains underserved by real-time tire monitoring despite rising highway freight volumes. The Bureau of Indian Standards develops automotive electronics certification frameworks that will shape sensor durability requirements. Chennai's automotive component manufacturing corridor attracts sensor integrators targeting aftermarket penetration for two-wheeler and commercial vehicle segments.
Automotive Smart Tire Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue semiconductor partnership models that bypass traditional rubber compounding advantages. The vendor base stratifies between integrated tire-electronics hybrids and component specialists supplying MEMS arrays to multiple rubber manufacturers. Three archetypes dominate: captive semiconductor partnerships, manufacturing scale operators, and RFID integration specialists. Competitive moves concentrate on strategic partnerships with foundry operators and portfolio diversification into predictive maintenance software layers.
Within the integrated tier, Continental AG exemplifies the captive semiconductor partnership archetype through European OEM supply anchoring. Michelin Group occupies a position representing RFID integration intensity for next-generation tire platforms. Bridgestone Corporation anchors the manufacturing scale archetype across Asia-Pacific assembly plants. Sumitomo Rubber Industries and Nokian Tyres sit within specialist positioning for regional market penetration. The Goodyear Tire & Rubber Company and Hankook Tire & Technology represent transatlantic and Korean manufacturing scale respectively, while Pirelli & C. S.p.A. exemplifies premium-tier focus. NXP Semiconductors represents the pure-play semiconductor supplier archetype enabling sensor fusion across multiple tire OEM programs.
| Leading Market Players |
|---|
| The Goodyear Tire & Rubber Company |
| Sumitomo Rubber Industries |
| Michelin Group |
| Nokian Tyres |
| Hankook Tire & Technology |
| Continental AG |
| Pirelli & C. S.p.A. |
| NXP Semiconductors |
| Bridgestone Corporation |
| Others |
Cost & Logistics Intelligence
Fleet operator concentration in Germany and the United States anchors contract-based long-term offtake structures, with volume bundling into predictive maintenance suites compressing spot-market exposure for tier-one suppliers.
Pricing Analysis
Warranty and service unbundling distinguishes premium tiers from standard offerings, with OEM procurement teams in Stuttgart and Munich demanding sensor-enabled traceability as a qualification criterion under CSRD disclosure requirements. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 certification grade and after-sales telemetry bundling. Cost compression in MEMS-integrated tiers is intensifying because semiconductor foundry scale in Taiwan and South Korea drives sensor unit costs toward mass-market thresholds. Aftermarket suppliers serving pre-2020 vehicle fleets exhibit highest price sensitivity due to CAN bus adapter hardware development burdens.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan Semiconductor Manufacturing Company and Samsung Foundry for advanced MEMS fabrication nodes. Production draws from Taiwan, South Korea, and Germany for semiconductor integration, with rubber compounding feedstock sourced from Southeast Asian plantations. Raw material dependencies center on copper and silver ink for RFID antennae, piezoelectric ceramics, and silicon wafers. Tariff exposure on semiconductor imports creates structural risk for tier-two tire suppliers lacking captive foundry partnerships. Distribution runs through OEM direct supply agreements and aftermarket distributor networks serving commercial fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Smart Tire Market sits in a technology-transition phase, with MEMS sensor miniaturization displacing legacy passive RFID architectures as the dominant embedded intelligence platform.
For Market Incumbents: Lock in captive semiconductor partnerships with Taiwan Semiconductor Manufacturing Company or Samsung Foundry nodes to defend against silicon supply concentration risks. Secure ISO 26262 functional safety certification ahead of NHTSA cybersecurity guidance finalization to extend firmware validation timelines as a competitive moat. Deepen backward integration into MEMS accelerometer design to capture road condition mapping value pools. For New Entrants and Emerging Players: Launch via aftermarket distributor channels targeting commercial fleet density in Maharashtra and Gujarat, where real-time tire monitoring remains underserved despite rising highway freight volumes. Exploit edge-AI sensor fusion white space for road condition mapping without cloud dependency. Target parametric insurance unbundling partnerships with Munich Re and Swiss Re as the most penetrable revenue model. For Investors and Strategic Acquirers: The window for entry favors semiconductor-tire hybrid specialists with functional safety engineering capabilities. Long-term viability hinges on regulatory sandbox positioning under Japan METI connected mobility standards. Watch NHTSA-EU protocol harmonization progress as the inflection signal for validation timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Partnership | Secures MEMS foundry allocation ahead of tier-two supplier competition for Taiwan node access. |
| ISO 26262 Certification Investment | Accelerates OEM procurement qualification under Stuttgart and Munich premium platform requirements. |
| Predictive Maintenance Software Layer | Captures recurring revenue from German fleet operator telematics convergence for fuel efficiency compliance. |
| Edge-AI Sensor Fusion Development | Enables road condition mapping without cloud dependency under Japan METI testbed standards. |
| Aftermarket Channel Expansion | Penetrates underserved commercial fleet density in Maharashtra and Gujarat highway corridors. |
Research Approach
Multi-period observation of MEMS sensor cost curves, fleet telematics adoption rates, and regulatory validation timelines anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet operations managers. Secondary validation drew from NHTSA FMVSS guidance documents, EU F-Gas Regulation durability standards, Japan METI connected mobility testbed reports, and vehicle production databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across automotive electronics manufacturing clusters.
Segment-weighting across product type, technology, application, and end-user dimensions informed the analytical framework over the projection horizon. Modeled dimensions included pressure monitoring versus predictive wear functions, MEMS versus RFID sensor architectures, commercial transport versus personal vehicle deployment, and OEM versus aftermarket channel structures. CAGRs derived from fitted growth curves applied to semiconductor unit cost decline trajectories and fleet operator contract volume patterns.
The model assumes a particular technology adoption path; alternative pathways for self-powered energy harvesting architectures would alter the outlook if commercial fleet pilots in Germany demonstrate superior total cost of ownership economics. Forecasts reflect assumptions about regulatory harmonization between NHTSA and EU protocols, cybersecurity certification friction resolution, and silicon supply concentration stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Truck and Bus Tires Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Global Automotive Tire Inflator Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Indirect Tire Pressure Monitoring System Market
Tires and Wheels
Asia Pacific 2-Wheeler Tire Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Europe Agricultural Tires Market
Tires and Wheels
Tire Cord Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Automotive Green Tires Market