
 Car Refrigerator Market | 2026-2036
Car Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Car Refrigerator Market Analysis
Subscription-based temperature monitoring and remote diagnostics is consolidating around the hardware sale, transforming one-time purchases into recurring revenue relationships. Dometic leverages its integrated smart-control platform to sustain aftermarket service attach rates. ARB anchors its position in the Australian and North American overlanding segments through ruggedized compressor units. Webasto competes across European OEM channels with factory-fit refrigeration for premium van conversions.
A car refrigerator is a portable thermoelectric, compressor, or absorption cooling unit engineered to maintain sub-ambient temperatures within vehicle cabins, typically operating from 12V or 24V DC supplies with power draws between 30W and 150W depending on compressor technology and insulation specification. These units serve commercial fleet cold transport, recreational vehicle food preservation, and consumer outdoor recreation where grid-independent cooling extends trip duration and payload flexibility. Compressor refrigerators command the dominant margin pool due to superior coefficient of performance and freezing capability down to minus 18 degrees Celsius, while thermoelectric coolers occupy the entry price band with lighter weight and silent operation suited to short-duration private vehicle use. Solar-powered configurations represent the fastest-growing power-source segment as panel efficiency gains and MPPT charge controllers enable off-grid deployment for remote camping and expedition vehicles.
FCC certification governs wireless-enabled smart refrigerator modules in the United States, while NHTSA crashworthiness guidelines influence mounting hardware and projectile-risk design for in-cabin installation. EPA energy-consumption labeling programs shape consumer comparison behavior and manufacturer R&D prioritization toward lower amp-draw compressors. Stakeholders must monitor evolving state-level zero-emission vehicle mandates that could restrict idling-based power delivery and accelerate demand for high-efficiency battery-native refrigeration architectures.
Market Dynamics
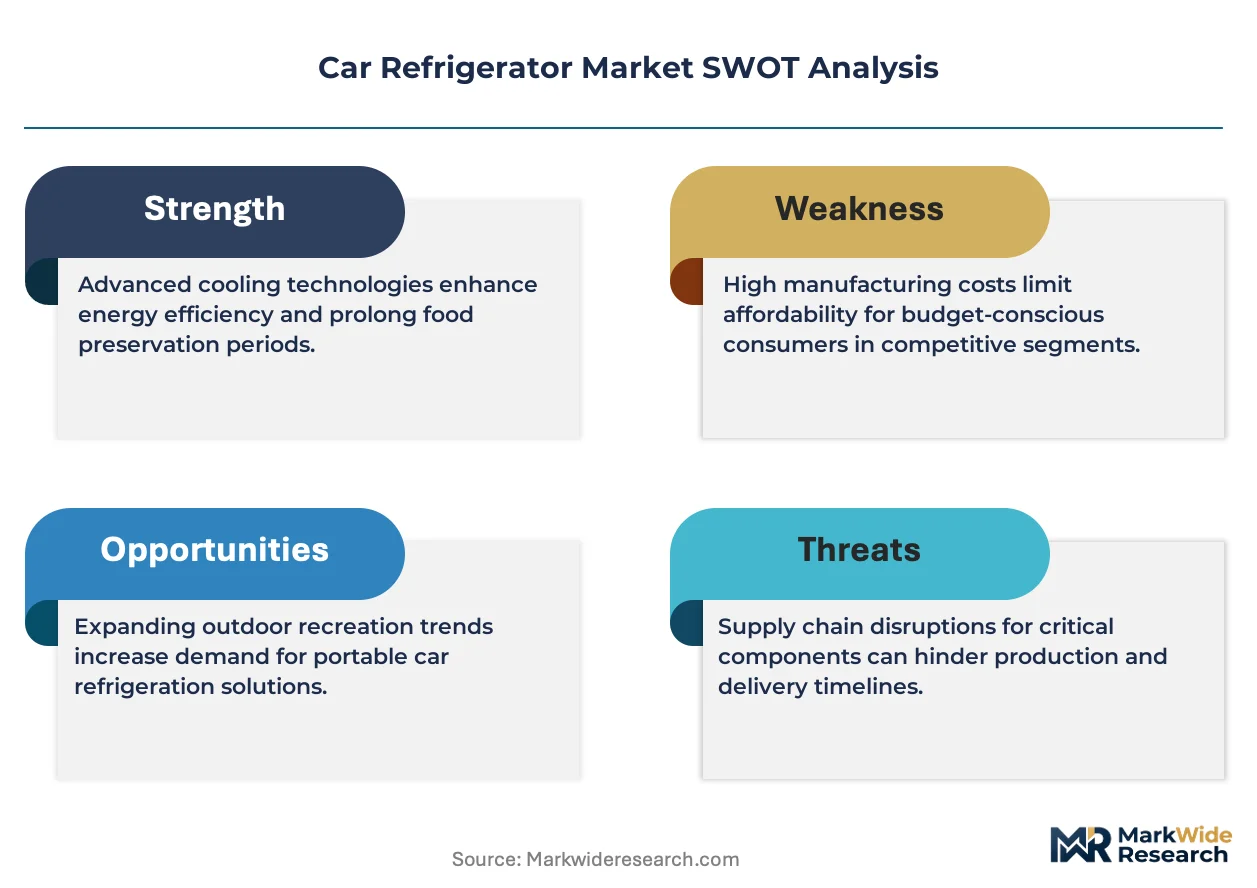
Fleet electrification timelines are compressing refrigeration design cycles as commercial van operators demand battery-native cooling architectures that eliminate engine-idling dependency.
Growth Catalysts
- EPA fuel-efficiency standards:Manufacturers accelerate low-power compressor R&D to meet Corporate Average Fuel Economy thresholds for light commercial vehicles.
- Last-mile delivery expansion:Cold-chain logistics operators retrofit van fleets with DC-native refrigeration to capture pharmaceutical and perishable grocery contracts.
- Solar panel efficiency gains:MPPT charge controllers enable off-grid deployment for expedition vehicles and remote camping applications.
Market Restraints
- Compressor component concentration:Sealed unit supply clusters in Chinese manufacturing zones, exposing procurement to tariff volatility.
- Thermoelectric performance ceiling:Peltier modules cannot achieve freezing temperatures, limiting addressable market in pharmaceutical transport.
- Lithium battery cost exposure:Raw material price swings for cells used in portable power stations compress margin on solar-refrigerator bundles.
Strategic Opportunities
- Indian pharmaceutical cold chain:CDSCO temperature-compliance mandates for vaccine distribution create fleet retrofit demand.
- Subscription telemetry services:Remote temperature monitoring and predictive maintenance transform hardware sales into recurring revenue streams.
- Vanlife platform convergence:Integration with vehicle telematics and smart-home ecosystems opens OEM factory-fit channels.
Industry Challenges
- FCC certification timelines:Wireless-enabled smart modules face 6-12 month approval cycles for connected refrigeration controls.
- Thermal engineering talent scarcity:Specialized expertise in low-amp-draw compressor design concentrates among legacy automotive HVAC suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Refrigerator Market |
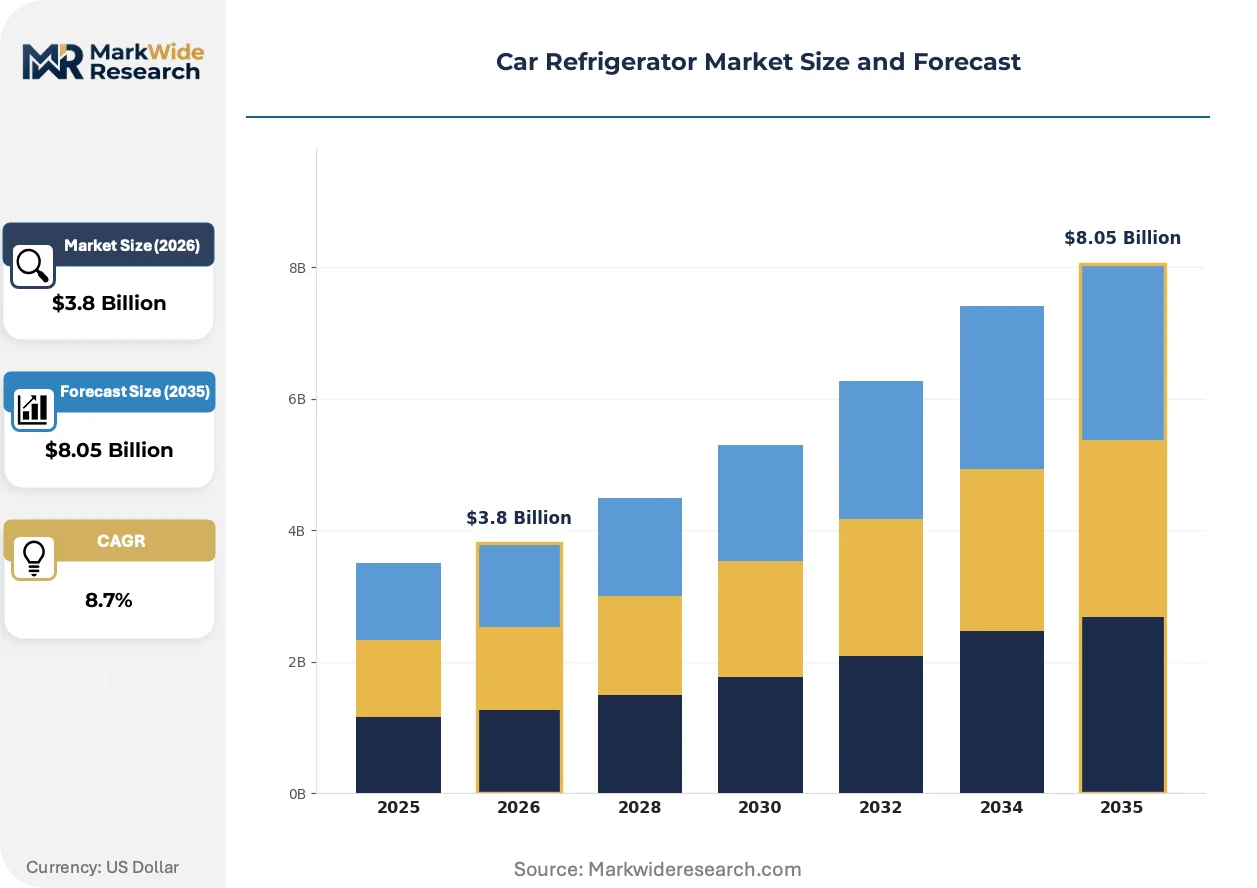
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Coolers, Compressor Refrigerators, Thermoelectric Coolers, Absorption Refrigerators End User: Private Vehicle Owners, Fleet Operators, RV Owners, Off-Road Enthusiasts Capacity: 20-30 Liters, 31-50 Liters, 51-70 Liters, Above 70 Liters Power Source: 12V Battery, 24V Battery, AC Adapter, Solar Powered |
| Companies Covered | Whynter, Coleman, Dometic, Indel B, Webasto, Engel, Igloo, BougeRV, ARB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Refrigerator Market Emerging Trajectories
Refrigeration architecture is bifurcating between battery-optimized efficiency and connectivity-enabled service models, with hardware design decisions now preceding software stack choices.
Variable-speed DC compressors are converging with vehicle-native electrical systems to eliminate inverter losses and extend runtime on auxiliary battery banks. Off-road expedition builders and overland outfitters in the Mountain West specify these units for multi-day autonomy. The technology is compressing the addressable gap between thermoelectric coolers and full compressor systems.
CARB emissions rules for medium- and heavy-duty vehicles are forcing refrigeration suppliers to certify idle-reduction technologies. Fleet operators in California face penalties for engine-idling beyond five minutes, accelerating demand for battery-powered cooling. Refrigerated van upfitters respond with factory-integrated lithium architectures that meet NHTSA crashworthiness guidelines.
Buyers now expect unbundled after-sales service contracts separate from hardware purchase. Commercial fleet managers negotiate remote diagnostics and preventive maintenance subscriptions independent of unit procurement. This pattern concentrates in United States Sun Belt states where RV and vanlife ownership rates drive premium service attach rates.
Car Refrigerator Market Segmentation
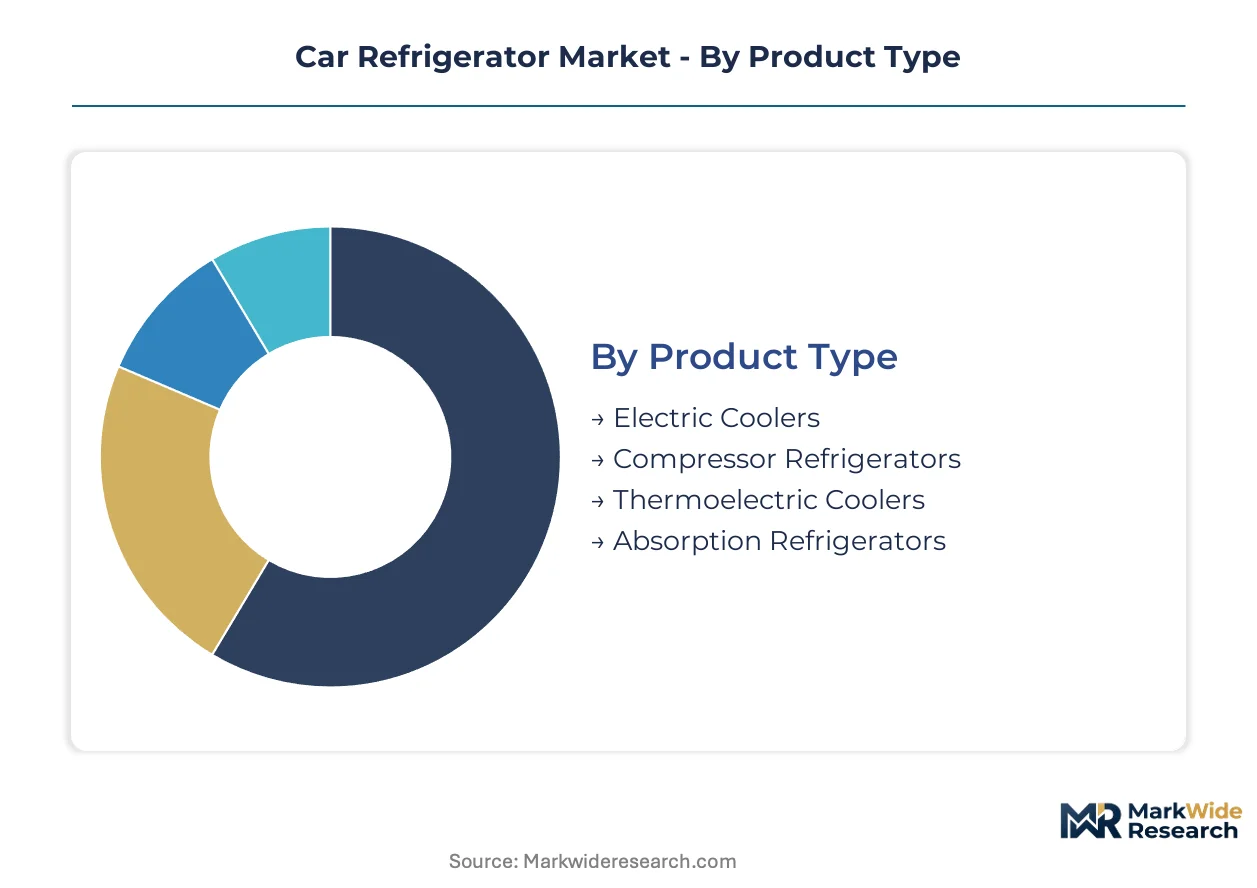
Segmentation in the car refrigerator market reveals divergent engineering priorities across buyer types. Fleet operators prioritize energy efficiency and telemetry integration, while recreational users trade power consumption for portability and freezing depth.
Product Type:
Technology choice dictates coefficient of performance, noise signature, and minimum achievable temperature—factors that separate commercial pharmaceutical transport from weekend camping use.
- Compressor Refrigerators:Sealed DC compressors achieve temperatures down to minus 18 degrees Celsius with superior energy efficiency. Demand concentrates among RV owners in the United States Sun Belt where multi-day autonomy and frozen food storage justify premium positioning.
- Thermoelectric Coolers:Peltier modules provide silent, vibration-free cooling through solid-state heat pumping. Private vehicle owners in short-duration recreational applications accept the 20-degree-Celsius below-ambient limitation in exchange for lighter weight and lower cost.
- Electric Coolers:Basic semiconductor units serve entry-level price points with minimal insulation and direct 12V connection.
- Absorption Refrigerators:Ammonia-based systems operate on propane or electric power, finding niche use in off-grid expedition builds where fuel diversity outweighs efficiency concerns.
Compressor refrigerators lead volumes today; solar-integrated compressor configurations are gaining share fastest.
End User:
Customer archetypes differ sharply in procurement scale, service contract appetite, and regulatory exposure.
- Fleet Operators:Cold-chain logistics providers retrofit commercial van fleets with DC-native refrigeration to capture pharmaceutical and perishable grocery contracts. EPA idle-reduction rules and CARB emissions penalties accelerate battery-native architecture adoption.
- RV Owners:United States Sun Belt states drive premium unit demand with factory-integrated installations and subscription telemetry attach rates.
- Off-Road Enthusiasts:Mountain West overland builders specify ruggedized compressor units with auxiliary battery compatibility for multi-day trail autonomy.
- Private Vehicle Owners:Casual campers and road-trippers populate the entry tier with thermoelectric purchases driven by price accessibility.
Fleet operators command the highest per-customer lifetime value; off-road enthusiasts show the steepest expansion trajectory.
Capacity:
Volume requirements map directly to trip duration, payload constraints, and cooling load calculations.
- 31-50 Liters:The recreational sweet spot balances food storage for 3-4 day trips against vehicle space constraints. United States vanlife conversions and Australian overland builds standardize this footprint.
- 51-70 Liters:Extended expedition use and small commercial routes require this intermediate capacity with dual-zone temperature control.
- 20-30 Liters:Compact sedans and single-occupant vehicles accommodate this minimal footprint for beverage cooling and short-trip provisioning.
- Above 70 Liters:Large RV installations and specialized pharmaceutical fleet vehicles occupy this segment with custom mounting and reinforced insulation.
31-50 liter units dominate shipment volumes; 51-70 liter configurations climb the fastest as vanlife platform convergence extends average trip duration.
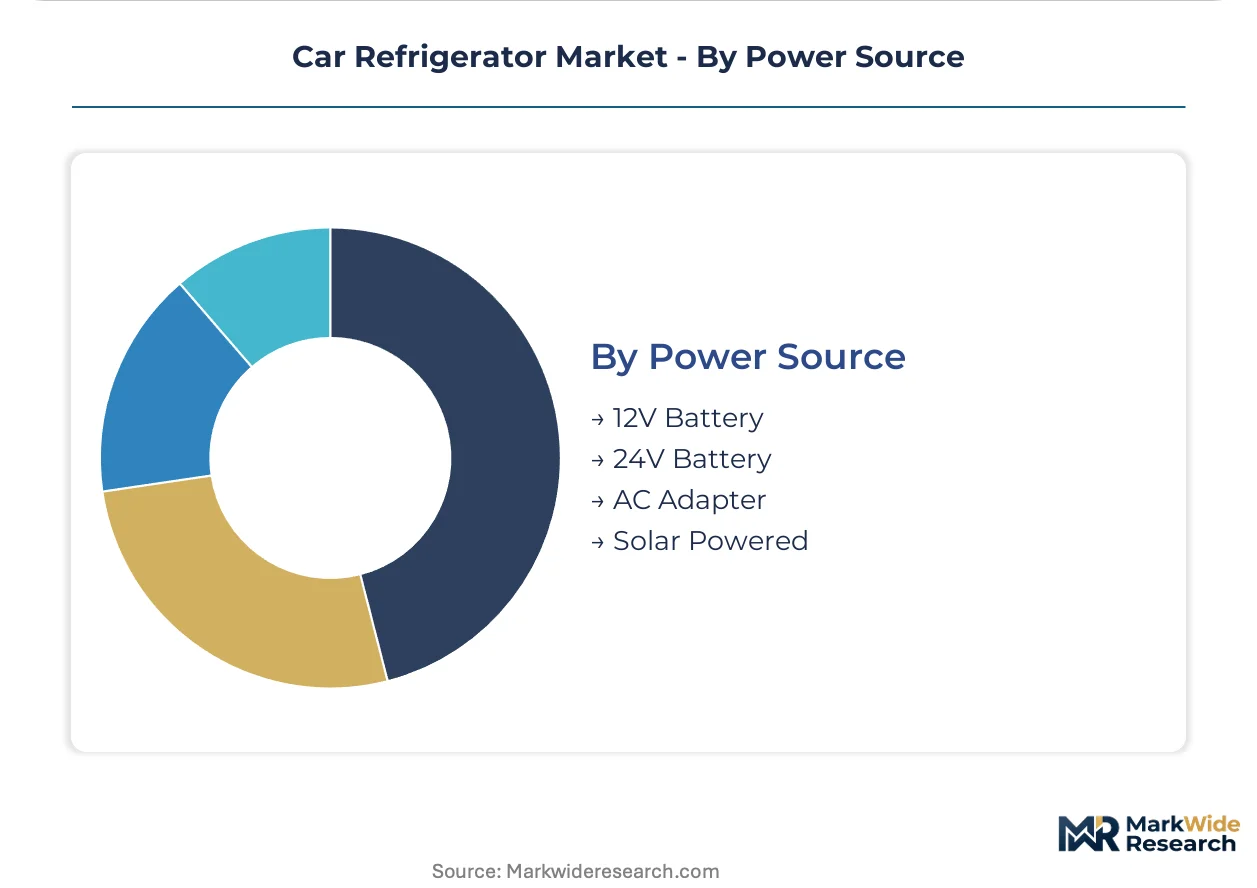
Power Source:
Electrical architecture decisions determine off-grid autonomy, installation complexity, and total cost of ownership.
- Solar Powered:MPPT charge controllers and lithium auxiliary banks enable indefinite off-grid operation. Expedition vehicle builders in remote camping applications drive adoption as panel efficiency gains reduce array size requirements.
- 12V Battery:Vehicle-native electrical integration eliminates inverter losses. Standard across passenger vehicles and light commercial vans with established wiring harness compatibility.
- 24V Battery:Heavy-duty commercial vehicles and European truck platforms specify this voltage for reduced current draw and thinner gauge wiring.
- AC Adapter:Grid-connected pre-cooling and stationary deployment capability add flexibility for RV park and residential garage use.
12V battery connection maintains installed base dominance; solar-powered configurations expand most quickly as battery cost curves improve bundle economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's commercial van conversion sector outpaces France in factory-fit refrigeration integration, while the United States dominates aftermarket volume through dispersed RV and overland ownership patterns.
United States
Sun Belt RV owners and Mountain West overland enthusiasts drive compressor unit demand with auxiliary battery compatibility. EPA fuel-efficiency standards and CARB emissions rules push manufacturers toward idle-reduction architectures. Vanlife conversion clusters in Colorado and Utah standardize solar-integrated refrigeration for multi-day autonomy.
Germany
Premium van conversion specialists and OEM factory-fit channels absorb high-efficiency compressor systems. KBA vehicle-type approval requirements shape mounting hardware and electrical integration standards. Stuttgart and Munich automotive engineering corridors concentrate thermal design expertise for low-amp-draw architectures.
Australia
Remote expedition vehicle builders prioritize solar-powered configurations with lithium auxiliary banks. TGA pharmaceutical transport guidelines influence fleet cold-chain specifications for vaccine distribution networks. Perth and Brisbane overland outfitters drive ruggedized compressor adoption for Outback deployment.
China
Domestic compressor manufacturing clusters supply sealed units to global assembly operations while domestic vanlife culture emerges in tier-one cities. MIIT new energy vehicle mandates accelerate battery-native cooling R&D for electric commercial fleets. Guangdong and Zhejiang provinces concentrate thermoelectric and compressor component fabrication.
India
Pharmaceutical cold-chain fleet retrofits expand under CDSCO temperature-compliance mandates for vaccine distribution. FSSAI food safety regulations extend traceability requirements to last-mile refrigerated transport. Maharashtra and Gujarat logistics hubs drive DC-native refrigeration procurement for perishable cargo networks.
Car Refrigerator Market Vendor Landscape
Top-tier vendors anchor premium factory-fit and smart-telemetry segments, while mid-tier fabricators compete on price-accessible compressor and thermoelectric units. The vendor base spans automotive HVAC heritage players, outdoor recreation specialists, and emerging solar-integrated challengers. Three archetypes dominate: integrated platform providers bundling hardware with subscription services, ruggedized expedition specialists serving overland niches, and volume manufacturers supplying private-label retail channels. Competitive moves concentrate on strategic partnerships with van conversion platforms and geographic expansion into pharmaceutical cold-chain markets.
Within the integrated platform tier, Dometic and Webasto exemplify convergence between hardware sales and recurring telemetry revenue. ARB occupies a distinct position among ruggedized expedition specialists serving Australian and North American overland segments with compressor-focused portfolios. These three anchors represent divergent bets on service attach rates, off-grid autonomy, and OEM channel penetration respectively.
| Leading Market Players |
|---|
| Whynter |
| Coleman |
| Dometic |
| Indel B |
| Webasto |
| Engel |
| Igloo |
| BougeRV |
| ARB |
| Others |
Supply Flow & Price Mechanics
Compressor-thermoelectric performance bifurcation separates premium factory-fit architectures from entry-level portable units, with that gap manifesting in both component sourcing geography and buyer willingness to pay for certification-grade thermal performance. Fleet procurement teams in pharmaceutical cold-chain applications absorb higher unit costs for CDSCO-compliant telemetry integration, while recreational buyers in the United States Sun Belt trade absolute cooling depth for price accessibility.
Pricing Analysis
Capacity additions in Guangdong and Zhejiang provinces are reshaping price floors for sealed compressor units as Chinese manufacturing clusters expand DC-native refrigeration output. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier differentiation, with UL-listed and CE-marked units commanding substantial premiums over uncertified alternatives. Cost compression in thermoelectric entry segments is intensifying because Peltier module oversupply from domestic Chinese fabricators erodes margin. Private vehicle owners in short-duration recreational applications exhibit highest price sensitivity; fleet operators in pharmaceutical logistics demonstrate lowest sensitivity due to temperature-compliance liability exposure.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific manufacturing zones to North American distribution hubs compresses landed cost predictability for sealed compressor assemblies. Component fabrication concentrates in China, South Korea, and Germany, with final assembly gravitating toward regional demand centers. Raw material dependencies span copper windings for compressor motors, lithium cells for auxiliary power banks, and polyurethane foam for vacuum-insulated panels. Single-source vulnerability in semiconductor-based compressor motor controllers from Taiwanese foundries poses structural risk. Distribution runs through van conversion specialists, outdoor recreation retailers, and direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car refrigerator market functions as a stable compounder anchored by fleet electrification timelines that mandate battery-native cooling architectures across commercial van platforms.
For Market Incumbents: Anticipate margin compression from emerging solar-integrated challengers by deepening backward integration into lithium auxiliary battery supply and securing exclusive telemetry service contracts with fleet operators. Prioritize FCC certification pre-investment for smart-control modules to compress approval timelines against competitors. Vertical integration into MPPT charge controller design protects against solar bundle margin erosion. For New Entrants and Emerging Players: Indian pharmaceutical fleet retrofit demand represents an underserved buyer archetype with CDSCO compliance requirements that incumbent platforms have addressed slowly. Target last-mile vaccine distribution networks in Maharashtra and Gujarat with DC-native refrigeration bundled with temperature-monitoring subscriptions. Pursue partnership-first go-to-market positioning with regional logistics integrators rather than direct fleet sales. For Investors and Strategic Acquirers: Consolidation pressure builds where telemetry platform capabilities concentrate among legacy automotive HVAC suppliers with limited software stack depth. Frame long-term viability around service attach rate expansion rather than hardware shipment growth alone. Acquisition target archetype: mid-tier compressor fabricators with dormant OEM channel relationships but strong thermal engineering benches. Monitor CARB zero-emission vehicle mandate expansion as inflection indicator for battery-native architecture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Telemetry Platform Launch | Transforms hardware transactions into recurring revenue relationships with fleet operators. |
| Solar-Integrated Product Line Expansion | Captures off-grid expedition vehicle builders as lithium battery cost curves improve bundle economics. |
| Indian Pharmaceutical Fleet Partnership | Positions for CDSCO-mandated cold-chain retrofit demand in vaccine distribution networks. |
| Compressor Motor Controller Backward Integration | Reduces single-source exposure to Taiwanese semiconductor foundries for variable-speed DC architectures. |
| Vanlife Platform Ecosystem Integration | Opens OEM factory-fit channels through telematics and smart-home convergence partnerships. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet procurement managers, van conversion specialists, thermal engineering directors at automotive HVAC suppliers, and outdoor recreation retail buyers with secondary validation. Data sources included EPA fuel-efficiency filings, CARB emissions compliance databases, NHTSA crashworthiness guidelines, customs records for compressor component trade flows, and SEC disclosures from refrigeration equipment manufacturers. Bottom-up shipment modeling triangulated against top-down fleet penetration estimates across commercial van populations.
Segment-weighting approaches distributed value and volume across product type, end-user archetype, capacity tier, and power source configuration throughout the forecast period. CAGRs derived from regression analysis against fleet electrification timelines, solar panel efficiency improvement curves, and battery cost reduction trajectories. Industry-specific forecast inputs incorporated EPA idle-reduction rulemaking progression and CDSCO pharmaceutical transport mandate implementation schedules.
Inputs from fleet operator interviews and regulatory filing databases were available through the study window; gaps in real-time lithium raw material pricing and tariff schedule certainty introduce uncertainty bands around solar-refrigerator bundle cost projections. Forecasts reflect modeling assumptions about MPPT controller adoption rates and auxiliary battery penetration in recreational vehicle installations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Tow Bar Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Automotive Ignition Coil Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Automotive Air Compressor Market
Automotive Parts
Automotive Parts Zinc Die Casting Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
Mexico Passenger Vehicles Lubricants Market
Automotive Parts
Brake Shoe Market
Automotive Parts
Accelerator Pedal Module Market
Automotive Parts
Japan Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
United States Automotive Glass Market