
 Automotive Pressure Switch Market | 2026-2036
Automotive Pressure Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Pressure Switch Market Analysis
Modular sensor packaging is recalibrating how Tier-1 suppliers specify pressure switches for integrated brake-by-wire and thermal modules. Bosch Mobility Solutions leverages its captive semiconductor foundry to anchor high-volume programs across German and Chinese OEMs. Continental AG competes through vertical integration into ceramic capacitive elements, while Sensata Technologies differentiates via aerospace-derived MEMS fabrication adapted for under-hood automotive duty cycles.
An automotive pressure switch is an electromechanical or solid-state device that opens or closes a circuit at a predetermined fluid pressure threshold, typically rated between 0.5 bar and 350 bar depending on system architecture. It monitors hydraulic, pneumatic, or refrigerant states to protect compressors, actuate warning systems, or enable closed-loop engine management. Electronic switches are displacing mechanical diaphragm designs as 48V mild-hybrid and full-electric platforms demand faster response times and digital bus compatibility. Within application categories, braking system pressure sensors command premium positioning due to functional safety requirements under ISO 26262, while climate control segments expand fastest as heat-pump-based thermal management proliferates across battery electric vehicles.
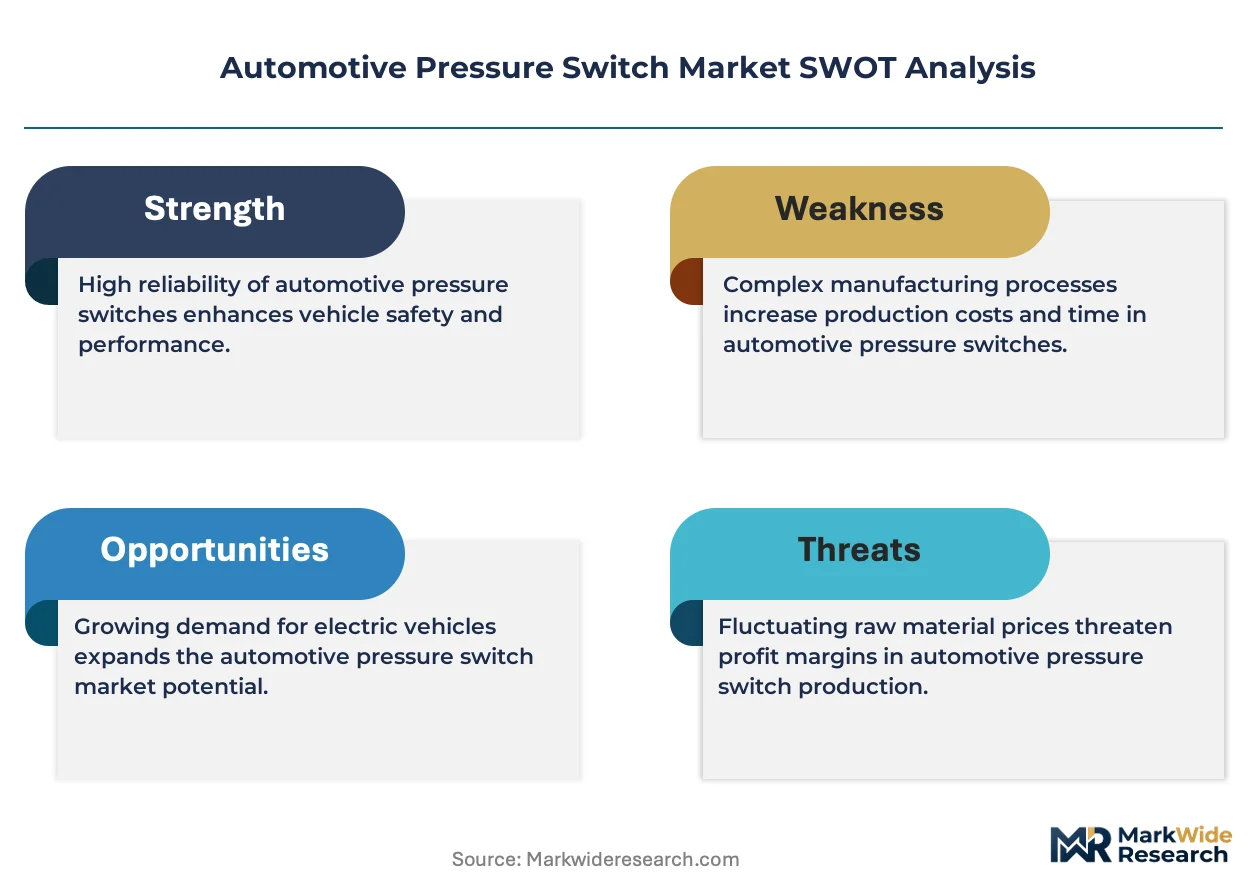
NHTSA FMVSS 135 brake system standards and EPA corporate average fuel economy rules jointly shape pressure switch calibration tolerances and material specifications in the United States. The EU AI Act and CE marking under the Machinery Directive add conformity layers for smart switches with embedded diagnostic algorithms. Stakeholders must monitor how functional safety certification costs and semiconductor content requirements reshape supplier qualification timelines across electrified vehicle programs.
Market Dynamics
Electrification of vehicle architectures is fragmenting legacy supply relationships as 48V mild-hybrid and battery-electric platforms demand pressure switches with digital bus compatibility and sub-millisecond response times incompatible with mechanical diaphragm designs.
Growth Catalysts
- Euro 7 emissions protocols:These standards compel automakers to redesign fluid control architectures with precision pressure sensing for real-time monitoring of hydraulic and pneumatic systems.
- Heat-pump thermal management:Battery electric vehicles across China, Germany, and the United States are expanding refrigerant circuit complexity and multiplying pressure switch installation points per vehicle.
- ISO 26262 functional safety mandates:Brake-by-wire systems require redundant pressure sensing with ASIL-D certification, elevating specification standards and supplier qualification barriers.
Market Restraints
- Semiconductor input volatility:MEMS fabrication depends on silicon wafer supply concentrated in East Asian foundries, exposing sensor manufacturers to capacity allocation disruptions.
- Mechanical switch substitution ceiling:Cost-optimized internal combustion engine vehicles in emerging markets retain bimetallic diaphragm designs that block electronic sensor penetration.
- REACH substance restrictions:Ceramic capacitive elements face scrutiny over piezoelectric material compositions, complicating material qualification for European OEM programs.
Strategic Opportunities
- India automotive production scaling:Domestic OEMs and PLI scheme beneficiaries are localizing pressure switch procurement for compressed natural gas and flex-fuel vehicle lines.
- Air suspension proliferation:Premium electric SUVs are integrating multi-chamber pneumatic systems that multiply pressure switch count per axle beyond conventional coil-spring architectures.
- CE marking diagnostic integration:Smart switches with embedded algorithms for predictive maintenance align with EU AI Act conformity pathways and Machinery Directive requirements.
Industry Challenges
- MEMS process engineer scarcity:Automotive duty cycle adaptation of aerospace fabrication techniques requires specialized cleanroom expertise concentrated in aerospace hubs.
- Dual certification timeline compression:Suppliers must simultaneously pursue AEC-Q100 automotive reliability and ISO 26262 functional safety approvals for brake system programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Pressure Switch Market |
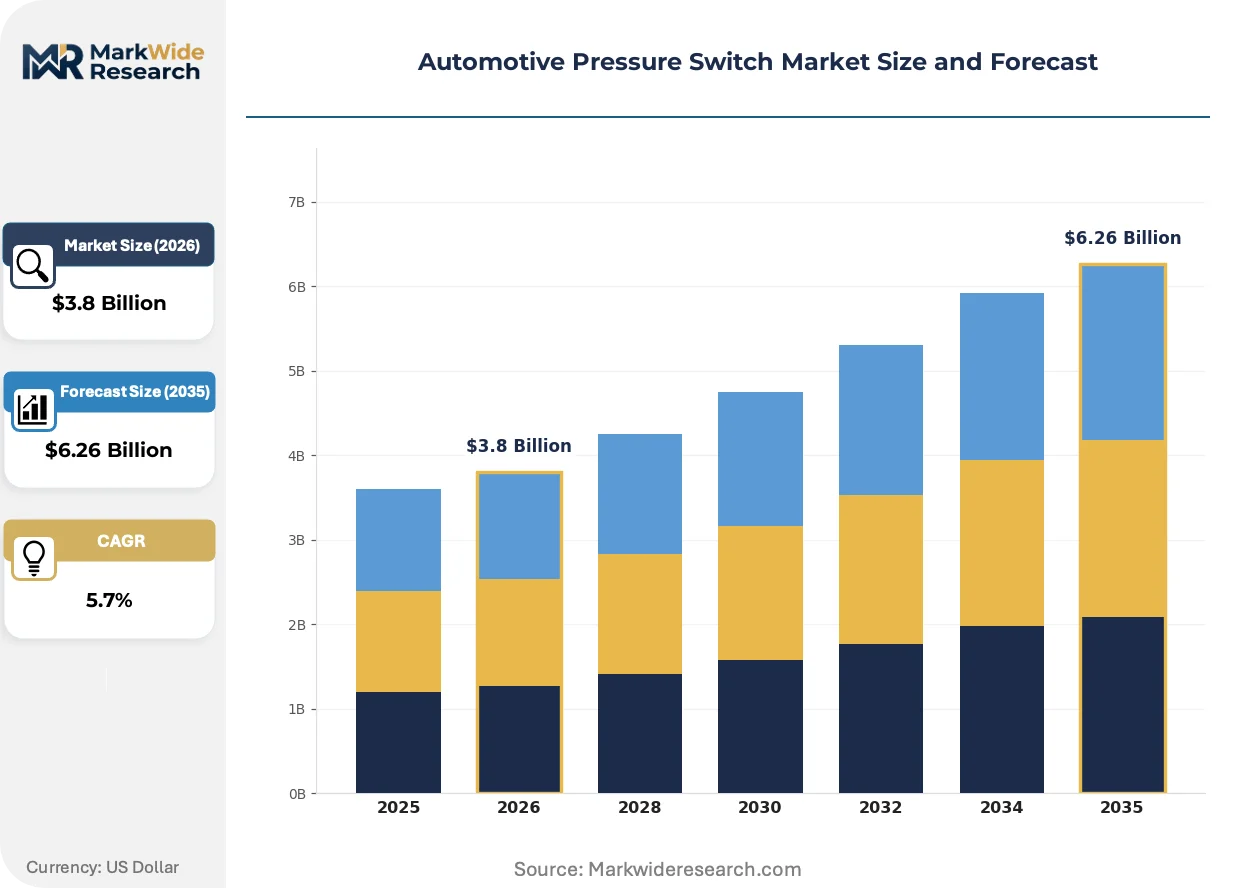
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Switches, Pneumatic Switches, Electronic Switches, Mechanical Switches Application: Braking System, Engine Management, Fuel System, Climate Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Onboard Systems, Externally Mounted, Integrated Solutions, Custom Installations |
| Companies Covered | Bosch Mobility Solutions, Denso Corporation, Continental AG, Delphi Technologies, Sensata Technologies, Schrader International, CTS Corporation, NXP Semiconductors, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Pressure Switch Market Emerging Trajectories
Solid-state sensing architectures are compressing the competitive window for mechanical switch incumbents as digital integration becomes non-negotiable for electrified platforms.
Silicon-carbide MEMS pressure transducers is rewriting thermal management system design by enabling continuous refrigerant state monitoring at temperatures exceeding 150°C. Battery electric vehicle manufacturers in Germany and China are specifying these devices for heat-pump compressors. The technology is compressing supplier margins on legacy ceramic capacitive alternatives while opening premium positioning for semiconductor-capable vendors.
EPA Tier 3 evaporative emission standards are tightening fuel vapor pressure monitoring requirements across light-duty vehicle fleets. This is forcing redesign of tank pressure sensor architectures with enhanced leak detection resolution. The climate control segment is responding with integrated pressure-temperature multi-sensor modules that reduce wiring harness complexity.
Fleet operators and automotive OEMs are consolidating sensor procurement under multi-year sole-source agreements with embedded volume commitments. Traditional spot-buying through Tier-2 distributors is contracting in brake and thermal system categories. This concentration is most visible in United States commercial vehicle programs where vertical integration between sensor suppliers and axle manufacturers has eliminated independent distributor tiers.
Automotive Pressure Switch Market Segmentation
Pressure switch specification varies sharply across vehicle architectures. Electrification is fragmenting legacy categories while functional safety mandates create new premium tiers in braking and thermal systems.
Product Type:
Technical specification axes—pressure range, response latency, and bus compatibility—now override traditional mechanical-electronic divides in supplier selection.
- Electronic Switches:Solid-state MEMS architectures deliver sub-millisecond response times and CAN/LIN bus integration mandatory for 48V mild-hybrid and battery-electric platforms. German and Chinese OEMs specify these for brake-by-wire and heat-pump thermal management where ISO 26262 ASIL-D certification applies. Silicon-carbide variants enable continuous operation above 150°C, displacing ceramic capacitive alternatives in premium BEV compressor circuits.
- Mechanical Switches:Bimetallic diaphragm designs persist in cost-optimized internal combustion engine vehicles across India and Southeast Asia, constrained by price ceilings that block electronic sensor penetration. These devices handle 0.5–50 bar ranges with millisecond-scale response times adequate for legacy hydraulic brake assist and engine oil pressure monitoring.
- Hydraulic Switches:Piston-actuated designs rated 50–350 bar serve heavy-duty commercial vehicle brake systems and power steering circuits.
- Pneumatic Switches:Diaphragm and bellows configurations monitor 0.5–10 bar ranges in air suspension and compressed natural gas fuel systems.
Electronic switches lead on scale; electronic switches lead on momentum.
Application:
Functional safety tiering concentrates margin in braking while thermal management multiplies unit count per vehicle.
- Braking System:Redundant pressure sensing with ASIL-D certification commands premium positioning under ISO 26262. NHTSA FMVSS 135 and EU brake system directives mandate real-time hydraulic pressure monitoring for electronic stability control and brake-by-wire architectures. Suppliers face compressed dual-certification timelines for AEC-Q100 reliability and functional safety approvals.
- Climate Control:Heat-pump-based thermal management in battery electric vehicles expands refrigerant circuit complexity, multiplying pressure switch installation points per vehicle. EPA Tier 3 evaporative emission standards tighten fuel vapor pressure monitoring requirements, forcing integrated pressure-temperature multi-sensor modules that reduce wiring harness complexity.
- Engine Management:Oil pressure and fuel rail monitoring in internal combustion platforms, declining in absolute share as electrification accelerates.
- Fuel System:Tank pressure sensing for leak detection and evaporative emission control, specification-intensifying under tightening EPA protocols.
Braking system applications command premium pricing; climate control applications expand most quickly.
End User:
Procurement consolidation is eliminating independent distributor tiers in favor of multi-year sole-source agreements with embedded volume commitments.
- OEMs:Volkswagen, BYD, and Ford specify pressure switches directly for captive thermal management and brake system programs, leveraging scale to extract semiconductor allocation priority from Bosch and Continental.
- Tier-1 Suppliers:Brake and axle manufacturers integrate pressure sensing into modular subassemblies, compressing qualification timelines through backward integration into MEMS fabrication.
- Aftermarket Providers:Independent distributors face contracting spot-buying volumes as fleet operators consolidate sensor procurement under OEM service contracts.
- Vehicle Assemblers:Contract manufacturers in India and Mexico localize pressure switch sourcing to meet domestic content requirements under PLI schemes and USMCA rules.
OEMs lead on scale; Tier-1 suppliers lead on momentum.
Installation:
Packaging density and thermal environment dictate mounting architecture selection across vehicle platforms.
- Integrated Solutions:Multi-sensor modules combining pressure, temperature, and diagnostic algorithms reduce connector count and assembly labor. CE marking under the EU Machinery Directive and AI Act conformity pathways favor smart switches with embedded predictive maintenance capabilities.
- Onboard Systems:Engine bay and under-hood mounting expose sensors to 125–150°C thermal cycling, driving silicon-carbide MEMS adoption over polymer-housed alternatives.
- Externally Mounted:Chassis and fuel tank applications prioritize ingress protection ratings and mechanical robustness over response latency.
- Custom Installations:Low-volume commercial vehicle and specialty equipment programs requiring non-standard pressure ranges or connector configurations.
Integrated solutions lead on scale; integrated solutions lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision automotive pressure sensing during the 1980s integration of electronic engine management systems, establishing fabrication protocols that Chinese and American suppliers now replicate at scale.
United States
NHTSA FMVSS 135 brake system standards and EPA Tier 3 evaporative emission rules compel Detroit automakers to specify redundant pressure sensing for electronic stability control architectures. Commercial vehicle axle manufacturers in Michigan and Ohio have consolidated procurement under multi-year sole-source agreements, eliminating independent distributor tiers from brake system supply chains.
Germany
Heat-pump thermal management proliferation across Volkswagen and BMW battery electric platforms multiplies refrigerant circuit pressure switch installation points per vehicle. KBA type-approval requirements under EU brake system directives mandate ASIL-D functional safety certification, compressing supplier qualification timelines for MEMS fabricators in Baden-Württemberg and Bavaria.
China
BYD and domestic OEMs scale production of battery electric vehicles with 48V mild-hybrid architectures demanding sub-millisecond pressure sensor response times. MIIT new energy vehicle mandates and GB standards for automotive electronics pressure domestic suppliers in Shanghai and Shenzhen to localize semiconductor-capable sensor fabrication.
India
PLI scheme beneficiaries and domestic OEMs localize pressure switch procurement for compressed natural gas and flex-fuel vehicle lines expanding across Maharashtra and Gujarat. BIS automotive component standards and tightening emission norms in Delhi-NCR force redesign of fluid control architectures with precision pressure monitoring.
Japan
Legacy automotive suppliers adapt aerospace-derived MEMS fabrication techniques for under-hood duty cycles in hybrid vehicle thermal management systems. METI carbon neutrality roadmaps and JIS standards for automotive electronics pressure Toyota and Honda suppliers in Aichi Prefecture to accelerate solid-state sensor qualification.
Automotive Pressure Switch Market Vendor Landscape
Premium-margin players sit above commodity-margin players across functional safety certification tiers, with ASIL-D qualified suppliers capturing brake-by-wire programs while mechanical switch fabricators compete on price in emerging market internal combustion platforms. The vendor base concentrates around three strategic archetypes: semiconductor-capable integrated suppliers with captive foundry access, ceramic capacitive specialists with backward integration into piezoelectric material supply, and aerospace-derived MEMS fabricators adapting cleanroom expertise for automotive duty cycles. Dominant competitive moves include capacity expansion in silicon-carbide MEMS fabrication for heat-pump thermal management and strategic partnerships between sensor suppliers and axle manufacturers to compress qualification timelines.
Among German-based integrated suppliers, Bosch Mobility Solutions and Continental AG occupy positions at the premium-tier vector, with the former anchoring high-volume programs through semiconductor foundry control and the latter exemplifying ceramic capacitive specialization. Sensata Technologies represents the aerospace-adaptation archetype, sitting within the MEMS fabrication tier where automotive duty cycle expertise concentrates. These three entities illustrate how geographic clustering around Stuttgart, Hanover, and Massachusetts shapes competitive positioning through proximity to OEM engineering centers and regulatory certification bodies.
| Leading Market Players |
|---|
| Bosch Mobility Solutions |
| Denso Corporation |
| Continental AG |
| Delphi Technologies |
| Sensata Technologies |
| Schrader International |
| CTS Corporation |
| NXP Semiconductors |
| TE Connectivity |
| Others |
Supply Flow & Price Mechanics
Euro 7 emissions protocols gate qualified supply and premium-tier pricing access by mandating ASIL-D functional safety certification for brake system pressure switches, compressing the supplier base to semiconductor-capable fabricators while mechanical switch producers compete on price in cost-optimized segments. This regulatory filter concentrates pricing power among certified vendors serving German and Chinese OEM electrification programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified MEMS sensors for brake-by-wire from ceramic capacitive units for thermal management and bimetallic diaphragm designs for legacy combustion platforms. Price differentiation hinges on ISO 26262 certification grade and silicon-carbide fabrication capability versus commodity mechanical specifications. Cost compression in the economy tier intensifies because Indian and Southeast Asian OEMs retain price ceilings that block electronic sensor penetration. Fleet operators and commercial vehicle buyers exhibit the highest price sensitivity, while German premium BEV manufacturers prioritize response latency over unit cost.
Supply Chain Analysis
MEMS process engineer scarcity in Baden-Württemberg and Bavaria constrains cleanroom capacity expansion for automotive duty cycle adaptation. Silicon wafer supply concentrates in Taiwan and South Korea, while ceramic piezoelectric material sourcing rests on German and Japanese specialty chemical producers. Single-source vulnerability in East Asian foundry allocation exposes sensor manufacturers to capacity disruption during semiconductor supply crunches. Distribution runs through multi-year sole-source agreements between Tier-1 brake manufacturers and OEM platform engineering teams, eliminating independent distributor tiers from high-volume programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Euro 7 and EPA Tier 3 standards continuously elevate certification barriers, transforming compliance investment into sustainable competitive moats for qualified suppliers.
For Market Incumbents: Anchor high-volume programs through captive semiconductor foundry access or strategic foundry partnerships that secure wafer allocation priority during supply crunches. Deepen backward integration into silicon-carbide MEMS fabrication for heat-pump compressor applications where temperatures exceed 150°C, preempting displacement by aerospace-adapted competitors. Defend against mechanical switch substitution in emerging markets by embedding predictive diagnostic algorithms that justify electronic premium through total cost of ownership reduction. For New Entrants and Emerging Players: The price-point gap between ASIL-D certified brake sensors and economy mechanical switches creates entry space for mid-tier MEMS fabricators targeting 48V mild-hybrid thermal management applications outside functional safety tiers. Target India's compressed natural gas vehicle expansion under PLI scheme localization mandates, where precision pressure monitoring requirements are tightening but certification barriers remain below European brake system standards. Pursue partnership routes with domestic OEM engineering centers in Shanghai and Shenzhen to accelerate GB standards compliance timelines. For Investors and Strategic Acquirers: Roll-up economics work for aerospace-derived MEMS specialists with cleanroom expertise because automotive duty cycle adaptation requires specialized process engineering that concentrates in Aichi Prefecture and Massachusetts aerospace clusters. Five-to-ten year viability favors acquisition targets possessing dual AEC-Q100 and ISO 26262 certification capabilities that compress qualification timelines for brake-by-wire programs. Monitor silicon-carbide MEMS yield rates as the inflection indicator for which fabrication technologies will displace legacy ceramic capacitive alternatives in premium BEV thermal management.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Functional safety approval unlocks brake-by-wire programs at Volkswagen and BMW. |
| Silicon-Carbide MEMS Capacity Expansion | 150°C continuous operation capability captures heat-pump compressor specifications from BYD. |
| India Localization Partnership | PLI scheme alignment secures CNG vehicle pressure switch procurement from domestic OEMs. |
| Multi-Sensor Module Integration | Combined pressure-temperature-diagnostic packaging reduces wiring harness complexity for EPA Tier 3 compliance. |
| Foundry Allocation Agreement | Semiconductor supply security anchors high-volume programs during East Asian capacity crunches. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution heads, and MEMS fabrication operations managers with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from listed sensor manufacturers, and KBA type-approval records. Bottom-up unit volume estimates by vehicle architecture and propulsion system were triangulated against top-down market value assessments.
Historical reference periods spanning electrification acceleration and semiconductor supply disruption anchored the projection horizon, with analytical frameworks modeling pressure switch demand across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from segmented growth rate analysis incorporating heat-pump thermal management proliferation rates, brake-by-wire adoption curves, and internal combustion platform decline trajectories. Forecast inputs included OEM electrification platform announcements, MIIT new energy vehicle production targets, and EPA regulatory phase-in schedules.
Caveats apply where semiconductor input volatility, REACH substance restriction expansions, or Euro 7 implementation delays could materially shift the outlook for supplier qualification timelines and technology substitution rates. Material deviation in foundry capacity allocation, ceramic piezoelectric material availability, or functional safety certification processing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Global Automotive VVT System Market
Automotive Circuit Systems
Middle East and Africa Automotive LED Lighting Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Automotive V2X Antenna Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Automotive Cell Contact System Carrier Market
Automotive Circuit Systems
Vehicle Roof Control Module Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Automotive Digital Isolators Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Global Automotive Control Panel Market