
 Global Automotive VVT System Market | 2026-2036
Global Automotive VVT System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive VVT System Market Intelligence
The shift towards asset-light manufacturing models, where Tier-1 suppliers handle more complex sub-assembly, is rewriting the competitive landscape for VVT systems. BorgWarner Inc. leverages its extensive R&D in electro-hydraulic technology to secure large OEM contracts. DENSO Corporation differentiates through its leadership in compact, high-precision electric VVT components for Japanese automakers. Meanwhile, Continental AG anchors its position with integrated powertrain solutions for the European market.
An automotive variable valve timing (VVT) system is a powertrain technology designed to alter the timing of an engine's valve lift events. It optimizes engine performance and fuel efficiency by using hydraulic actuators or electric motors to adjust the camshaft's phase angle relative to the crankshaft. While hydraulic VVT systems remain prevalent, the adoption of more precise electric VVT technology is accelerating in premium vehicles. Passenger vehicles constitute the largest application segment by volume, driven by mass-market integration.
Emissions mandates from the US EPA and upcoming Euro 7 standards in Europe directly influence VVT system design and adoption rates. Similarly, China's GB standards for fuel consumption and pollutants create a mandatory requirement for advanced engine management technologies. Stakeholders must now navigate the long-term investment horizon for VVT as the industry balances optimizing internal combustion engines against the transition to full electrification.
Market Dynamics
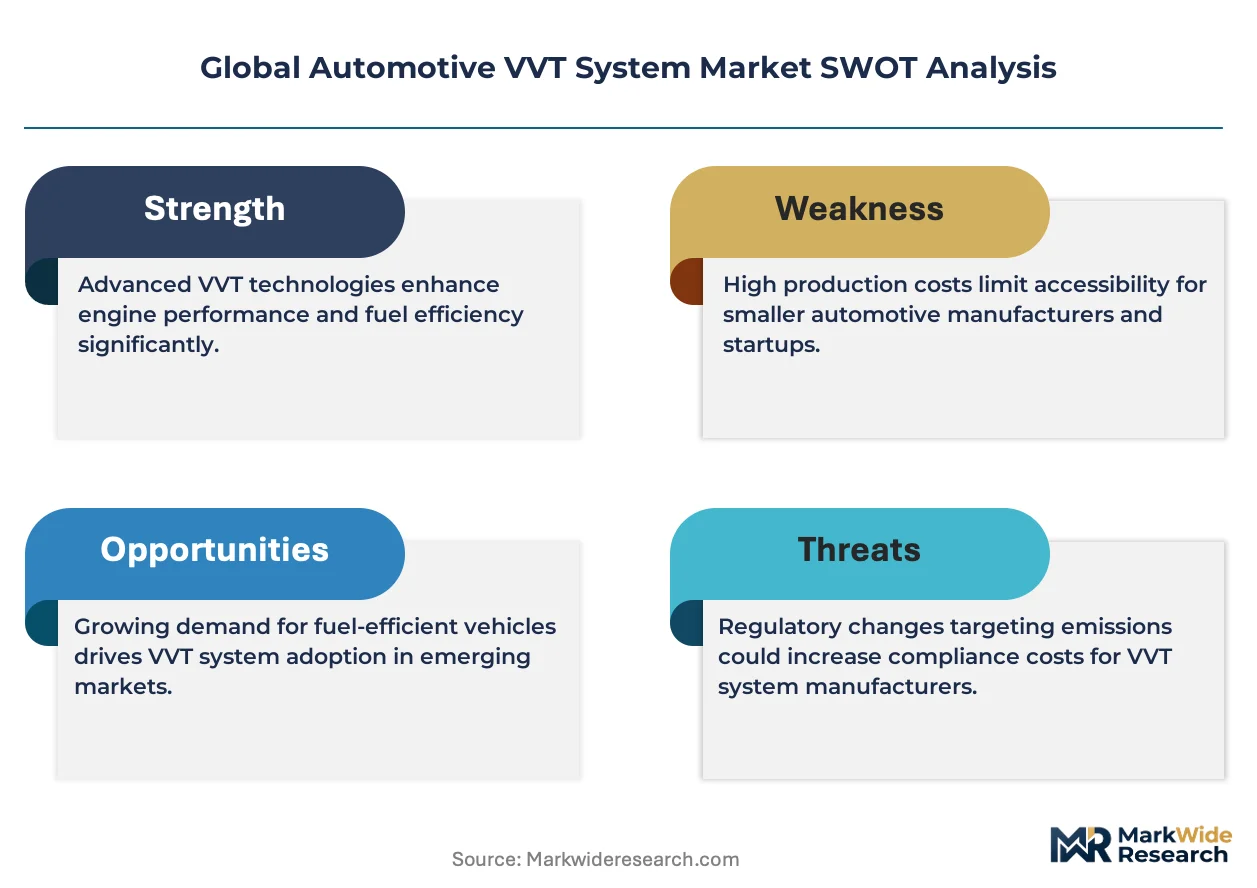
The market's central dynamic is the tension between near-term regulatory mandates for cleaner internal combustion engines (ICE) and the long-term strategic pivot to full electrification. This forces investment in advanced VVT systems while simultaneously capping their ultimate lifespan.
Growth Catalysts
- Stringent Emissions Standards:Regulations including Europe's forthcoming Euro 7 and existing US EPA rules compel automakers to adopt technologies like VVT to reduce CO2 and NOx emissions from internal combustion engines.
- Fuel Economy Demand:Within the high-volume passenger vehicle segment, consumer and regulatory pressure for improved fuel efficiency makes VVT systems a standard feature for optimizing engine performance.
- Chinese Regulatory Push:China’s GB standards for fuel consumption create a non-negotiable requirement for advanced engine management technologies, directly spurring VVT adoption in the world's largest automotive market.
Market Restraints
- BEV Substitution Threat:The industry-wide transition to battery electric vehicles (BEVs), which do not have internal combustion engines or valves, presents a terminal threat to the entire VVT system market.
- Higher System Cost:The increased complexity and cost of advanced electric VVT systems compared to mature hydraulic versions can slow their adoption in economy and mid-range vehicle segments.
- Powertrain Development Cycles:Long automotive design and validation cycles mean that even proven VVT technology takes years to integrate into new engine platforms, slowing market penetration.
Strategic Opportunities
- Hybrid Powertrain Optimization:VVT systems can significantly improve the efficiency of the ICE component in hybrid electric vehicles (HEVs), creating a durable market segment during the electrification transition. *
- Emerging Market Adoption:Tightening emissions regulations in large, underpenetrated automotive markets like India and Brazil create new growth frontiers for established VVT technologies.
- Integration with Cylinder Deactivation:Combining VVT with technologies like cylinder deactivation offers synergistic efficiency gains, creating opportunities for suppliers who can deliver integrated valvetrain solutions.
Industry Challenges
- Capital Allocation Dilemma:Suppliers face the challenge of justifying significant capital expenditure on new VVT production lines when the long-term future of the internal combustion engine is uncertain.
- Software Integration Complexity:Integrating the control logic for advanced electric VVT systems with existing engine control unit (ECU) software architectures is a significant engineering hurdle for automakers.
- Skilled Engineering Scarcity:A shortage of powertrain engineers with dual expertise in precision mechanical systems and advanced electro-hydraulic controls constrains product development capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive VVT System Market |
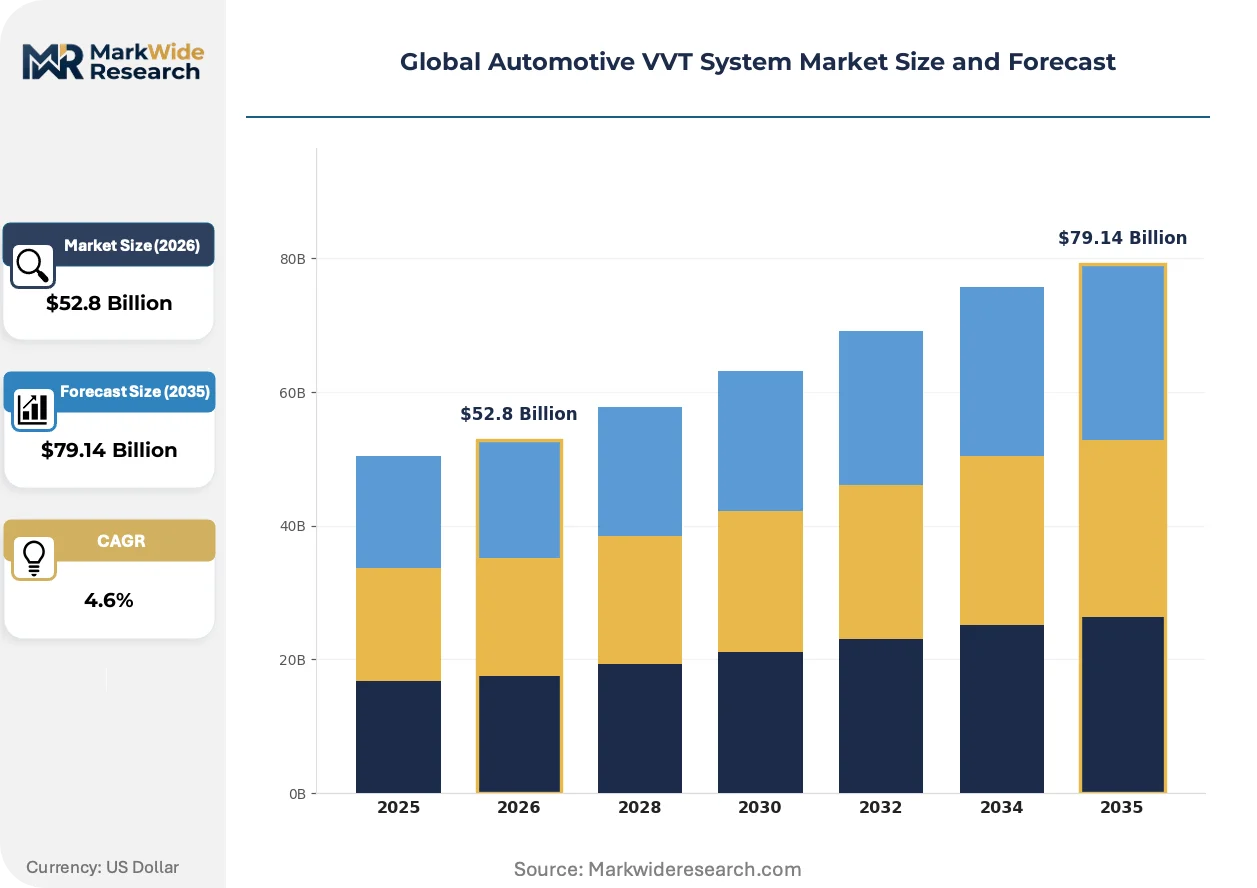
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $79.14 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic VVT, Electric VVT, Cam Phaser, Variable Valve Lift, Mechanical VVT Technology: Electro-Hydraulic, Fully Electronic, Electro-Mechanical, Mechanical Timing Drive, Variable Duration Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Equipment, Off-Road Machinery, Two-Wheelers End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Vehicle Assembly Plants |
| Companies Covered | Robert Bosch GmbH, BorgWarner Inc., DENSO Corporation, Aisin Seiki Co., Ltd., Continental AG, Mitsubishi Electric Corporation, Schaeffler AG, Eaton Corporation, Valeo S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive VVT System Market Strategic Shifts & Innovations
The evolution of the automotive powertrain, driven by both efficiency targets and the shift toward electrification, is reshaping VVT system design. Technology is now focused on achieving greater precision and faster response times to extract maximum efficiency from internal combustion engines.
Electric variable valve timing (e-VVT) technology utilizes a compact electric motor attached to the camshaft phaser. Premium vehicle segments, particularly from German and Japanese automakers, are adopting this technology for its superior speed and precision over hydraulic systems. This innovation is digitizing valvetrain control, allowing for instantaneous and independent adjustment of intake and exhaust timing that is impossible with conventional hardware.
Europe's EU Green Deal and its associated emissions targets are forcing automakers to extract every possible efficiency gain from ICE platforms. This regulatory pressure directly impacts powertrain design, making advanced VVT systems a critical compliance tool rather than a performance option. The compact and mid-size passenger car segments, which form the bulk of the European market, are seeing accelerated integration of these technologies.
OEM purchasing behavior is moving towards the procurement of complete, pre-validated engine sub-systems from Tier-1 suppliers. This shift displaces the traditional model of buying individual components, placing greater R&D and integration burdens on suppliers. This trend is most prominent in North America, where major automakers are streamlining their in-house powertrain engineering teams and relying on partners for complex modules like the valvetrain.
Global Automotive VVT System Market Segmentation
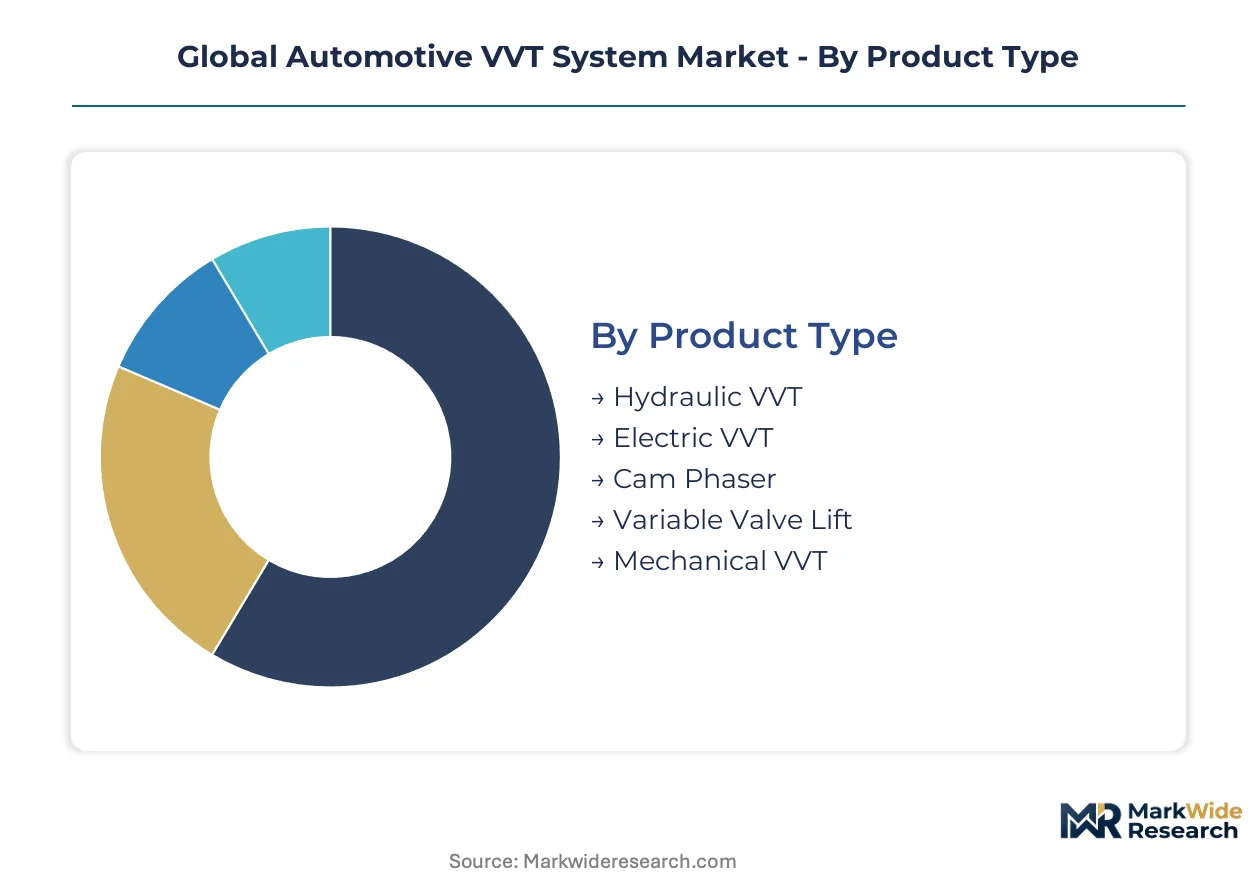
The global automotive VVT system market segments reflect the diverse technological approaches and application demands within the powertrain industry. Understanding these distinctions is crucial for identifying areas of innovation, market concentration, and strategic investment. Each segment responds differently to regulatory pressures and the evolving landscape of vehicle electrification.
Product Type:
The market for VVT product types features varying development cycles, with some segments experiencing rapid technological turnover and others maintaining longer lifespans. Suppliers must balance investment in mature technologies against emerging innovations.
- Hydraulic VVT:These systems utilize engine oil pressure to adjust camshaft phase angles, offering a cost-effective and proven solution for mass-market internal combustion engines. Demand for hydraulic VVT systems remains high in regions like China and India, where cost efficiency is a primary driver for vehicle manufacturers.
- Electric VVT:Electric VVT systems employ electric motors for precise and rapid camshaft adjustment, enabling finer control over valve timing and lift compared to hydraulic counterparts. This technology sees strong adoption in premium vehicles from German and Japanese automakers, driven by stringent emissions targets and performance demands.
- Cam Phaser:Cam phasers are mechanical devices that adjust the rotational position of the camshaft relative to the crankshaft, forming the core mechanism of many VVT systems. These components are standard across a wide range of gasoline and diesel engines globally.
- Variable Valve Lift:This technology alters the distance a valve opens, optimizing air intake and exhaust flow for different engine speeds and loads. Variable valve lift systems are integrated into advanced valvetrain designs for enhanced fuel economy.
- Mechanical VVT:Simpler mechanical VVT systems use fixed cam profiles or basic cam-shifting mechanisms to achieve limited valve timing adjustments. These systems are typically found in older engine designs or entry-level vehicles.
Hydraulic VVT anchors the volume base while Electric VVT gains share at the steepest rate.
Technology:
Different VVT technologies offer varying levels of precision and integration, influencing their cost and suitability for specific vehicle segments. The choice of technology often reflects a balance between performance, efficiency, and manufacturing complexity.
- Electro-Hydraulic:These systems combine electric control with hydraulic actuation, offering a balance of precision and cost-effectiveness for mainstream applications. Electro-hydraulic VVT remains a prevalent technology in North American and European mass-market vehicles due to its proven reliability.
- Fully Electronic:Fully electronic VVT systems eliminate hydraulic components, relying entirely on electric actuators for instantaneous and independent valve control. This advanced technology commands a premium, finding application in high-performance and luxury vehicles requiring ultimate precision.
- Electro-Mechanical:Electro-mechanical VVT combines electric motors with mechanical linkages to achieve valve timing adjustments. This technology offers a robust solution for certain engine architectures, balancing complexity and performance.
- Mechanical Timing Drive:Mechanical timing drives include traditional cam chains or belts that synchronize crankshaft and camshaft rotation without variable timing capabilities. These are foundational components in all internal combustion engines.
- Variable Duration:Variable duration technology modifies the length of time valves remain open, optimizing engine breathing across the RPM range. This advanced VVT feature contributes to significant efficiency gains.
Fully Electronic technology is seeing the most rapid development, while Electro-Hydraulic systems maintain widespread integration across global vehicle platforms.
Application:
The application segments for VVT systems highlight where the technology is most critical for meeting performance and regulatory objectives. Each vehicle type presents unique demands for durability, cost, and efficiency gains.
- Passenger Vehicles:This segment includes sedans, SUVs, and hatchbacks, where VVT systems are standard to meet fuel economy and emissions regulations from the US EPA and EU Green Deal. Passenger vehicles represent the largest volume application for VVT systems globally, particularly in China and Europe.
- Commercial Vehicles:Commercial vehicles, such as light and medium-duty trucks, utilize VVT to enhance engine efficiency and reduce emissions under varying load conditions. Manufacturers focus on robust VVT solutions that can withstand demanding operational cycles.
- Heavy-Duty Equipment:VVT systems in heavy-duty equipment like construction machinery and agricultural vehicles improve torque delivery and fuel efficiency in off-highway applications. Durability and reliability are paramount for these industrial engines.
- Off-Road Machinery:This segment encompasses a range of specialized vehicles operating in challenging environments, where VVT contributes to optimized power output and reduced fuel consumption. Engine performance under extreme conditions is a key consideration.
- Two-Wheelers:A smaller but growing segment, two-wheelers in regions like India and Southeast Asia are beginning to adopt VVT for improved fuel efficiency and compliance with local emissions standards. Compact and lightweight VVT solutions are critical for these applications.
Passenger Vehicles drive the majority of VVT system volume, while Commercial Vehicles are increasingly integrating advanced VVT for efficiency gains.
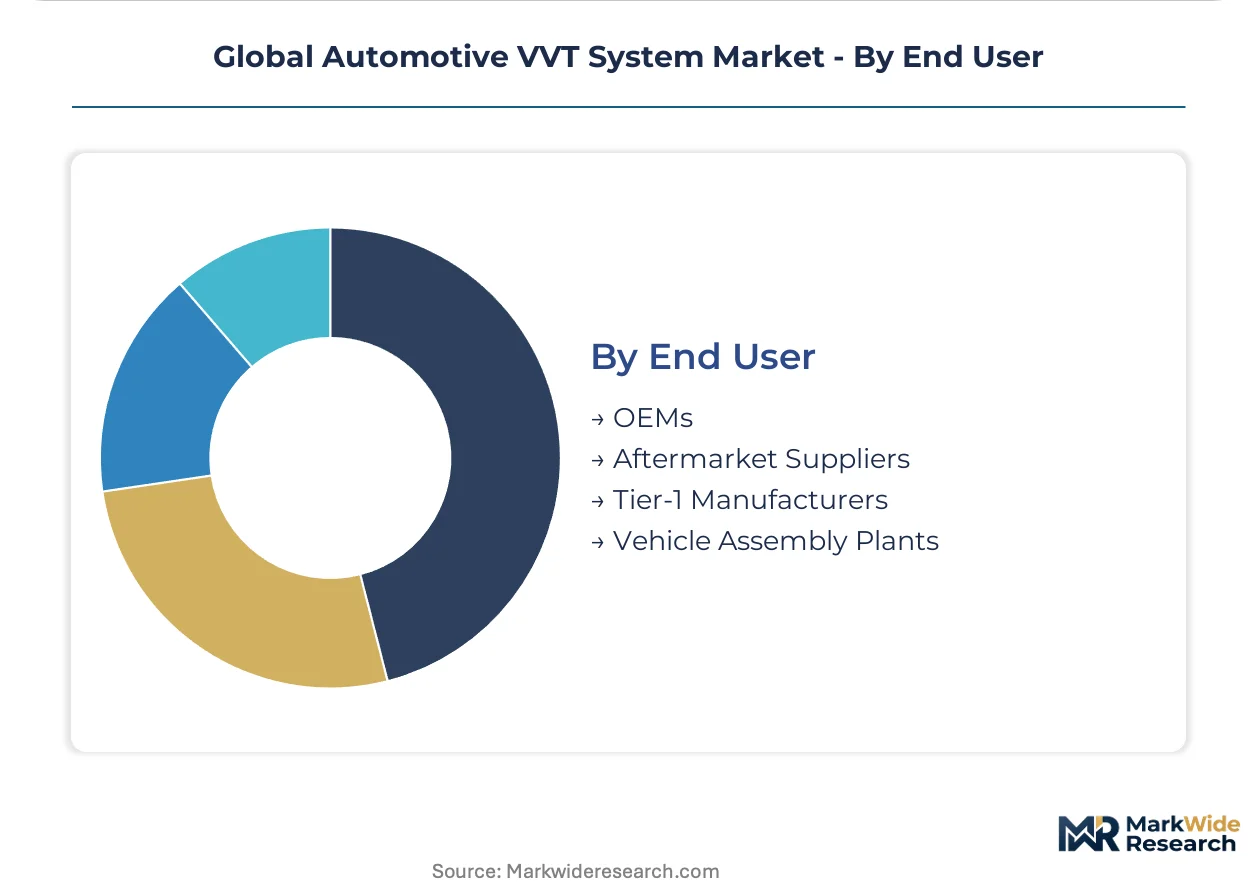
End User:
The VVT system market serves different types of end users, each with distinct procurement processes and technical requirements. Understanding these channels helps suppliers tailor their offerings and support structures.
- OEMs:Original Equipment Manufacturers integrate VVT systems directly into their new vehicle production lines, requiring extensive validation and long-term supply agreements. OEMs dictate the specifications and performance requirements for VVT technology.
- Aftermarket Suppliers:Aftermarket suppliers provide VVT components for vehicle repair and maintenance, focusing on compatibility with existing engine designs and competitive pricing. This segment supports the longevity of the installed vehicle base.
- Tier-1 Manufacturers:Tier-1 manufacturers design, develop, and supply complete VVT modules or sub-systems directly to OEMs, often undertaking significant R&D. Companies like BorgWarner Inc. and DENSO Corporation are prominent Tier-1 suppliers.
- Vehicle Assembly Plants:Vehicle assembly plants are the facilities where VVT systems are installed into new engines and vehicles during the manufacturing process. These plants require timely delivery and quality assurance from suppliers.
OEMs represent the largest purchasing power for VVT systems, with Tier-1 Manufacturers serving as critical development and integration partners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stringent emissions regulations across major automotive markets compel automakers to integrate advanced VVT systems. The EU Green Deal and China's GB standards specifically drive efficiency gains in internal combustion engines. This regulatory push sustains VVT technology investment even amidst electrification trends.
China
China's vast automotive market and its stringent fuel consumption standards drive significant VVT system adoption. The country's GB standards for fuel consumption and pollutants create a mandatory requirement for advanced engine management. The Yangtze River Delta region, with its numerous automotive manufacturing plants, sees widespread VVT system integration for compliance.
Germany
Germany's premium vehicle production and the upcoming Euro 7 standards in Europe necessitate advanced VVT solutions. Automakers here prioritize technologies that deliver superior performance and emissions control. Bavaria, home to major luxury automakers, focuses on electric VVT for both performance and environmental compliance.
United States
The United States' large passenger vehicle market and US EPA regulations drive demand for VVT systems. These rules compel automakers to enhance fuel economy and reduce emissions across their vehicle fleets. Michigan's automotive hub, particularly around Detroit, integrates advanced electro-hydraulic VVT into high-volume truck and SUV platforms.
Japan
Japan's focus on compact, high-precision VVT components reflects its leadership in automotive engineering. METI initiatives support advanced powertrain development, influencing VVT system design. The Aichi Prefecture, a core automotive manufacturing region, is a center for the development and adoption of compact electric VVT components.
India
India's growing passenger vehicle segment and tightening local emissions standards are spurring VVT adoption. The country's Bharat Stage (BS) emission norms compel manufacturers to integrate efficiency-enhancing technologies. The Chennai automotive corridor sees increasing VVT adoption in mass-market vehicles for fuel efficiency and regulatory compliance.
Global Automotive VVT System Market Key Industry Players
Channel-controlling players compete with product-specialist players across the VVT system market. The competitive landscape exhibits a tiered structure, with large Tier-1 suppliers dominating the integrated module segment. These established players act as strategic partners to OEMs, offering complete valvetrain solutions. Two archetypes emerge: integrated powertrain solution providers and precision component specialists. Dominant competitive moves include strategic partnerships for module integration and continuous R&D investment in advanced electric VVT technology.
Within the integrated powertrain solution providers archetype, BorgWarner Inc. and Continental AG exemplify global reach and broad product portfolios. DENSO Corporation, a Japanese entity, represents the precision component specialists, focusing on compact and high-precision electric VVT components. These companies anchor the market through their extensive R&D capabilities and established OEM relationships, particularly in their respective geographic strongholds. Their offerings span from cost-effective hydraulic systems to cutting-edge electric VVT technologies, addressing diverse OEM requirements for fuel efficiency and emissions compliance.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| BorgWarner Inc. |
| DENSO Corporation |
| Aisin Seiki Co., Ltd. |
| Continental AG |
| Mitsubishi Electric Corporation |
| Schaeffler AG |
| Eaton Corporation |
| Valeo S.A. |
| Others |
Cost & Logistics Intelligence
Commodity volatility for critical raw materials, such as rare earth elements and specialized alloys, determines both pricing tier spreads and the supply chain shape for VVT systems. This volatility directly impacts the cost structures of Tier-1 suppliers and, subsequently, OEM procurement budgets.
Pricing Analysis
Product performance tier creates the primary spread in VVT system pricing. The market operates on a hybrid pricing model, combining long-term contract-based agreements for high-volume OEM supply with transactional pricing for aftermarket components. Price differentiation stems from technology complexity, such as electric VVT systems commanding a premium over hydraulic VVT due to enhanced precision. Pricing softness runs through the mechanical VVT segment due to its mature technology and widespread availability. Passenger vehicle OEMs are highly price-sensitive in economy and mid-range segments, while premium vehicle manufacturers prioritize performance and integration.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common practices to manage capital flow for VVT system suppliers. The supply chain for VVT systems draws from specialized component manufacturers concentrated in Germany, Japan, and China. Raw material dependencies include rare earth metals for electric motors, specialized steel alloys for cam phasers, and advanced plastics for housing units. A structural risk involves single-source vulnerability for specific precision components, particularly in electric VVT technology. Distribution runs through a direct model to Original Equipment Manufacturers, with Tier-1 suppliers handling integration into engine sub-assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a buyer-power-shift story, driven by OEM consolidation of powertrain engineering and increased reliance on Tier-1 suppliers for complete module integration.
For Market Incumbents: Pre-empt the terminal threat from battery electric vehicles by accelerating VVT system development for hybrid electric vehicle applications. Strengthen strategic partnerships with major OEMs for integrated valvetrain solutions, leveraging deep R&D in electro-hydraulic and electric VVT technologies. Invest in advanced manufacturing capabilities within key automotive hubs like Germany and Japan to maintain a competitive edge. Defend market share against emerging players by offering cost-effective hydraulic VVT options for price-sensitive markets.
For New Entrants and Emerging Players: Pursue niche opportunities in compact electric VVT components for two-wheelers and smaller passenger vehicles in India and Southeast Asia. Target the aftermarket segment by offering compatible VVT components that meet existing engine specifications and provide competitive pricing. Focus on developing specialized software integration expertise for advanced VVT control units, addressing a significant engineering hurdle for automakers. A go-to-market angle could involve offering modular, easily integrable VVT sub-systems to smaller engine manufacturers.
For Investors and Strategic Acquirers: The market sits at a transitional phase that favors integrated powertrain solution providers with strong OEM relationships. Long-term viability (5-10 year window) depends on successful pivots to hybrid powertrain optimization and advanced valvetrain integration. Identify acquisition targets with proprietary electric VVT technology or robust software control capabilities. The signal to watch is the rate of internal combustion engine investment by major OEMs, particularly for new hybrid platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerate HEV VVT System R&D | This extends the market relevance of VVT technology during the industry's electrification transition. |
| Deepen OEM Integration Partnerships | Securing long-term supply agreements reinforces Tier-1 suppliers' market position with vehicle manufacturers. |
| Invest in Electric VVT Manufacturing | Scaling production for advanced electric VVT components meets demand from premium vehicle segments. |
| Develop Integrated Valvetrain Solutions | Offering combined VVT and cylinder deactivation modules creates synergistic efficiency gains for automakers. |
| Expand Aftermarket Component Portfolio | Serving the repair and maintenance segment ensures continued revenue streams from the installed vehicle base. |
Research Approach
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, and government emissions reports. This approach involved extensive interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and ECU software developers. The methodology employed both bottom-up and top-down triangulation to ensure data accuracy across all market segments.
Forecast inputs being considered include the evolving regulatory landscape, such as Euro 7 and China's GB standards, and the pace of hybrid vehicle adoption. The analytical framework modeled segmentation dimensions by product type, technology, application, end user, and regional production hubs. Compound annual growth rates were derived from historical data trends and projected future demand scenarios. Industry-specific forecast inputs included BEV adoption rates and ICE powertrain investment cycles.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or geopolitical tensions would shift the trajectory. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement across the analysis window. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Automotive Launch Control System Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Automotive Digital Isolators Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Automotive Integrated Control Panel Market
Automotive Circuit Systems
Automotive V2X Antenna Market
Automotive Circuit Systems
Vehicle Roof Control Module Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Steering Column Control Modules Market