
 Global Mid-And-High-Level Precision GPS Receiver Market | 2026-2036
Global Mid-And-High-Level Precision GPS Receiver Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mid-And-High-Level Precision GPS Receiver Market Outlook
Agriculture is restructuring demand patterns across the precision GPS receiver landscape. Autonomous tractor fleets and variable-rate input systems now consume multi-frequency RTK units at volumes that rival traditional surveying. Trimble Inc. leverages its integrated farm management software stack to lock in recurring hardware replacement cycles. Topcon sustains dominance in optical-mechanical hybrid surveying instruments across Japanese infrastructure projects. Hexagon AB anchors its position through captive correction services that reduce customer churn in geospatial accounts.
Mid-and-high-level precision GPS receivers are electronic devices that decode satellite signals from multiple constellations to achieve centimeter-level positional accuracy through carrier-phase differential techniques, typically employing multi-frequency L1/L2/L5 tracking with real-time kinematic correction loops. These instruments serve commercial and military operators requiring geodetic-grade coordinates for machine control, aerial navigation, and cadastral boundary determination. The technology dimension shows RTK architectures commanding the largest installed base while PPP-RTK hybrids capture the fastest expansion as cellular networks densify. Application segmentation reveals agriculture overtaking surveying in annual unit volume though marine and aerospace retain superior per-unit pricing. Device type dynamics favor embedded modules over handheld units as OEMs integrate positioning directly into vehicle control systems.
The US FCC governs spectrum allocation for GPS augmentation services while the FAA certifies receiver performance for aviation approaches under WAAS criteria. Europe's EASA and EUSPA enforce EGNOS integrity standards that filter lower-accuracy devices from safety-critical applications. Japan's MIC and METI coordinate QZSS augmentation mandates that shape regional product specifications. Stakeholders must monitor constellation modernization timelines and augmentation service interoperability as procurement criteria harden around multi-constellation resilience.
Market Dynamics
RTK-to-PPP-RTK migration is compressing hardware refresh cycles as agricultural OEMs demand embedded multi-constellation modules capable of sub-inch accuracy without dedicated base stations.
Growth Catalysts
- EGNOS augmentation mandates:Europe's EUSPA integrity standards are filtering lower-accuracy receivers from safety-critical aviation and rail applications, forcing fleet-wide hardware upgrades.
- Variable-rate input systems:Precision farming corridors across the US Corn Belt and North China Plain now specify multi-frequency RTK units for autonomous spraying and seeding operations.
- QZSS regional specifications:Japan's MIC coordination of centimeter-level augmentation services is accelerating receiver replacement in construction machine control and cadastral surveying.
Market Restraints
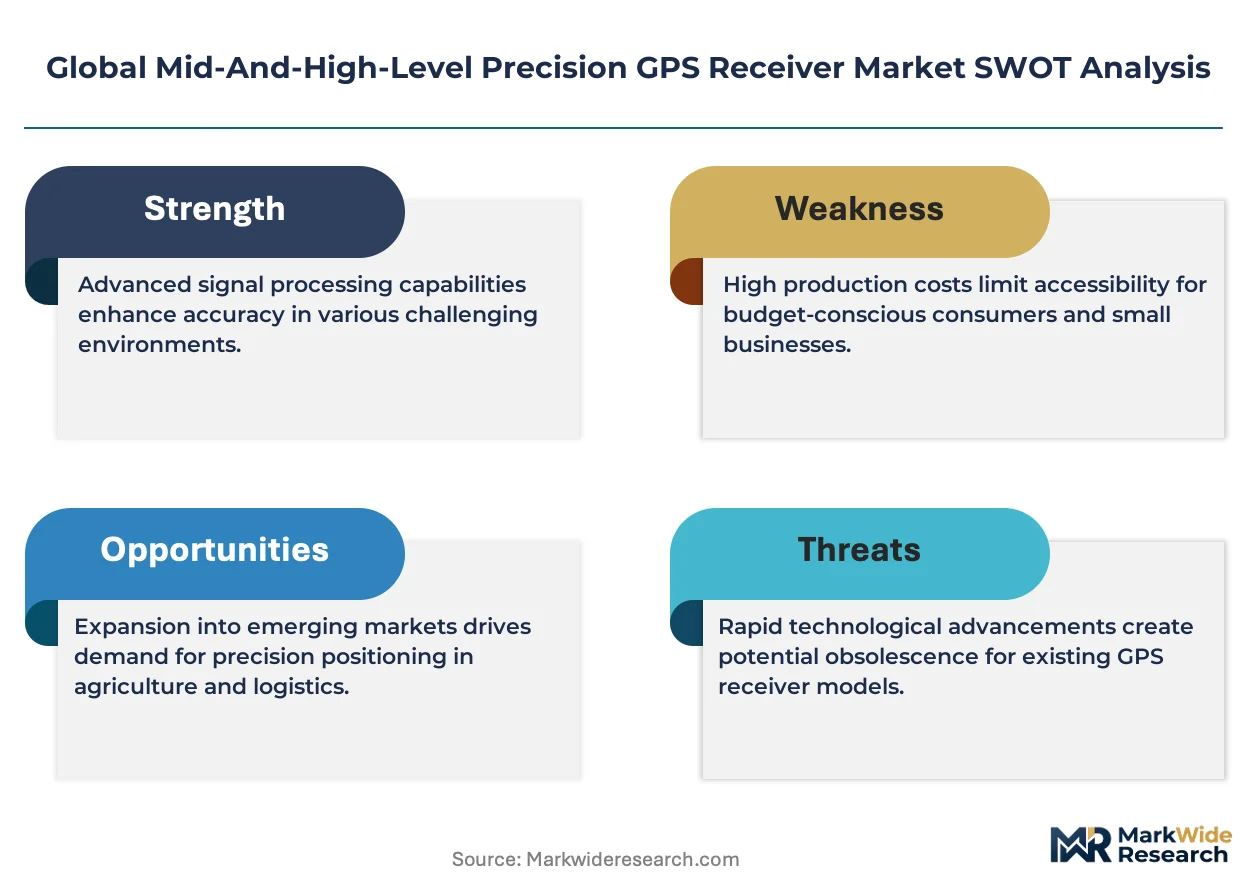
- Multi-frequency chipset concentration:Supply of L1/L2/L5-capable GNSS front-end silicon concentrates among three foundry sources, exposing procurement to geographic disruption.
- Ionospheric correction latency:Real-time kinematic loops degrade accuracy during equatorial scintillation events, limiting reliable deployment in Brazilian soybean regions without redundant augmentation.
- Spectrum reallocation friction:US FCC Ligado proceedings created interference concerns in L-band correction channels, delaying fleet certification timelines for precision agriculture operators.
Strategic Opportunities
- Autonomous marine docking:Harbor authorities in Rotterdam and Singapore are specifying PPP-RTK receivers for container vessel auto-berthing, opening vessel-integrated module demand.
- Indian geodetic infrastructure:GAGAN augmentation network densification creates white space for CORS-networked receivers in rail track surveying and smart city cadastre.
- 5G positioning convergence:Cellular network timing synchronization requirements are merging with GNSS correction distribution, enabling hybrid receiver architectures that reduce dedicated radio hardware.
Industry Challenges
- Carrier-phase ambiguity resolution expertise:Field engineering talent capable of diagnosing RTK baseline initialization failures remains scarce in distributed agricultural service networks.
- Multi-constellation certification backlog:FAA WAAS and EASA EGNOS receiver approvals face 18-month queues as manufacturers submit Galileo-BeiDou-capable variants for aviation approach eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mid-And-High-Level Precision GPS Receiver Market |
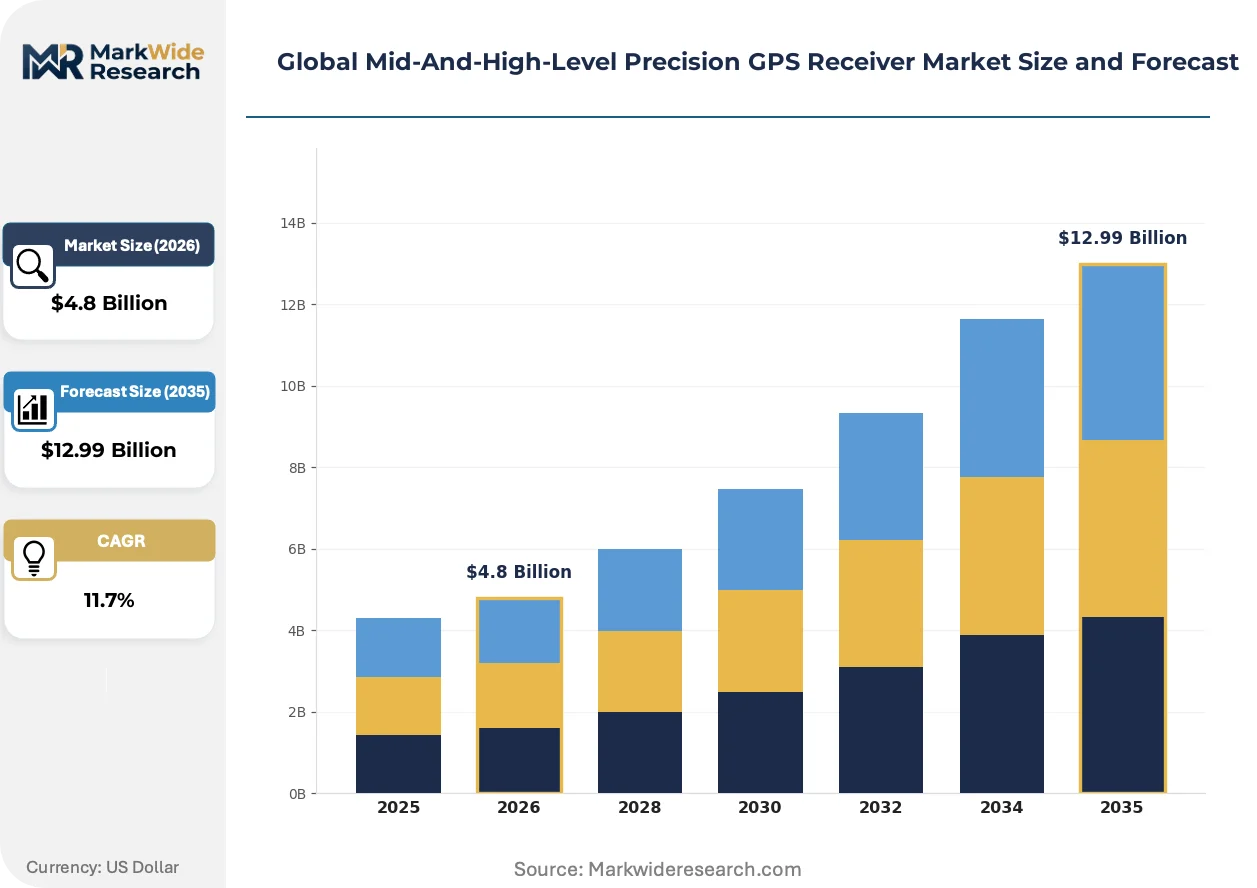
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerospace, Agriculture, Surveying, Marine Technology: RTK, PPP, DGPS, SBAS End User: Government, Commercial, Military, Research Institutions Device Type: Handheld, Embedded, Rover, Base Station |
| Companies Covered | Trimble Inc., Topcon, Hexagon AB, Hemisphere GNSS Inc., Septentrio, Javad GNSS, AG Leader Technology Inc., CNH Industrial N.V., Comnav Technology Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mid-And-High-Level Precision GPS Receiver Market Strategic Shifts
Receiver architectures are converging around software-defined positioning engines that decouple signal processing from RF front-ends, enabling firmware-upgradable constellation support without hardware replacement.
Multi-band GNSS system-on-chip designs are electrifying cost structures in high-volume OEM applications. Trimble and u-blox have shipped embedded modules combining L1/L2/L5 tracking with integrated IMU fusion for agricultural machine control. This integration is compressing bill-of-materials differentiation between premium geodetic and mid-tier precision tiers.
Japan's METI positioning standards now mandate QZSS L6 signal reception for centimeter-level public services, forcing receiver manufacturers to add 1278.75 MHz front-end support. Construction machine control vendors serving Japanese infrastructure projects are redesigning antenna and RF chains to meet these specifications. Domestic contractors face equipment replacement timelines tied to METI's 2027 full-operational capability deadline.
Equipment-as-a-service contracting is displacing capital purchase models in North American precision agriculture. John Deere and CNH Industrial dealers now bundle RTK correction subscriptions with seasonal hardware access, compressing customer switching costs and locking in multi-year receiver deployment. This shift concentrates procurement authority among dealer groups and reduces direct manufacturer channel control.
Global Mid-And-High-Level Precision GPS Receiver Market Segmentation
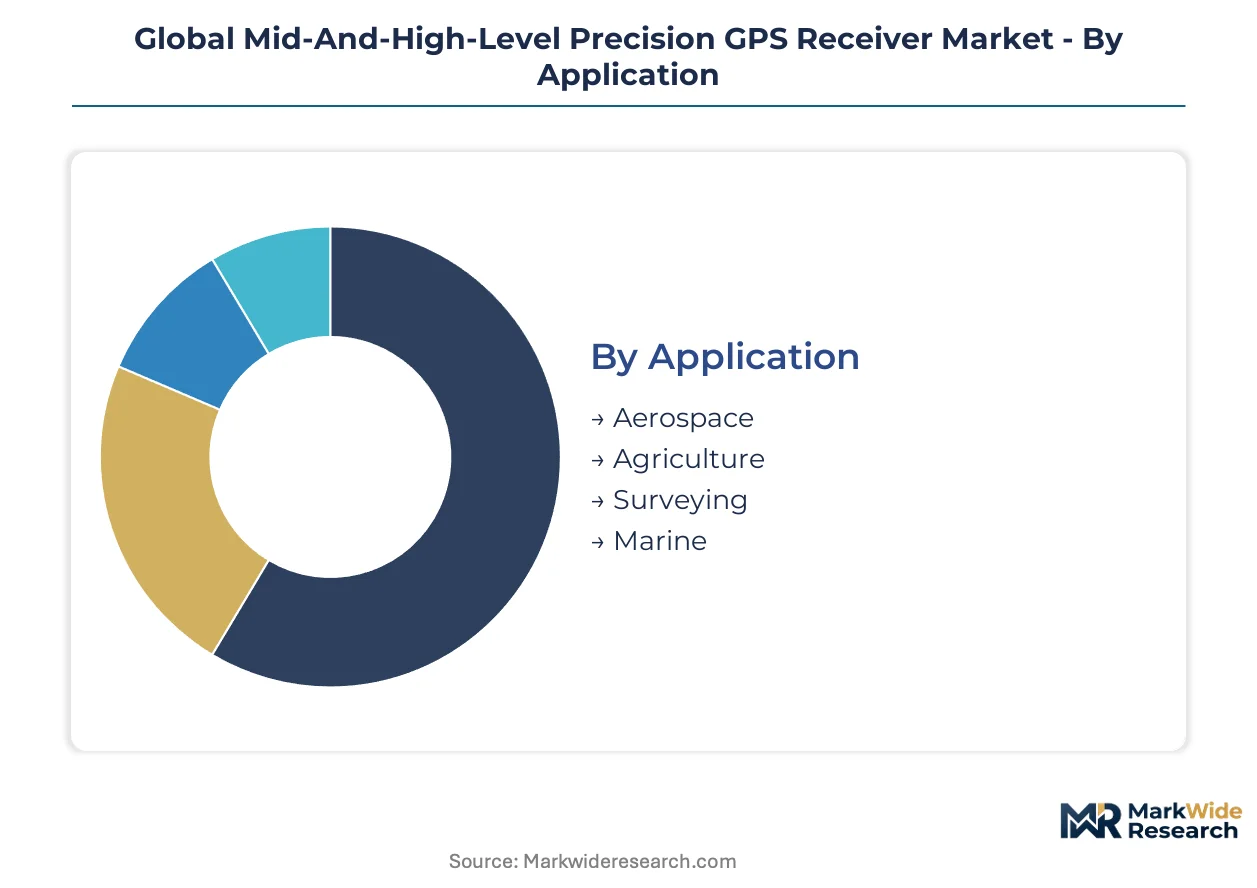
Precision GPS receiver segmentation reveals how certification requirements, integration depth, and end-use economics fragment procurement patterns across aviation, agriculture, and geospatial workflows. Each dimension carries distinct hardware specifications and regulatory burdens that shape supplier positioning.
Application:
FAA WAAS certification governs aviation receivers, while EASA EGNOS mandates filter European safety-critical deployments. Agriculture and marine applications face less prescriptive approval frameworks but demand ruggedization against environmental stressors.
- Agriculture:Multi-frequency RTK units with integrated IMU fusion dominate autonomous tractor and variable-rate input systems. Procurement concentrates across the US Corn Belt and North China Plain as dealer networks bundle hardware with correction subscriptions.
- Surveying:Geodetic-grade receivers with optical-mechanical hybrid interfaces serve cadastral boundary determination and construction machine control. Japanese infrastructure projects impose METI positioning standards that mandate QZSS L6 signal reception.
- Aerospace:WAAS-certified multi-constellation modules support precision approach navigation with integrity monitoring. Per-unit pricing exceeds other applications due to failure-mode analysis and extended certification timelines.
- Marine:PPP-RTK receivers for auto-berthing and offshore positioning integrate vessel control systems directly. Rotterdam and Singapore harbor authorities specify centimeter-level accuracy without dedicated base station infrastructure.
Leading the category by volume: Agriculture. Growing fastest: Marine.
Technology:
Cost tier stratification separates subscription-dependent services from hardware-intensive differential architectures. Cellular network densification is compressing the premium gap between RTK and PPP-RTK deployments.
- RTK:Real-time kinematic loops achieve centimeter accuracy through carrier-phase differential correction from dedicated base stations. Installed base remains largest across precision farming corridors despite infrastructure dependency.
- PPP:Precise point positioning delivers global coverage without local reference stations via satellite correction streams. Latency limitations constrain time-critical machine control applications.
- PPP-RTK:Hybrid architectures merge PPP coverage density with RTK convergence speed, gaining share fastest as 5G networks enable rapid correction distribution.
- DGPS:Differential GPS provides sub-meter accuracy through single-frequency correction, persisting in legacy marine navigation and budget-constrained surveying.
- SBAS:Satellite-based augmentation systems including WAAS, EGNOS, and GAGAN broadcast integrity data for aviation approach eligibility. Regional mandates force receiver compatibility across multiple geostationary channels.
Volume concentration: RTK. Steepest expansion trajectory: PPP-RTK.
End User:
Customer type determines procurement authority structure and replacement cycle predictability. Government and military buyers prioritize multi-constellation resilience over unit economics.
- Commercial:Agricultural OEMs and marine operators drive embedded module demand with seasonal procurement patterns. Equipment-as-a-service contracting concentrates authority among dealer groups and fleet managers.
- Government:National mapping agencies and infrastructure authorities specify geodetic-grade receivers for cadastre and rail track surveying. Indian GAGAN network densification creates procurement windows for CORS-networked installations.
- Military:Encrypted signal authentication and anti-jamming specifications dominate requirements. Multi-constellation resilience including Galileo PRS and BeiDou B1C shapes receiver architecture.
- Research Institutions:Academic geodesy and atmospheric science applications demand open firmware interfaces for algorithm development. Lower volumes tolerate higher per-unit customization.
Dominant procurement volume: Commercial. Most stringent certification: Military.
Device Type:
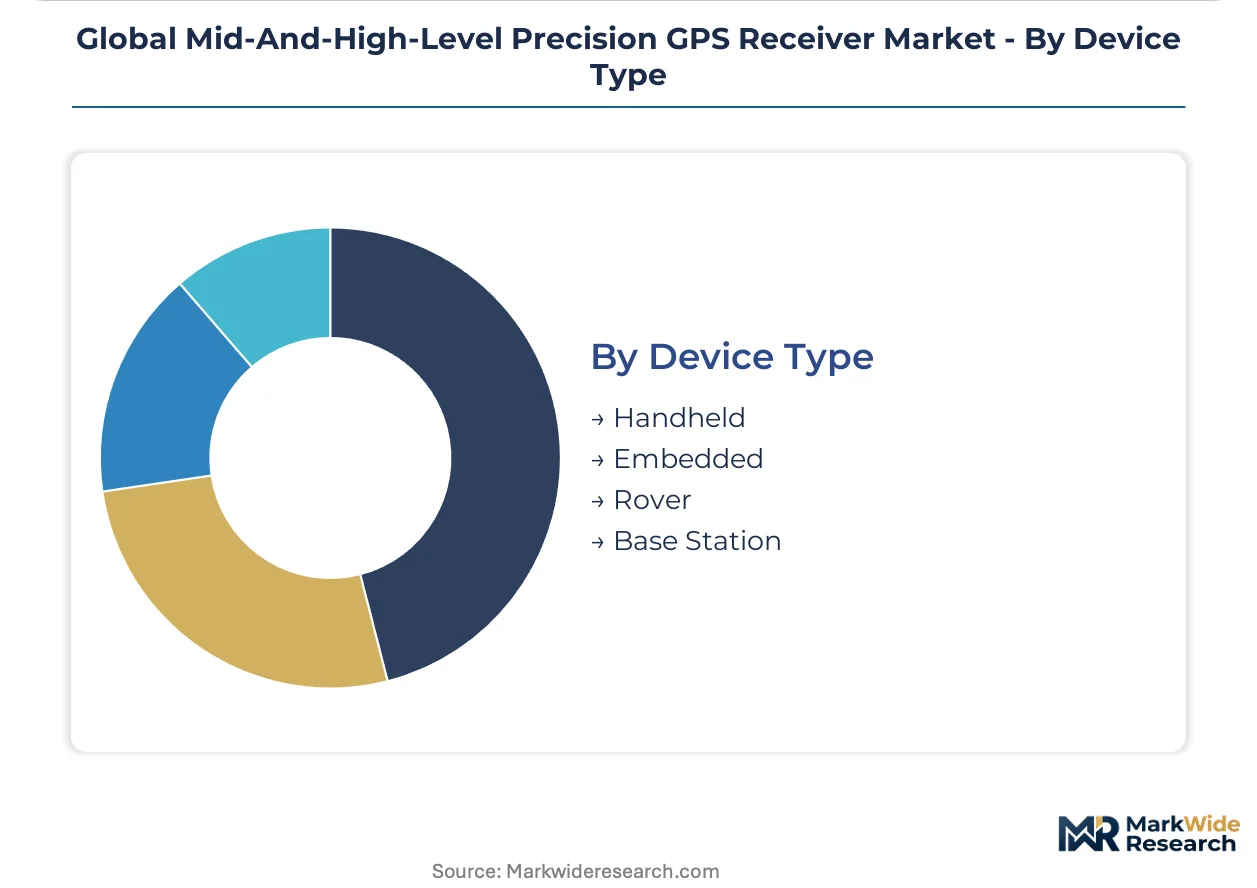
Integration depth determines margin structure and customer switching costs. OEM embedded modules capture growing share as vehicle control systems internalize positioning intelligence.
- Embedded:System-on-chip designs combine multi-band GNSS tracking with IMU fusion for direct vehicle control integration. John Deere and CNH Industrial specify these modules for autonomous agricultural equipment.
- Handheld:Portable receivers with integrated displays serve field surveying and asset mapping workflows. Ruggedization against dust and moisture defines competitive differentiation.
- Rover:Pole-mounted units with external antenna connectivity enable rapid site reconnaissance. Bluetooth and UHF radio links support flexible base station pairing.
- Base Station:Fixed reference installations broadcast correction streams to rover networks. CORS infrastructure expansion in India and Brazil sustains deployment demand.
Highest shipment volume: Embedded. Slowest growth: Handheld.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhangjiang Hi-Tech Park in Shanghai concentrates GNSS module design centers serving agricultural OEMs across the Yangtze River Delta. Tax incentives for semiconductor packaging have drawn multi-frequency chipset foundries to this zone.
United States
Autonomous tractor fleets across Iowa and Illinois drive embedded RTK module procurement through dealer networks. The FAA certifies receiver performance for WAAS aviation approaches under strict integrity standards. Chicago-based precision agriculture distributors bundle hardware with seasonal correction subscriptions.
Japan
Construction machine control vendors redesign antenna systems for QZSS L6 signal reception mandated by METI positioning standards. The MIC coordinates centimeter-level augmentation services through public-private partnerships. Osaka-based infrastructure contractors face equipment replacement deadlines tied to METI's 2027 full-operational capability timeline.
Germany
Harbor authorities in Hamburg specify PPP-RTK receivers for container vessel auto-berthing applications. EASA enforces EGNOS integrity standards that filter lower-accuracy devices from safety-critical rail and aviation deployments. Bavarian precision farming cooperatives procure multi-constellation units for variable-rate input systems.
Brazil
Soybean producers in Mato Grosso accelerate RTK-enabled receiver procurement for autonomous spraying operations. ANVISA regulates electromagnetic compatibility for agricultural electronics entering the market. Campinas hosts CORS network expansion projects addressing ionospheric correction latency in equatorial regions.
Australia
Wheatbelt autonomous agriculture fleets demand sub-inch accuracy without dedicated base station infrastructure. The TGA oversees spectrum allocation for GPS augmentation services alongside geodetic infrastructure standards. Perth-based dealer networks consolidate procurement authority through equipment-as-a-service contracting models.
Global Mid-And-High-Level Precision GPS Receiver Market Competitive Environment
Top-tier vendors anchor integrated solution stacks, while mid-tier specialists compete on module cost and regional service density. The vendor base stratifies across geodetic-grade instrument manufacturers, agricultural OEM captive suppliers, and GNSS chipset-integrated module providers. Three archetypes dominate: full-stack farm management platforms, optical-mechanical hybrid surveying instrument specialists, and correction service network operators. Competitive moves concentrate on strategic partnerships with agricultural OEMs and vertical integration into CORS infrastructure ownership.
Within the integrated platform tier, Trimble Inc. and Hexagon AB exemplify archetypes combining hardware with recurring correction service revenue. Topcon occupies a position representing optical-mechanical hybrid instrumentation dominance in Japanese infrastructure markets. These three entities anchor competitive dynamics through divergent approaches to customer lock-in: software-stack integration, captive geospatial services, and regional specification compliance.
| Leading Market Players |
|---|
| Trimble Inc. |
| Topcon |
| Hexagon AB |
| Hemisphere GNSS Inc. |
| Septentrio |
| Javad GNSS |
| AG Leader Technology Inc. |
| CNH Industrial N.V. |
| Comnav Technology Ltd. |
| Others |
Value Chain & Pricing Dynamics
Multi-frequency GNSS front-end silicon costs cascade through receiver pricing tiers as foundry capacity constraints in Taiwan and South Korea tighten procurement leverage for agricultural OEMs and surveying instrument manufacturers.
Pricing Analysis
Short-lead-time premiums of fifteen to twenty percent apply to RTK modules serving Brazilian soybean operators during planting windows, while spot inventory discounts emerge in European surveying markets during winter construction lulls. Three-tier pricing structure across aviation-certified, geodetic-grade, and OEM-embedded levels separates failure-mode analysis costs from volume manufacturing economies. Cost compression in mid-tier precision receivers is intensifying because agricultural dealers bundle hardware with correction subscriptions, masking true unit economics. Commercial farming cooperatives exhibit highest price sensitivity; military procurement offices show least.
Supply Chain Analysis
Refurbishment flows from Australian wheatbelt equipment-as-a-service returns feed secondary markets across Southeast Asian surveying operations, extending module lifecycle revenue. Taiwan, South Korea, and China concentrate L1/L2/L5-capable RF front-end foundry output. Raw material dependencies include gallium arsenide substrates, precision ceramic antenna elements, and IMU-grade MEMS sensors. Single-source vulnerability in multi-frequency chipset supply exposes procurement to geographic disruption. Distribution runs through agricultural dealer networks and geospatial equipment distributors with regional service density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-frequency chipset consolidation among three foundry sources is forcing weaker receiver assemblers toward exit or acquisition as margin compression accelerates.
For Market Incumbents: Extend correction service network ownership to lock in recurring revenue and raise switching costs against modular competitors. Secure captive supply agreements with Taiwan-based foundries to mitigate single-source vulnerability in L1/L2/L5 front-end silicon. Invest in QZSS L6 and Galileo PRS certification ahead of METI and EASA mandate deadlines to filter lower-accuracy rivals from safety-critical applications. For New Entrants and Emerging Players: Enter via Indian rail track surveying and smart city cadastre segments where GAGAN network densification creates white space for CORS-networked receiver deployment. Target PPP-RTK marine modules for Rotterdam and Singapore harbor auto-berthing specifications, where vessel-integrated demand outpaces incumbent capacity. Pursue direct partnerships with construction machine control OEMs serving Japanese infrastructure projects facing 2027 equipment replacement deadlines. For Investors and Strategic Acquirers: METI's 2027 full-operational capability deadline for QZSS L6 signal reception is the leading indicator that Japanese construction equipment replacement cycles will concentrate procurement authority among certified suppliers. Five-to-ten-year viability favors correction service network operators with CORS infrastructure ownership over pure hardware assemblers. Monitor FAA WAAS and EASA EGNOS certification queue lengths as signals of regulatory moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Correction Service Network Acquisition | CORS infrastructure ownership raises customer switching costs and stabilizes recurring revenue against hardware commoditization. |
| Multi-Constellation Certification Investment | Galileo PRS and QZSS L6 approvals filter competitors from Japanese and European safety-critical procurement. |
| Foundry Partnership Structuring | Taiwan and South Korea foundry agreements mitigate single-source vulnerability in L1/L2/L5 chipset supply. |
| Equipment-as-a-Service Platform Launch | Dealer network bundling compresses customer switching costs and concentrates multi-year deployment authority. |
| PPP-RTK Module Development | Hybrid architectures capture marine auto-berthing and autonomous agriculture demand without base station infrastructure. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with precision agriculture OEM procurement directors, geospatial equipment distributors, CORS network operators, and FAA certification engineers provided operational validation. EASA EGNOS integrity standards documentation, Japan MIC augmentation service specifications, and FCC spectrum allocation proceedings supplied regulatory boundary conditions. Bottom-up shipment estimates from embedded module manufacturers triangulated against top-down precision farming corridor demand models.
Granularity-level modeling tracked receiver deployments by technology tier, application segment, and device type across the projection horizon. RTK, PPP-RTK, and SBAS architectures were modeled separately with constellation modernization timelines and cellular network densification curves as exogenous inputs. CAGRs derived from unit shipment trajectories and average selling price compression curves in agricultural OEM channels. 5G positioning convergence and ionospheric correction latency in equatorial regions shaped regional adoption differential assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EGNOS mandate enforcement or prolonged FCC Ligado interference disputes. Forecasts reflect documented assumptions regarding constellation operational status and augmentation service interoperability. Practitioners should monitor FAA WAAS certification queue lengths and Taiwan foundry utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
Inertial Sensing Products Market
Sensors and Controls
Aton Management and Monitoring System Market
Sensors and Controls
Non-Glass Capacitive Sensors Market
Sensors and Controls
Ultrasound Sensors Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Parking Sensors Market
Sensors and Controls
Asia-Pacific Wireless Brain Sensors Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Multi-Function Timer Market