
 Aton Management and Monitoring System Market | 2026-2036
Aton Management and Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Aton Management and Monitoring System Market Intelligence
A long-standing reliance on large government contracts from public institutions is unwinding as demand from commercial Transportation Operators and Utility Providers accelerates. Thales Group leverages its extensive defense and aerospace expertise to serve national maritime authorities. Kongsberg Gruppen ASA competes with integrated sensor-to-software solutions for port and coastal surveillance. Tideland Signal Corporation specializes in the core aids to navigation hardware and monitoring systems.
An Aton management and monitoring system is a networked platform for the remote oversight of maritime aids to navigation. It uses telemetry to transmit data on asset status, such as light function and GPS position, ensuring navigational integrity for maritime authorities. While Real-Time Monitoring solutions are mature, Predictive Analytics modules are gaining traction. Cloud-Based deployment models are increasingly preferred over On-Premise systems for their scalability in managing geographically dispersed assets.
Recommendations from the International Association of Marine Aids to Navigation and Lighthouse Authorities (IALA) guide system design globally. National bodies like the U.S. Coast Guard and Japan's Maritime Safety Agency enforce specific performance criteria for aids in their waters. System providers face a strategic choice between offering all-in-one platforms or specializing in modular components for an open ecosystem.
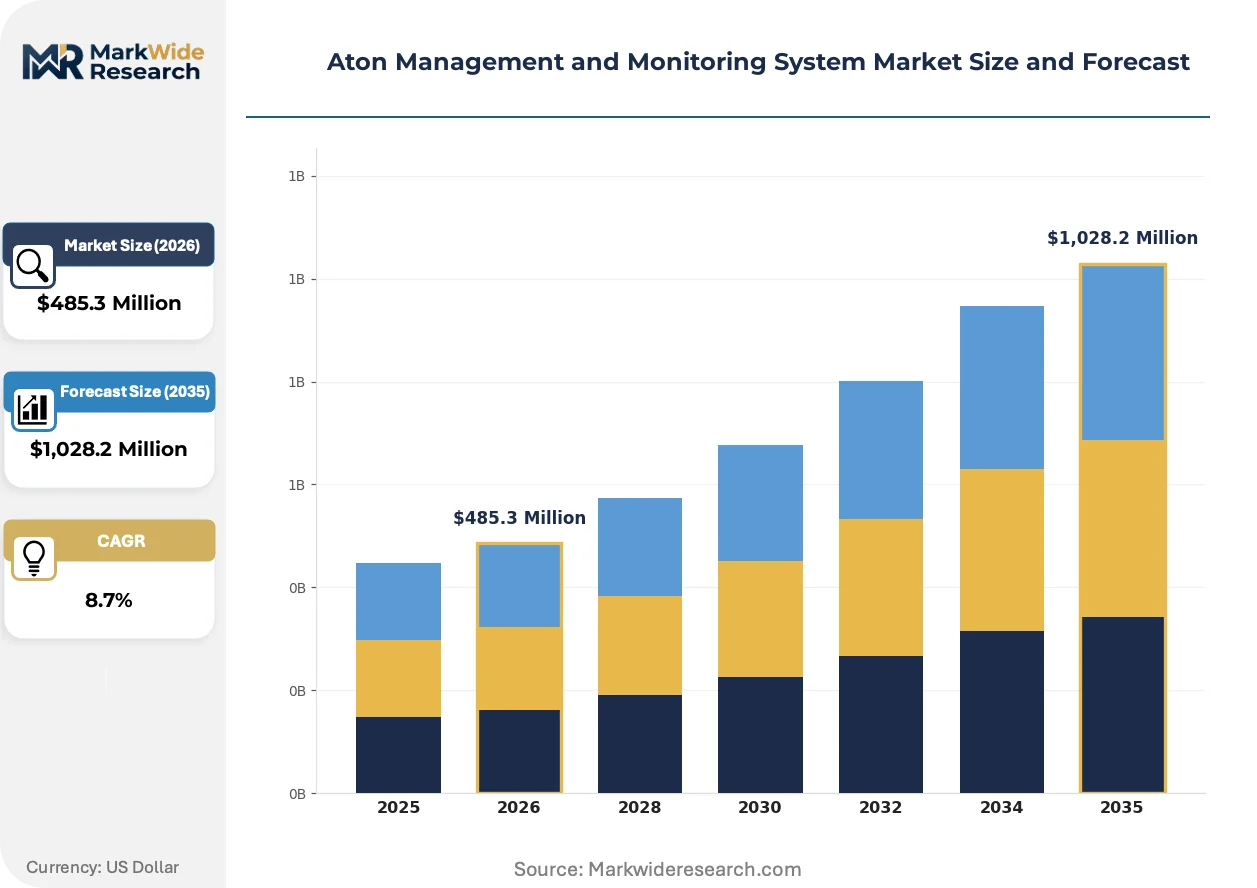
Market Dynamics
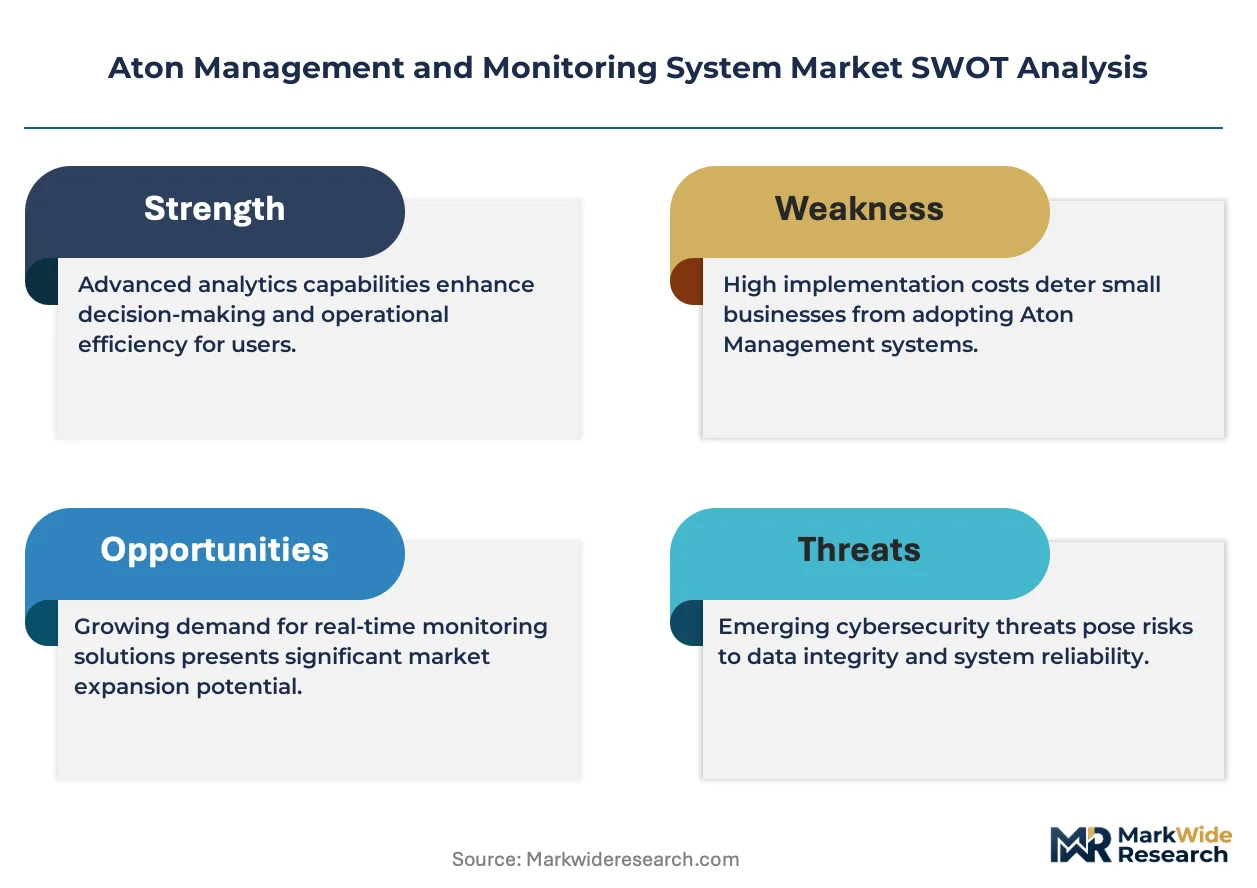
The transition from public-sector capital expenditure to subscription-based services for commercial operators defines the market's core dynamic. This shift prioritizes software scalability and real-time data analytics over traditional, hardware-centric government contracts for physical aids.
Growth Catalysts
- IALA Recommendations:Guidelines from the International Association of Marine Aids to Navigation and Lighthouse Authorities on data exchange and cybersecurity encourage the adoption of modern, interoperable systems by national maritime bodies, creating a baseline for technology upgrades.
- Offshore Energy Expansion:The rapid construction of offshore wind and tidal energy farms, particularly in the North Sea and off the U.S. East Coast, generates substantial demand for new Aton systems to mark infrastructure and ensure navigational safety.
- Satellite Connectivity Advances:Decreasing costs and increasing availability of low-earth orbit (LEO) satellite services make it economically feasible to connect and monitor remote maritime assets, expanding the addressable market for real-time monitoring solutions.
Market Restraints
- High Retrofitting Costs:The significant capital investment required to upgrade or replace legacy, non-networked aids with modern telemetry units acts as a major deterrent for budget-constrained port authorities and government agencies.
- Remote Area Connectivity Gaps:Inconsistent or non-existent cellular and satellite coverage in polar regions or vast oceanic expanses limits the effectiveness of real-time monitoring, forcing reliance on less effective periodic checks.
- Cybersecurity Concerns:The networking of critical navigational aids introduces vulnerabilities to cyberattacks, a risk that can cause significant hesitation among maritime authorities responsible for ensuring safe passage.
Strategic Opportunities
- Predictive Maintenance Modules:Developing AI-powered analytics to forecast component failures in lanterns, batteries, and moorings offers a significant value-add, enabling operators to shift from reactive repairs to proactive, cost-saving maintenance.
- VTS and Aton System Integration:Combining Aton monitoring data with Vessel Traffic Service (VTS) platforms creates a unified maritime domain awareness picture, a high-value proposition for port authorities seeking comprehensive oversight.
- Arctic Shipping Route Development:The gradual opening of new Arctic shipping lanes due to climate change creates a greenfield opportunity for deploying rugged, ice-resistant Aton infrastructure in a region with minimal existing navigational support.
Industry Challenges
- Legacy System Interoperability:Integrating modern IP-based platforms with a diverse installed base of older, proprietary aids to navigation presents significant technical hurdles, often requiring custom development work and complex middleware.
- Shortage of Hybrid-Skilled Technicians:A scarcity of personnel possessing combined expertise in maritime operations, electronics, and IT networking complicates the installation, maintenance, and troubleshooting of sophisticated Aton systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aton Management and Monitoring System Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,028.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Real-Time Monitoring, Predictive Analytics, Asset Tracking, Alert Management, Data Visualization, Risk Assessment Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing Use Case: Equipment Management, Environmental Monitoring, Energy Consumption Tracking, Facility Oversight, Security Surveillance, Compliance Control Client Sector: Manufacturing Plants, Transportation Operators, Utility Providers, Smart Buildings, Telecommunication Firms, Public Institutions |
| Companies Covered | Thales Group, Kongsberg Gruppen ASA, Honeywell International Inc., Tideland Signal Corporation, McMurdo Group, Furuno Electric Co., Ltd., ATLAS ELEKTRONIK GmbH, Saab AB, Japan Radio Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aton Management and Monitoring System Market Strategic Shifts & Innovations
System intelligence is fundamentally altering the value proposition of Aton management. The focus is shifting from simple asset tracking to leveraging data for operational efficiency, predictive maintenance, and enhanced maritime safety, creating new competitive frontiers for vendors.
Cloud-based software platforms are becoming the standard deployment model for Aton management. Commercial transportation operators and forward-looking maritime authorities are rapidly adopting these scalable systems. This software-as-a-service approach is displacing the traditional on-premise hardware servers and manual data collection processes that defined legacy operations.
The U.S. Coast Guard's initiatives for digital and virtual aids to navigation (e-Aton) are creating new system requirements. This regulatory push requires platforms to manage and transmit data for non-physical markers, which exist only as digital signals broadcast to shipboard systems. System providers serving the U.S. market must now incorporate functionalities to handle these virtual assets alongside traditional physical buoys.
A preference for outcome-based service contracts is changing purchasing behavior among end-users. Instead of buying individual buoys and software licenses, operators increasingly procure a complete, managed monitoring service on a subscription basis. This trend is most visible with private port operators and offshore energy firms in Europe and North America that lack large in-house maintenance teams.
Aton Management and Monitoring System Market Segmentation
The Aton Management and Monitoring System market comprises several distinct segments, each addressing specific operational needs and technological preferences within maritime infrastructure. Understanding these segment dynamics reveals how different stakeholders prioritize system capabilities and deployment strategies. This granular view highlights areas of concentrated investment and evolving user requirements.
Solution Type:
Substitution pressure within solution types is evident as advanced modules begin to displace simpler, standalone functionalities. Operators increasingly seek integrated platforms that offer more than basic asset status reporting, shaping procurement decisions for new system implementations.
- Real-Time Monitoring:These solutions provide instantaneous data on Aton operational status, including light function and GPS position, ensuring immediate awareness of navigational integrity. National maritime authorities and port operators requiring continuous oversight drive demand.
- Predictive Analytics:AI-powered modules analyze historical and live data to forecast potential component failures, enabling proactive maintenance scheduling for Atons. Offshore energy firms and large commercial operators in Europe adopt these tools to optimize asset uptime.
- Asset Tracking:This functionality monitors the physical location and movement of mobile Atons, such as buoys, crucial for recovery and redeployment.
- Alert Management:Systems generate automated notifications upon detecting deviations from normal Aton operational parameters or predefined thresholds.
- Data Visualization:Platforms present complex Aton data through intuitive graphical interfaces, enhancing situational awareness for monitoring teams.
- Risk Assessment:These tools evaluate potential hazards to navigation based on Aton status and environmental factors, informing maritime safety decisions.
Real-Time Monitoring anchors the volume base while Predictive Analytics gains share at the steepest rate.
Deployment Model:
Market preference for deployment models is shifting, driven by scalability, maintenance overhead, and data accessibility considerations. Legacy on-premise systems are giving way to more agile and distributed architectures, reflecting broader IT infrastructure trends impacting maritime operations.
- Cloud-Based:These models host Aton management software and data on remote servers, accessible via the internet, offering unparalleled scalability and global accessibility. Commercial transportation operators and offshore wind developers prioritize cloud solutions for managing dispersed assets.
- On-Premise:Systems are installed and managed directly on the user's local infrastructure, providing maximum control over data security and customization. Public institutions with stringent data sovereignty requirements, like the U.S. Coast Guard, often favor this model.
- Hybrid:This approach combines elements of both on-premise and cloud deployments, leveraging cloud benefits while retaining sensitive data locally.
- Edge Computing:Data processing occurs closer to the Aton asset, reducing latency and bandwidth, particularly beneficial for remote or intermittently connected locations.
Cloud-Based solutions are expanding most quickly, offering flexibility that contrasts with the established control of On-Premise installations.
Use Case:
The application focus for Aton management systems extends beyond basic navigational support, addressing broader operational efficiency and regulatory compliance. End-users increasingly leverage these platforms for diverse functions within their maritime infrastructure, creating new value propositions.
- Equipment Management:This core use case involves monitoring the operational status, performance, and maintenance schedules of physical aids to navigation. National maritime authorities, including Japan's Maritime Safety Agency, rely heavily on this function.
- Compliance Control:Systems assist operators in meeting regulatory requirements set by bodies like IALA and national authorities, ensuring Atons adhere to specific performance criteria. Port authorities in the United States utilize these systems to demonstrate adherence to U.S. Coast Guard standards.
- Environmental Monitoring:Aton platforms integrate sensors to collect data on environmental conditions like water temperature, supporting broader maritime situational awareness.
- Energy Consumption Tracking:Monitoring power usage of Aton assets, especially solar-powered units, helps optimize energy efficiency and predict battery lifespan.
- Facility Oversight:This use case applies to larger maritime facilities, such as port infrastructure, where Aton systems contribute to overall operational visibility.
- Security Surveillance:Integration with security sensors provides an additional layer of oversight around critical maritime infrastructure, enhancing protection.
Equipment Management remains fundamental, while Compliance Control applications are experiencing significant uptake among regulated entities.
Client Sector:
Procurement patterns vary significantly across client sectors, influenced by budget cycles, regulatory mandates, and operational scales. The transition from public-sector capital expenditure to subscription-based services impacts how different client types acquire Aton systems, redefining vendor-client relationships.
- Transportation Operators:This sector includes commercial shipping companies, port authorities, and ferry operators requiring reliable Aton systems for safe passage and asset protection. Private port operators in Europe increasingly adopt outcome-based service contracts for Aton management.
- Public Institutions:National coast guards, naval forces, and government-run lighthouse authorities constitute this segment, procuring systems for national maritime safety and sovereign waters management. The U.S. Coast Guard represents a major client, driving requirements for physical and e-Aton capabilities.
- Manufacturing Plants:Industrial facilities near waterways use Aton systems for internal navigation, marking private channels, or supporting their own port operations.
- Utility Providers:This segment includes operators of offshore wind farms and oil and gas platforms that deploy Aton systems to mark their infrastructure for navigational safety.
- Smart Buildings:Waterfront smart building complexes may integrate Aton data for localized maritime awareness or facility management purposes.
- Telecommunication Firms:These companies use Aton systems to mark subsea cables or offshore communication infrastructure, ensuring protection and visibility.
Transportation Operators are driving new service models, contrasting with the established, large-scale procurements typical of Public Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The intricate network of global shipping lanes, particularly those facilitating trade between Asia and Europe, drives significant demand for Aton management systems. Coastal nations with high maritime traffic invest heavily in navigational infrastructure oversight. This ensures safe passage and efficient logistics for commercial vessels.
United States
U.S. Coast Guard initiatives for digital and virtual aids create new system requirements. Strict performance criteria enforced by national bodies drive system upgrades for safety. Major port complexes along the East and West Coasts, like those in Los Angeles and New York, prioritize comprehensive oversight. Offshore energy expansion off the U.S. East Coast further stimulates demand for new Aton systems.
China
China's vast coastline and high-volume shipping channels necessitate advanced Aton management for maritime safety. The national maritime authorities implement strict guidelines for navigational integrity across its ports. Major port cities such as Shanghai and Shenzhen integrate real-time monitoring solutions to manage dense marine traffic. Investments in modernizing coastal infrastructure support the deployment of cloud-based systems.
Germany
Germany's strategic location in Europe and its focus on offshore wind energy expansion generate demand for Aton systems. European maritime safety regulations, including those influenced by IALA, guide system design and implementation. Major ports like Hamburg and Bremerhaven require integrated solutions for Vessel Traffic Services and Aton oversight. Advanced analytics for predictive maintenance are gaining traction among commercial operators in the North Sea.
Japan
Japan's Maritime Safety Agency heavily relies on Aton systems for managing its extensive network of aids to navigation. National performance criteria ensure navigational accuracy and safety across its busy shipping lanes. Major industrial coastal areas, including Tokyo Bay and the Seto Inland Sea, demand robust equipment management solutions. Cloud-based platforms are increasingly adopted for scalable management of geographically dispersed assets.
Canada
Canada's long coastlines and developing Arctic shipping routes create opportunities for rugged Aton infrastructure. The national coast guard enforces specific performance criteria for aids in challenging environments. Ports along the Great Lakes and the Pacific coast, such as Vancouver, require reliable real-time monitoring. Satellite connectivity advances are particularly relevant for connecting remote maritime assets in its northern regions.
Aton Management and Monitoring System Market Key Industry Players
Player mix skews toward established defense contractors and specialized maritime technology firms. The market structure exhibits a tiered approach, with a few large integrated solution providers and numerous niche component suppliers. Strategic archetypes include comprehensive platform developers offering end-to-end solutions and hardware-centric specialists focusing on core aids to navigation. Companies increasingly pursue portfolio diversification and strategic partnerships to expand their offerings and address evolving customer demands.
On the premium-tier vector, Thales Group exemplifies large-scale defense and aerospace expertise, serving national maritime authorities with sophisticated solutions. Kongsberg Gruppen ASA, a Norwegian firm, represents integrated sensor-to-software solutions, competing in port and coastal surveillance. Tideland Signal Corporation, a specialist firm, anchors the market for core aids to navigation hardware and monitoring systems. These players sit within distinct strategic segments, reflecting diverse approaches to Aton system provision and catering to varying client needs, from government contracts to commercial operators.
| Leading Market Players |
|---|
| Thales Group |
| Kongsberg Gruppen ASA |
| Honeywell International Inc. |
| Tideland Signal Corporation |
| McMurdo Group |
| Furuno Electric Co., Ltd. |
| ATLAS ELEKTRONIK GmbH |
| Saab AB |
| Japan Radio Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Typical lead times for Aton system component delivery, often extending several months for specialized hardware, directly influence project timelines and vendor pricing power. This market's supply chain configuration, with its reliance on niche manufacturers, impacts the cost structure for end-users.
Pricing Analysis
The pricing gap for next-generation Aton systems, featuring predictive analytics and cloud integration, commands a premium over legacy on-premise solutions. Subscription-based models are becoming the dominant pricing structure, offering operational expenditure flexibility. Price differentiation stems from the level of customization for specific maritime environments and the integration with existing Vessel Traffic Service platforms. Pricing pressure stems from the increasing availability of modular components, especially for less complex Aton hardware. Commercial transportation operators exhibit higher price sensitivity compared to national maritime authorities.
Supply Chain Analysis
Just-in-time inventory strategies are challenging for specialized Aton components, leading to strategic stockpiles for critical parts. Geographic supply concentration for core Aton hardware, such as lanterns and telemetry units, centers in countries like Germany and Japan. Key component dependencies include specialized marine-grade electronics and robust power management systems. Single-source vulnerability for advanced sensor arrays represents a structural supply chain risk. Distribution runs through a network of specialized maritime technology integrators and direct sales to large public institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market, marked by high-growth disruption, is driven by the rapid integration of satellite connectivity and IoT sensors.
For Market Incumbents: Fortify core market positions by investing in modular, open-ecosystem platforms that integrate with diverse legacy Aton hardware. This counters the threat from specialized software providers offering niche solutions. Leverage extensive defense and aerospace expertise to secure large government contracts, particularly for cybersecurity features mandated by national maritime authorities like the U.S. Coast Guard. Pursue strategic partnerships for advanced AI-powered predictive maintenance modules.
For New Entrants and Emerging Players: A certification fast-track for IALA-compliant digital and virtual aids offers a clear entry point into the Aton management market. Target under-served regions with developing Arctic shipping routes, where minimal existing navigational support creates greenfield opportunities. Focus on cloud-native solutions for commercial transportation operators and offshore energy firms, leveraging a flexible subscription-based go-to-market angle. Emphasize scalability and real-time data analytics for port authorities seeking comprehensive oversight.
For Investors and Strategic Acquirers: Long-term, this sits as a critical infrastructure play because navigational safety and maritime trade depends on robust Aton systems. Target mid-sized software specialists with proven expertise in predictive analytics or VTS integration, offering high-value intellectual property. The signal to watch is the increasing adoption rate of outcome-based service contracts among private port operators, indicating a shift towards managed solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Predictive Maintenance | Enables proactive repairs for Aton assets, reducing operational costs for port authorities. |
| Expand Cloud-Based SaaS Offerings | Attracts commercial transportation operators seeking scalable, flexible Aton management solutions. |
| Integrate with Vessel Traffic Service (VTS) Platforms | Creates a unified maritime domain awareness picture for port and coastal surveillance. |
| Target Arctic Shipping Route Infrastructure | Captures greenfield opportunities for rugged Aton systems in a climatically changing region. |
| Acquire Specialized Cybersecurity Firms | Addresses growing concerns among maritime authorities regarding networked navigational aid vulnerabilities. |
Research Approach
A spread of perspectives from national maritime authorities, commercial port operators, Aton system integrators, and offshore energy developers converged on the working assumptions for this analysis. Primary interviews with these industry stakeholders were rigorously combined with secondary validation from sources like IALA guidelines, U.S. Coast Guard reports, and Japan's Maritime Safety Agency publications. This approach ensured a robust bottom-up and top-down triangulation of market estimates.
Market segmentation dimensions modeled include solution type, deployment model, use case, and client sector, alongside the regional adoption patterns for advanced Aton technologies. The analytical framework integrated historical data trends with projected technological advancements and regulatory shifts across the analysis window. Compound annual growth rates were derived through a multi-variable regression analysis, incorporating factors like new offshore energy farm developments and satellite connectivity costs.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement by national bodies, with deviation risk concentrated in unforeseen global supply chain disruptions or rapid shifts in maritime trade routes. Revision becomes warranted when major technological breakthroughs in Aton hardware or unexpected changes in international maritime safety standards cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
HVAC Sensor Market
Sensors and Controls
Rangefinder Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
US Distributed Acoustic Sensing Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Weather Radar Market
Sensors and Controls
Europe Nano Radiation Sensors Market
Sensors and Controls
Mexico Smart Ventilation Fans Market
Sensors and Controls
Contact Steering Torque Sensor Market