
 Automotive Interior Trims Market | 2026-2036
Automotive Interior Trims Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Interior Trims Market Analysis
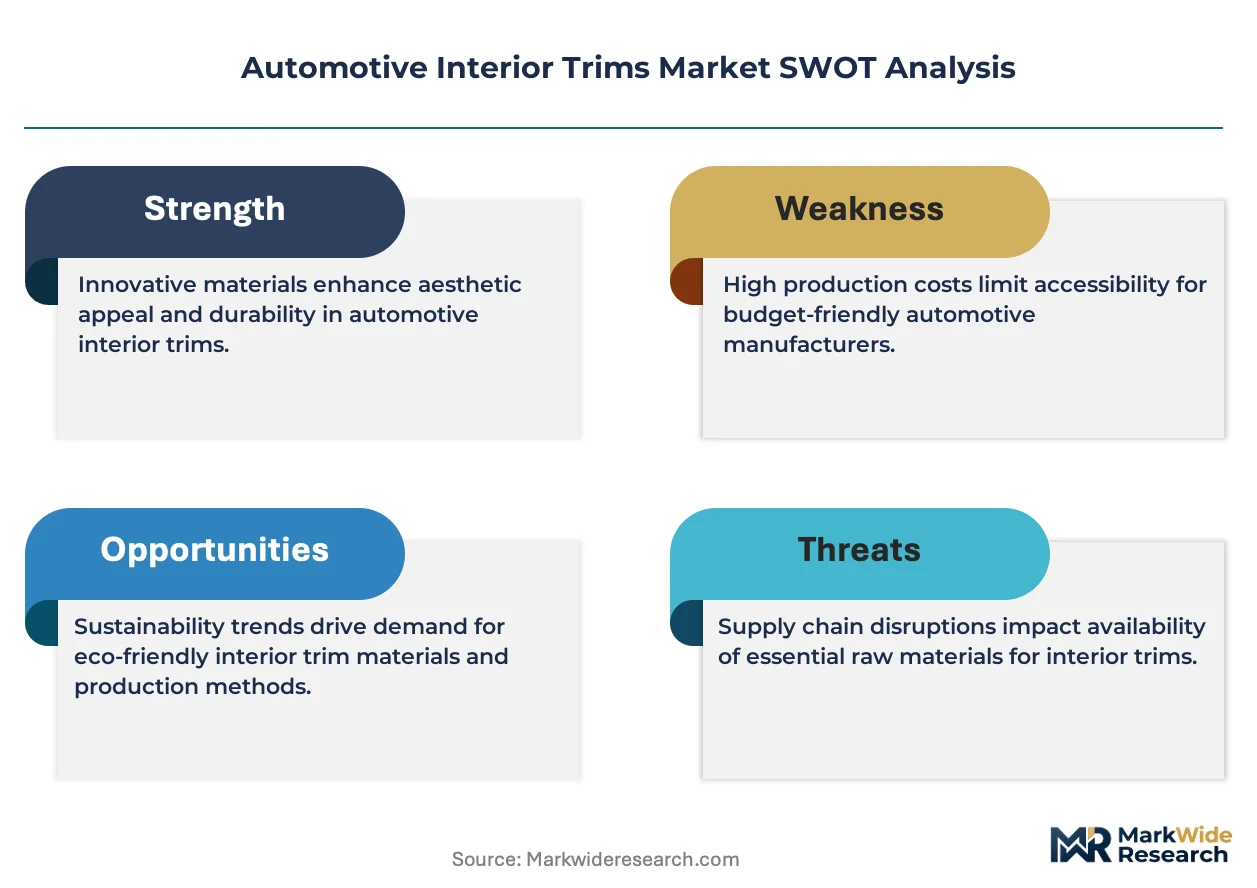
The EU Green Deal's interior air quality mandates is realigning material selection across European automotive supply chains. Lear Corporation leverages its vertical integration in sustainable foam technologies to capture premium seating contracts. Yanfeng Automotive Interiors anchors its competitive position through manufacturing scale across Asia-Pacific assembly corridors.
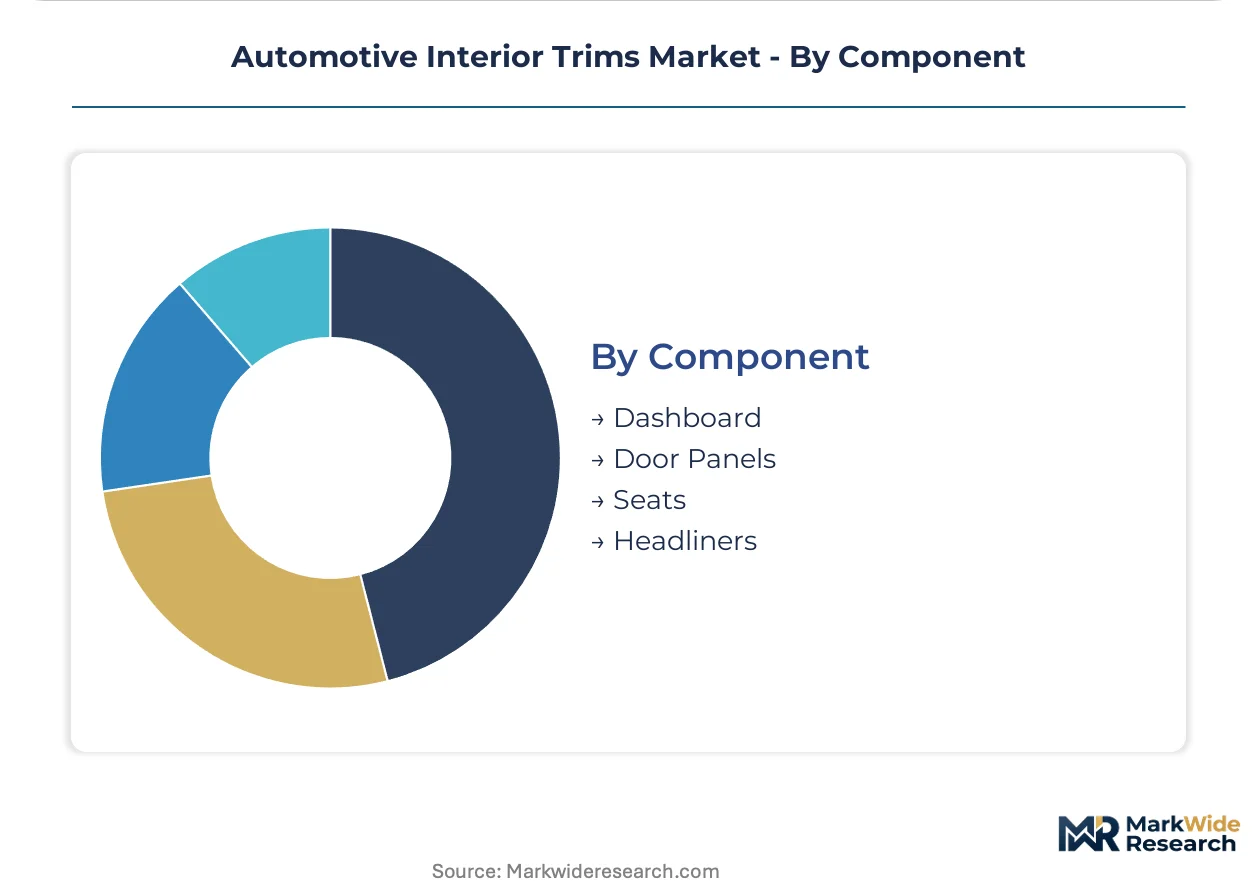
Automotive interior trims encompass surface finishing components, structural panels, and decorative elements manufactured from polymers, textiles, natural fibers, or leather substrates through injection molding, compression forming, or textile lamination processes, serving both aesthetic differentiation and occupant protection functions. Plastic and leather material categories command the dominant share of current value pools, though fabric alternatives are gaining structural ground in mass-market electric vehicle platforms where weight reduction intersects with cost targets. Dashboard and door panel components concentrate the highest engineering intensity and supplier margin capture, while headliner applications represent a faster-growing segment driven by acoustic and thermal management integration.
EPA vehicle interior emissions guidelines, ECHA REACH substance restrictions, and China's GB standards for cabin air quality collectively constrain volatile organic compound thresholds and material composition choices across major production regions. These frameworks elevate compliance costs for conventional petroleum-based substrates while creating certified-access advantages for suppliers with validated bio-based material portfolios. Stakeholders must monitor evolving chemical disclosure requirements and assess captive recycling capabilities against emerging extended producer responsibility frameworks.
Market Dynamics
REACH chemical restrictions are forcing Tier 1 suppliers to rebuild material portfolios around bio-based polymers, while electric vehicle OEMs demand premium cabin specifications that compress development cycles and elevate engineering intensity.
Growth Catalysts
- EU Green Deal interior air quality mandates:These frameworks accelerate certified-access advantages for suppliers with validated sustainable material portfolios across European automotive supply chains.
- Electric vehicle platform differentiation:EV OEMs expand premium cabin specifications to distinguish their offerings, driving specification upgrades in seating, dashboard, and door panel systems.
- China's GB standards for cabin air quality:These technical requirements constrain volatile organic compound thresholds and elevate compliance standards for interior trim components sold into Chinese assembly plants.
Market Restraints
- Petrochemical feedstock volatility:Conventional petroleum-based substrates face input cost instability that compresses margin predictability for injection molding and compression forming operations.
- Extended producer responsibility frameworks:Emerging regulations impose end-of-life accountability costs on manufacturers without established captive recycling infrastructure.
- Technical limitations in natural fiber processing:Moisture sensitivity and batch-to-batch property variation constrain bio-based polymer adoption in safety-critical structural panels.
Strategic Opportunities
- Acoustic-thermal integration in headliner applications:Multi-functional trim systems that combine sound absorption with thermal management command premium positioning in electric vehicle platforms.
- India's automotive PLI scheme:Production-linked incentives for advanced manufacturing create localized supply chain advantages for interior trim suppliers establishing captive operations.
- Closed-loop textile lamination:Mechanical recycling of polymer-fiber laminates enables circular material flows that satisfy ESG procurement criteria from fleet operators.
Industry Challenges
- Material certification timelines:ECHA substance authorization and OEM-specific validation protocols extend qualification periods for novel bio-based substrates.
- Legacy equipment retrofit requirements:Compression forming assets designed for petroleum-based compounds demand capital-intensive modification to process temperature-sensitive natural fiber composites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Interior Trims Market |
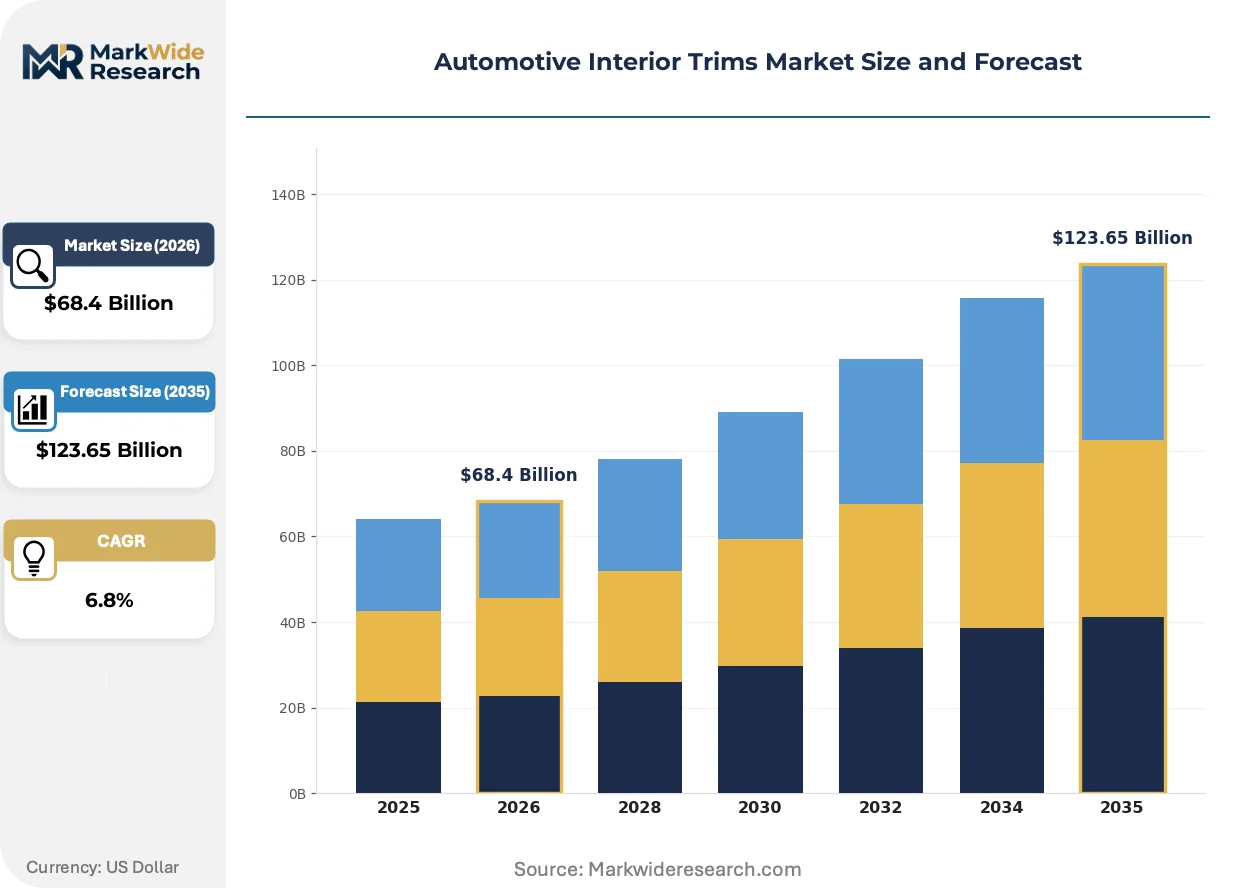
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Leather, Fabric, Plastic, Wood Vehicle Type: SUV, Sedan, Coupe, Hatchback Trim Level: Base, Mid-range, Premium, Luxury Component: Dashboard, Door Panels, Seats, Headliners |
| Companies Covered | Lear Corporation, Adient, Faurecia, Grupo Antolin, Magna International, Draexlmaier Group, Yanfeng Automotive Interiors, Toyota Boshoku Corporation, International Automotive Components, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Interior Trims Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are converging to transform how interior surfaces are engineered, sourced, and validated across automotive supply chains.
Algae-derived polyurethane foams are rewriting the economics of premium seating systems. Tier 1 suppliers in Germany and the United States are qualifying these materials for production volumes exceeding 100,000 units annually. The technology is compressing the cost premium between bio-based and petroleum-derived cushioning substrates.
ECHA REACH substance restrictions are eliminating legacy plasticizers and flame retardants from cockpit applications. Suppliers must reformulate PVC and TPO compounds to maintain compliance while preserving haptic and durability specifications. Dashboard manufacturers serving European OEMs face the most compressed reformulation timelines.
Fleet operators are consolidating interior trim procurement around lifecycle carbon metrics rather than unit cost. Leasing companies and ride-hailing platforms now specify certified recycled content thresholds in their sourcing agreements. This pattern is most visible in corporate fleet contracts across Germany and the Netherlands.
Automotive Interior Trims Market Segmentation
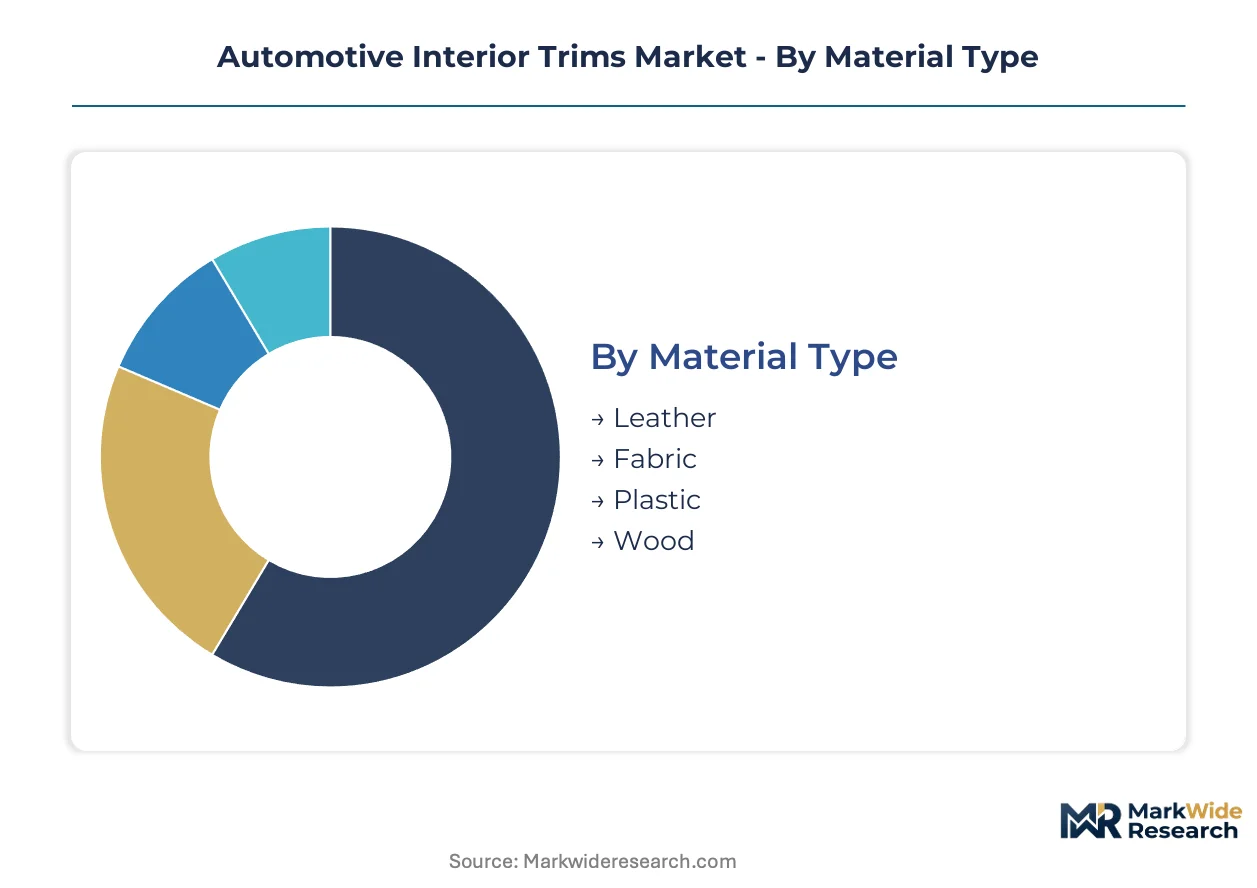
Interior trim segmentation reveals how material selection, vehicle architecture, and specification tiers intersect to determine supplier margin structures. Understanding these category boundaries clarifies where engineering intensity concentrates and where commoditization pressures dominate procurement negotiations.
Material Type:
Standalone surface applications command different validation protocols than substrates embedded within structural laminates or foam assemblies.
- Leather:Premium hides and synthetic alternatives deliver tactile differentiation in seating and steering wheel applications. European luxury OEMs in Germany and Italy specify full-grain leather for flagship sedans, though REACH chemical restrictions on tanning agents are compressing supplier qualification timelines.
- Plastic:Injection-molded thermoplastics and thermoplastic olefins form the structural backbone of dashboard carriers, door panel substrates, and console housings. Chinese assembly plants source polypropylene compounds at scale for mass-market electric vehicle platforms where cost targets intersect with GB standards for cabin emissions.
- Fabric:Woven and knitted textiles serve headliner facing, seat inserts, and pillar trim applications with acoustic absorption properties. Natural fiber blends from flax and hemp gain traction in German OEM supply chains seeking bio-based content certification.
- Wood:Veneer and reconstructed wood laminates occupy premium dashboard and center console positions. Japanese luxury marques specify open-pore walnut and ash finishes that demand precise humidity control throughout manufacturing.
Plastic leads volumes today; fabric is gaining share fastest.
Vehicle Type:
Platform architecture dictates interior surface area, panel complexity, and the economic viability of material upgrades across passenger compartments.
- SUV:Elevated seating positions and expanded cabin volumes multiply trim surface requirements per vehicle. American OEMs specify premium materials for three-row SUVs serving family and fleet segments in the United States.
- Sedan:Traditional three-box proportions concentrate engineering investment in dashboard and rear seat comfort systems. Chinese domestic brands upgrade sedan interiors to compete with German luxury imports in tier-one cities.
- Coupe:Reduced rear compartment priority shifts material budget toward front-seat haptic surfaces and door panel finishes. Italian and German sports car manufacturers specify carbon fiber and Alcantara for weight-conscious performance variants.
- Hatchback:Compact footprints and price-sensitive positioning favor fabric and synthetic leather substitutions. Indian and Brazilian assembly plants prioritize localization of hatchback trim supply under production-linked incentive frameworks.
SUV commands the largest absolute demand; sedan maintains stable share in corporate fleet procurement.
Trim Level:
Specification stratification determines which material grades and surface technologies enter production bill-of-materials at each price positioning.
- Base:Hard-touch plastics and minimal acoustic insulation satisfy regulatory minimums without aesthetic elaboration. Fleet operators in the Netherlands and Germany specify base trim for high-utilization ride-hailing vehicles where durability outweighs differentiation.
- Mid-range:Soft-touch surfaces and partial leather seating balance perceived quality with manufacturing cost control. Mass-market electric vehicle platforms in China concentrate volume at this specification tier.
- Premium:Full leather upholstery, genuine wood veneer, and active noise cancellation integration distinguish upper-middle positioning. Korean and German OEMs expand premium trim penetration in SUV segments.
- Luxury:Bespoke material selection, artisan finishing, and individualized color programming serve ultra-high-net-worth buyers. British and Italian marques maintain atelier operations for commissioned interior specifications.
Mid-range captures the highest unit volumes; premium is climbing the fastest as electric vehicle OEMs seek differentiation.
Component:
System integration depth varies dramatically—dashboards function as electronic housing assemblies while headliners increasingly incorporate sensor and lighting modules.
- Dashboard:Multi-material assemblies combining structural carriers, decorative skins, and human-machine interface integration represent the highest engineering complexity. Suppliers serving German OEMs invest in simultaneous engineering capabilities for instrument panel development.
- Door Panels:Armrest, map pocket, and window switch integration demands precise tolerance management across material transitions. Mexican and Eastern European manufacturing clusters specialize in door trim module assembly for North American and European vehicle plants.
- Seats:Foam, frame, and surface material integration determines occupant comfort and safety performance. Lear Corporation and Adient dominate seating supply through captive foam production and just-in-sequence delivery systems.
- Headliners:Acoustic insulation, ambient lighting, and overhead console integration transform this formerly commodity component into a technology carrier. Electric vehicle platforms specify thermally insulated headliners to reduce HVAC energy consumption.
Dashboard retains the highest supplier margin capture; headliner is expanding most quickly through functional integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive interior trims industry traces its modern scaling to post-war Germany, where precision tooling and polymer processing converged around Stuttgart and Munich to supply European luxury marques with dashboard and seating systems.
China
Domestic electric vehicle manufacturers in Shanghai and Shenzhen are expanding premium cabin specifications to differentiate mass-market platforms. MIIT emission standards and GB cabin air quality regulations constrain volatile organic compound thresholds for all interior components. The Yangtze River Delta cluster around Shanghai anchors the highest concentration of Tier 1 seating and dashboard module suppliers serving BYD, NIO, and Xpeng assembly plants.
Germany
Luxury OEMs in Munich and Stuttgart specify full-grain leather and open-pore wood veneers for flagship sedans and performance SUVs. ECHA REACH substance restrictions are compressing qualification timelines for tanning agents and plasticizers across cockpit applications. The Baden-Württemberg manufacturing corridor specializes in precision-molded thermoplastic carriers and acoustic-thermal headliner systems for BMW, Mercedes-Benz, and Porsche.
United States
Three-row SUV demand from family and fleet segments in Detroit and Nashville is multiplying trim surface requirements per vehicle. EPA vehicle interior emissions guidelines elevate compliance costs for conventional petroleum-based substrates. The Southeast manufacturing belt spanning Tennessee, Kentucky, and Alabama hosts door panel and console assembly operations supplying North American vehicle plants.
Japan
Hybrid and battery-electric platforms from Toyota and Honda are integrating active noise cancellation into headliner and pillar trim systems. METI carbon neutrality roadmaps are accelerating bio-based polymer adoption among domestic supply chains. The Nagoya-Toyota industrial zone maintains captive production of precision-instrument panels and steering wheel assemblies.
India
Compact hatchback and sub-4-meter SUV production in Pune and Chennai is prioritizing localization of fabric and synthetic leather supply under cost-sensitive positioning. The automotive PLI scheme for advanced manufacturing creates tariff advantages for interior trim suppliers establishing captive operations. The Tamil Nadu belt around Chennai is attracting seating and door panel module investments from global Tier 1 suppliers.
Automotive Interior Trims Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material certification and simultaneous engineering capabilities. The supplier base concentrates around seating systems and dashboard modules, with door panel and headliner segments showing greater fragmentation. Three archetypes dominate: integrated seating specialists with captive foam production, diversified module suppliers spanning multiple trim categories, and region-focused fabricators serving single-country assembly corridors. Consolidation pressures are intensifying through strategic partnerships for bio-based material qualification and geographic expansion into India's PLI-subsidized manufacturing zones.
Within the integrated seating tier, Lear Corporation and Adient exemplify archetypes built around backward integration into sustainable foam technologies and just-in-sequence delivery systems. Yanfeng Automotive Interiors occupies a position representing manufacturing scale advantages across Asia-Pacific assembly corridors. These three entities anchor competitive positioning through divergent strategic emphases: Lear Corporation through upstream control over sustainable material portfolios, Adient through global footprint density, and Yanfeng through proximity to Chinese electric vehicle platform development.
| Leading Market Players |
|---|
| Lear Corporation |
| Adient |
| Faurecia |
| Grupo Antolin |
| Magna International |
| Draexlmaier Group |
| Yanfeng Automotive Interiors |
| Toyota Boshoku Corporation |
| International Automotive Components |
| Others |
Supply Flow & Price Mechanics
Algae-derived polyurethane foam qualification across German and United States seating plants compresses the cost premium between bio-based and petroleum-derived cushioning substrates while simultaneously concentrating supply among Tier 1 suppliers with validated sustainable material portfolios.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies interior trim procurement by certification grade and volume scale. Price differentiation separates REACH-compliant bio-based substrates from conventional petroleum-derived compounds, with fleet operators in Germany and the Netherlands exhibiting highest price sensitivity for base trim specifications. Cost compression in mass-market electric vehicle platforms intensifies as Chinese OEMs localize supply chains under MIIT emission standards. Luxury marques in Italy and Germany demonstrate lowest price sensitivity, absorbing premiums for full-grain leather and open-pore wood veneers.
Supply Chain Analysis
ECHA substance authorization and OEM-specific validation protocols function as certification gating mechanisms that extend qualification timelines for novel bio-based substrates. Supply concentrates in Germany, China, and Mexico, with German manufacturers anchoring precision-molded thermoplastic carrier production and Mexican assembly clusters specializing in door trim module operations. Raw material flows draw from petrochemical feedstocks, natural fiber cultivars in European agricultural zones, and algae biomass cultivation facilities in North America. Single-source vulnerability runs through certified tanning agent suppliers serving Italian and German luxury OEMs. Distribution runs through just-in-sequence delivery systems coordinated with vehicle assembly plant schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's interior air quality mandates compound regulatory pressure into sustained demand for certified bio-based materials across European automotive supply chains.
For Market Incumbents: Extend backward integration into sustainable foam technologies to capture premium seating contracts as electric vehicle OEMs expand cabin specifications. Defend margin position by retrofitting compression forming assets for temperature-sensitive natural fiber composites before legacy equipment obsolescence accelerates. Prioritize captive recycling infrastructure development to satisfy emerging extended producer responsibility frameworks in European markets. For New Entrants and Emerging Players: REACH substance restrictions in Europe open a window for specialized bio-based polymer suppliers to penetrate dashboard and cockpit applications facing compressed reformulation timelines. Target India's automotive PLI scheme for localized seating and door panel module investments serving compact hatchback production in Pune and Chennai. Lead with mechanical recycling capabilities for polymer-fiber laminates to satisfy ESG procurement criteria from fleet operators. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators serving single-country assembly corridors without validated sustainable material portfolios. Long-term viability hinges on certification density and simultaneous engineering capabilities for instrument panel development. Monitor algae-derived polyurethane foam production scale-up as inflection indicator for bio-based substrate cost parity achievement.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Material Portfolio Certification | ECHA REACH compliance creates certified-access advantages for validated sustainable foam suppliers serving BMW and Mercedes-Benz. |
| Acoustic-Thermal Headliner Integration | Multi-functional trim systems command premium positioning in electric vehicle platforms from Tesla and BYD. |
| Captive Recycling Infrastructure Buildout | Extended producer responsibility frameworks in Germany elevate compliance costs for conventional petroleum-based substrate manufacturers. |
| India PLI Manufacturing Footprint | Production-linked incentives create tariff advantages for seating suppliers establishing operations in Tamil Nadu belt. |
| Simultaneous Engineering Capability Investment | German OEMs demand concurrent development partnerships for dashboard carrier and human-machine interface integration. |
Methodological Framework
Bottom-up vehicle production modeling reconciled against top-down supplier capacity tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations executives combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings from listed suppliers, and ECHA substance authorization records. Triangulation across these sources ensures segmentation integrity across material type, vehicle architecture, and regional production cluster dimensions.
Input-output matrices map propulsion architecture transitions, content-per-vehicle trajectories, and OEM tier specifications against regional production volumes across the analysis window. Segmentation dimensions include material category, vehicle class, trim level tier, and component system integration depth. CAGRs derive from regression analysis of historical production data and scenario-weighted projections for electric vehicle penetration rates. Industry-specific inputs incorporate REACH substance restriction timelines and MIIT emission standard phase-in schedules.
Revisions become necessary when ECHA expands restricted substance lists, when major OEMs accelerate platform standardization timelines, or when bio-based polymer processing breakthroughs alter cost economics. A model refresh is warranted upon material change in EU Green Deal implementation intensity or Chinese electric vehicle subsidy structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
Global Automotive Rear Window Blinds Market
Automotive Interior & Exterior
Automotive Drawer Slides Market
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Impact-Modified PCR Plastics for Automotive Interiors Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
Reflective Air Bags Market
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Auto Internal Connector Market
Automotive Interior & Exterior
Automotive Roof Liners Market