
 Global Automotive Tinted Window Pane Market | 2026-2036
Global Automotive Tinted Window Pane Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Tinted Window Pane Market Intelligence
The EU Green Deal's focus on vehicle energy efficiency is hardening OEM requirements for components that reduce cabin heat gain. Eastman Chemical Company leverages its specialty materials portfolio to offer advanced ceramic film solutions. Saint-Gobain differentiates through integrated glazing systems that incorporate tinting at the point of glass manufacturing. Meanwhile, 3M competes with a strong brand presence and extensive distribution network in the aftermarket segment.
Automotive tinted window panes are glass or polymer film layers designed to reduce solar radiation entering a vehicle's cabin. Products are specified by Visible Light Transmission (VLT) and Total Solar Energy Rejected (TSER) ratings. Within product types, ceramic films are gaining share from dyed films due to superior heat rejection without electronic signal interference. Demand from OEMs for factory-installed solutions is outpacing growth in the traditional aftermarket installer channel.
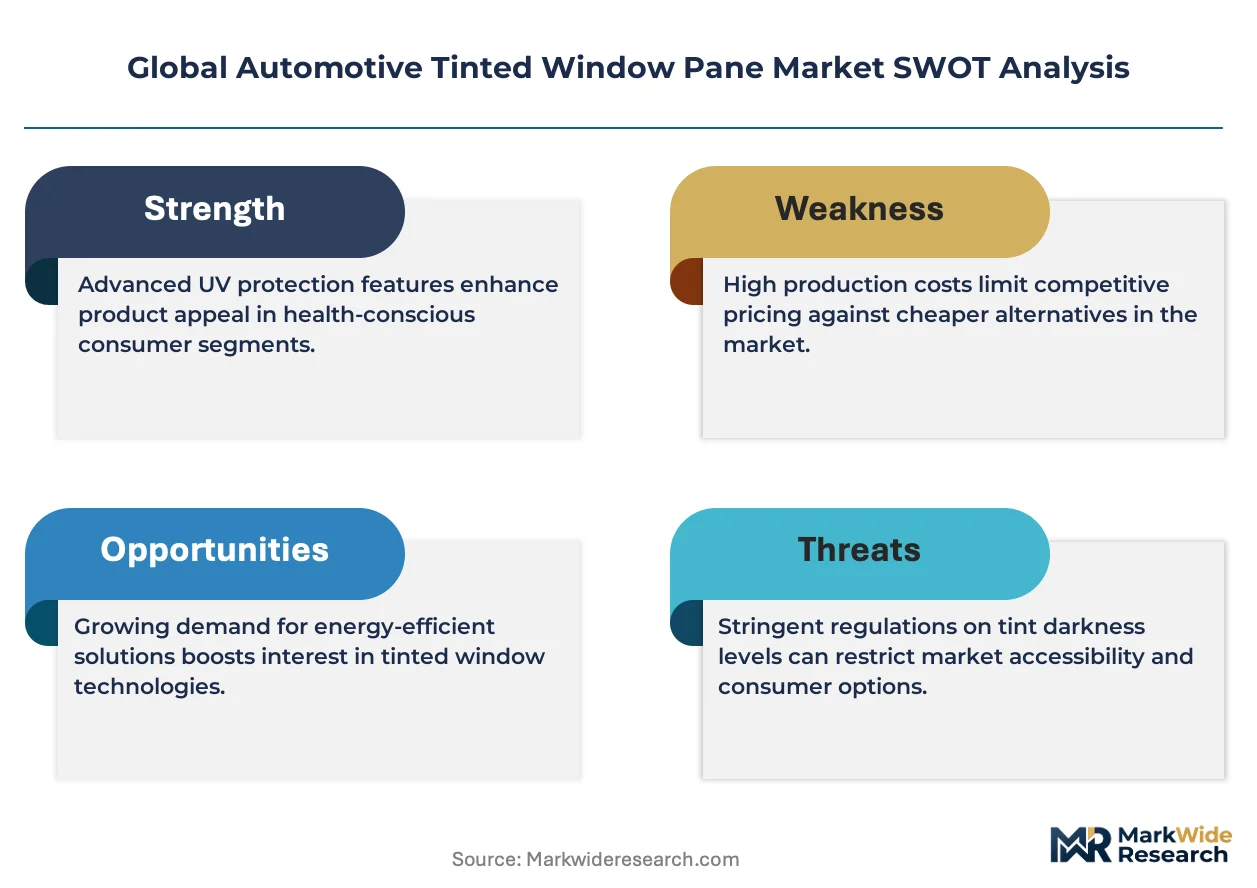
Regulatory frameworks established by bodies such as the US National Highway Traffic Safety Administration (NHTSA) and Germany's Kraftfahrt-Bundesamt (KBA) directly govern market access. These national regulations primarily define permissible Visible Light Transmission (VLT) levels for different windows, varying significantly by country. Stakeholders must now evaluate how to position their film-based products against the emerging threat and opportunity of electronically switchable glazing technologies.
Market Dynamics
The central force shaping the market is the reclassification of tinted panes from a cosmetic accessory to a performance-critical component, driven by OEM demand for improved thermal efficiency in electric vehicles and premium SUVs to extend range and reduce HVAC energy consumption.
Growth Catalysts
- Advanced Film Materials:The development of ceramic and hybrid films provides superior heat rejection and durability without the signal interference common in older metallic films, meeting demands from the EV sector for high-performance, non-disruptive components.
- Regulatory Efficiency Mandates:Frameworks like the EU Green Deal pressure automotive OEMs to improve overall vehicle energy efficiency, creating a direct pull for components like high-TSER window panes that reduce cabin heat gain and lower air conditioning loads.
- EV Manufacturing Scale:Rapid expansion of electric vehicle production, particularly in manufacturing hubs like China, creates concentrated, high-volume demand for factory-installed tinted glass solutions that contribute to battery range optimization.
Market Restraints
- Regulatory Fragmentation:Divergent national regulations on permissible Visible Light Transmission (VLT) levels, enforced by bodies like the NHTSA in the US and the KBA in Germany, create complexity and increase costs for manufacturers seeking to offer standardized products globally.
- Substitution from Smart Glass:The emergence of electronically switchable glazing, which offers variable tint on demand, presents a long-term substitution threat, particularly in the premium and luxury vehicle segments where the technology is first being introduced.
- Cost Barriers in Economy Segments:The higher material and application cost of advanced ceramic films compared to traditional dyed films limits their adoption in cost-sensitive, high-volume economy vehicle segments, slowing overall market penetration.
Strategic Opportunities
- Aftermarket Development in New Regions:Expanding branded installer networks in regions with a large and aging vehicle parc but historically low tinting penetration, such as in parts of Latin America and Southeast Asia, offers a significant volume opportunity.
- Films for Integrated Glazing:Developing specialized films designed for lamination within integrated glazing systems, rather than as a post-production application, aligns with OEM trends toward modular, pre-assembled components and creates a new B2B channel.
- Convergence with Sensor Technologies:Integrating transparent conductive films or other functional layers into tinting products can enable new applications like de-icing, HUD-compatibility, or antenna integration, creating value in the premium connected car segment.
Industry Challenges
- Navigating Compliance Labyrinths:Manufacturers face the operational burden of testing, certifying, and labeling products to comply with the disparate VLT and safety glazing standards across key automotive markets, delaying product launches and adding administrative overhead.
- Supply Chain Reorientation:The market's pivot from a fragmented aftermarket installer base to a concentrated OEM direct-supply model requires film manufacturers to develop new capabilities in just-in-time delivery, zero-defect quality control, and long-term contract management.
- Installer Skill Gaps:A shortage of technicians skilled in applying advanced, multi-layer films or servicing integrated smart glazing systems can create installation bottlenecks and impact end-user satisfaction, particularly in the aftermarket channel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Tinted Window Pane Market |
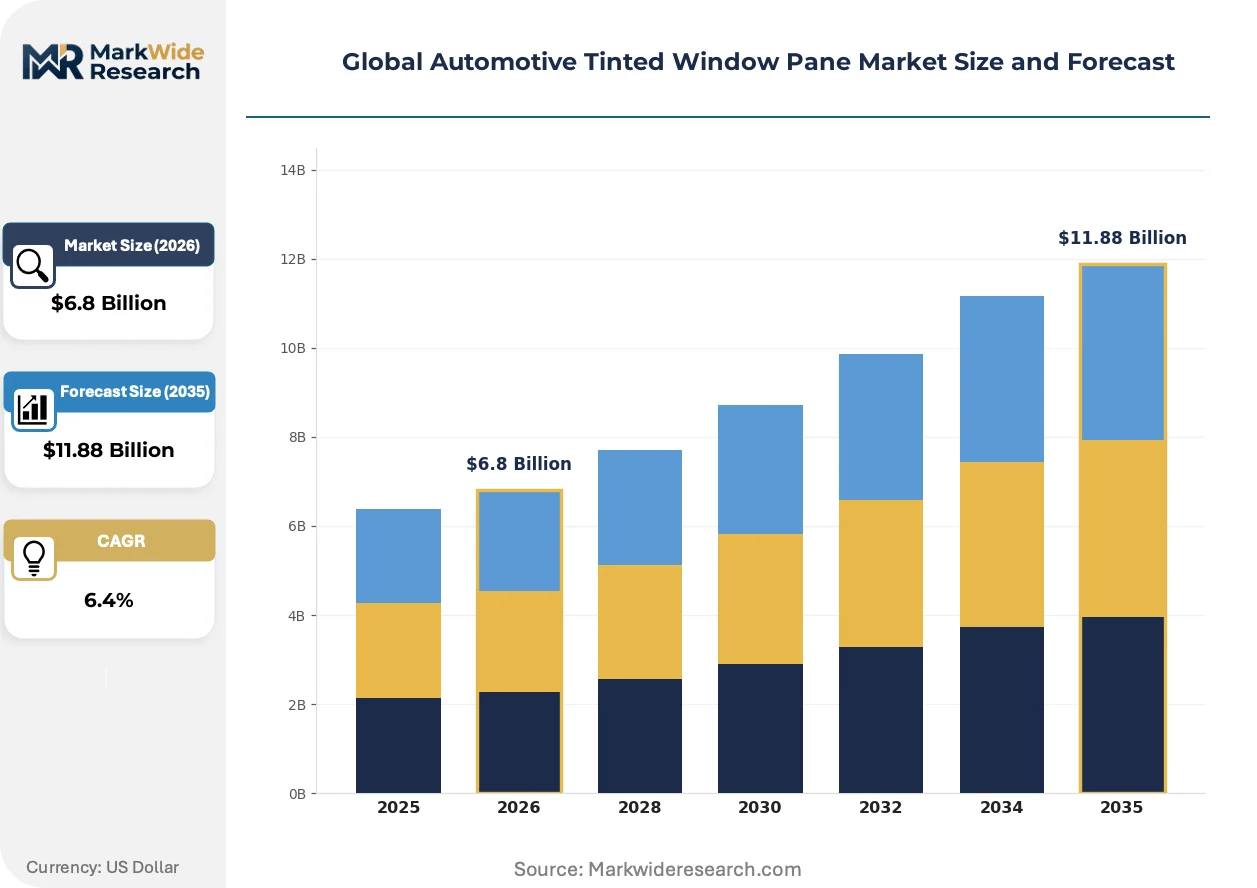
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyed Film, Metalized Film, Ceramic Film, Carbon Film, Hybrid Film Application: Passenger Cars, Commercial Vans, Pickups, SUVs, Specialty Vehicles Technology: Pressure-Sensitive, Heat-Activated, Pre-Tinted, Dyed, Metallized End User: OEMs, Vehicle Refurbishers, Aftermarket Installers, Fleet Operators |
| Companies Covered | Eastman Chemical Company, 3M, Saint-Gobain, AGC Inc., Nippon Sheet Glass Co., Ltd., PPG Industries, Inc., Fuyao Glass Industry Group Co., Ltd., Xinyi Glass Holdings Limited, Madico, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Tinted Window Pane Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental shift from aftermarket customization to OEM-integrated performance enhancement. This transition is driven by the technical demands of vehicle electrification and a stricter global focus on energy efficiency, elevating window tinting from an aesthetic choice to an engineering specification.
Advanced ceramic films offer superior total solar energy rejection without interfering with the radio, GPS, or cellular signals essential for modern connected vehicles. Automotive OEMs are rapidly adopting this technology, especially for their flagship electric vehicle and premium SUV lines. This performance advantage is consolidating the market for high-TSER films around ceramic-based technologies, pushing aside older dyed and metallic film chemistries in new vehicle specifications.
Mandates within the EU Green Deal are intensifying OEM requirements for components that contribute to vehicle efficiency. This regulatory pressure forces manufacturers to evaluate the thermal performance of all cabin materials, including glass, to minimize HVAC energy draw. Consequently, the premium vehicle segment is increasingly specifying high-performance tinting with documented TSER ratings as a standard feature, not an optional extra.
Original Equipment Manufacturers are increasingly sourcing tinted panes as a factory-installed component, bypassing traditional sales channels. This procurement pattern disrupts the fragmented aftermarket installer network that historically dominated product distribution, favoring direct supply relationships with Tier 1 glass producers or film manufacturers. The trend is most pronounced in major automotive production centers like Germany and China, where new EV platforms are designed with integrated thermal management solutions from inception.
Global Automotive Tinted Window Pane Market Segmentation
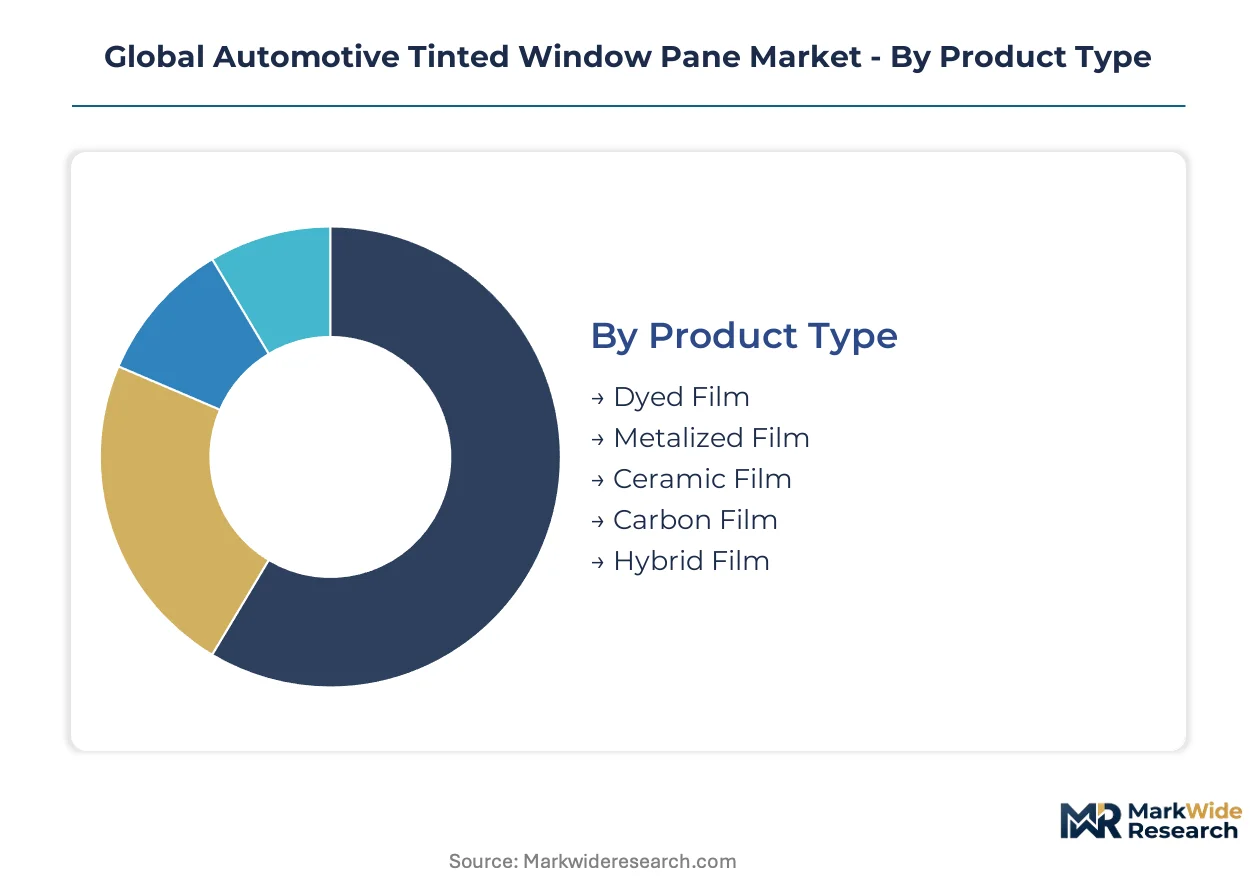
The automotive tinted window pane market categorizes products and applications based on critical performance attributes and end-user requirements. Understanding these distinctions is essential for manufacturers to tailor their material science innovations and distribution strategies, aligning with evolving OEM demands and regulatory shifts.
Product Type:
Buyers in this category differentiate products primarily by their optical clarity, thermal rejection capabilities, and durability. Performance characteristics like Total Solar Energy Rejected (TSER) and Visible Light Transmission (VLT) drive material selection in specific vehicle segments.
- Dyed Film:This film type incorporates dye in its adhesive or polyester layers, offering basic solar heat rejection and aesthetic darkening at a lower cost point. Economy vehicle segments in emerging markets like India still utilize dyed films for basic customization.
- Metalized Film:These films embed microscopic metal particles to reflect solar energy, providing good heat rejection but often interfering with electronic signals. Aftermarket installers in regions with less stringent signal interference concerns, such as parts of Southeast Asia, continue to offer metalized options.
- Ceramic Film:Composed of non-conductive ceramic nanoparticles, this film offers superior heat rejection and UV protection without electronic signal interference. Electric vehicle manufacturers in Germany and China increasingly specify ceramic films for factory-installed solutions to optimize battery range.
- Carbon Film:Utilizing carbon particles, this film provides a matte finish, good heat rejection, and blocks infrared radiation without signal disruption. Premium SUV owners in the United States often choose carbon films for their aesthetic appeal and performance balance.
- Hybrid Film:Combining dyed and metalized layers, hybrid films offer a balance of heat rejection, glare reduction, and reduced signal interference compared to purely metalized options. Traditional passenger car segments in Europe frequently adopt hybrid films for cost-effective performance upgrades.
Ceramic Film leads volumes today; Hybrid Film is gaining share fastest.
Application:
The application segment distinguishes market demand by vehicle type, reflecting varying requirements for passenger comfort, cargo protection, and regulatory compliance. Each vehicle category presents unique challenges for tinting solutions, from large glass areas to specific safety standards.
- Passenger Cars:This segment encompasses standard sedans and hatchbacks, representing the largest volume demand for tinted windows due to widespread ownership. Demand from new car buyers in Japan focuses on UV protection and glare reduction for daily commutes.
- Commercial Vans:Tinting in commercial vans primarily serves to protect cargo from theft and reduce cabin heat for drivers, enhancing operational efficiency. Fleet operators in the United Kingdom prioritize durability and cost-effectiveness for their vehicle modifications.
- Pickups:Pickup trucks utilize tinted windows for driver comfort, privacy, and to shield cabin interiors from intense solar radiation, especially in warmer climates. Owners in Australia often seek robust films that can withstand harsh environmental conditions.
- SUVs:The SUV segment drives demand for high-performance tinted windows, particularly for premium models seeking enhanced thermal efficiency and passenger comfort. OEMs in South Korea integrate advanced tinting into luxury SUV lines to extend range and reduce HVAC load.
- Specialty Vehicles:This category includes emergency vehicles, limousines, and custom builds, where tinting provides specific security, privacy, or aesthetic functions. Armored vehicle manufacturers in the UAE require specialized films for ballistic protection and solar control.
Demand from Passenger Cars remains strong, while SUVs exhibits significant expansion.
Technology:
The technological differences in tinted window panes primarily relate to their manufacturing process and installation method, influencing performance characteristics and integration capabilities. These technologies cater to distinct market needs, from aftermarket flexibility to factory integration.
- Pressure-Sensitive:These films feature an adhesive layer that activates upon pressure, allowing for easier aftermarket application and repositioning during installation. Aftermarket installers in Brazil favor pressure-sensitive films for their user-friendliness and broad compatibility.
- Heat-Activated:Heat-activated films require heat for the adhesive to bond, offering a strong, durable attachment once cured. Specialized installers for high-end vehicles in France use heat-activated films for a more permanent and secure application.
- Pre-Tinted:This technology involves tinting the glass during the manufacturing process, either by incorporating dyes or applying a coating before lamination. Automotive OEMs in China integrate pre-tinted glass into new EV platforms from the design phase.
- Dyed:Dyed technology involves coloring the film material itself, providing a uniform tint throughout the material. This traditional method remains cost-effective for basic aesthetic applications in various global markets.
- Metallized:Metallized technology involves depositing a thin layer of metal onto the film, which reflects solar energy and provides excellent heat rejection. Some older vehicle models in the United States still utilize metallized films for their proven thermal performance.
The shift towards Pre-Tinted reflects OEM preferences for integrated solutions.
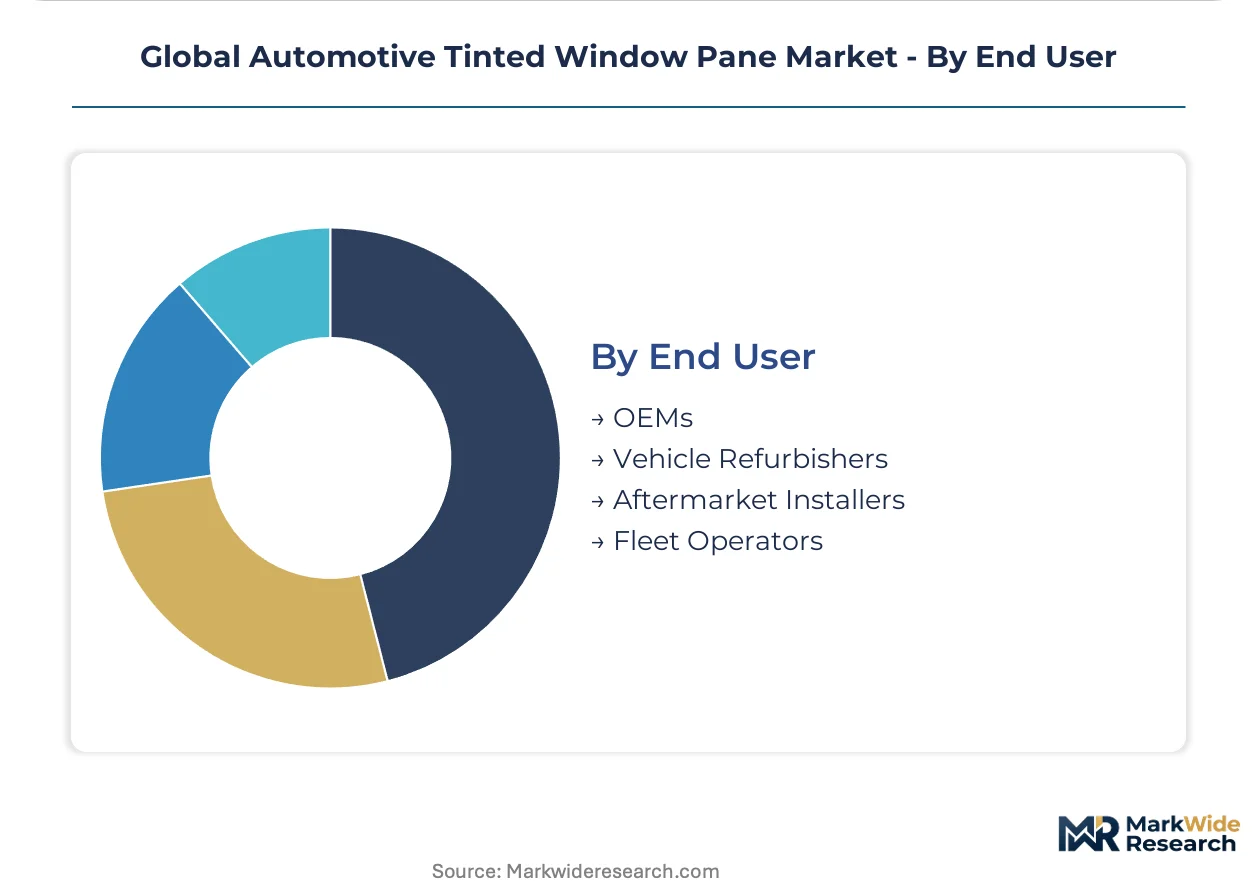
End User:
End-user segmentation highlights the distinct procurement channels and decision-making processes within the market, from large-scale factory integration to individual vehicle customization. Each end-user group has specific criteria for product selection and service delivery.
- OEMs:Original Equipment Manufacturers integrate tinted glass directly into new vehicle production lines, prioritizing performance, quality, and supply chain reliability. German automotive manufacturers demand high-TSER films for their premium electric vehicle models.
- Vehicle Refurbishers:These entities specialize in restoring or upgrading used vehicles, often replacing or adding tinting as part of a comprehensive overhaul. Refurbishment centers in the United Kingdom source films that match existing vehicle specifications or offer aesthetic upgrades.
- Aftermarket Installers:This segment comprises independent businesses that apply tinting films to vehicles post-sale, catering to individual consumer preferences for aesthetics, privacy, and heat reduction. Small businesses in Mexico serve a broad customer base seeking customized tinting solutions.
- Fleet Operators:Companies managing large vehicle fleets, such as logistics or taxi services, procure tinted windows to improve driver comfort, protect cargo, and enhance fuel efficiency. Logistics companies in Canada invest in tinting to reduce HVAC load and operating costs.
OEMs now dictate product specifications, influencing the entire value chain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive tinted window pane market initially developed to provide aesthetic customization and basic solar control for vehicle owners. This industry segment scaled significantly with the rise of mass-produced automobiles, particularly in regions with strong automotive manufacturing bases. Early innovations focused on dyed and metallized film technologies to meet consumer demand.
China
China's rapid electric vehicle manufacturing scale drives demand for factory-installed tinted glass solutions. The country's dual carbon goals pressure OEMs to optimize vehicle energy efficiency, promoting high-TSER window panes. EV production hubs in the Yangtze River Delta integrate advanced tinting into new platforms from inception.
Germany
German automotive manufacturers prioritize high-performance tinted windows for premium electric vehicle models. The EU Green Deal's focus on vehicle energy efficiency hardens OEM requirements for thermal management components. Automotive clusters in Bavaria, including Munich and Ingolstadt, lead in specifying advanced ceramic films for battery range optimization.
United States
United States consumers, particularly premium SUV owners, seek carbon films for aesthetic appeal and performance balance. National Highway Traffic Safety Administration (NHTSA) regulations define permissible Visible Light Transmission (VLT) levels for vehicle windows. The Detroit automotive manufacturing region drives demand for OEM-specified tinting in new vehicle designs.
Japan
Japanese new car buyers focus on UV protection and glare reduction for daily commutes. The Ministry of Economy, Trade and Industry (METI) promotes energy efficiency standards for automotive components. Major automotive production facilities in the Kanto region integrate advanced tinting solutions into passenger car lines.
South Korea
South Korean OEMs integrate advanced tinting into luxury SUV lines to extend range and reduce HVAC load. The Ministry of Food and Drug Safety (MFDS) oversees general product safety, indirectly influencing automotive component standards. Manufacturing hubs in the Seoul Capital Area increasingly specify high-TSER films as a standard feature for premium vehicles.
Global Automotive Tinted Window Pane Market Key Industry Players
Premium-margin players sit above commodity-margin players across the automotive integration dimension. The market exhibits a tiered structure, with established chemical and glass manufacturers dominating OEM supply for advanced solutions. Specialized film producers and a fragmented network of aftermarket installers operate in segments driven by cost or customization. Strategic archetypes include material science innovators, integrated glazing system providers, and extensive aftermarket distributors. Portfolio diversification into high-performance films and strategic partnerships with OEMs are dominant competitive moves.
Among established material science innovators, Eastman Chemical Company exemplifies a focus on advanced ceramic film solutions, leveraging its specialty materials portfolio. Saint-Gobain, a French-based industrial group, occupies a position as an integrated glazing systems provider, incorporating tinting at the point of glass manufacturing for OEM clients. Meanwhile, 3M, a diversified American multinational conglomerate, anchors a significant presence in the aftermarket segment through its strong brand and extensive global distribution network. These companies represent distinct strategic approaches within the automotive tinted window pane market, catering to different procurement channels and performance requirements.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| 3M |
| Saint-Gobain |
| AGC Inc. |
| Nippon Sheet Glass Co., Ltd. |
| PPG Industries, Inc. |
| Fuyao Glass Industry Group Co., Ltd. |
| Xinyi Glass Holdings Limited |
| Madico, Inc. |
| Others |
Cost & Logistics Intelligence
Polyester film resin prices, a primary input for advanced tinted window films, cascade through the supply chain, influencing the final pricing tiers for both OEM and aftermarket segments. This material cost variability directly impacts manufacturer margins and product differentiation strategies.
Pricing Analysis
Contract-based long-term offtake agreements define pricing for Original Equipment Manufacturers, prioritizing reliability and certified performance over spot market fluctuations. Price differentiation stems from film technology (ceramic vs. dyed), Total Solar Energy Rejected (TSER) ratings, and volume scale in OEM orders. Pricing softness stems from intense competition in the aftermarket segment, particularly for basic dyed and metalized films. Economy vehicle segments in emerging markets exhibit the highest price sensitivity, while premium EV manufacturers prioritize performance and are less price-constrained.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks facilitate the movement of raw materials and finished films to automotive manufacturing clusters. The global supply chain concentrates in major automotive production hubs like China, Germany, and Japan, which also host key film and glass manufacturers. The industry relies on specialized polyester film, ceramic nanoparticles, and chemical additives. Single-source vulnerability for certain advanced film chemistries represents a structural risk. Distribution runs through direct OEM supply for integrated solutions and fragmented aftermarket installer networks for post-sale customization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage opportunity, leveraging the cost efficiencies of certain production regions against the high-performance demand driven by EU Green Deal energy efficiency mandates.
For Market Incumbents: Hedge against the long-term threat of smart glass substitution by actively investing in next-generation switchable film R&D. Consolidate market share in the OEM channel through strategic partnerships with Tier 1 glass manufacturers, offering integrated glazing solutions. Deepen vertical integration into specialized film material production to control input costs and ensure supply reliability for high-TSER ceramic films.
For New Entrants and Emerging Players: Aftermarket installer networks in regions like Latin America and Southeast Asia present a white-space opportunity for branded film products. Target the growing premium SUV and EV aftermarket segments in these underpenetrated geographies with high-performance carbon and hybrid films. Develop go-to-market strategies that emphasize installer training and certification to build brand trust and differentiate from commodity offerings.
For Investors and Strategic Acquirers: Asymmetric upside sits with material science innovators specializing in advanced film technologies that enhance thermal management and reduce electronic interference. The long-term viability of the market is anchored in the shift from cosmetic accessory to performance-critical component. A signal to watch is the increasing OEM specification of high-TSER films as standard equipment in new EV platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Ceramic Film Production Capacity | This move supports OEM demand for high-performance, non-interfering thermal management solutions in electric vehicles. |
| OEM Joint Development Programs | Partnerships with automakers align film innovation with future vehicle platform requirements and secure long-term supply contracts. |
| Consolidate Aftermarket Installer Networks | This strategy enhances brand presence and service quality in fragmented regions, capturing volume from aging vehicle parcs. |
| Invest in Integrated Glazing Solutions | Developing films for lamination within glass manufacturing aligns with OEM trends toward modular, pre-assembled vehicle components. |
| R&D into Next-Gen Switchable Films | This innovation positions companies to compete with emerging smart glass technologies, offering variable tint functionality. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming a robust data collection framework. Primary insights came from OEM procurement leads, Tier 1 glass manufacturers, film material scientists, and aftermarket installation business owners. Secondary validation drew from automotive production databases, regulatory body publications from NHTSA and KBA, trade association reports, and company financial filings. This approach facilitated both bottom-up market sizing and top-down trend analysis.
The forecast window was anchored to historical reference periods, with projections extending across the analysis window using an integrated analytical framework. Segmentation dimensions modeled included product type, application, technology, end-user, and key regional automotive clusters. Compound annual growth rates were derived from an assessment of historical trends and projected growth drivers, with specific inputs from global EV production forecasts and regulatory efficiency targets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rapid regulatory shifts in VLT levels, raw material price volatility, and the pace of smart glass adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Global Light Vehicle (LV) Cabin AC Filters Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Africa and Middle East Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market