
 China Electric Power Steering Market | 2026-2036
China Electric Power Steering Market Size, Share, and Industry Trends Forecast 2026-2036
China Electric Power Steering Market Outlook
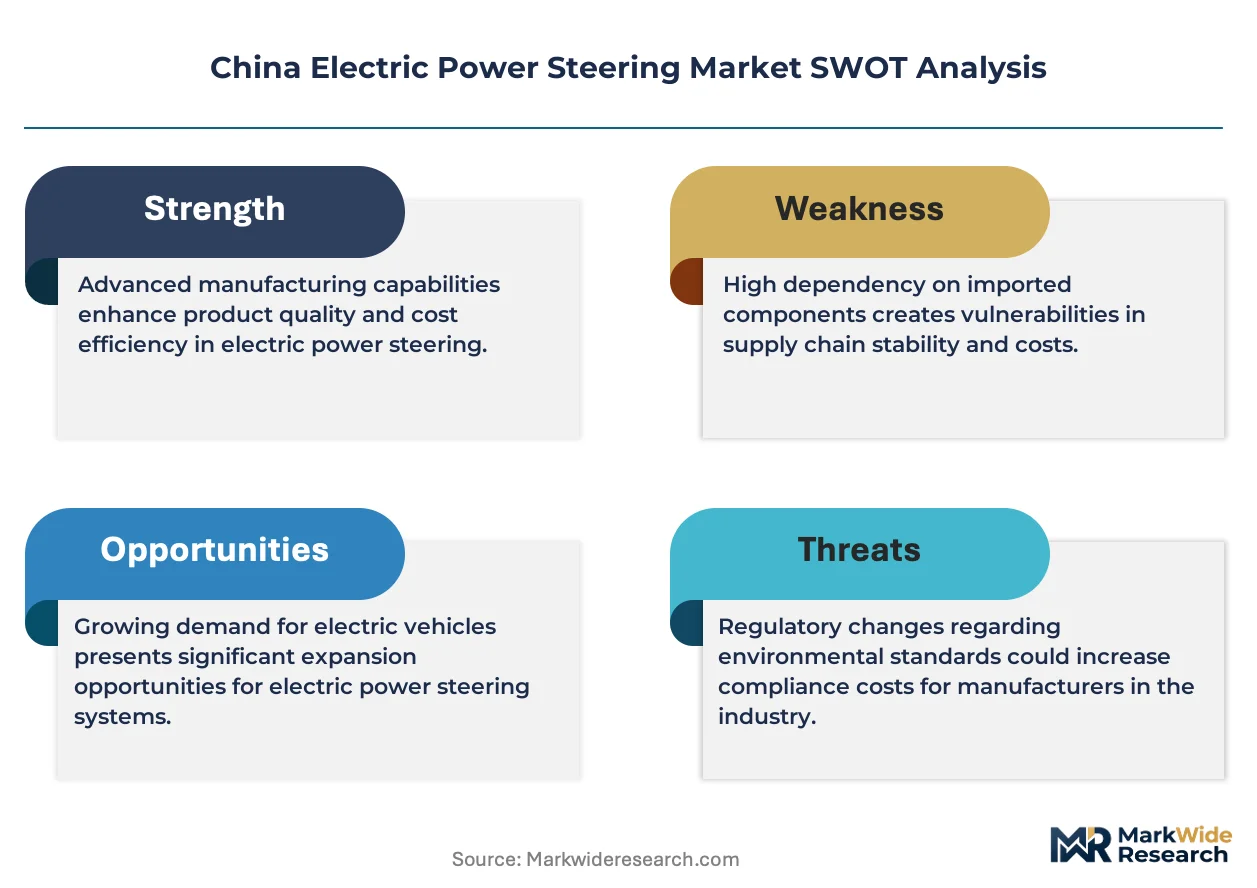
MIIT's updated fuel-consumption standards for passenger vehicles is realigning supplier qualification thresholds across the China Electric Power Steering Market. Robert Bosch GmbH leverages its integrated motor-control architecture to sustain premium positioning among domestic OEMs. Denso Corporation anchors its competitiveness through high-volume production of brushless DC motor assemblies for compact passenger vehicles. JTEKT Corporation specializes in torque-sensor calibration protocols that differentiate its rack-assist systems in technical bidding processes.
Electric power steering replaces hydraulic assist with an electric motor mounted on the steering column, rack, or pinion, drawing power from the vehicle's electrical system rather than a belt-driven hydraulic pump and typically operating at 12V or 48V depending on vehicle architecture. Its primary purpose is to reduce fuel consumption by eliminating parasitic engine load while enabling advanced driver-assistance features such as lane-keeping and automated parking. Rack assist configurations dominate commercial vehicle applications due to higher load-bearing requirements, whereas column assist systems lead in compact passenger vehicles where packaging space and cost sensitivity shape procurement decisions. The electric vehicle end-user segment commands disproportionate R&D attention because native high-voltage architectures allow 48V and above implementations that hydraulic systems cannot match.
SAMR enforces GB standards for automotive electrical safety that directly affect EPS motor insulation and electromagnetic compatibility testing protocols. CEA grid-interconnection rules for charging infrastructure indirectly steer NEV platform electrification strategies that encompass steering-system voltage upgrades. The country's dual carbon goals cascade through MIIT production quotas, compelling Tier-1 suppliers to certify carbon footprints in component sourcing. Stakeholders must monitor how GB standard revision cycles and provincial NEV subsidy taper schedules interact to reshape procurement timelines and supplier qualification windows.
Market Dynamics
MIIT fuel-efficiency mandates are compressing procurement timelines across China's automotive supply base, forcing steering-system suppliers to accelerate 48V architecture certification ahead of model-year platform deadlines.
Growth Catalysts
- Dual carbon goals:Beijing's 2030 carbon peak and 2060 neutrality targets cascade through MIIT production quotas, compelling automakers to eliminate belt-driven hydraulic pumps in favor of electric assist systems.
- NEV platform electrification:Native high-voltage architectures in battery electric vehicles enable 48V and above EPS implementations that hydraulic systems cannot match, creating exclusive demand for rack-assist configurations.
- Yangtze River Delta concentration:Manufacturing clusters spanning Shanghai, Jiangsu, and Zhejiang provinces provide integrated motor, sensor, and controller supply chains within 200-kilometer radii of major OEM assembly plants.
Market Restraints
- Rare earth magnet cost volatility:Neodymium-iron-boron permanent magnets constitute 15-20% of brushless DC motor material costs, with prices fluctuating on Chinese export quota announcements.
- GB standard revision cycles:SAMR electromagnetic compatibility testing protocol updates force redundant certification rounds, extending supplier qualification windows by 6-12 months.
- Hydraulic system residual demand:Heavy commercial vehicle segments retain hydraulic assist for extreme load-bearing requirements above 15 kN rack force, capping EPS penetration in long-haul trucking.
Strategic Opportunities
- Western China NEV expansion:Chongqing and Chengdu automotive hubs are scaling battery electric vehicle production, creating greenfield EPS procurement without incumbent hydraulic supplier relationships.
- Steer-by-wire convergence:Integration of EPS with autonomous driving architectures eliminates mechanical steering columns, enabling Tier-1 suppliers to capture value previously held by chassis manufacturers.
- Provincial NEV subsidy extensions:Zhejiang and Jiangsu municipal governments are prolongating purchase incentives through 2027, sustaining above-replacement demand for electric power steering in domestic brand vehicles.
Industry Challenges
- Torque-sensor calibration expertise scarcity:Precision drift compensation algorithms require embedded software engineers with automotive functional safety (ISO 26262) certification, a skill set concentrated at JTEKT and Bosch engineering centers.
- 48V insulation validation capex:Motor winding systems for high-voltage architectures require upgraded partial discharge testing equipment and cleanroom winding facilities, demanding 40-60 million RMB facility investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electric Power Steering Market |
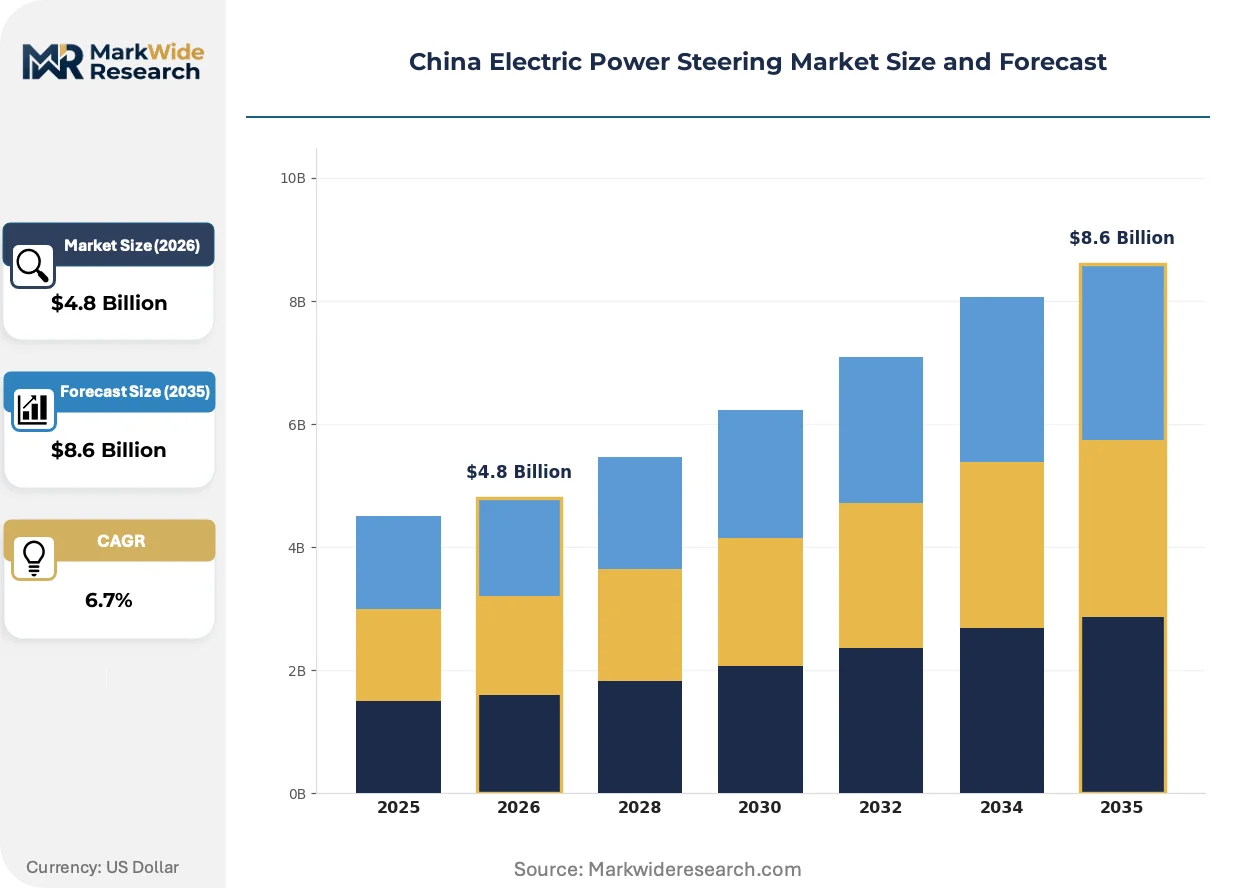
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Assist, Rack Assist, Pinion Assist, Mixed Assist End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles Technology: Brushless DC Motor, AC Motor, Torque Sensor, Electric Rack Distribution Channel: Online Sales, Direct Sales, Distributors, OEM |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, JTEKT Corporation, Hitachi Astemo Ltd., Hyundai Mobis, Nexteer Automotive, NSK Ltd., thyssenkrupp AG, ZF Friedrichshafen AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electric Power Steering Market Strategic Shifts
Steering-system electrification is converging with autonomous driving hardware roadmaps, compressing the traditional boundary between chassis mechanics and electronic control units. Three developments are reconfiguring competitive positioning.
Integrated motor-control architectures are consolidating discrete ECU, inverter, and motor housing into single-module designs. Domestic OEMs are adopting these consolidated units at accelerating pace to reduce wiring harness complexity and assembly labor. The consolidation is compressing Tier-2 component supplier margins while elevating system integrators with in-house motor manufacturing.
MIIT's updated passenger vehicle fuel-consumption standards are tightening corporate average fuel economy thresholds. The regulation forces automakers to count steering-system parasitic losses in fleet compliance calculations, accelerating hydraulic system phase-out in A-segment and B-segment vehicles. Suppliers are responding with 12V-to-48V voltage upgrade roadmaps aligned to NEV platform launches.
Automotive procurement departments are unbundling after-sales service contracts from initial system supply agreements. Fleet operators and ride-hailing platforms are demanding predictive maintenance telemetry separate from hardware procurement, disrupting the traditional bundled pricing model. This unbundling is most visible in Shenzhen and Hangzhou, where NEV taxi fleets exceed 50,000 vehicles per operator.
China Electric Power Steering Market Segmentation
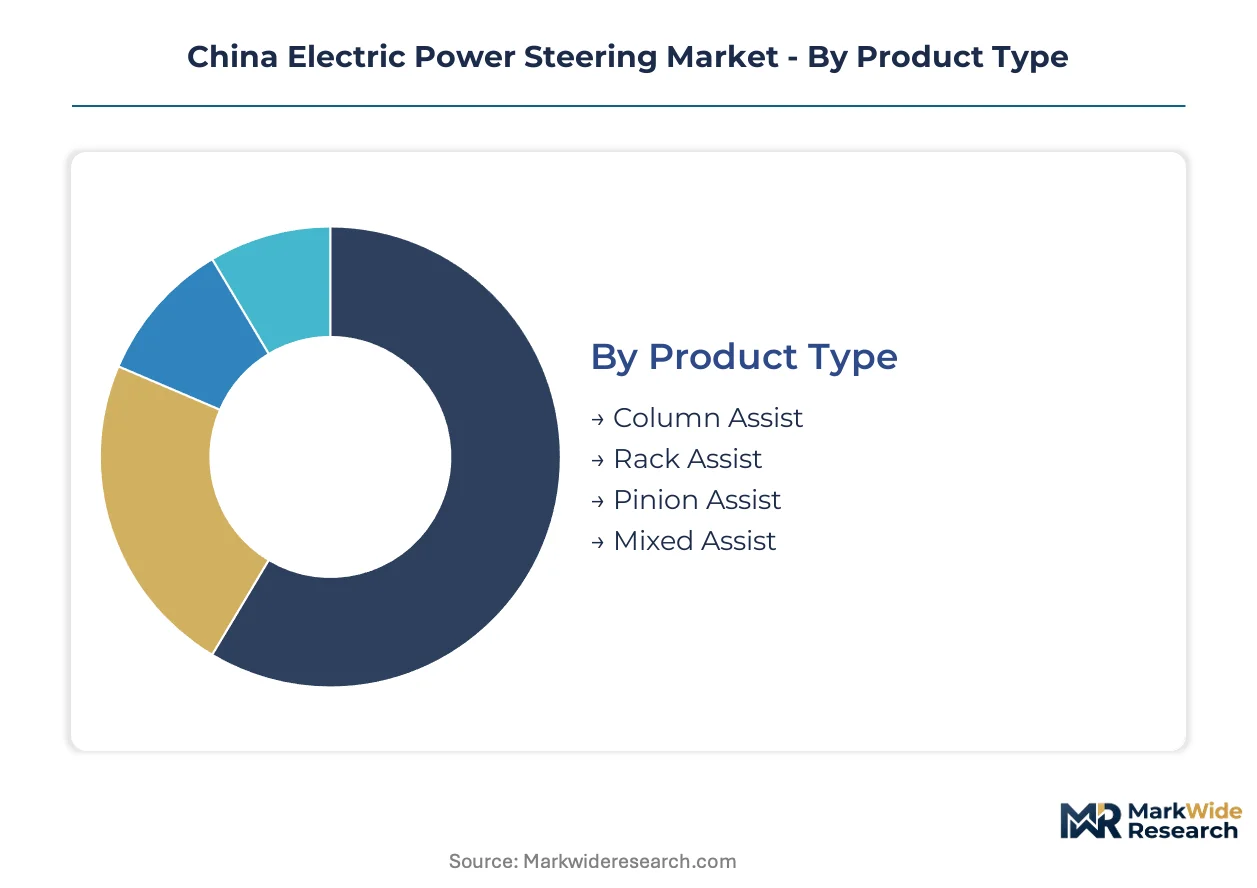
Segmentation in China's electric power steering market tracks how integration depth varies across vehicle platforms. Suppliers calibrate motor torque, sensor precision, and control algorithms differently depending on whether systems operate as standalone modules or embed within broader chassis electronics.
Product Type:
Standalone column-mounted systems serve cost-sensitive compact vehicles, while rack-integrated configurations embed deeper into chassis architectures for load-bearing applications.
- Column Assist:Electric motor mounts directly on the steering column, reducing assembly complexity and wiring harness length. Procurement concentrates among domestic OEMs producing A-segment passenger vehicles in the Yangtze River Delta, where packaging constraints and MIIT fuel-efficiency calculations favor lightweight implementations.
- Rack Assist:Motor integrates with the steering rack itself, delivering higher torque output for commercial vehicle platforms. Demand clusters in heavy-duty applications requiring rack forces above 12 kN, though neodymium magnet costs and 48V insulation requirements compress margins for suppliers lacking in-house motor winding capabilities.
- Pinion Assist:Motor drives the pinion gear directly, occupying a middle ground between column and rack integration.
- Mixed Assist:Hybrid configurations combine multiple assist points for specialized vehicle architectures.
Volume placements concentrate in Column Assist; the faster expansion belongs to Rack Assist.
End User:
Cost tiers separate mass-market passenger applications from premium electric vehicle platforms commanding higher per-unit system values.
- Passenger Vehicles:A-segment and B-segment sedans and SUVs generate baseline demand for 12V column-assist systems. Procurement timelines compress as MIIT corporate average fuel economy thresholds tighten, forcing automakers to eliminate hydraulic pumps across entire model lines.
- Electric Vehicles:Native high-voltage architectures enable 48V and above implementations unavailable to hydraulic competitors. Battery electric platforms in Shenzhen and Hangzhou taxi fleets demand predictive maintenance telemetry unbundled from hardware supply, reshaping supplier business models.
- Commercial Vehicles:Long-haul trucking retains hydraulic assist for extreme load requirements above 15 kN.
- Two-Wheelers:Emerging applications for electric scooters and motorcycles.
Passenger Vehicles anchor current placements; Electric Vehicles are gaining share fastest as NEV production quotas expand.
Technology:
Maturity gradients separate proven brushless DC architectures from emerging torque-sensor calibration protocols.
- Brushless DC Motor:Permanent magnet synchronous designs dominate production volumes, with neodymium-iron-boron magnets constituting 15-20% of material costs. Denso Corporation and domestic suppliers compete on winding automation and partial discharge testing capacity.
- Torque Sensor:Precision drift compensation algorithms require ISO 26262-certified embedded software engineers, a capability concentrated at JTEKT and Bosch engineering centers. MIIT electromagnetic compatibility testing under GB standards forces redundant certification rounds.
- AC Motor:Alternative motor architectures for specific voltage requirements.
- Electric Rack:Integrated rack-motor assemblies for compact packaging.
Brushless DC Motor commands current volume; Torque Sensor shows the steepest expansion trajectory as steer-by-wire architectures advance.
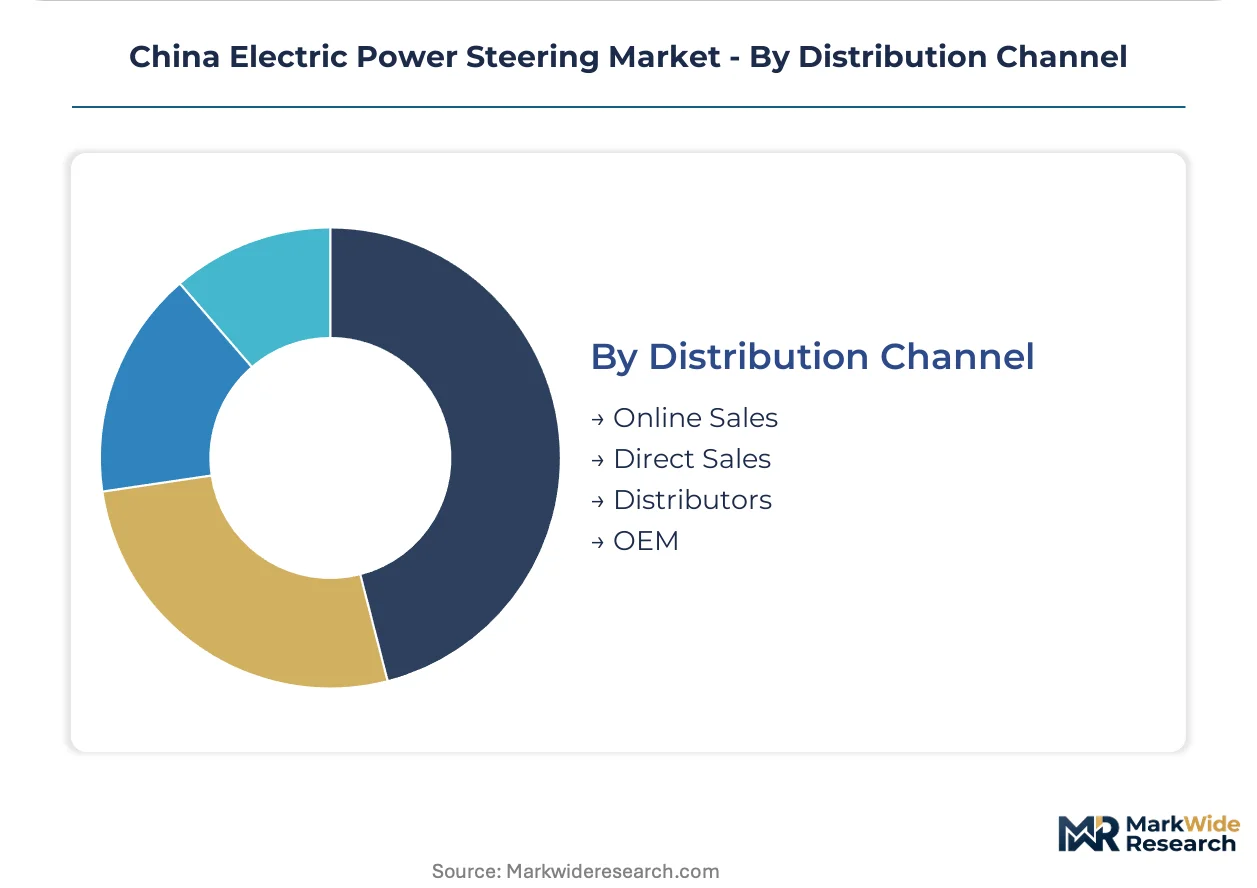
Distribution Channel:
Supply concentration in OEM direct procurement contrasts with fragmented aftermarket channels.
- OEM:Direct supply agreements with SAIC, BYD, Geely, and other domestic automakers lock in multi-year platform commitments. Tier-1 suppliers certify carbon footprints in component sourcing to satisfy MIIT production quotas tied to dual carbon goals.
- Distributors:Regional parts networks serve independent repair shops.
- Direct Sales:Limited to fleet operator contracts for NEV taxi and ride-hailing platforms.
- Online Sales:Emerging channel for replacement components.
OEM placements dominate absolute volume; Distributors show climbing growth as vehicle parc expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate EPS manufacturing through integrated motor and controller supply chains within 200-kilometer radii of major OEM assembly plants. Provincial governments in Jiangsu and Zhejiang extend NEV purchase incentives through 2027, sustaining procurement timelines for electric power steering systems.
Shanghai
SAIC Motor headquarters and Tesla Gigafactory Shanghai drive premium EPS demand for both domestic and export-bound electric vehicles. MIIT production quotas tied to dual carbon goals compel automakers to source certified low-carbon steering components. Pudong and Jiading districts host Tier-1 supplier engineering centers specializing in 48V motor-control integration.
Jiangsu
Nanjing and Changzhou automotive hubs scale battery electric vehicle platforms requiring rack-assist configurations above 12 kN. SAMR enforces GB standards for electromagnetic compatibility testing that extend supplier qualification windows. Suzhou Industrial Park concentrates brushless DC motor winding facilities serving BYD and Geely assembly lines.
Zhejiang
Geely Holding headquarters in Hangzhou anchors procurement for Lynk & Co and Zeekr premium electric brands. Provincial NEV subsidy extensions through 2027 sustain above-replacement demand for column-assist systems in A-segment vehicles. Ningbo port infrastructure facilitates neodymium magnet imports for permanent magnet synchronous motor production.
Sichuan-Chongqing
Changan Automobile and Seres expand battery electric production in Chongqing Liangjiang New Area, creating greenfield EPS procurement without incumbent hydraulic supplier relationships. Western China NEV expansion policies redirect supply chain investment inland. Chengdu Economic and Technological Development Zone attracts motor-controller manufacturers seeking lower labor costs than coastal provinces.
Guangdong
BYD headquarters in Shenzhen commands disproportionate R&D attention for 48V and above EPS implementations in native high-voltage architectures. CEA grid-interconnection rules for charging infrastructure indirectly steer platform electrification strategies encompassing steering-system voltage upgrades. Guangzhou and Shenzhen NEV taxi fleets exceeding 50,000 vehicles per operator demand predictive maintenance telemetry unbundled from hardware supply.
China Electric Power Steering Market Competitive Environment
German and Japanese producers anchor one tier; Chinese domestic specialists hold contract manufacturing positions for cost-sensitive compact vehicle platforms. The supplier base organizes around three strategic archetypes: integrated system architects with in-house motor manufacturing, component specialists focused on torque-sensor calibration, and scale-driven brushless DC motor assemblers. Competitive moves concentrate on 48V insulation validation capacity expansion and carbon footprint certification for MIIT quota compliance.
Among German-based fabricators, Robert Bosch GmbH and ZF Friedrichshafen AG occupy positions within the integrated system tier, while thyssenkrupp AG exemplifies the steel-to-chassis conglomerate archetype navigating electrification transitions. Japanese specialists Denso Corporation and JTEKT Corporation represent contrasting competitive positions: Denso anchors high-volume production capabilities, while JTEKT exemplifies precision sensor calibration expertise. Korean and Chinese players including Hyundai Mobis and Nexteer Automotive sit within the scale-driven contract supply segment serving domestic OEM platform commitments.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| JTEKT Corporation |
| Hitachi Astemo Ltd. |
| Hyundai Mobis |
| Nexteer Automotive |
| NSK Ltd. |
| thyssenkrupp AG |
| ZF Friedrichshafen AG |
| Others |
Value Chain & Pricing Dynamics
Captive motor-winding capabilities among Yangtze River Delta suppliers anchor both supply security and pricing power for Tier-1 integrators serving MIIT quota-compliant OEMs. The concentration of neodymium magnet processing in Ningbo and Suzhou creates tiered sourcing economics where in-house winding commands premium positioning against contract assemblers.
Pricing Analysis
Short-lead-time procurement for 48V rack-assist systems commands premium positioning against standard-timeline column-assist contracts. Pricing stratifies across premium, standard, and economy tiers based on ISO 26262 certification grade and after-sales telemetry bundling. Cost compression in economy-tier column systems is intensifying because domestic OEMs unbundle predictive maintenance from hardware supply. Fleet operators in Shenzhen and Hangzhou demonstrate lowest price sensitivity due to uptime-value calculations, while A-segment passenger OEMs in Jiangsu prioritize unit cost minimization.
Supply Chain Analysis
Remanufacturing flows for torque sensors and motor controllers are emerging through supplier-sponsored take-back programs targeting NEV taxi fleets. Primary manufacturing concentrates in China, Japan, and Germany, with neodymium-iron-boron magnets, silicon steel laminations, and automotive-grade microcontrollers constituting critical input dependencies. Single-source vulnerability sits with rare earth magnet supply from Chinese export quota-controlled processors. Distribution runs through OEM direct procurement agreements with multi-year platform lock-ins, supplemented by authorized distributor networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China Electric Power Steering Market occupies a technology-transition phase where 48V rack-assist architectures displace 12V column systems and hydraulic legacy across NEV platforms.
For Market Incumbents: Deploy carbon footprint certification as a qualification lever to secure MIIT production quota-aligned OEM contracts. Accelerate partial discharge testing capacity expansion in Jiangsu and Zhejiang facilities to defend against emerging domestic challengers with greenfield 48V insulation validation. Lock in multi-year neodymium magnet offtake agreements before export quota volatility escalates input costs. For New Entrants and Emerging Players: Begin with Chongqing and Chengdu automotive hubs where greenfield EPS procurement lacks incumbent hydraulic supplier relationships. Target western China NEV expansion corridors for rack-assist system penetration in heavy-duty battery electric commercial vehicles. Pursue fleet operator direct sales channels in Shenzhen and Hangzhou where predictive maintenance telemetry unbundling creates service-revenue attach opportunities. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated Tier-1 suppliers seeking torque-sensor calibration expertise and ISO 26262-certified engineering teams. Long-term viability favors specialists with captive motor-winding capabilities and SAMR GB standards pre-certification. Monitor MIIT fuel-efficiency mandate revision cycles and provincial NEV subsidy taper schedules as inflection indicators for procurement timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| 48V Architecture Certification | MIIT fuel-efficiency mandates force voltage upgrades across A-segment and B-segment vehicle platforms. |
| Carbon Footprint Certification | Dual carbon goals cascade through production quotas requiring Tier-1 supplier component sourcing documentation. |
| Neodymium Magnet Supply Agreement | Rare earth export quota volatility necessitates long-term offtake security for brushless DC motor cost stability. |
| Predictive Maintenance Telemetry Unbundling | Shenzhen and Hangzhou NEV taxi fleets demand service contracts separate from hardware procurement. |
| Western China Manufacturing Footprint | Chongqing Liangjiang New Area and Chengdu development zones offer greenfield EPS procurement without hydraulic incumbents. |
Study Parameters
Document review covered MIIT regulatory filings, SAMR GB standard publications, and CEA grid-interconnection rules, complemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, and aftermarket distributor operations heads. Secondary sources included vehicle production databases, IHS Markit registration data, and customs records for neodymium magnet trade flows. Bottom-up segment sizing triangulated against top-down market value estimates.
Historical shipment trajectories cross-referenced against panel input from supplier engineering centers and OEM sourcing committees shaped the analytical framework. Segmentation modeled vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from curve-fitting approaches applied to technology substitution patterns and regulatory mandate compliance timelines.
Underlying measurement precision varies by segment; electric vehicle and rack-assist categories carry tighter precision than two-wheeler and pinion-assist estimates. Forecasts reflect assumptions regarding MIIT quota enforcement consistency and rare earth magnet supply continuity. Practitioners should monitor SAMR electromagnetic compatibility testing protocol updates and provincial NEV subsidy extension announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Alternator and Starter Motor Market
Automotive Electrical & Electronics
Asia Pacific Automotive Camera Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
Canada Automotive Electric Actuators Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Automotive Traction Inverters Market
Automotive Electrical & Electronics
Automotive Electronic Logging Device (ELD/E-Log) Market
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Motor Vehicle Sensor Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Automotive Immersion Cooling Dielectric Fluid Market
Automotive Electrical & Electronics
Europe Automotive Tpms Market
Automotive Electrical & Electronics
Automotive E-Compressor Market