
 In-Chassis Cooling Market | 2026-2036
In-Chassis Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
In-Chassis Cooling Market Outlook
Hyperscale data center operators are unwinding legacy air-cooling commitments as power densities per rack exceed thermal limits. CoolIT Systems leverages direct liquid cooling architectures to sustain performance at chip-level heat fluxes above 500W. Delta Electronics, Inc. anchors its position through captive manufacturing of pumps and cold plates across Taiwan and Mexico. Asetek Inc. dominates the sealed-loop all-in-one segment for enterprise server deployments.
In-chassis cooling encompasses thermal management systems integrated within enclosed equipment housings, employing liquid-cooled cold plates with copper micro-channel structures, aluminum heat exchangers, or forced-air impingement to maintain component temperatures below rated thresholds. Liquid cooling technology leads product-level margins as immersion and direct-to-chip architectures displace conventional air handlers in high-performance computing environments. Thermal conductive materials represent the fastest-growing product category, driven by gallium-based phase-change alloys and graphite-sheet interfaces replacing silicone greases in electric vehicle powertrains.
The EPA regulates fluorinated greenhouse gas emissions under Section 608 of the Clean Air Act, constraining refrigerant choices for hybrid cooling systems deployed in US infrastructure. EMA and REACH frameworks in Europe impose substance restrictions on thermal interface materials, compelling reformulation of conductive compounds. OEM procurement teams must monitor evolving efficiency mandates from the CEA in India and NMPA material-certification requirements in China as these jurisdictions expand domestic semiconductor and EV manufacturing capacity.
Market Dynamics
Power density thresholds in AI training clusters are forcing hyperscale operators to abandon air-cooled architectures entirely, rewriting procurement specifications and supplier qualification criteria across the compute infrastructure stack.
Growth Catalysts
- EU F-Gas Regulation phase-down:Tightening quotas on high-GWP refrigerants are accelerating capital redeployment toward liquid-cooled server designs in European data center construction.
- Electric vehicle powertrain thermal loads:Gallium-based phase-change alloys are displacing silicone greases in inverter and battery module interfaces, expanding addressable chassis volume.
- Direct-to-chip cooling architectures:Cold plate designs sustaining heat flux above 500W are penetrating high-performance computing deployments previously served by facility-scale chillers.
Market Restraints
- Copper micro-channel fabrication concentration:Precision machining capacity for cold plate substrates clusters in Taiwanese and German supplier bases, creating single-source vulnerability.
- REACH substance restrictions:ECHA classification of certain thermal interface compounds as substances of very high concern is forcing compound reformulation and qualification delays.
- Hybrid system refrigerant lock-in:EPA Section 608 compliance requirements constrain retrofit pathways for existing infrastructure, extending replacement cycles.
Strategic Opportunities
- India semiconductor manufacturing expansion:CEA efficiency mandates for domestic fab construction are creating first-mover advantage for liquid cooling system integrators.
- Two-phase immersion convergence:Dielectric fluid engineering advances are merging with direct liquid cooling expertise to enable rack-scale thermal uniformity.
- Aftermarket thermal material upgrade cycles:Graphite-sheet interface products are penetrating electric vehicle service channels as owners seek range recovery through improved heat rejection.
Industry Challenges
- Fluid chemistry certification timelines:NMPA material-certification requirements in China are extending product validation periods for gallium-alloy compounds.
- Legacy facility integration complexity:Retrofitting direct liquid cooling into existing raised-floor environments demands simultaneous reengineering of power distribution and leak detection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Chassis Cooling Market |
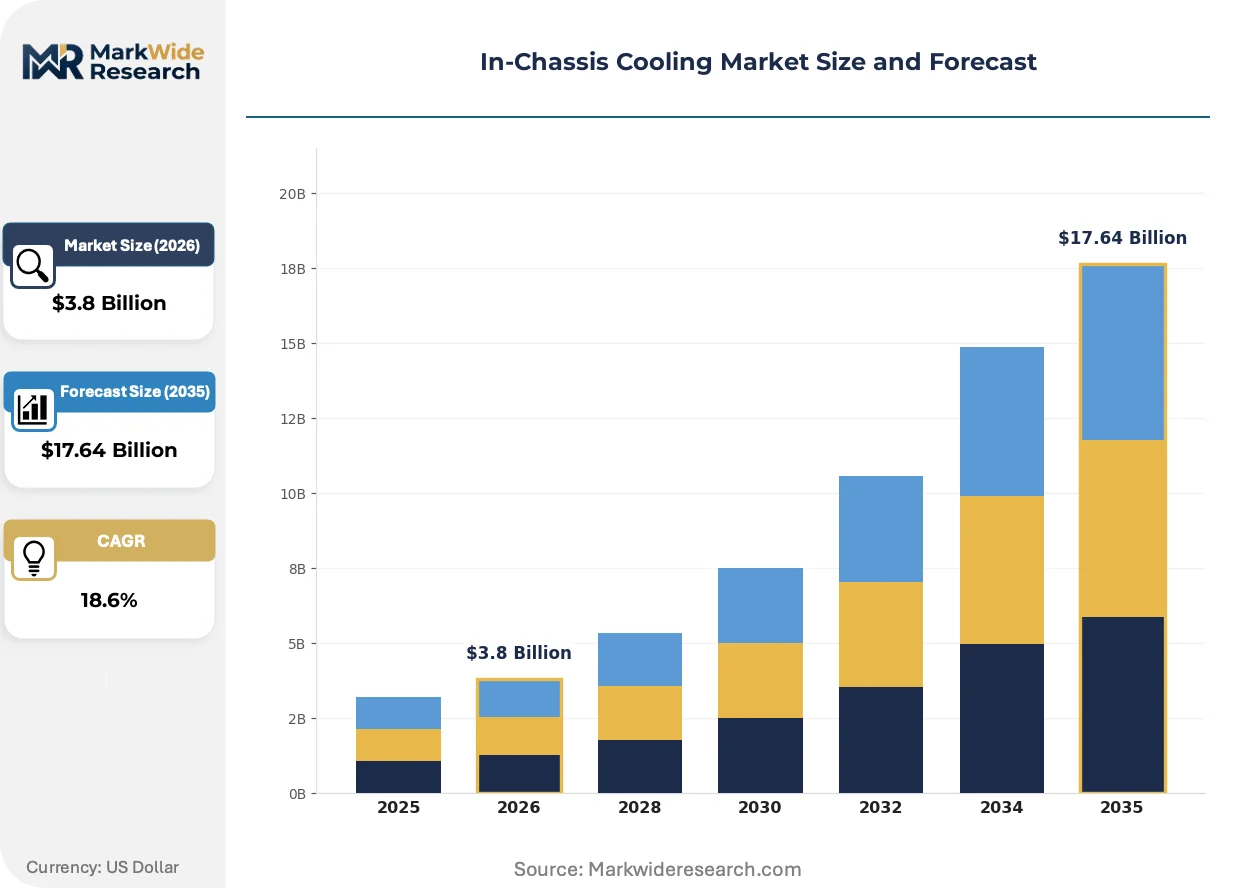
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Plates, Heat Exchangers, Thermal Conductive Materials, Fans Application: Automotive, Aerospace, Industrial Equipment, Railways End User: OEMs, Aftermarket Providers, Fleet Operators, Maintenance Providers Technology: Liquid Cooling, Air Cooling, Passive Cooling, Hybrid Cooling |
| Companies Covered | Asetek Inc., CoolIT Systems, Delta Electronics, Inc., Iceotope Technologies, Boyd Corporation, Fujitsu Ltd., Vertiv Holdings Co., Schneider Electric, LiquidStack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Chassis Cooling Market Strategic Shifts
Cooling architecture decisions are migrating upward from facilities engineering to chip design teams, collapsing traditional procurement boundaries between semiconductor and infrastructure suppliers.
Direct-to-chip cold plates with copper micro-channel structures are displacing conventional air handlers in AI training clusters. Hyperscale operators are mandating liquid cooling compatibility in all new server procurements. This shift is compressing the addressable market for facility-scale chillers while expanding captive pump and heat exchanger manufacturing.
REACH substance restrictions are compelling reformulation of thermal interface materials across European supply chains. Manufacturers are substituting gallium-based alloys for legacy silicone compounds to maintain conductivity compliance. Electric vehicle powertrain suppliers face the steepest qualification burden under ECHA registration deadlines.
Hyperscale procurement teams are unbundling thermal management from server OEM contracts to source directly from specialized cooling vendors. Direct vendor relationships are replacing tiered distribution in North American and German deployments. This channel restructuring concentrates specification authority with infrastructure engineering teams rather than commodity IT procurement functions.
In-Chassis Cooling Market Segmentation
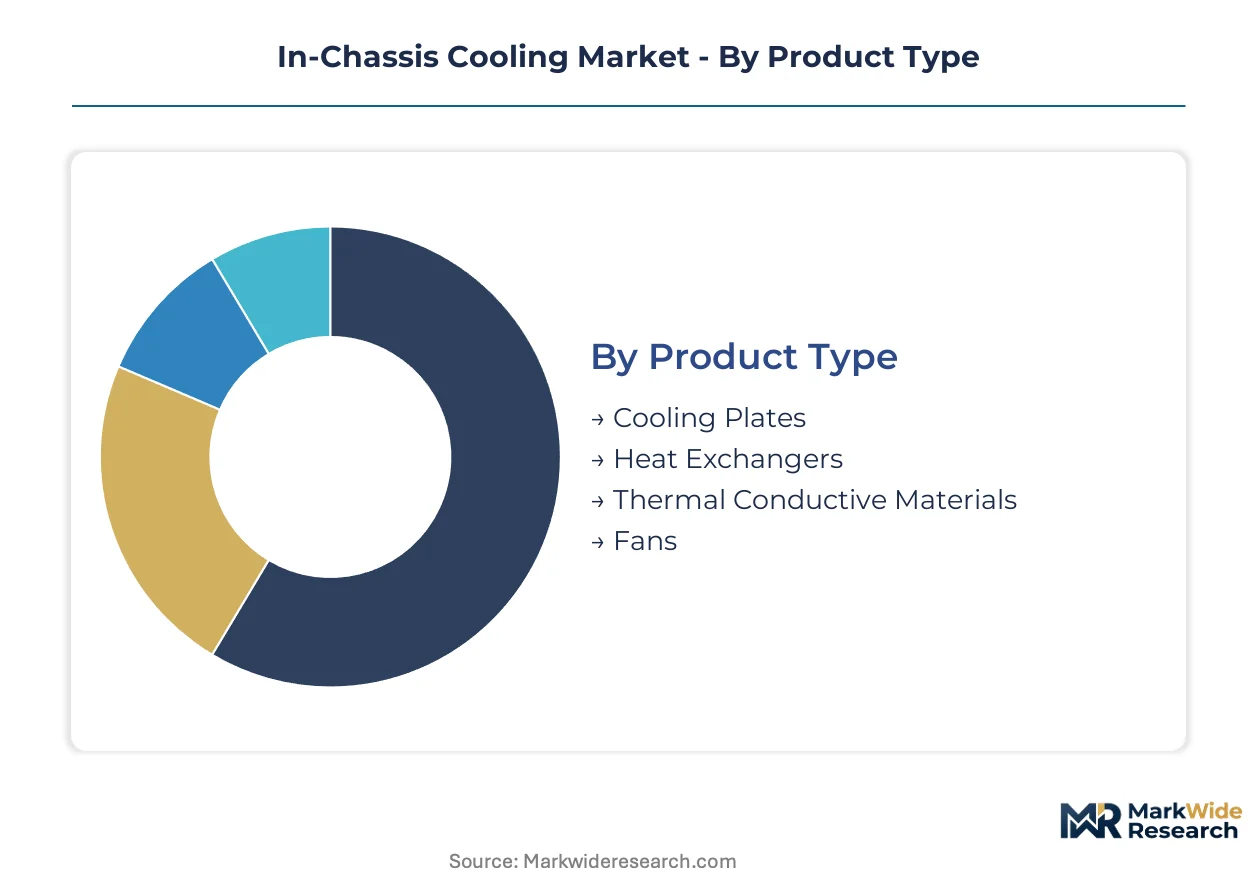
In-chassis cooling procurement splits along thermal performance thresholds and integration complexity. Product-level margins concentrate in liquid-cooled architectures, while technology choices determine qualification timelines and regulatory exposure across end-use verticals.
Product Type:
Margin pools concentrate in precision-machined cold plate substrates and advanced thermal interface compounds, where proprietary geometries and material chemistry create pricing power.
- Cooling Plates:Copper micro-channel structures dominate high-performance computing deployments, sustaining heat flux above 500W per chip. Hyperscale operators in Germany and the United States are mandating liquid-cooled server designs, compressing air-cooled procurement specifications.
- Thermal Conductive Materials:Gallium-based phase-change alloys and graphite-sheet interfaces displace silicone greases in electric vehicle powertrains. ECHA substance restrictions under REACH are forcing compound reformulation across European supply chains.
- Heat Exchangers:Aluminum-brazed designs serve facility-scale thermal rejection in hybrid cooling architectures.
- Fans:Forced-air impingement retains position in cost-optimized industrial equipment and legacy infrastructure.
Cooling plates hold installed capacity. Thermal conductive materials are rotating up the share rankings.
Application:
Volume concentrates in automotive electrification, where inverter and battery module thermal loads are expanding chassis-level cooling demand fastest.
- Automotive:Electric vehicle powertrains require gallium-alloy thermal interfaces and liquid-cooled cold plates for battery modules and inverters. NMPA material-certification requirements in China extend validation periods for gallium compounds entering domestic EV manufacturing.
- Industrial Equipment:Factory automation and robotics deployments employ hybrid cooling architectures balancing precision thermal control against total cost of ownership constraints.
- Aerospace:Dielectric fluid immersion and passive cooling architectures address altitude pressure variations and weight restrictions in avionics enclosures.
- Railways:Traction inverter cooling demands aluminum heat exchangers and forced-air systems for rolling stock power electronics.
Automotive claims the steepest expansion trajectory. Industrial equipment maintains baseline volume stability.
End User:
Procurement authority is migrating from commodity IT purchasing to infrastructure engineering teams, restructuring channel relationships across all user categories.
- OEMs:Original equipment manufacturers specify thermal architectures at the chassis design phase, integrating cooling plates and thermal materials into platform roadmaps. Captive manufacturing of pumps and cold plates anchors supplier relationships in Taiwan and Mexico.
- Aftermarket Providers:Service channels for electric vehicles are adopting graphite-sheet interface products as owners seek range recovery through improved heat rejection.
- Fleet Operators:Commercial vehicle and data center fleet managers demand standardized thermal architectures to simplify maintenance protocols.
- Maintenance Providers:Third-party service networks require backward compatibility with legacy air-cooled and hybrid systems.
OEMs control specification authority. Aftermarket providers are gaining share in thermal material replacement cycles.
Technology:
Technology selection determines capital intensity, operating expenditure profiles, and regulatory compliance pathways across deployment geographies.
- Liquid Cooling:Direct-to-chip and immersion architectures displace facility-scale chillers in AI training clusters. EU F-Gas Regulation phase-down accelerates capital redeployment toward liquid-cooled designs in European data center construction.
- Hybrid Cooling:Combined liquid-air systems bridge legacy infrastructure and next-generation thermal loads. EPA Section 608 compliance requirements constrain refrigerant choices and retrofit pathways for US infrastructure.
- Air Cooling:Conventional forced-air systems retain position in cost-sensitive and low-density compute environments.
- Passive Cooling:Heat sink and thermal mass architectures serve aerospace and remote deployment scenarios where active system maintenance is impractical.
Liquid cooling commands technology leadership. Hybrid cooling maintains transition market presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese precision machining clusters export cold plate substrates to German data center operators and US hyperscale facilities. German automotive OEMs source gallium-alloy thermal interfaces from Japanese material suppliers. Mexican manufacturing bases serve captive pump production for North American server deployments.
United States
Hyperscale operators in Northern Virginia and Phoenix are mandating liquid-cooled server designs for AI training clusters. EPA Section 608 constrains refrigerant choices for hybrid cooling retrofits in legacy facilities. Austin and Dallas-Fort Worth host expanding captive manufacturing of pumps and cold plates for domestic server OEMs.
Germany
Automotive electrification in Stuttgart and Munich drives demand for battery module thermal interfaces. EU F-Gas Regulation phase-down accelerates capital redeployment toward liquid-cooled designs in Frankfurt and Berlin data center construction. Bavarian precision engineering clusters supply copper micro-channel machining capacity to European HPC deployments.
Japan
METI efficiency mandates push thermal management integration into next-generation semiconductor packaging. ECHA REACH substance restrictions on silicone compounds force reformulation of thermal interface materials for automotive inverter suppliers. Osaka and Nagoya industrial corridors concentrate dielectric fluid engineering for two-phase immersion systems.
China
NMPA material-certification requirements extend validation periods for gallium-alloy compounds entering domestic EV manufacturing. Yangtze River Delta fabs drive demand for direct-to-chip cooling in semiconductor test and assembly operations. Shenzhen and Dongguan electronics clusters integrate liquid cooling compatibility into server platform roadmaps.
India
CEA efficiency mandates for domestic fab construction create first-mover advantage for liquid cooling system integrators. Karnataka and Tamil Nadu semiconductor manufacturing zones specify thermal architectures at the chassis design phase. Delhi-Mumbai industrial corridors attract captive heat exchanger production for railway traction inverter deployments.
In-Chassis Cooling Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and technology integration dimensions. The vendor base stratifies into three tiers: integrated thermal platform providers, component specialists in precision machining or material chemistry, and captive manufacturing arms of server OEMs. Consolidation pressures concentrate in cold plate substrates and pump assemblies where scale economies dominate. Competitive moves center on backward integration into copper micro-channel fabrication and strategic partnerships with semiconductor packaging houses.
Within the liquid cooling architecture tier, Asetek Inc. and CoolIT Systems exemplify divergent strategic positions. Asetek occupies a position representing sealed-loop all-in-one specialization for enterprise server deployments. CoolIT Systems anchors the direct liquid cooling segment sustaining heat flux above 500W per chip. Delta Electronics, Inc. represents the integrated electronics manufacturing archetype with captive production spanning pumps and cold plates. These three patterns illustrate how competitive positioning fragments across technology specialization, manufacturing scope, and customer integration depth.
| Leading Market Players |
|---|
| Asetek Inc. |
| CoolIT Systems |
| Delta Electronics, Inc. |
| Iceotope Technologies |
| Boyd Corporation |
| Fujitsu Ltd. |
| Vertiv Holdings Co. |
| Schneider Electric |
| LiquidStack |
| Others |
Value Chain & Pricing Dynamics
Precision machining capacity utilization above 85% in Taiwanese cold plate fabrication clusters compresses margin flexibility for mid-tier suppliers while anchoring price floors for copper micro-channel substrates. Scale economies in captive pump manufacturing across Mexico and Taiwan simultaneously concentrate supply-side leverage and create tiered entry barriers for non-integrated competitors.
Pricing Analysis
Next-generation direct-to-chip liquid cooling systems command 40-60% price premiums over prior-generation hybrid architectures, while air-cooled legacy platforms face accelerating price erosion. Three-tier pricing structure across premium liquid-cooled, standard hybrid, and economy air-cooled levels reflects certification grade differentiation and volume scale. Cost compression in the mid-tier hybrid segment is intensifying because hyperscale operators are unbundling thermal management from server OEM contracts. Fleet operators and maintenance providers exhibit the highest price sensitivity, while AI training cluster operators prioritize thermal performance over unit cost.
Supply Chain Analysis
Taiwan Strait maritime transit underwrites 70% of precision-machined copper micro-channel substrate movements to German and US data center operators. Manufacturing draws from concentrated Taiwanese and German supplier bases for cold plate fabrication, with Mexican and Chinese facilities for pump and heat exchanger assembly. Single-source vulnerability in Bavarian and Taiwanese precision machining capacity creates structural risk for European and North American deployments. Distribution runs through direct vendor relationships with hyperscale infrastructure engineering teams, bypassing traditional tiered IT distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale data center operators and automotive OEMs, with procurement authority migrating from commodity IT purchasing to infrastructure engineering teams. This consolidation among large buyers is compressing supplier margins and rewriting qualification criteria across the thermal management stack.
For Market Incumbents: Secure backward integration into copper micro-channel fabrication to defend against single-source vulnerability in Taiwanese and German supplier bases. Anchor capacity expansion in Mexico and Taiwan to maintain captive supply of pumps and cold plates. Certification investment in NMPA material compliance and REACH substance reformulation creates switching costs against emerging gallium-alloy compound suppliers. For New Entrants and Emerging Players: Lead with aftermarket thermal material upgrade cycles for electric vehicle service channels, where graphite-sheet interface products penetrate range-recovery demand. Target India's CEA-mandated fab construction zones for first-mover liquid cooling integration. Develop dielectric fluid engineering partnerships with Osaka-based industrial corridors to access two-phase immersion convergence opportunities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among thermal interface material suppliers serving automotive electrification platforms with multi-year qualification cycles. Long-term viability centers on compound chemistry IP and precision machining scale rather than assembly integration. The signal to watch is hyperscale procurement team unbundling behavior, which accelerates direct vendor relationships and concentrates specification authority with infrastructure engineering teams.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold Plate Fabrication | Cupertino micro-channel machining capacity in Taiwan and Germany anchors pricing power for direct-to-chip architectures. |
| REACH-Compliant Compound Reformulation | Gallium-based phase-change alloys replace silicone greases under ECHA substance restrictions in European automotive supply chains. |
| Direct Vendor Relationship Establishment | Infrastructure engineering teams at hyperscale operators now control thermal specification authority, bypassing tiered distribution. |
| India Semiconductor Fab Integration | CEA efficiency mandates in Karnataka and Tamil Nadu create first-mover advantage for liquid cooling system integrators. |
| Two-Phase Immersion Fluid Engineering | Dielectric fluid advances in Osaka and Nagoya industrial corridors enable rack-scale thermal uniformity for AI training clusters. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA Section 608 enforcement data, ECHA REACH substance registrations, NMPA material-certification filings, and hyperscale operator capex disclosures. Primary interviews engaged data center infrastructure engineering directors, automotive powertrain thermal management leads, precision machining plant managers in Taiwan and Germany, and thermal interface material R&D heads. Bottom-up unit economics triangulate against top-down segment sizing across liquid-cooled, hybrid, and air-cooled technology tiers.
Segmentation dimensions modeled include product type (cooling plates, thermal conductive materials, heat exchangers, fans), application (automotive, industrial equipment, aerospace, railways), end user (OEMs, aftermarket providers, fleet operators, maintenance providers), and technology (liquid cooling, hybrid cooling, air cooling, passive cooling). CAGRs derive from installed base turnover rates, power density trajectory assumptions, and regulatory phase-down schedules. Industry-specific inputs capture EU F-Gas Regulation quota tightening, NMPA gallium-alloy validation timelines, and CEA fab construction mandates.
Underlying assumptions cover hyperscale liquid cooling procurement acceleration, REACH substance restriction enforcement continuity, and Taiwan-Germany precision machining capacity stability, with deviation risk concentrated in EPA refrigerant compliance delays and China EV manufacturing policy shifts. Practitioners should keep alternative scenarios live as fluid chemistry certification timelines and legacy facility retrofit economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Motor Vehicle Sensor Market
Automotive Electrical & Electronics
Automotive Electronic Suspension System (ESS) Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Automotive Magnetic Sensor Market
Automotive Electrical & Electronics
China Electric Power Steering Market
Automotive Electrical & Electronics
India Automotive Camera Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
Automotive Clean Cold Technology Market
Automotive Electrical & Electronics
Automotive Traction Inverters Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market
Automotive Electrical & Electronics
Europe Automotive EPS Market
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
Europe Automotive Pressure Sensor Market