
 Japan Passenger Vehicles Lubricants Market | 2026-2036
Japan Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Passenger Vehicles Lubricants Market Foresight
Aftermarket providers is decoupling from OEM-tied service channels as independent workshops build direct supplier relationships. ENEOS Corporation leverages its domestic refinery network to sustain bulk delivery contracts with major fleet operators. Idemitsu Kosan Co Ltd anchors its position through specialized synthetic formulations for hybrid powertrains. ExxonMobil Corporation competes on technology leadership in low-viscosity engine oils aligned with Japanese OEM specifications.
Japan passenger vehicles lubricants comprise formulated fluids engineered from base oils and additive packages, with viscosity grades typically ranging from 0W-16 to 5W-30 for gasoline engines, designed to reduce friction, dissipate heat, and prevent wear in powertrain components. These products serve the essential commercial purpose of extending engine life and maintaining fuel efficiency under stop-and-go urban driving conditions prevalent across Japanese metropolitan corridors. Engine oil commands the dominant value share among product types, though synthetic oil grades within oil grade segmentation capture the fastest expansion as OEM drain intervals lengthen and thermal stability requirements intensify. Aftermarket providers represent the most contested end user channel, where margin pools concentrate around certified workshop networks and direct-to-garage distribution models.
METI enforces fuel-economy standards that directly shape lubricant viscosity specifications and base oil selection for domestic vehicle parc compliance. JIS standards and PMDA-aligned quality frameworks govern product certification, creating barriers for unapproved imports and reinforcing domestic blender advantages. Stakeholders must monitor regulatory alignment between METI efficiency mandates and OEM warranty requirements as electrified powertrains alter thermal management fluid needs.
Market Dynamics
Fleet operators across Greater Tokyo are accelerating synthetic lubricant procurement as METI's fuel-economy standards tighten viscosity requirements and extend OEM drain intervals, compressing conventional oil demand.
Growth Catalysts
- METI Efficiency Mandates:Japan's Ministry of Economy, Trade and Industry enforces progressively stricter fuel-economy standards that directly mandate lower-viscosity lubricant formulations, creating regulatory pull for advanced synthetic grades.
- Hybrid Powertrain Proliferation:Stop-start cycling and thermal load variability in hybrid vehicles demand specialized thermal stability from lubricant additive packages, expanding the addressable premium segment.
- Greater Tokyo Fleet Density:Concentrated vehicle parc in the capital region generates economies of scale for bulk synthetic procurement and certified workshop network expansion.
Market Restraints
- Base Oil Supply Concentration:Domestic refining capacity constraints and import dependency for Group III+ base stocks create input cost volatility and supply security exposure.
- JIS Certification Barriers:Stringent Japanese Industrial Standards approval timelines and testing protocols delay market entry for non-domestic blenders, reinforcing incumbent advantages.
- Electrification Substitution:Battery electric vehicle penetration reduces engine oil consumption per vehicle, structurally compressing total addressable volume in the long-term fleet mix.
Strategic Opportunities
- Osaka-Kobe Industrial Corridor:Underpenetrated fleet service infrastructure in western Japan offers whitespace for independent workshop networks and direct supplier relationships.
- Thermal Management Fluids:Emerging demand for battery coolant and e-axle lubricants in electrified powertrains represents a formulation expansion path beyond traditional engine oils.
- PMDA-Aligned Quality Frameworks:Pharmaceutical-grade purity standards for lubricant additives open premium positioning in precision manufacturing and medical transport fleets.
Industry Challenges
- Additive Chemistry Expertise Gap:Formulation chemists with hybrid powertrain thermal management experience remain scarce, constraining R&D velocity for next-generation products.
- Certification Timeline Compression:Accelerating OEM specification updates outpace JIS approval cycles, creating warranty compliance gaps for aftermarket providers.
- Legacy Distribution Integration:Independent workshops struggle to reconcile direct supplier procurement systems with entrenched OEM-tied service channel workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Passenger Vehicles Lubricants Market |
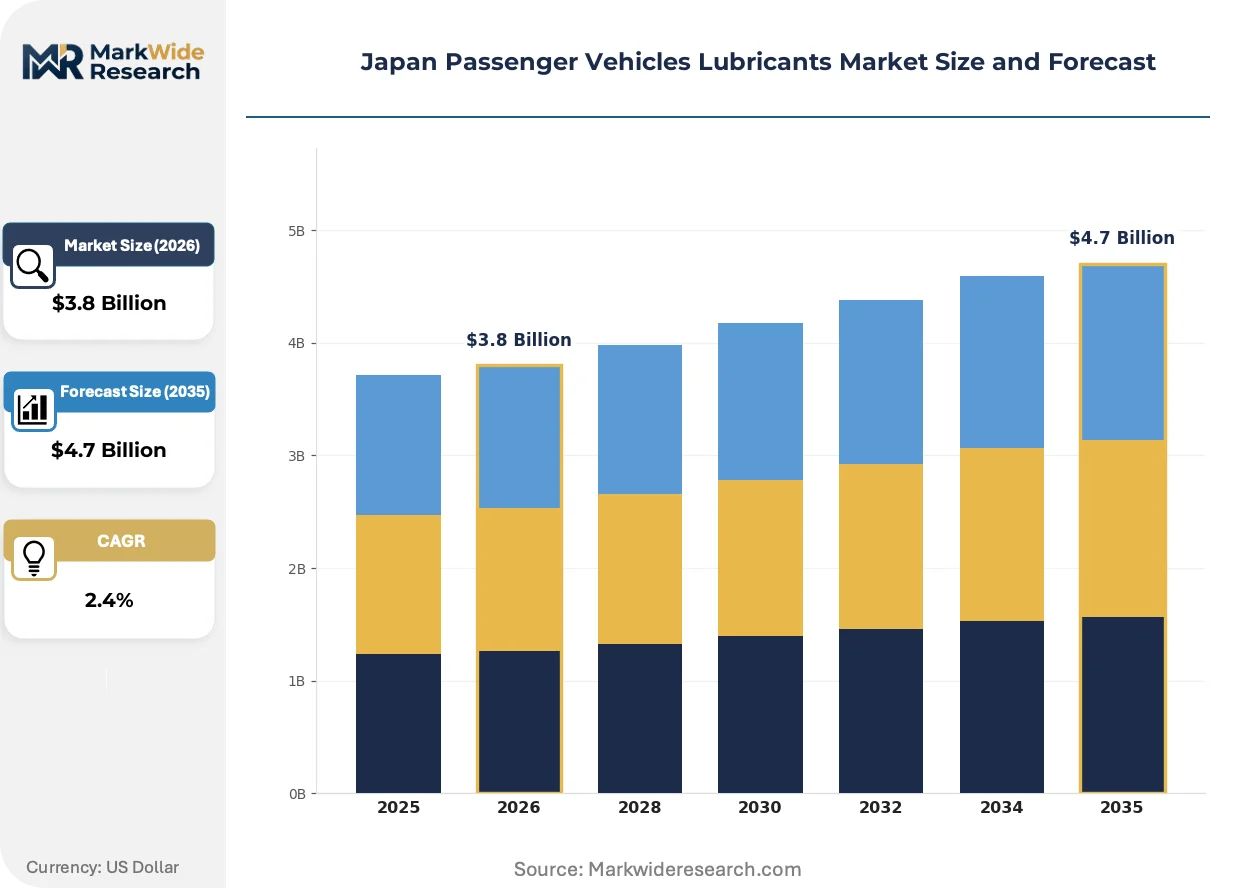
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.7 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Additives End User: Original Equipment Manufacturers, Aftermarket Providers, Fleet Operators, Workshops Oil Grade: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Bio-based Oil Packaging Type: Bulk, Drums, Bottles, Pouches |
| Companies Covered | Cosmo Energy Holdings Co Ltd, BP PLC (Castrol), ENEOS Corporation, FUCHS, Motul, Idemitsu Kosan Co Ltd, Royal Dutch Shell Plc, MITASU OIL CORPORATION, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Passenger Vehicles Lubricants Market Shifts & Advancements
Formulation automation and real-time viscosity monitoring are reshaping how lubricants are specified, procured, and consumed across Japan's passenger vehicle parc.
Artificial intelligence-driven blending systems are automating viscosity grade selection and additive package optimization based on individual vehicle telematics. Major fleet operators in Greater Tokyo are piloting these systems to match lubricant specifications to actual driving patterns rather than generic OEM intervals. This technology is automating the displacement of standardized bulk procurement with dynamic, vehicle-specific fluid management contracts.
METI's 2025 fuel-economy roadmap tightens corporate average fuel efficiency targets and explicitly references lubricant contribution to mechanical friction reduction. Domestic OEMs are responding by mandating 0W-16 and 0W-8 grades for new vehicle platforms, forcing aftermarket providers to stock ultra-low viscosity inventories ahead of parc turnover. The premium synthetic segment bears the immediate compliance burden as conventional blenders face specification obsolescence.
Direct-to-garage distribution platforms are unbundling traditional wholesaler relationships as independent workshops seek price transparency and reduced inventory carrying costs. Digital procurement interfaces now aggregate demand across workshop networks in Fukuoka and Sapporo, bypassing regional distributors. This behavioral shift concentrates purchasing power in platform intermediaries and compresses margin pools for legacy supply chain tiers.
Japan Passenger Vehicles Lubricants Market Segmentation
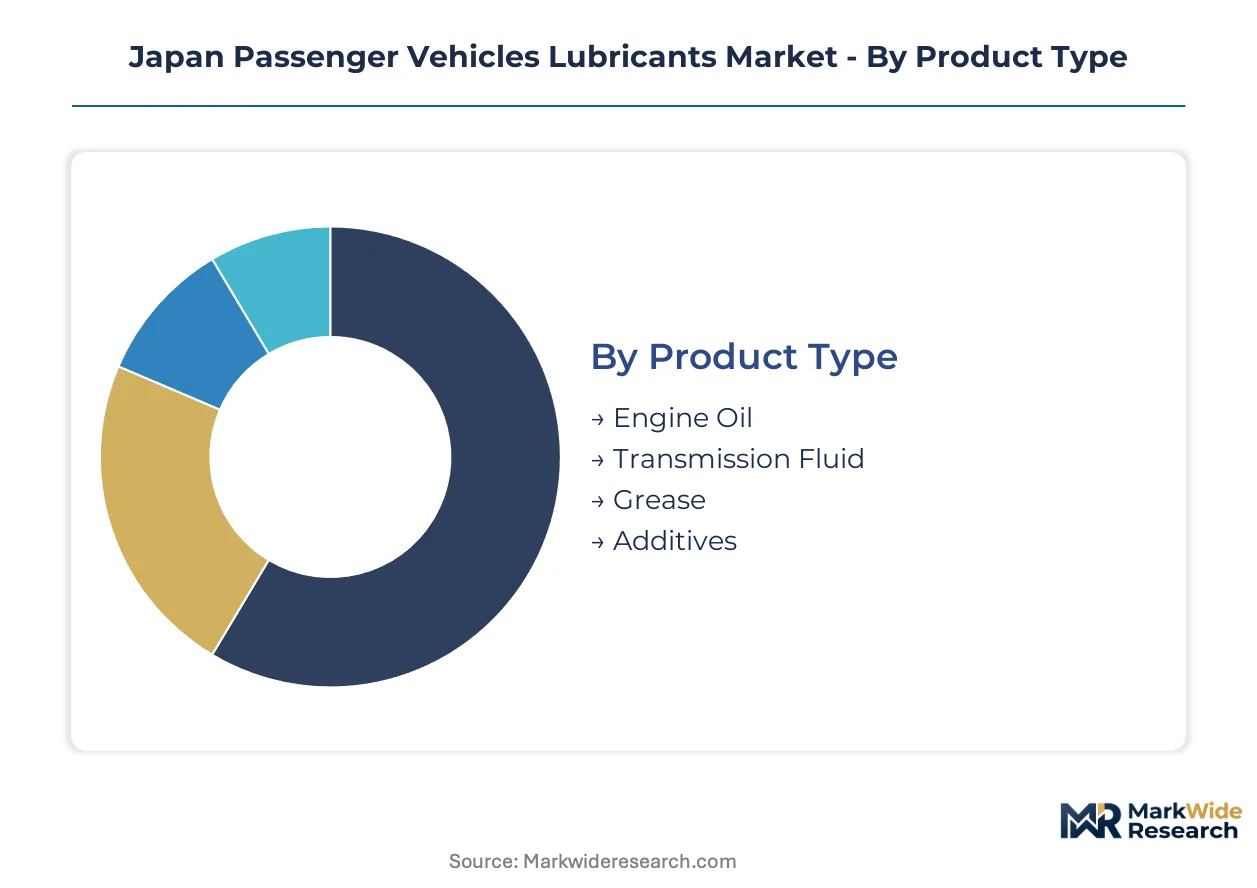
Segmentation in Japan's passenger vehicle lubricants market reveals how regulatory pressure and powertrain evolution reshape procurement patterns across distinct customer and product categories. Understanding these divisions exposes where margin pools concentrate and which specifications command premium positioning under METI's tightening efficiency mandates.
Product Type:
Product differentiation centers on thermal load tolerance and friction reduction coefficients as hybrid powertrains impose divergent operating conditions across fluid categories.
- Engine Oil:Formulated from Group II-IV base stocks with viscosity grades from 0W-16 to 5W-30, engine oil formulations face the steepest specification pressure as OEMs mandate ultra-low viscosity for CAFE compliance. Demand concentrates in Greater Tokyo fleet service bays where drain interval extension programs maximize synthetic uptake.
- Transmission Fluid:Specialized ATF and CVT formulations with enhanced shear stability address the torque converter cycling and belt-pulley friction management unique to Japanese hybrid architectures. Adoption accelerates in Kansai region independent workshops rebuilding transmission service revenue streams.
- Grease:Lithium-complex and polyurea-thickened greases serve chassis, wheel bearing, and auxiliary component lubrication with NLGI 2 consistency grades dominating.
- Additives:Pour point depressants, viscosity index improvers, and anti-wear chemistries constitute the formulation layer where domestic blenders maintain JIS-certified competitive barriers.
Engine Oil leads on scale; Synthetic-formulated Engine Oil leads on momentum as viscosity grades compress.
End User:
Channel structure determines pricing power and inventory risk allocation, with direct procurement models displacing traditional wholesaler intermediaries.
- Original Equipment Manufacturers:Factory-fill contracts specify proprietary additive packages aligned to powertrain warranty terms, with Toyota, Honda, and Nissan captive service networks enforcing exclusive fluid specifications. Procurement concentrates at Yokohama and Toyota City technical centers where formulation approval timelines extend 18-24 months.
- Aftermarket Providers:Independent distributors and certified workshop networks capture margin through JIS-certified product differentiation and technical service bundling. Growth accelerates in Osaka-Kobe corridor where fleet density supports bulk synthetic contracts outside OEM-tied channels.
- Fleet Operators:Municipal, corporate, and rental vehicle pools in Greater Tokyo negotiate direct supply agreements based on telematics-documented drain intervals.
- Workshops:Single-location and small-chain service facilities face inventory compression as digital procurement platforms aggregate demand and reduce carrying costs.
Aftermarket Providers lead on scale; Fleet Operators lead on momentum as direct procurement models expand.
Oil Grade:
Base oil selection governs thermal oxidation stability, cold-crank viscosity, and fuel-economy contribution coefficients under METI test protocols.
- Mineral Oil:Group I and II base stocks refined from domestic crude feedstocks face structural demand compression as drain interval extension and viscosity grade reduction render conventional formulations non-compliant with new vehicle warranties.
- Synthetic Oil:Group III, III+, and IV (PAO) base stocks deliver the -40°C pumpability and 150°C+ high-temperature shear stability required for 0W-16 and 0W-8 grades. Penetration accelerates in Sapporo and Fukuoka fleet conversions where cold-start protection and extended drain economics justify premium positioning.
- Semi-Synthetic Oil:Blended formulations balance cost and performance for older vehicle parc with less stringent OEM specifications.
- Bio-based Oil:Ester and vegetable-derived base stocks serve niche environmental compliance positioning in government and corporate sustainability mandates.
Synthetic Oil leads on scale; Synthetic Oil leads on momentum as specification grades compress toward ultra-low viscosity.
Packaging Type:
Packaging configuration aligns with consumption velocity, storage constraints, and regulatory handling requirements across customer segments.
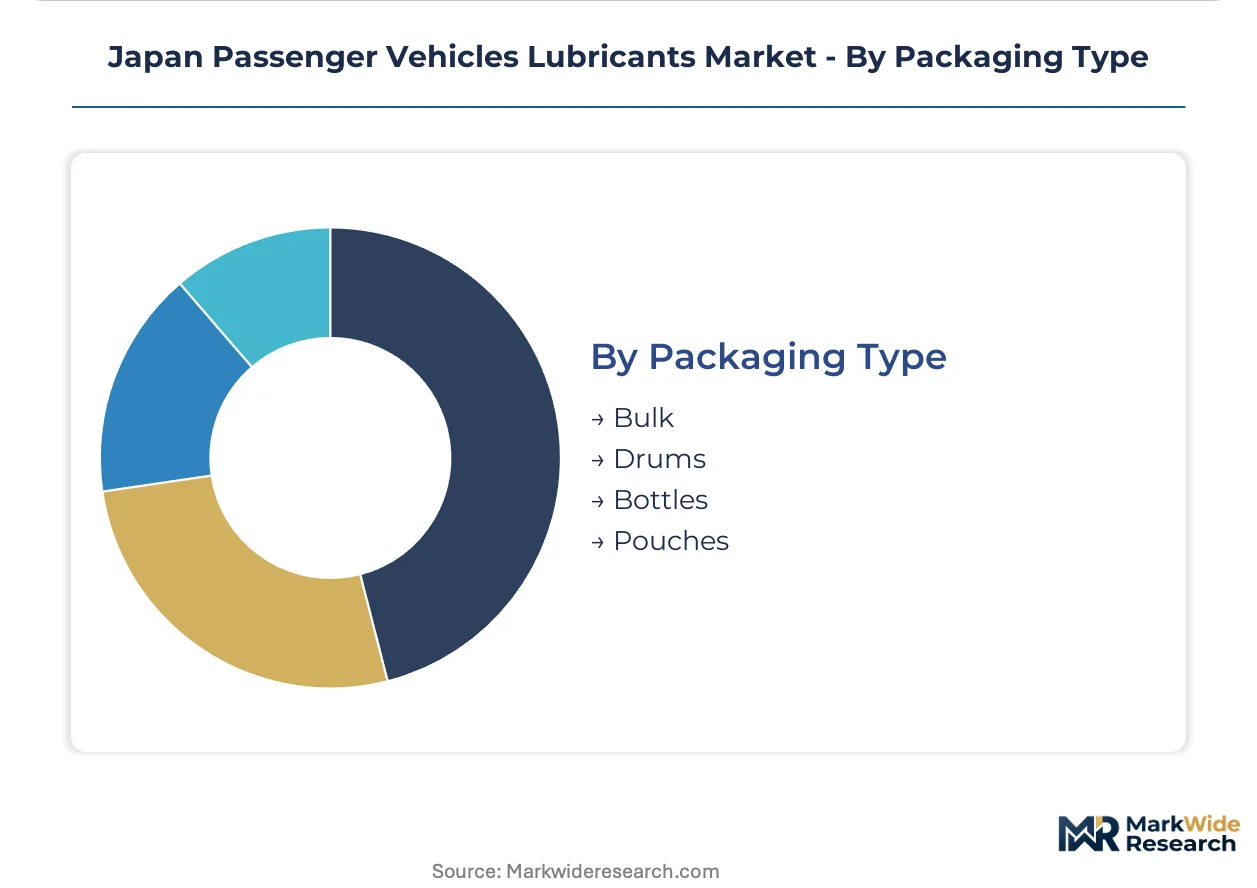
- Bulk:Tanker and tote deliveries to fleet depots and workshop chains minimize per-liter packaging cost and waste disposal burden. Concentration in Greater Tokyo reflects the infrastructure density supporting just-in-time replenishment systems.
- Drums:200-liter steel and polymer drums serve mid-scale workshops with moderate throughput and limited bulk storage capacity.
- Bottles:1-liter to 20-liter polyethylene and metal containers dominate retail and small-workshop channels where SKU variety and shelf visibility drive selection.
- Pouches:Flexible single-use and multi-dose formats address motorcycle, small-engine, and emergency top-up applications with minimal packaging mass.
Bulk leads on scale; Bottles lead on momentum as direct-to-garage digital platforms fragment order sizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in lubricant formulation compliance is pushing domestic blenders toward METI-aligned production clusters while import-dependent operators face JIS certification delays that inflate cost-of-compliance gaps.
Kanto/Tokyo
Fleet density and just-in-time bulk delivery infrastructure concentrate synthetic lubricant demand in the capital region. METI fuel-economy mandates drive 0W-16 and 0W-8 grade procurement among Greater Tokyo municipal and corporate vehicle pools. Yokohama technical centers host OEM formulation approval processes that extend 18-24 months, reinforcing captive supply relationships.
Kansai/Osaka
Independent workshop networks in the Osaka-Kobe corridor are decoupling from OEM-tied channels to negotiate direct supplier contracts. JIS certification requirements for aftermarket providers create competitive barriers that domestic blenders exploit. Transmission fluid service revenue is accelerating in Kansai rebuild shops as hybrid parc ages.
Chubu/Nagoya
Toyota City and surrounding Aichi Prefecture manufacturing clusters anchor factory-fill specification development for proprietary additive packages. METI efficiency standards are transmitted through OEM captive service networks that enforce exclusive fluid mandates. Nagoya-based procurement teams coordinate bulk synthetic contracts with refinery-adjacent blenders.
Kyushu
Fukuoka fleet operators are piloting digital procurement platforms that aggregate demand across workshop networks. Direct-to-garage distribution models are compressing regional distributor margins while expanding certified synthetic access. Cold-start protection requirements in northern Kyushu sustain premium synthetic positioning.
Hokkaido
Sapporo commercial vehicle pools justify synthetic oil conversion through extended drain interval economics and sub-zero pumpability needs. Bulk delivery infrastructure constraints limit just-in-time replenishment, favoring drum and tote formats over tanker contracts. METI compliance costs are absorbed through municipal fleet scale advantages.
Japan Passenger Vehicles Lubricants Market Competitive Landscape
Direct supplier relationships with independent workshops dominate the current landscape as aftermarket providers decouple from legacy distribution tiers. The vendor base concentrates around domestic refiners with captive base oil supply, integrated international majors with technology licensing networks, and specialized blenders serving hybrid powertrain niches. Strategic archetypes include refinery-anchored national champions, formulation-technology licensors, and regional service specialists. Competitive intensity centers on JIS certification velocity and bulk contract pricing power rather than product differentiation alone.
Among Japan-based energy conglomerates, ENEOS Corporation and Idemitsu Kosan Co Ltd exemplify the refinery-anchored archetype with domestic production infrastructure. BP PLC (Castrol) and ExxonMobil Corporation occupy positions as international technology licensors leveraging global formulation expertise. These three represent distinct competitive vectors: captive supply security, hybrid specialization, and low-viscosity leadership respectively.
| Leading Market Players |
|---|
| Cosmo Energy Holdings Co Ltd |
| BP PLC (Castrol) |
| ENEOS Corporation |
| FUCHS |
| Motul |
| Idemitsu Kosan Co Ltd |
| Royal Dutch Shell Plc |
| MITASU OIL CORPORATION |
| ExxonMobil Corporation |
| Others |
Supply & Pricing Matrix
Group III base oil spot indices in Asia cascade through Japanese blender cost structures into three distinct pricing tiers for synthetic formulations. METI efficiency mandates compress mineral oil premiums while elevating ultra-low viscosity synthetics into the dominant value pool.
Pricing Analysis
Distributor margins in the aftermarket channel absorb the steepest compression as direct-to-garage platforms disintermediate regional wholesalers. Pricing stratifies across JIS-certified premium, METI-compliant standard, and legacy mineral economy tiers. Cost compression in conventional grades intensifies because fleet operators negotiate telematics-validated drain intervals that eliminate bulk mineral procurement. Fleet operators demonstrate lowest price sensitivity due to lifecycle cost optimization, while independent single-location workshops face acute margin pressure from inventory carrying costs.
Supply Chain Analysis
Used oil collection and re-refining flows anchor circular supply chain economics for domestic blenders with JIS-certified reprocessing capabilities. Base oil production concentrates in Japan, South Korea, and Singapore, with Group III+ capacity expansion in South Korea tightening regional feedstock availability. Formulation chemistry draws from polyalphaolefin imports, additive packages from US and European suppliers, and domestic Group II base stocks from ENEOS and Idemitsu refinery networks. Single-source vulnerability persists for high-performance viscosity index improvers sourced from specialized German and US chemical producers. Distribution runs through certified workshop networks and direct fleet contracts, bypassing legacy petroleum distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through synthetic grade substitution and drain interval extension programs that reduce per-kilometer fluid consumption. Fleet telematics integration creates pricing power for formulation suppliers with predictive maintenance platforms.
For Market Incumbents: Lock in captive base oil supply through refinery-adjacent blending capacity or long-term offtake agreements with Group III+ producers. Defend against thermal management fluid substitution by accelerating R&D in battery coolant and e-axle lubricant formulations. Channel control through certified workshop network equity stakes preserves margin pools against digital platform disintermediation.
For New Entrants and Emerging Players: AI-driven viscosity optimization platforms offer a technology-first wedge into Greater Tokyo fleet procurement contracts. Osaka-Kobe independent workshops represent the most penetrable geography, with JIS certification timelines shorter than OEM factory-fill approval cycles. Direct-to-garage digital procurement interfaces provide the essential go-to-market angle, aggregating fragmented workshop demand into bulk-equivalent pricing power.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized blenders possessing hybrid powertrain thermal management formulation expertise and existing JIS certification infrastructure. Long-term viability over the next decade hinges on electrification transition pacing and synthetic oil grade specification compression. Acquisition target archetype: mid-scale domestic blenders with captive re-refining capabilities and established fleet relationships. Monitor METI fuel-economy mandate revision announcements as the critical inflection signal for ultra-low viscosity grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
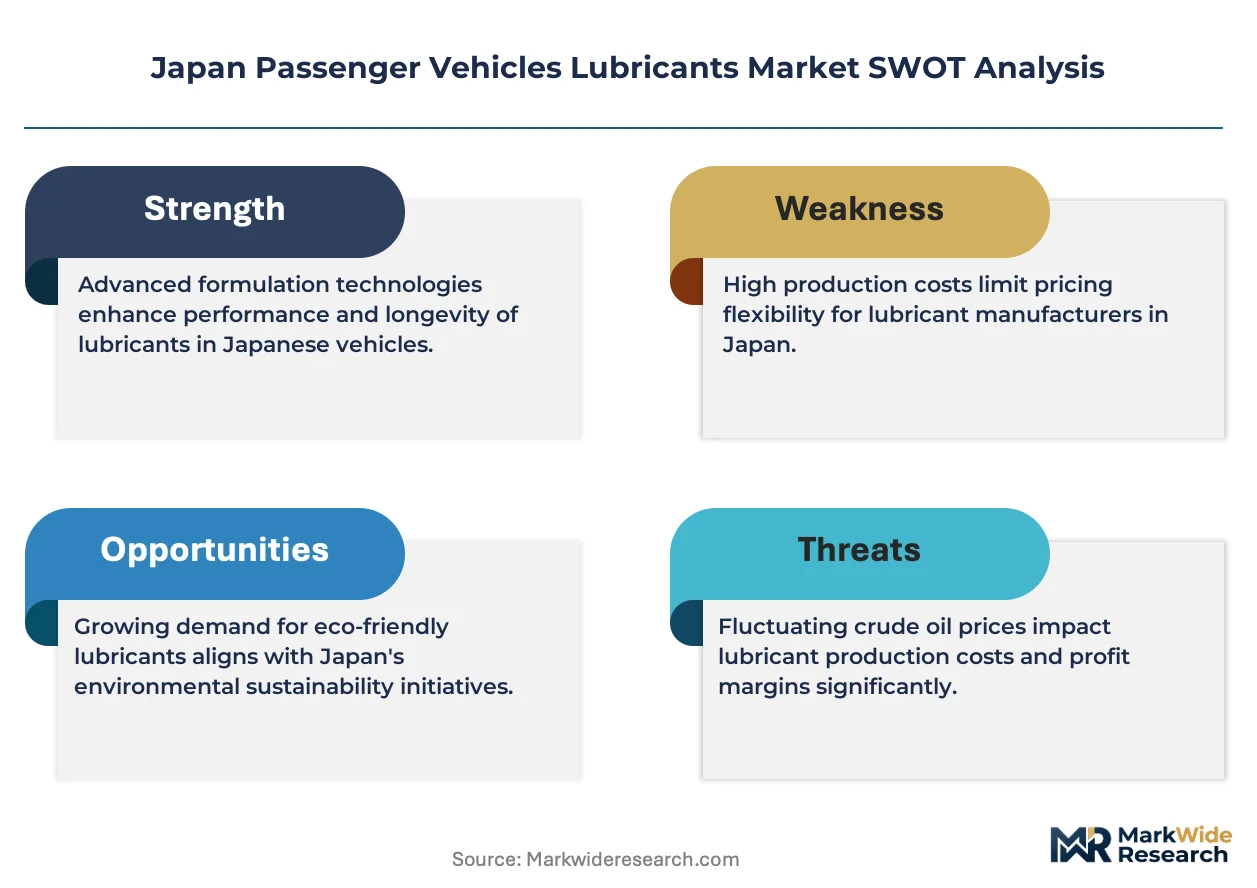
| Backward Integration into Group III+ Base Oil | Captive supply security reduces import dependency volatility and stabilizes input costs for synthetic formulations. |
| Thermal Management Fluid Portfolio Expansion | Battery coolant and e-axle lubricant development addresses electrification-driven demand beyond traditional engine oils. |
| Direct-to-Garage Digital Platform Launch | Aggregation of independent workshop demand bypasses distributor markups and concentrates purchasing power. |
| JIS Certification Acceleration Program | Compressed approval timelines enable faster market entry for next-generation hybrid powertrain formulations. |
| Telematics-Integrated Fluid Management Contracts | Vehicle-specific lubricant specification based on actual driving patterns displaces standardized bulk procurement. |
Research Methodology
Bottom-up fleet operator and workshop demand modeling reconciled against top-down refinery output and import tracking forms the analytical core of this study. Primary interviews with lubricant formulation chemists, fleet procurement managers, independent workshop owners, and METI regulatory officials combined with secondary validation from JIS certification databases, METI fuel-economy compliance filings, and customs trade records. Triangulation across supply-side capacity assessments and demand-side procurement pattern analysis ensures cross-verified market sizing.
Historical trendline analysis of synthetic oil penetration rates, viscosity grade adoption curves, and drain interval extension patterns informs the projection framework. Segmentation modeling spans product type, oil grade, end user channel, and regional demand cluster across the analysis window. CAGRs derive from regression analysis of specification-driven substitution elasticities and fleet turnover dynamics. Key forecast inputs include METI mandate implementation schedules and hybrid powertrain parc growth trajectories.
The model holds under steady METI regulatory enforcement and gradual electrification pacing; deviation in accelerated BEV adoption or base oil supply disruption would shift volume projections. Forecasts reflect documented assumptions about specification compliance timelines and fleet procurement behavior. Practitioners should monitor METI efficiency standard revision announcements and OEM factory-fill specification updates for early signals of formulation demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Mobile Diesel Heaters Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Automotive Fluids Market
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Remanufactured Parts Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
South America Gear Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
Traffic Control Products Market
Automotive Parts
Automotive Intercooler Market
Automotive Parts
South America Passenger Vehicles Lubricants Market