
 Tire Protection Chains Market | 2026-2036
Tire Protection Chains Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Protection Chains Market Insights
Leasing and rental-based procurement is reconfiguring competitive dynamics in the tire protection chains sector. Pewag leverages its forged-component heritage to sustain premium positioning across European mining districts. RUD anchors its position through backward integration into alloy steel production, controlling metallurgical consistency from melt to finished chain. Laclede Chain Manufacturing Company specializes in custom-fit tensioning systems for North American construction fleets, differentiating on rapid turnaround for non-standard tire profiles.
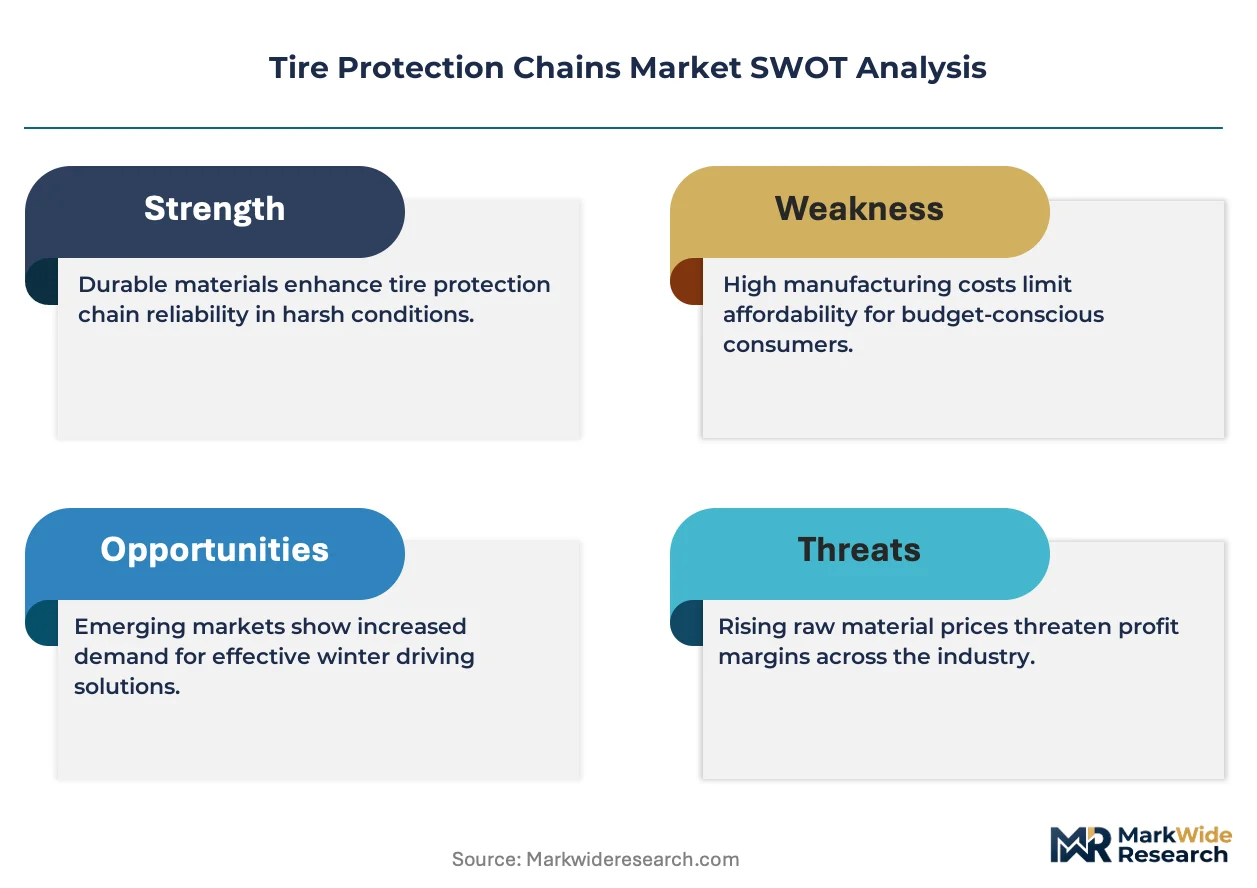
Tire protection chains are interlinked metal assemblies engineered from hardened alloy steel, typically measuring 16-25 mm in link diameter, designed to encircle pneumatic tires and shield tread and sidewall surfaces from abrasion, puncture, and thermal damage in severe operating environments. Their primary industrial purpose extends tire operational life by 300-500 percent in quarry, underground, and icy terrain applications where unprotected rubber would fail within weeks. Heavy-duty chains dominate installed base value owing to mining fleet specifications, while rubber coated chains represent the fastest-expanding material innovation as operators seek reduced vibration transmission and lower ground disturbance on sensitive haul roads. Steel remains the volume leader across all application categories, though alloy formulations command margin concentration in underground segments where weight restrictions and heat resistance carry premium pricing.
OSHA mandates on workplace equipment integrity and EPA emissions compliance indirectly shape replacement cycles by extending vehicle service intervals, which in turn prolongs chain attachment periods and accelerates wear-part turnover. China's MEE standards and the EU's CE marking requirements for machinery safety create divergent certification pathways that fragment supplier qualification regimes across export markets. Stakeholders must monitor alloy price volatility and regulatory harmonization progress between ISO durability standards and national mining safety codes to anticipate procurement cost shifts and compliance-driven specification changes.
Market Dynamics
Leasing-based procurement is compressing replacement cycles across mining fleets as operators prioritize uptime over ownership, forcing suppliers to restructure service agreements around wear-rate guarantees rather than unit sales.
Growth Catalysts
- Underground ore haulage intensity:Chilean and Peruvian copper operators run ultra-class trucks continuously, accelerating chain wear and sustaining replacement demand.
- EPA emissions enforcement:Extended vehicle service intervals in US mining fleets prolong chain attachment periods, increasing per-unit consumption.
- Rubber-coated chain innovation:Reduced vibration transmission opens quarry applications where ground disturbance sensitivity previously blocked metal-chain adoption.
Market Restraints
- Alloy steel price volatility:Nickel and chromium input costs swing unpredictably, compressing margins for forged-component manufacturers.
- Supplier concentration in Alpine Europe:Austrian and German forging houses control critical heat-treatment capacity, creating geographic supply risk.
- Weight restrictions in deep mining:Standard heavy-duty chains exceed load limits for some shaft-accessible operations, capping addressable volume.
Strategic Opportunities
- Australian iron ore expansion:Pilbara Basin operators seek longer-lasting protection for 400-tonne haulers operating on abrasive laterite surfaces.
- CE marking harmonization:Unified EU machinery safety certification reduces supplier qualification costs for cross-border mining equipment sales.
- Sensor-embedded chain monitoring:Integration of wear-detection IoT with maintenance scheduling software creates predictive replacement revenue streams.
Industry Challenges
- Metallurgical technician scarcity:Specialized heat-treatment expertise for hardened alloy links concentrates in aging European workforces.
- ISO 1082 certification timelines:Mining safety standard compliance delays new product introductions by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Protection Chains Market |
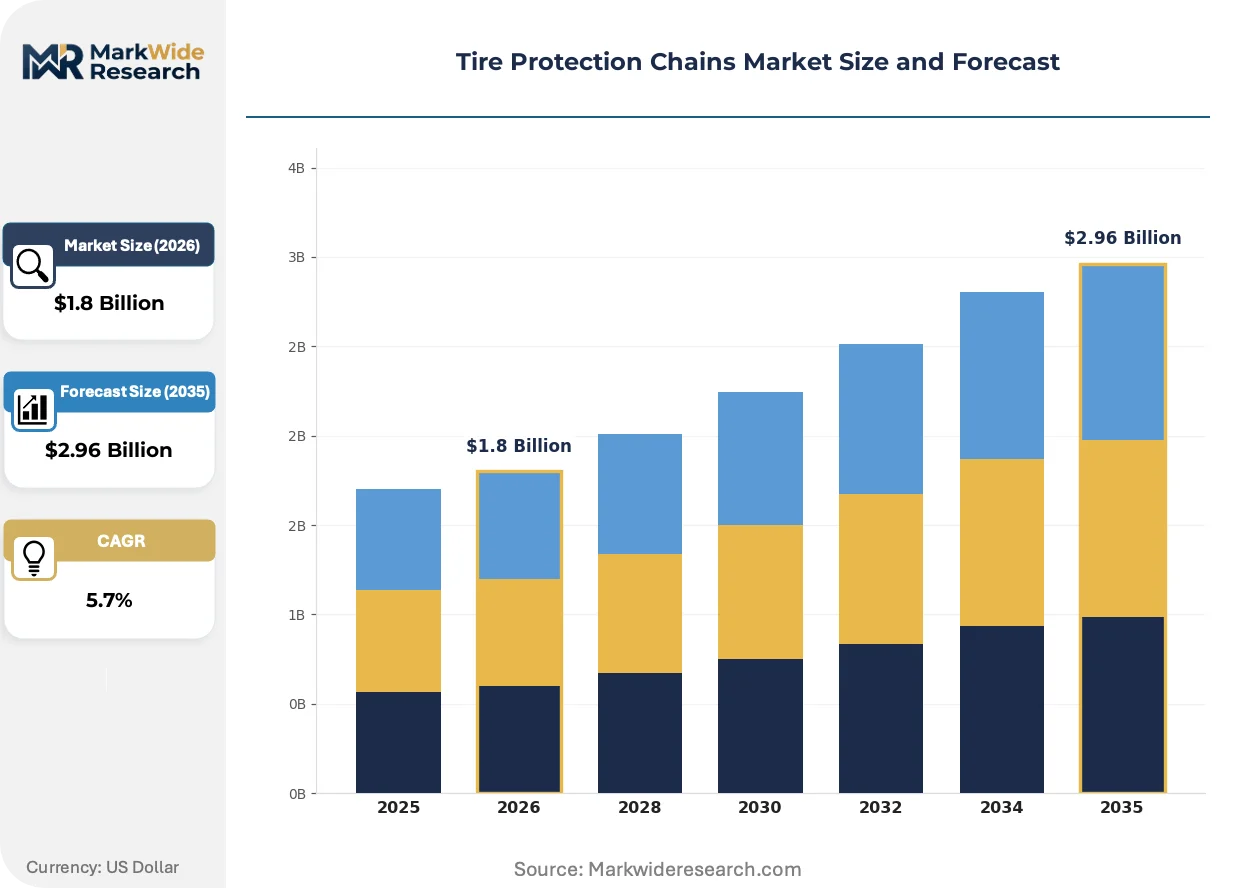
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Chains, Lightweight Chains, Rubber Coated Chains, Tensioning Chains Material: Steel, Alloy, Composite, Synthetic Application: Agriculture, Construction, Mining, Snow Removal End User: Agricultural Sector, Construction Companies, Mining Operators, Transportation Services |
| Companies Covered | Pewag, RUD, Las Zirh, Laclede Chain Manufacturing Company, Nordic Traction Group, Thule, Trygg, Maggi, Quality Chain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Protection Chains Market Trends and Innovations
Rubber-coated alloy assemblies are collapsing traditional trade-offs between protection durability and equipment vibration, while regulatory pressure on emissions intensifies fleet management sophistication.
Composite rubber-steel hybrid chains are collapsing the historical separation between quarry and mining applications. Surface operators in Scandinavian aggregate extraction now specify coated assemblies previously restricted to underground fleets. The technology is collapsing price premiums for vibration-dampened protection, forcing forged-metal suppliers to demonstrate thermal performance advantages.
China's MEE emissions standards now mandate extended equipment service intervals for heavy-duty vehicles in mining zones. Provincial environmental bureaus enforce quarterly compliance audits, compelling fleet managers to document tire protection system integrity. Underground coal operators in Shanxi and Inner Mongolia face the steepest documentation burdens, accelerating adoption of wear-monitoring attachments.
Rental-based maintenance agreements now dominate procurement for mid-size quarry fleets across Germany and Poland. Equipment lessors bundle chain replacement into hourly operating charges, transferring inventory risk from mine operators to service providers. The Rhine-Ruhr industrial corridor shows the fastest channel restructuring, with construction aggregates producers leading the shift from capital purchase to operating expenditure models.
Tire Protection Chains Market Segmentation
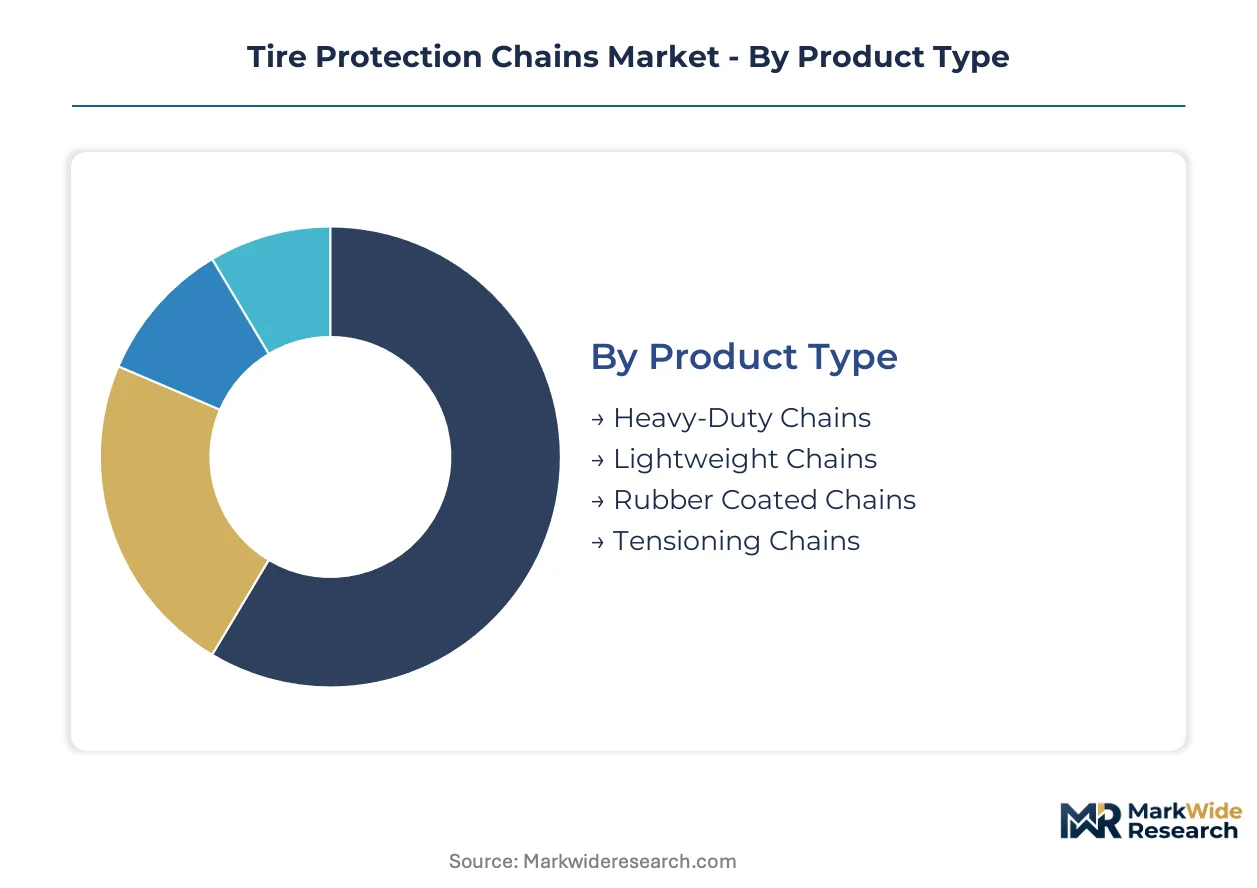
Segmentation in tire protection chains reflects divergent wear patterns across operating environments. Mining fleets prioritize durability over replacement frequency, while construction and agricultural users balance upfront cost against seasonal utilization rates. Understanding these trade-offs clarifies where suppliers can capture premium pricing versus volume turnover.
Product Type:
Replacement cycles vary dramatically by product category, with some segments turning over annually while others persist for multiple service intervals.
- Heavy-Duty Chains:Forged alloy steel assemblies with 20-25 mm link diameters engineered for ultra-class haul trucks. Chilean copper operators in the Atacama Desert run these continuously on 400-tonne vehicles, generating predictable replacement demand every 8-12 months under abrasive laterite conditions.
- Rubber Coated Chains:Hybrid constructions combining hardened steel cores with vulcanized rubber exteriors. Scandinavian aggregate quarries specify these for vibration-sensitive haul roads near residential zones, with Finnish and Norwegian operators leading adoption where ground disturbance regulations restrict conventional metal chains.
- Lightweight Chains:Reduced-link-diameter designs for medium-duty construction equipment. German municipal snow removal fleets specify these for seasonal attachment on wheel loaders.
- Tensioning Chains:Adjustable-fit systems accommodating non-standard tire profiles. North American construction rental companies stock these for rapid deployment across mixed equipment pools.
Heavy-Duty Chains dominate installed base. Rubber Coated Chains is where expansion concentrates.
Material:
Cost tiers separate commodity procurement from performance-critical specifications, with metallurgical grade determining margin capture.
- Steel:Standard carbon and manganese formulations serving price-sensitive agricultural and seasonal construction applications. Volume leadership persists across all categories, though margin compression intensifies during raw material price spikes.
- Alloy:Nickel-chromium hardened grades with controlled heat treatment for underground mining. Australian iron ore operators in the Pilbara Basin specify these for 24/7 haulage on abrasive surfaces, accepting premium pricing for extended service intervals.
- Composite:Polymer-steel hybrid constructions emerging in specialty quarry applications. Limited penetration reflects unproven durability in high-impact conditions.
- Synthetic:Experimental aramid and ultra-high-molecular-weight polyethylene alternatives. Development-stage products target weight-restricted deep mining shafts where every kilogram affects hoisting economics.
Steel commands volume leadership. Alloy captures margin concentration.
Application:
Customer sophistication and specification rigor vary sharply across end-use contexts, fragmenting supplier qualification requirements.
- Mining:Continuous-duty specifications with documented wear-rate guarantees. Peruvian open-pit copper operators require ISO 1082 certification and real-time wear monitoring integration.
- Construction:Seasonal and project-based procurement with rapid turnaround demands. Polish and German quarry fleets increasingly specify rental-inclusive maintenance agreements.
- Agriculture:Price-driven seasonal attachment for harvest and soil preparation equipment. Lower specification tolerance permits shorter product lifecycles.
- Snow Removal:Municipal and commercial fleet applications with standardized fitment requirements. Scandinavian public works departments specify rapid-install designs for emergency deployment.
Mining anchors value concentration. Construction shows the steepest channel restructuring toward operating expenditure models.
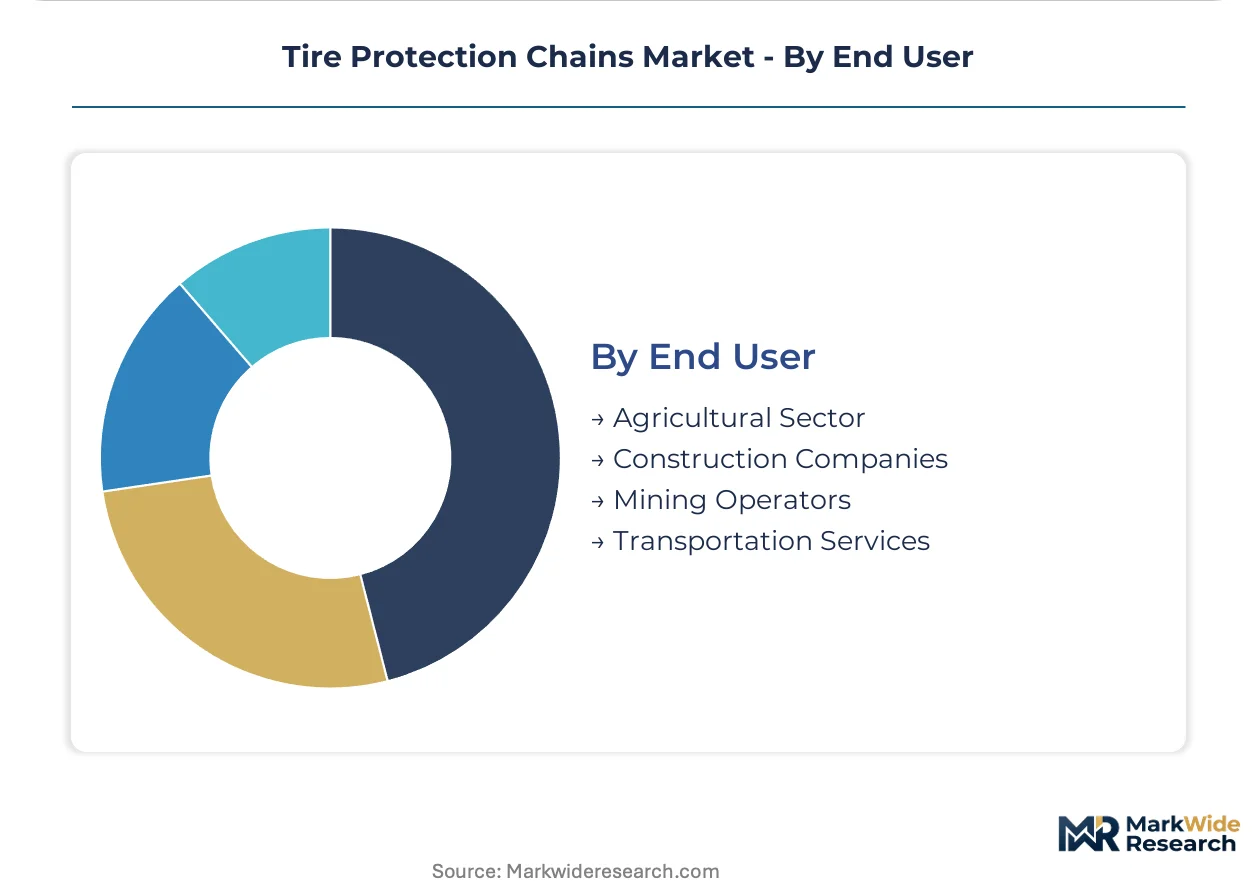
End User:
Procurement authority and technical specification capability diverge between owner-operators and outsourced fleet managers.
- Mining Operators:Integrated technical teams with metallurgical expertise and long-term supplier relationships. Direct negotiation of wear-rate guarantees and predictive maintenance integration.
- Construction Companies:Mixed ownership models with growing equipment lessor intermediation. Rhine-Ruhr corridor aggregates producers now delegate chain inventory management to rental providers.
- Agricultural Sector:Dispersed individual operators with limited technical specification capability. Dealer network dependence for fitment and replacement timing.
- Transportation Services:Logistics and specialized haulage contractors with standardized fleet specifications. Seasonal demand concentration in winter road maintenance.
Mining Operators concentrate premium demand. Construction Companies are restructuring procurement toward service-based models fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power clusters in Alpine European forging districts while cost-sensitive procurement dominates South American mining corridors. Austrian and German heat-treatment capacity commands margin premiums. Chilean and Peruvian operators prioritize replacement velocity over metallurgical sophistication.
Chile
Atacama Desert copper operators run ultra-class haul trucks continuously on abrasive laterite surfaces. MEE-equivalent provincial environmental audits enforce equipment service documentation. Antofagasta and Calama mining clusters sustain predictable 8-12 month chain replacement cycles.
Peru
Open-pit copper extraction in the Andean Cordillera generates intensive tire protection consumption. ISO 1082 mining safety compliance mandates documented wear-rate guarantees. The Cerro de Pasco and Arequipa mining districts concentrate procurement authority among integrated technical teams.
Australia
Pilbara Basin iron ore operators seek extended service intervals for 400-tonne haulers on abrasive surfaces. TGA-equipment safety frameworks align with ISO durability standards. Port Hedland and Newman mining hubs drive demand for premium alloy formulations.
Germany
Rhine-Ruhr construction aggregates producers lead Europe's shift from capital purchase to operating expenditure procurement models. CE marking machinery safety requirements streamline cross-border equipment certification. Dortmund and Essen quarry clusters increasingly specify rental-inclusive maintenance agreements.
China
Shanxi and Inner Mongolia underground coal operators face steep documentation burdens under MEE emissions enforcement. Provincial environmental bureaus mandate quarterly compliance audits for heavy-duty vehicle fleets. Datong and Ordos mining centers accelerate adoption of wear-monitoring attachments.
Tire Protection Chains Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in metallurgical and tensioning subsystems. The vendor base organizes around three strategic archetypes: Alpine forging houses with captive heat-treatment capacity, regional fabricators serving rental intermediaries, and custom-fit specialists addressing non-standard tire profiles. Dominant competitive moves include backward integration into alloy steel production and sensor-embedded predictive maintenance partnerships.
Among Alpine European forging houses, Pewag and RUD exemplify the premium-tier archetype through metallurgical control from melt to finished chain. Laclede Chain Manufacturing Company occupies a position within the North American custom-fit segment. Nordic Traction Group, Trygg, and Thule represent Scandinavian vibration-dampening specialists. Quality Chain and Maggi sit within mid-market construction procurement channels. Las Zirh anchors Turkish fabrication capacity serving regional mining corridors.
| Leading Market Players |
|---|
| Pewag |
| RUD |
| Las Zirh |
| Laclede Chain Manufacturing Company |
| Nordic Traction Group |
| Thule |
| Trygg |
| Maggi |
| Quality Chain |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor channels alloy steel from Austrian and German forging houses to Chilean mining clusters, with transport cost differentials amplifying price spreads between captive-heat-treatment suppliers and regional fabricators serving price-sensitive construction fleets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across mining procurement, with pricing stratifying across premium, standard, and economy tiers based on ISO 1082 certification grade and wear-rate guarantee documentation. Cost compression in standard-grade steel chains is intensifying because nickel and chromium input volatility squeezes forged-component margins. Construction rental intermediaries in the Rhine-Ruhr corridor exhibit the highest price sensitivity, while Australian Pilbara operators accept premium alloy formulations for extended service intervals.
Supply Chain Analysis
Alloy steel feedstock draws from Austrian, German, and Chinese metallurgical capacity, with nickel-chromium formulations resting on South African and Indonesian ore sources. Supply chain risk centers on single-source vulnerability in Alpine European heat-treatment expertise concentrated among aging workforces. Distribution runs through equipment lessors bundling replacement into hourly operating charges for mid-size quarry fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent suppliers face substitution pressure from rubber-coated hybrid chains collapsing traditional vibration-durability trade-offs, requiring defensive repositioning around thermal performance differentiation and predictive maintenance integration.
For Market Incumbents: Entrench metallurgical control through backward integration into alloy steel production, mirroring RUD's captive supply from melt to finished chain. Secure ISO 1082 certification pipelines to compress new product introduction timelines against emerging composite alternatives. Prioritize sensor-embedded wear monitoring partnerships to lock in predictive replacement revenue streams before vibration-dampened hybrids capture quarry market share.
For New Entrants and Emerging Players: Australian iron ore expansion in the Pilbara Basin offers the most penetrable white-space for premium alloy formulations targeting 400-tonne hauler specifications. Target rental-inclusive maintenance agreements across German and Polish construction aggregates producers as the fastest channel restructuring toward operating expenditure models. Lead with rapid-turnaround tensioning systems for non-standard tire profiles where Laclede Chain Manufacturing Company's custom-fit specialization has not yet saturated North American demand.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors Alpine forging houses with captive heat-treatment capacity and documented supplier relationships across Chilean and Peruvian copper operators. Long-term viability hinges on rubber-coated innovation adoption curves and MEE emissions enforcement documentation burdens accelerating wear-monitoring attachment demand. Watch quarterly provincial environmental audit compliance rates in Shanxi and Inner Mongolia as inflection indicators for predictive maintenance hardware pull-through.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Steel Production | RUD's captive metallurgical control from melt to finished chain commands premium positioning across European mining districts. |
| Sensor-Embedded Chain Monitoring Development | Wear-detection IoT integration with maintenance scheduling software creates predictive replacement revenue streams for OEMs. |
| Rental-Inclusive Maintenance Agreement Expansion | Rhine-Ruhr construction aggregates producers delegate inventory risk to equipment lessors bundling hourly operating charges. |
| ISO 1082 Certification Pipeline Investment | Peruvian open-pit operators mandate documented wear-rate guarantees, compressing supplier qualification timelines. |
| Rubber-Coated Hybrid Product Line Launch | Scandinavian aggregate quarries specify vibration-dampened assemblies where ground disturbance regulations restrict conventional metal chains. |
Research Methodology
The analysis maps heavy-duty chains, rubber-coated chains, lightweight chains, and tensioning chains, each validated through maintenance directors at mining operators, procurement leads at construction rental companies, aftermarket service heads at OEMs, and plant engineers at alloy steel foundries. Primary interview insights triangulate against customs and trade data for alloy steel imports, SEC filings from publicly traded mining equipment suppliers, ISO certification registry databases, and provincial environmental bureau audit disclosures. Bottom-up unit demand estimates from tire profile specifications reconcile with top-down mining fleet expenditure patterns.
Assumptions held fixed include MEE emissions enforcement intensity in China, EPA extended service interval compliance in US mining fleets, and CE marking harmonization progress across EU machinery safety frameworks. The projection horizon models segmentation across product type, material grade, application environment, and end-user procurement authority. CAGRs derive from replacement cycle velocity in Chilean copper operations, alloy price elasticity in forged-component manufacturing, and rental channel penetration rates in German construction aggregates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Turkish fabrication houses or accelerated composite material breakthroughs would shift outcomes beyond modeled ranges. Cross-checking against TGA-equipment safety framework alignment with ISO durability standards is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Global Bead Wire (Tyre Bead Wire) Market
Tires and Wheels
Europe Green Tire Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Automotive Wheel Spindle Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Smart Tire Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Tire Bead Wire Market
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Bicycle Rim Market