
 Automotive Airbag Fabric Market | 2026-2036
Automotive Airbag Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Airbag Fabric Market Analysis
The EU Green Deal's material circularity mandates is consolidating procurement criteria across European automotive supply chains. Toray Industries leverages its polymer-to-fiber vertical integration to secure long-term OEM contracts in Japan and Europe. Hyosung Advanced Materials anchors its position through high-tenacity nylon 66 capacity at its South Korean facilities. Teijin Limited differentiates via aramid fiber expertise transferred from aerospace and ballistic protection divisions.
Automotive airbag fabric comprises engineered textile substrates—typically nylon 6,6 or polyester multifilament yarns woven to precise densities between 200–400 grams per square meter—designed to withstand instantaneous inflation pressures exceeding 200 kPa while maintaining controlled permeability for deployment timing. Woven technology dominates current output volumes owing to established tear-strength reliability and cost-efficient loom throughput, while coated laminates capture expanding margin pools as OEMs specify heat-resistant silicone barriers for engine-bay-proximate curtain modules. Front airbags retain the largest application share by unit volume, though curtain airbags represent the fastest-growing configuration as side-impact protocols tighten across multiple jurisdictions.
NHTSA's Federal Motor Vehicle Safety Standard 208 and the EU's General Safety Regulation collectively mandate phased expansion of occupant protection zones, directly inflating fabric procurement specifications for knee and center-console airbag modules. China's GB standards on automotive passive safety, administered by MIIT, require localized testing certification that filters non-domestic suppliers from native OEM programs. Stakeholders must monitor evolving chemical compliance thresholds under REACH and state-level extended producer responsibility frameworks to preempt fiber reformulation costs.
Market Dynamics
Multi-chamber airbag configurations are compressing fabric specifications across mid-range vehicle platforms, forcing suppliers to reconcile performance differentiation with volume-scale cost structures.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 208:Phased expansion of occupant protection zones mandates additional knee and center-console airbag modules, directly inflating fabric procurement volumes across North American OEM programs.
- Side-impact protocol tightening:Curtain airbag configurations are capturing specification share as regulatory bodies in Germany, Japan, and the United States impose stricter lateral collision standards.
- High-tenacity nylon 66:South Korean and Japanese fiber producers are scaling specialized polymer capacity to meet tear-strength requirements exceeding 200 kPa instantaneous pressure tolerance.
Market Restraints
- Petrochemical feedstock volatility:Caprolactam and adipic acid input costs for nylon 6,6 synthesis fluctuate with crude oil derivatives, compressing margin predictability for non-integrated weavers.
- East Asian supply concentration:Polymer-to-fiber capacity clusters in South Korea and Japan create geographic vulnerability to regional logistics disruptions or trade policy shifts.
- REACH chemical compliance thresholds:ECHA's evolving substance restrictions on flame retardants and processing aids force iterative fiber reformulation, extending qualification timelines.
Strategic Opportunities
- Engine-bay-proximate curtain modules:Heat-resistant silicone-coated laminates command expanding margin pools as OEMs relocate side-impact protection closer to thermal zones.
- India's PLI scheme for automotive textiles:Domestic component manufacturing incentives are attracting tier-1 suppliers to establish captive weaving operations near Chennai and Pune assembly clusters.
- Aramid-polyester hybrid substrates:Ballistic protection fiber expertise from aerospace divisions is transferring to automotive applications, enabling lighter-weight modules with equivalent pressure containment.
Industry Challenges
- Silicone coating certification timelines:Heat-aging validation protocols for engine-compartment-rated fabrics extend development cycles by 18-24 months, delaying revenue recognition.
- Multi-jurisdiction homologation complexity:China's GB standards administered by MIIT require localized testing certification that fragments engineering resources across parallel qualification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Airbag Fabric Market |
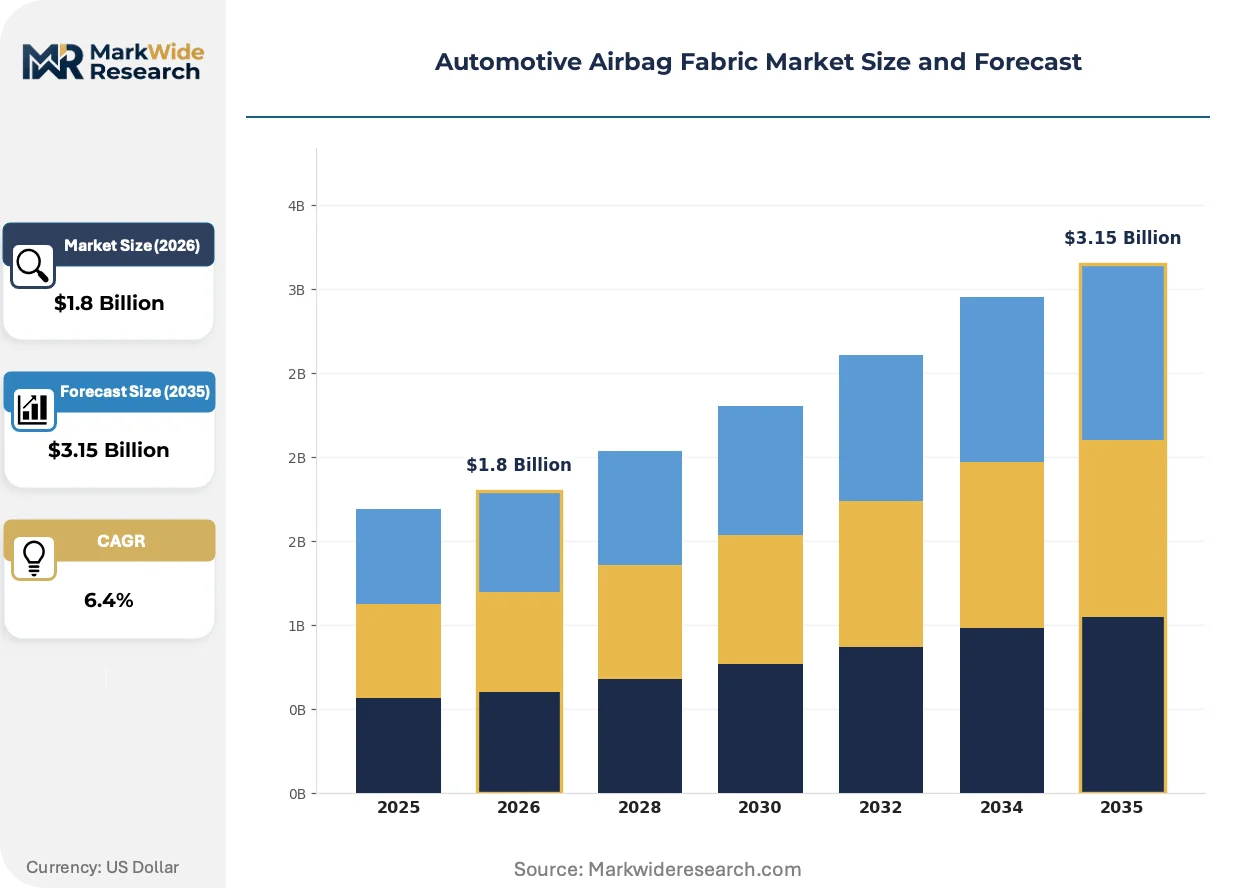
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
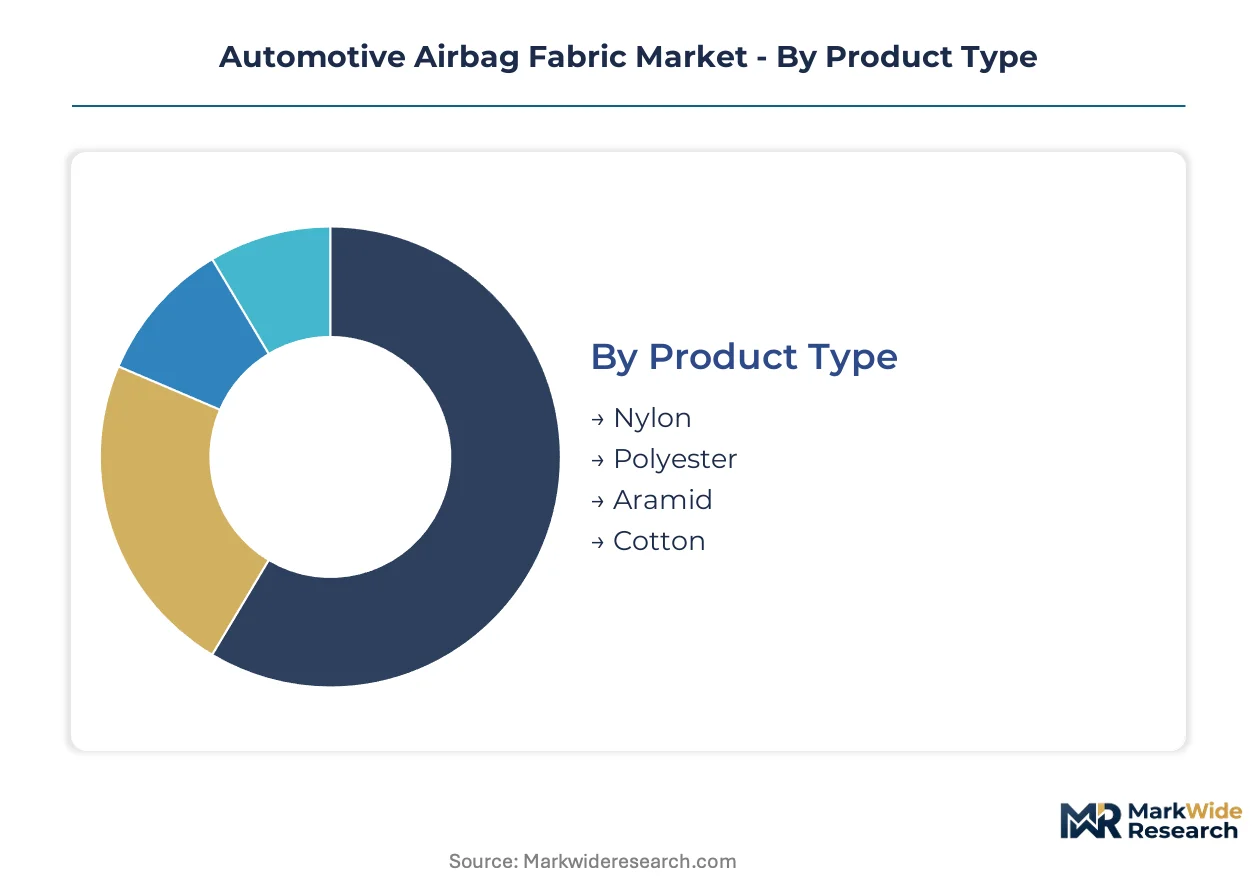
| Segmentation | Product Type: Nylon, Polyester, Aramid, Cotton Application: Front Airbags, Side Airbags, Curtain Airbags, Knee Airbags Technology: Woven, Non-Woven, Coated, Laminated End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Manufacturers |
| Companies Covered | Toray Industries, Hyosung Advanced Materials, Toyobo Co., Ltd., Teijin Limited, Kolon Industries, Asahi Kasei Corporation, HMT (Xiamen) New Technical Materials, Indorama Ventures, Global Safety Textiles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Airbag Fabric Market Emerging Trajectories
Silicone barrier coatings and hybrid fiber architectures are compressing traditional woven-dominant supply structures while regulatory fragmentation accelerates regional specialization.
Silicone-coated laminates are modularizing airbag fabric construction by separating substrate engineering from thermal protection layers. Tier-1 suppliers in Germany and the United States are qualifying these stack configurations for engine-bay-proximate curtain modules. The technology is modularizing procurement patterns, enabling OEMs to source substrate and coating from distinct specialized vendors rather than integrated weavers.
REACH chemical traceability mandates are consolidating European automotive textile procurement criteria around certified polymer origin documentation. ECHA's substance of very high concern screening now extends to flame retardant additives used in coating formulations. German and French OEMs are responding by mandating blockchain-tracked fiber provenance from tier-2 yarn suppliers.
Long-term supply agreements with volume-tiered pricing are displacing spot-market purchasing for nylon 6,6 multifilament yarn. Japanese and South Korean OEMs are consolidating procurement through three-to-five-year contracts with polymer-to-fiber integrated suppliers. This pattern is most pronounced in Germany, where tier-1 airbag module assemblers seek captive supply commitments to hedge against caprolactam price volatility.
Automotive Airbag Fabric Market Segmentation
Automotive airbag fabric procurement decisions hinge on the interplay between instantaneous pressure tolerance requirements and cost-positioning across vehicle platforms. Segmentation reveals how material chemistry, module placement, and manufacturing technology each create distinct competitive arenas with divergent margin structures.
Product Type:
Buyer selection prioritizes tear-strength performance against raw material cost volatility, with polymer chemistry determining qualification timelines for multi-chamber configurations.
- Nylon:High-tenacity nylon 6,6 multifilament yarns dominate front and side airbag specifications due to tear-strength reliability exceeding 200 kPa. German and Japanese OEMs concentrate procurement through South Korean and Japanese fiber producers with polymer-to-fiber integration.
- Polyester:Lower-cost multifilament alternatives capture specification share in economy-tier vehicle platforms where deployment timing tolerances permit slightly reduced pressure containment. Demand clusters in India's domestic OEM programs under PLI scheme incentives.
- Aramid:Teijin Limited and aerospace-heritage suppliers transfer ballistic protection fiber expertise to enable lighter-weight modules with equivalent pressure ratings.
- Cotton:Legacy applications persist in specific regional aftermarket segments with limited thermal performance requirements.
Nylon leads on scale; aramid leads on momentum as lightweighting pressures intensify.
Application:
Regulatory mandate expansion across occupant protection zones is fragmenting engineering resources while concentrating procurement volumes in curtain configurations.
- Curtain Airbags:Side-impact protocol tightening in Germany, Japan, and the United States accelerates specification of engine-bay-proximate modules requiring heat-resistant silicone barriers. NHTSA Federal Motor Vehicle Safety Standard 208 and EU General Safety Regulation directly inflate fabric procurement for these lateral protection systems.
- Front Airbags:Retain the largest unit volume position as standard equipment across all vehicle tiers, with woven nylon 6,6 substrates maintaining cost-efficient loom throughput for high-volume deployment.
- Side Airbags:Seat-integrated configurations face specification compression as multi-chamber designs consolidate protection zones.
- Knee Airbags:NHTSA phased mandates for expanded occupant protection zones create incremental procurement specifications, though volumes remain subordinate to frontal and curtain modules.
Front airbags lead on scale; curtain airbags are climbing the fastest on regulatory momentum.
Technology:
Manufacturing process selection determines the separation between substrate engineering and thermal protection layers, with coating technologies commanding expanding margin pools.
- Woven:Established tear-strength reliability and cost-efficient loom throughput sustain dominance in current output volumes for standard interior-positioned modules.
- Coated:Silicone barrier coatings modularize procurement patterns, enabling OEMs to source substrate and coating from distinct specialized vendors for engine-compartment-proximate applications.
- Laminated:Stack configurations separate mechanical performance from thermal protection, attracting tier-1 supplier qualification investment in Germany and the United States.
- Non-Woven:Limited penetration in primary airbag applications; niche positioning in specific cushioning or supplemental restraint configurations.
Woven technology leads on scale; coated laminates lead on margin expansion.
End User:
Supply chain position determines captive weaving requirements versus outsourced procurement, with tier-1 module assemblers consolidating long-term polymer supply agreements.
- OEMs:Direct procurement of airbag fabric remains concentrated among premium German and Japanese manufacturers seeking polymer-origin traceability under REACH and EU Green Deal mandates.
- Tier-1 Suppliers:Airbag module assemblers in Germany and Japan are consolidating three-to-five-year volume-tiered contracts with integrated fiber producers to hedge against caprolactam price volatility.
- Aftermarket Providers:Fragmented demand for replacement modules follows vehicle parc age distribution with reduced performance specification stringency.
- Manufacturers:Captive weaving operations near Chennai and Pune assembly clusters are emerging under India's PLI scheme for automotive textiles.
Tier-1 suppliers lead on procurement volume concentration; OEM direct sourcing leads on specification stringency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive airbag fabric production originated in Japan and Germany during the 1980s as domestic OEMs developed integrated safety systems. These two markets established the technical standards and polymer-to-fiber integration models that subsequent regional entrants adapted. Today's supply geography reflects this heritage while incorporating new capacity clusters responding to localized regulatory mandates.
Germany
Curtain airbag specifications for engine-bay-proximate modules drive procurement from tier-1 suppliers with integrated weaving and coating operations. ECHA's REACH substance restrictions and the EU Green Deal's circularity mandates enforce blockchain-tracked fiber provenance requirements. Stuttgart and Wolfsburg assembly corridors anchor captive supply agreements between OEMs and polymer-integrated fiber producers.
Japan
Multi-chamber airbag configurations across mid-range vehicle platforms sustain demand for high-tenacity nylon 66 with tear-strength reliability exceeding 200 kPa. METI coordinates with JIS standards bodies to align domestic certification with export market requirements. Nagoya and Tokyo industrial corridors host polymer-to-fiber integrated suppliers serving both domestic OEMs and European transplant programs.
United States
NHTSA Federal Motor Vehicle Safety Standard 208 mandates phased expansion into knee and center-console modules, inflating fabric procurement specifications across Detroit Three programs. Side-impact protocol tightening accelerates curtain airbag adoption requiring heat-resistant silicone barriers. Michigan and Ohio assembly clusters concentrate tier-1 module assembler operations with three-to-five-year volume contracts.
South Korea
Specialized polymer capacity for nylon 66 synthesis scales to meet instantaneous pressure tolerance requirements from German and Japanese OEMs. Caprolactam and adipic acid feedstock costs fluctuate with crude oil derivatives, compressing margin predictability for non-integrated weavers. Busan-Ulsan industrial zones anchor fiber production with backward integration into polymer synthesis.
India
Domestic OEM programs under the PLI scheme for automotive textiles attract tier-1 suppliers establishing captive weaving operations. Economy-tier vehicle platforms specify polyester multifilament alternatives where deployment timing tolerances permit reduced pressure containment. Chennai and Pune assembly clusters emerge as procurement concentration points for localized module production.
Automotive Airbag Fabric Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a consolidated oligopoly where polymer-to-fiber integration determines cost position. Japanese and South Korean fiber producers anchor the supply base through captive polymer synthesis capacity, while European and North American tier-1 module assemblers concentrate procurement through long-term volume agreements. Three archetypes dominate: vertically integrated polymer-to-fiber specialists, technology licensors with aerospace heritage, and regional weavers serving domestic OEM programs under localized certification regimes. Competitive moves center on capacity expansion in high-tenacity nylon 66 and strategic partnerships for silicone coating qualification.
Within the integrated-fiber tier, Toray Industries exemplifies polymer-to-fiber vertical control securing long-term OEM contracts across Japan and Europe. Hyosung Advanced Materials anchors South Korean supply through high-tenacity nylon 66 capacity concentration. Teijin Limited occupies a position transferring aramid fiber expertise from aerospace and ballistic protection divisions into automotive lightweighting applications. These three entities represent the dominant competitive anchors shaping procurement patterns and qualification timelines.
| Leading Market Players |
|---|
| Toray Industries |
| Hyosung Advanced Materials |
| Toyobo Co., Ltd. |
| Teijin Limited |
| Kolon Industries |
| Asahi Kasei Corporation |
| HMT (Xiamen) New Technical Materials |
| Indorama Ventures |
| Global Safety Textiles |
| Others |
Supply Flow & Price Mechanics
Polymer-to-fiber vertical integration anchors both supply security and pricing power for tier-1 airbag fabric producers, with Japanese and South Korean integrated suppliers commanding premium positions against non-integrated weavers exposed to caprolactam volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silicone-coated laminates for engine-bay applications from woven nylon substrates and polyester alternatives. Price differentiation hinges on certification grade under NHTSA FMVSS 208 and EU General Safety Regulation compliance, plus volume-scale contract terms. Cost compression in polyester tier intensifies because India's PLI scheme attracts new weaving capacity. Economy-tier domestic OEMs in India exhibit highest price sensitivity; German premium OEMs prioritize traceability over unit cost.
Supply Chain Analysis
Freight cost differentials between polymer synthesis hubs in South Korea and weaving operations in Germany or the United States compress margins for non-integrated assemblers. Supply concentrates in South Korea, Japan, and Germany, with caprolactam, adipic acid, and high-tenacity multifilament yarn as critical inputs. Single-source vulnerability runs through East Asian polymer capacity clusters exposed to regional logistics disruption. Distribution runs through tier-1 module assemblers holding three-to-five-year volume contracts with integrated fiber producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
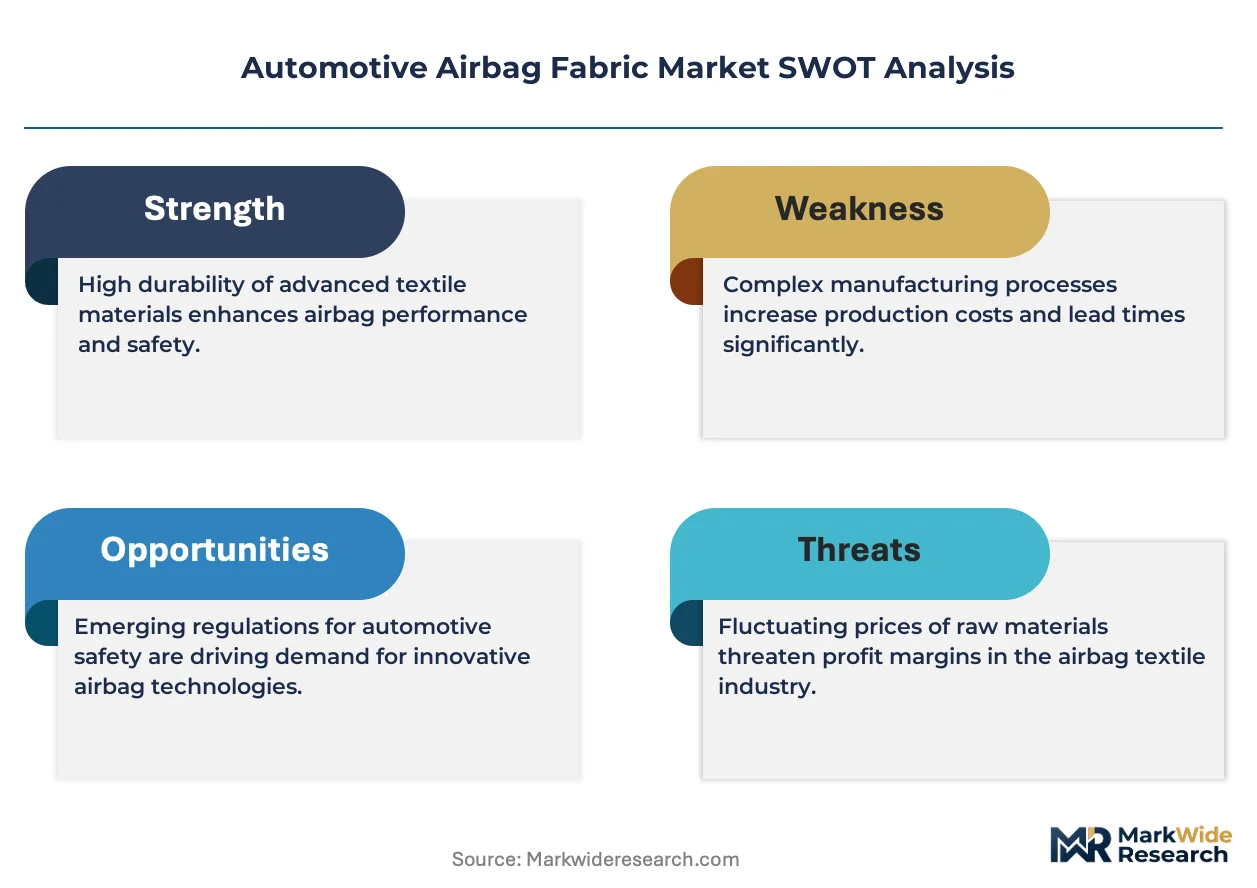
This market offers geographic-arbitrage value where REACH compliance costs in Europe diverge from India's PLI-scheme production incentives, enabling cost-positioned entrants to serve price-sensitive economy tiers.
For Market Incumbents: Acquire silicone coating qualification capabilities to defend against modular procurement patterns fragmenting substrate and barrier layer sourcing. Secure captive polymer supply agreements in South Korea to hedge caprolactam volatility. Invest in blockchain-tracked fiber provenance systems to meet ECHA's evolving traceability mandates and maintain German OEM contract access. For New Entrants and Emerging Players: Silicone barrier coating expertise transferred from industrial textiles offers entry into engine-bay-proximate curtain modules where premium pricing persists. Target India's domestic OEM programs under PLI scheme incentives where polyester specifications tolerate lower pressure containment. Pursue joint qualification pathways with tier-1 module assemblers seeking second-source substrate supply. For Investors and Strategic Acquirers: Consolidation pressure builds where polymer-to-fiber integration gaps expose mid-scale weavers to margin compression from feedstock volatility. Long-term viability favors integrated specialists with backward control over caprolactam supply and qualified coating partnerships. Watch for REACH substance restriction announcements as inflection signals triggering fiber reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive caprolactam supply insulates Hyosung and Toray from crude derivative volatility. |
| Silicone Coating Qualification Investment | Heat-aging validation for engine-bay modules commands margin premiums from German OEMs. |
| Long-term Supply Agreement Structuring | Volume-tiered contracts with Japanese OEMs displace spot purchasing for nylon 66 yarn. |
| Blockchain Traceability Implementation | Fiber provenance documentation satisfies ECHA's REACH substance screening for European supply. |
| Geographic Manufacturing Footprint Expansion | Captive weaving near Chennai and Pune assembly clusters captures India's PLI scheme benefits. |
Methodological Framework
Direct dialogue with tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fiber producer technical directors grounded this analysis in operational reality. Secondary validation drew from NHTSA FMVSS filings, ECHA REACH substance registrations, vehicle production databases, and customs trade records for caprolactam and adipic acid flows. Bottom-up modeling of airbag content per vehicle by platform triangulated against top-down OEM procurement spend estimates.
Segment-level outputs across material chemistry, module placement, manufacturing technology, and end-user supply chain position were generated over the projection horizon. CAGRs were derived from regression analysis of historical procurement volumes against regulatory mandate implementation timelines, with inputs including multi-chamber airbag adoption curves and curtain airbag penetration by vehicle class.
The model holds under steady regulatory implementation schedules and stable petrochemical feedstock pricing; deviation in REACH substance restriction timing or crude oil derivative volatility would shift fiber substitution patterns and integrated supplier margins. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Heated Steering Wheel Market
Automotive Interior & Exterior
India Automotive Door Seals Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Automotive Display Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Sealants Market
Automotive Interior & Exterior
Heated Windshield Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Automotive Intelligent Lighting System Market