
 Automotive Fabric Market | 2026-2036
Automotive Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fabric Market Intelligence
The EU Green Deal is rebalancing procurement criteria across European automotive supply chains, compelling fabric suppliers to certify recycled content ratios and lower carbon footprints. Toyota Boshoku leverages its vertical integration from yarn to seat assembly to control cost structures across Asia. Sage Automotive Interiors anchors North American supply through dedicated dyeing and finishing capacity in the southeastern United States. Lear Corporation competes on modular seating systems where fabric specification ties directly to platform economics for electric and hybrid architectures.
Automotive fabric encompasses woven, knitted, and non-woven textile structures engineered from synthetic or natural fibers, typically specified to meet abrasion resistance above 20,000 Martindale cycles, flammability standards, and dimensional stability under temperature cycling from minus forty to eighty degrees Celsius, serving primarily as interior surface materials for occupant contact and acoustic management. Upholstery commands the largest value pool given its visibility and touchpoint density, though headliners represent the fastest-growing application as acoustic and thermal management requirements intensify in electric vehicles where powertrain noise masking differs fundamentally from combustion architectures. Flame retardant treatments concentrate margin capture in commercial vehicle and premium passenger segments where regulatory thresholds exceed baseline passenger car requirements.
The EPA governs volatile organic compound emissions from automotive interior materials through testing protocols that directly shape fabric finishing chemistry selections in the United States, while REACH restricts specific flame retardant and dye substances across European supply chains, forcing reformulation investments. China's GB standards and MIIT circular economy directives are tightening recycled content verification for domestically produced automotive textiles. Stakeholders must monitor divergence between regional chemical compliance regimes when configuring global sourcing footprints and capital allocation for treatment capacity.
Market Dynamics
Electric vehicle platform architectures are reconfiguring material specifications across automotive interiors, forcing fabric suppliers to engineer for acoustic dampening and thermal management properties absent in combustion-engine vehicles.
Growth Catalysts
- EU Green Deal procurement mandates:European OEMs now require certified recycled content ratios in seat upholstery and headliner substrates, redirecting converter investments toward bio-based polyester feedstocks.
- China MIIT circular economy directives:Domestic automotive textile producers face tightening verification standards for recycled material incorporation, accelerating domestic supply chain reconfiguration.
- Lightweighting imperatives:EV battery weight penalties are compressing allowable mass for interior components, pulling demand toward engineered non-woven structures with superior strength-to-weight ratios.
Market Restraints
- Petrochemical feedstock volatility:Synthetic fiber production depends on purified terephthalic acid and caprolactam pricing, exposing margin structures to crude oil derivative swings.
- Dyeing capacity concentration:Wet processing for automotive-grade colorfastness concentrates in coastal China and southeastern United States, creating single-point vulnerability for global supply.
- REACH substance restrictions:ECHA limitations on specific halogenated flame retardants force reformulation of commercial vehicle fabrics, extending qualification timelines by 12-18 months.
Strategic Opportunities
- Underpenetrated Indian passenger vehicle interiors:Domestic OEMs are localizing seat assembly, creating openings for regional fabric converters with GB standards-adjacent certification capabilities.
- Acoustic management in EV headliners:Powertrain noise masking requirements are elevating technical textile specifications for ceiling substrates, expanding addressable value per vehicle.
- Digital textile printing convergence:Direct-to-fabric inkjet systems are compressing minimum order quantities and lead times, enabling mass customization for limited-production EV platforms.
Industry Challenges
- Color matching across distributed supply chains:OEM brand consistency requirements strain dye lot control when yarn spinning, weaving, and finishing occur across three or more countries.
- Flammability certification fragmentation:Divergent FMVSS 302, ECE R118, and GB 8410 test protocols force redundant testing investments for global platform suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fabric Market |
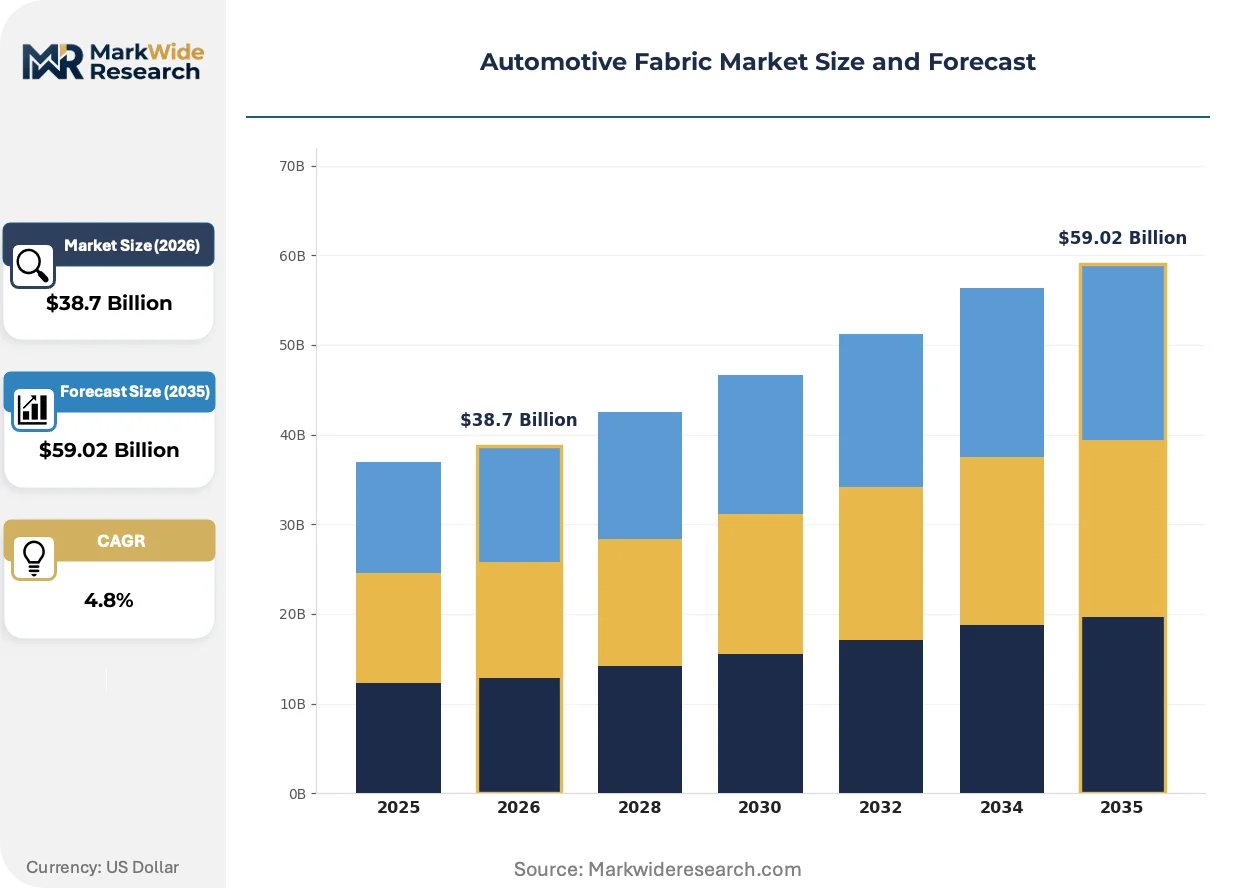
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Nylon, Cotton, Vinyl End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Fabric Treatment: Coating, Flame Retardant, Waterproofing, Stain Resistance Application Area: Upholstery, Carpeting, Headliners, Door Panels |
| Companies Covered | Toyota Boshoku, Sage Automotive Interiors, Lear Corporation, Autoneum, Seiren Co., Ltd, Faurecia, Grupo Antolin, Freudenberg Performance Materials, Adient, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fabric Market Strategic Shifts & Innovations
Material science advances are collapsing the traditional separation between aesthetic and functional layers in automotive interiors, enabling single-substrate solutions that previously required multi-material lamination.
Solution-dyed nylon 6,6 is unifying color permanence and abrasion resistance in a single fiber construction. Premium EV platforms are specifying this material for seat faces and bolsters to eliminate separate finishing steps. The technology is unifying what were historically distinct yarn production and piece-dyeing supply chain nodes, compressing converter margins in commodity upholstery tiers.
REACH authorization requirements for cyclic siloxanes in soft-touch coatings are forcing reformulation of polyurethane surface treatments across European supply chains. Finish houses are migrating to water-based alternatives with higher cure energy requirements. Commercial vehicle seating in Germany and France faces the steepest compliance cost escalation, with some suppliers exiting the segment rather than absorbing capital equipment upgrades.
Fleet operators and mobility-as-a-service providers are compressing replacement cycles for high-wear interior components, shifting procurement from platform-integrated supply toward aftermarket service contracts. This disintermediates traditional Tier 1 seating suppliers from recurring revenue streams. The pattern is most visible in North American and European urban ride-hail deployments, where vehicle utilization rates exceed 200,000 annual kilometers.
Automotive Fabric Market Segmentation
Automotive fabric procurement divides sharply between platform-integrated supply for new vehicle assembly and replacement cycles for fleet refurbishment. Specification intensity varies dramatically across these channels, with OEM programs demanding full material certification while aftermarket buyers prioritize cost compression and lead-time reliability.
Material Type:
Upgrade cycles for vehicle interiors accelerate replacement demand for higher-performance substrates that outlast original specifications in commercial applications.
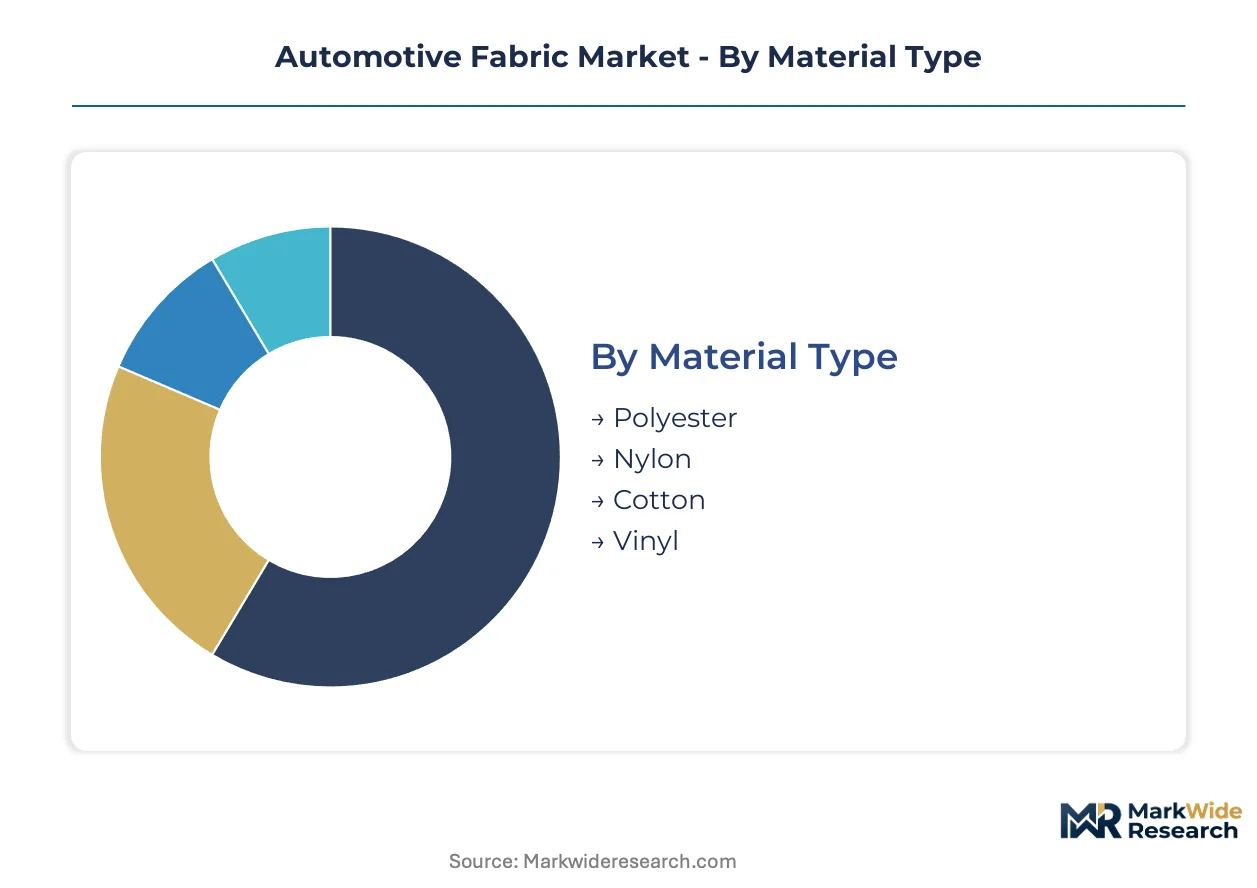
- Polyester:Dominates seat upholstery and headliner substrates through solution-dyed variants that eliminate separate finishing steps. European OEMs under EU Green Deal mandates now specify certified recycled PET content above 30 percent, redirecting converter investments toward chemical recycling capacity in Germany and Spain.
- Nylon:Commands premium seating positions through nylon 6,6 constructions unifying abrasion resistance above 40,000 Martindale cycles with inherent flame retardancy. Lear Corporation and Toyota Boshoku specify this material for EV platforms where battery weight penalties intensify durability requirements.
- Cotton:Retains niche positioning in heritage luxury segments and commercial vehicle applications where natural fiber aesthetics justify higher maintenance costs.
- Vinyl:Serves commercial fleet and entry passenger segments through polyurethane-coated constructions offering liquid resistance and sanitization compatibility for high-utilization vehicles.
Polyester sits at the top of the volume ranking, with nylon climbing the fastest as electric vehicle platforms rewrite durability specifications.
End User:
Cost tier stratification separates specification-intensive platform supply from price-sensitive replacement channels.
- OEMs:Direct material specification authority rests with Volkswagen Group, Toyota Motor, and General Motors, who embed fabric selection into platform architecture decisions 36-48 months before production launch.
- Tier-1 Suppliers:Adient, Lear Corporation, and Toyota Boshoku consolidate converter relationships through dedicated yarn-forward partnerships that lock in dye lot consistency across multi-country supply chains.
- Aftermarket Providers:Fleet operators and mobility-as-a-service platforms compress replacement cycles below 24 months, creating demand for rapid-color-match inventory systems independent of original platform specifications.
- Vehicle Assemblers:Contract manufacturers in China and India source fabrics through trading houses rather than direct converter relationships, accepting wider specification tolerances in exchange for volume pricing.
Tier-1 suppliers capture the dominant value share, with aftermarket providers expanding most quickly as fleet utilization rates intensify wear-cycle frequency.
Fabric Treatment:
Application-specific performance requirements fragment treatment chemistry selection across passenger, commercial, and emergency vehicle segments.
- Coating:Polyurethane and silicone surface treatments enable soft-touch aesthetics while meeting REACH authorization constraints on cyclic siloxanes in European supply chains.
- Flame Retardant:Halogen-free formulations now dominate German and French commercial vehicle seating as ECHA restrictions eliminate legacy brominated systems, extending qualification timelines by 12-18 months.
- Waterproofing:Fluorocarbon-based repellency treatments face regulatory pressure from EPA and ECHA, driving migration to bio-based alternatives with shorter performance lifespans.
- Stain Resistance:C6 fluorochemistry remains standard for North American family vehicle segments despite environmental scrutiny, while European OEMs specify plasma-based nanocoatings with lower environmental persistence.
Flame retardant treatments command the steepest premium tier, with waterproofing gaining share fastest as outdoor-activity vehicle configurations multiply.
Application Area:
Volume concentration in visible touchpoints contrasts with technical specification intensity in acoustic and thermal management positions.
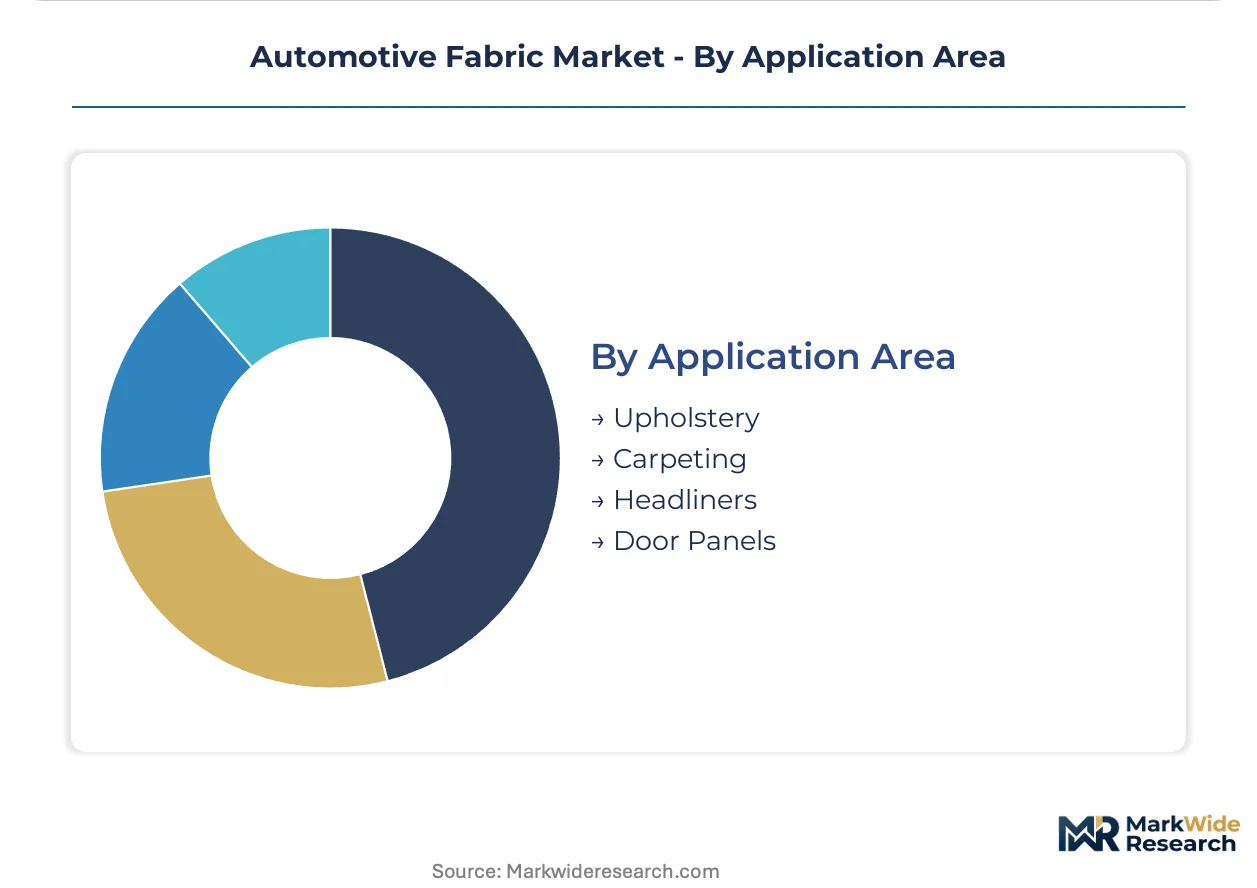
- Upholstery:Seat faces, bolsters, and headrests absorb 60-70 percent of interior fabric value through multi-layer constructions combining aesthetic surface with foam substrate adhesion.
- Carpeting:Tufted and needle-punched constructions for footwell and cargo applications prioritize stain masking and acoustic absorption over surface aesthetics.
- Headliners:Non-woven and knit-backed substrates now integrate thermal insulation and antenna accommodation for EV architectures where powertrain noise masking requirements differ fundamentally from combustion vehicles.
- Door Panels:Insert and armrest fabrics face the most severe cost compression as OEMs consolidate specifications across platform variants.
Upholstery retains the largest absolute volume position, with headliners on the steepest expansion trajectory as electric vehicle thermal and acoustic specifications escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive fabric manufacturing traces its modern scaling to post-war Germany and Japan, where seat assembly integration with vehicle production established the template for converter-tier supply chains now replicated across three continents.
China
Domestic EV production exceeding eight million units annually is compressing specification cycles for interior materials. MIIT circular economy directives now mandate recycled content verification for automotive textiles sold into domestic assembly plants. Yangtze River Delta converters in Shanghai and Jiangsu provinces are retrofitting chemical recycling lines to supply certified rPET yarn to BYD and NIO seating programs.
Germany
Volkswagen Group and BMW platform architectures drive specification authority for European supply chains. REACH authorization requirements for cyclic siloxanes in soft-touch coatings are forcing polyurethane reformulation across Baden-Württemberg finishing houses. Bavaria's automotive textile cluster around Ingolstadt and Munich anchors premium seating supply for Audi and BMW electric platforms.
United States
EPA volatile organic compound protocols shape finishing chemistry selections for Detroit Three OEM programs. Lear Corporation and Adient operate dedicated dyeing capacity in southeastern states to lock in color consistency for North American seat assembly. Michigan-based engineering centers coordinate fabric specification 36-48 months ahead of production launch for electric truck platforms.
Japan
Toyota Boshoku's vertical control from yarn spinning to seat assembly sets cost benchmarks for Asian supply chains. METI carbon neutrality roadmaps are accelerating bio-based polyester feedstock adoption in Nagoya-area converter operations. Kansai region chemical companies supply solution-dyed nylon 6,6 for premium EV seating positions requiring 40,000-plus Martindale cycle durability.
India
Maruti Suzuki and Hyundai Motor India are localizing seat assembly to compress logistics costs for sub-four-meter vehicle platforms. BIS automotive textile standards are converging toward GB-adjacent certification requirements. Tamil Nadu and Maharashtra fabric converters are qualifying with Suzuki Motor Gujarat and Hyundai Motor India Engineering to bypass trading house intermediation.
Automotive Fabric Market Key Industry Players
Premium-margin players sit above commodity-margin players across specification intensity and certification burden, with integrated converters capturing value through dye lot control while trading-house-dependent assemblers compete on volume pricing. The vendor base organizes into three strategic archetypes: yarn-to-seat integrators controlling cost structures through captive supply, regional specialists anchoring geographic demand clusters, and modular system suppliers bundling fabric into seating platform economics. Dominant competitive moves include backward integration into chemical recycling capacity and dedicated finishing investments to lock in OEM color consistency requirements.
Within the integrated converter tier, Toyota Boshoku exemplifies yarn-forward control through in-house production spanning fiber to finished seat assembly. Sage Automotive Interiors occupies a position among North American specialists with southeastern dyeing and finishing capacity dedicated to domestic OEM programs. Lear Corporation sits within the modular system supplier archetype, bundling fabric specification into platform economics for electric and hybrid architectures.
| Leading Market Players |
|---|
| Toyota Boshoku |
| Sage Automotive Interiors |
| Lear Corporation |
| Autoneum |
| Seiren Co., Ltd |
| Faurecia |
| Grupo Antolin |
| Freudenberg Performance Materials |
| Adient |
| Others |
Cost & Logistics Intelligence
EU Green Deal recycled content mandates are forcing converters to absorb chemical recycling capital costs, compressing margins in commodity upholstery tiers while premium nylon specifications capture pricing power through qualification scarcity. Buyers with 36-48 month platform lock-in cycles face stepped cost structures as bio-based feedstock premiums flow through supply contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates solution-dyed nylon 6,6 specifications from commodity polyester and vinyl alternatives. Price differentiation hinges on Martindale cycle certification thresholds and REACH-compliant flame retardant chemistry tiers. Cost compression in standard-grade upholstery is intensifying because Chinese converters are absorbing dyeing capacity consolidation premiums. Fleet operators and mobility-as-a-service platforms exhibit the highest price sensitivity due to compressed 24-month replacement cycles, while German premium OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Certification gating through FMVSS 302, ECE R118, and GB 8410 protocols fragments supplier qualification across export destinations, forcing redundant testing investments. Manufacturing concentrates in China, Germany, and the United States, with wet processing anchored in coastal China and the southeastern United States. Raw material flows draw from purified terephthalic acid and caprolactam feedstocks tethered to crude oil derivative pricing. Single-source vulnerability concentrates in dyeing capacity where color lot consistency requires dedicated finishing lines. Distribution runs through Tier 1 seating suppliers who bundle fabric into modular platform economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive fabric market compounds steadily as electric vehicle platform proliferation sustains specification intensity across interior material categories. Durability requirements intensify with battery weight penalties, creating persistent demand for engineered substrates.
For Market Incumbents:Hedge margin erosion in commodity tiers by securing captive chemical recycling capacity in Germany or Spain to capture EU Green Deal compliance premiums. Lock in 36-48 month dye lot consistency agreements with southeastern United States finishing houses before capacity constraints tighten. Battery weight penalties on EV platforms threaten to commoditize standard upholstery specifications faster than historical replacement cycles.
For New Entrants and Emerging Players:Begin with acoustic management substrates for EV headliners, where technical specifications outpace incumbent converter capacity expansion. Tamil Nadu and Maharashtra clusters offer the most penetrable qualification pathway for regional seat assembly localization. Pursue GB-adjacent certification capabilities to bypass trading house intermediation in Indian passenger vehicle programs.
For Investors and Strategic Acquirers:Asymmetric upside sits with regional specialists controlling dedicated dyeing capacity in automotive manufacturing corridors. Five-to-ten year viability favors converters with backward integration into yarn spinning rather than trading-house-dependent assemblers. Watch for MIIT circular economy directive enforcement intensity as the inflection signal for recycled content premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Capacity Investment | Captures EU Green Deal recycled PET mandates for Volkswagen Group and BMW programs. |
| Solution-Dyed Nylon 6,6 Qualification | Consolidates Toyota Boshoku and Lear Corporation specifications for EV durability tiers. |
| Southeastern US Dyeing Footprint | Locks color consistency for Detroit Three OEM electric truck platform launches. |
| Acoustic Headliner Substrate Development | Addresses thermal and noise masking requirements unique to BYD and NIO architectures. |
| Halogen-Free Flame Retardant Reformulation | Meets ECHA restrictions for German and French commercial vehicle seating contracts. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers with secondary validation. Sources included vehicle production databases, IHS Markit registration data, customs and trade flow records, and SEC filings from seating system suppliers. Bottom-up volume modeling and top-down market sizing triangulated across yarn production, converter capacity, and vehicle assembly data.
Historical reference periods anchored the projection horizon to documented specification cycles and platform launch cadences. Segmentation dimensions spanned material type, end user category, fabric treatment chemistry, and application area, with additional modeling for propulsion architecture differentiation between combustion and electric platforms. CAGRs were derived from regression analysis against vehicle production forecasts and content-per-vehicle assumptions. Key inputs included MIIT circular economy directive implementation timelines and REACH authorization requirement phase-ins.
Caveats apply where petrochemical feedstock volatility or ECHA substance restriction expansions could materially shift the outlook. Forecasts reflect assumptions around OEM platform standardization rates and recycled content verification protocol adoption. A model refresh is warranted upon material change in EU Green Deal procurement mandate enforcement or MIIT directive implementation intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market
Automotive Interior & Exterior
Automotive Baggage Handling System Market
Automotive Interior & Exterior
North America Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Convertible Top Market
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Heated Windshield Market
Automotive Interior & Exterior
Automotive Mudguards Market
Automotive Interior & Exterior
Automotive Seat Covers Market
Automotive Interior & Exterior
Windscreen Washer System Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
Automotive Wooden Interior Decorative Market