
 Automotive Auto Dimming Mirror Market | 2026-2036
Automotive Auto Dimming Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Auto Dimming Mirror Market Analysis
The gap between premium electrochromatic systems and commodity manual-dimming units is repositioning supplier portfolios across the automotive mirror value chain. Gentex Corporation leverages its electrochromatic technology leadership to sustain dominant positions in interior mirror supply to North American OEMs. Magna International anchors exterior mirror assembly through integrated electronics manufacturing across multiple vehicle platforms. Ficosa International S.A. competes on smart-mirror development, combining camera integration with traditional dimming functions.
Automotive auto dimming mirrors incorporate electrochromatic gel layers between conductive glass substrates that darken automatically when forward-facing sensors detect headlight glare, primarily eliminating driver distraction and improving nighttime safety. Interior mirrors using electrochromatic technology dominate current OEM fitment due to established reliability and lower integration complexity versus exterior applications. Smart mirrors represent the fastest-expanding segment as camera-monitor systems displace conventional reflective glass in premium vehicle programs, while manual dimming persists in cost-sensitive economy segments where margin pools remain thin.
NHTSA Federal Motor Vehicle Safety Standards and ECE R46 regulations in Europe mandate minimum field-of-view and glare-control performance, directly shaping product certification requirements for mirror suppliers. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces parallel visibility standards that constrain market entry for non-compliant manufacturers. Stakeholders must monitor divergent regional timelines for camera-based mirror legalization and assess whether electrochromatic technology retains relevance as display-based alternatives achieve regulatory approval.
Market Dynamics
Camera-monitor systems are compressing the addressable market for reflective glass mirrors as regulators in Japan, Europe, and the United States advance divergent approval timelines for display-based visibility systems. This technological substitution pressure forces electrochromatic suppliers to defend their core interior mirror business while hedging into smart-mirror electronics.
Growth Catalysts
- NHTSA glare-reduction mandates:Federal Motor Vehicle Safety Standards in the United States require automatic dimming performance in specified vehicle categories, sustaining baseline demand for compliant electrochromatic systems.
- Premium passenger vehicle electrification:Battery-electric platforms from German and Japanese OEMs bundle advanced interior electronics, expanding fitment rates for electrochromatic mirrors with integrated compass and telematics displays.
- ECE R46 compliance requirements:European field-of-view and glare-control standards constrain non-compliant suppliers, protecting incumbent electrochromatic manufacturers with established certification pathways.
Market Restraints
- Indium tin oxide supply concentration:Conductive coating materials for electrochromatic glass substrates depend on limited refining capacity, exposing mirror manufacturers to input cost volatility and geographic supply risk.
- Camera-monitor substitution threat:Display-based rear visibility systems eliminate the physical mirror entirely, threatening electrochromatic technology with functional obsolescence in premium vehicle segments where adoption begins.
- Legacy vehicle fleet inertia:Manual-dimming mirrors persist in economy segments where OEM procurement prioritizes unit cost over safety feature content, capping addressable market expansion.
Strategic Opportunities
- India automotive safety regulation tightening:Bureau of Indian Standards proposals for enhanced visibility requirements create a compliance-driven entry window for electrochromatic suppliers as domestic OEMs upgrade feature content.
- Camera-electrochromatic convergence:Hybrid smart-mirror architectures combine physical reflective surfaces with overlay camera feeds, preserving electrochromatic dimming while adding digital functionality.
- Commercial vehicle aftermarket channel:Fleet operators in long-haul trucking segments represent an underserved retrofit opportunity for glare-reduction upgrades outside OEM new-vehicle supply chains.
Industry Challenges
- Electro-optical engineering talent scarcity:Specialized expertise in gel-layer chemistry and sensor integration remains concentrated among legacy suppliers, constraining new entrant capability building.
- Dual certification timeline compression:Simultaneous pursuit of NHTSA, ECE R46, and Japan MLIT approvals demands parallel testing resources and extends product launch cycles.
- Legacy vehicle electronics integration:Retrofitting electrochromatic systems into older CAN bus architectures requires protocol adaptation that fragments engineering resources across model-year variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Auto Dimming Mirror Market |
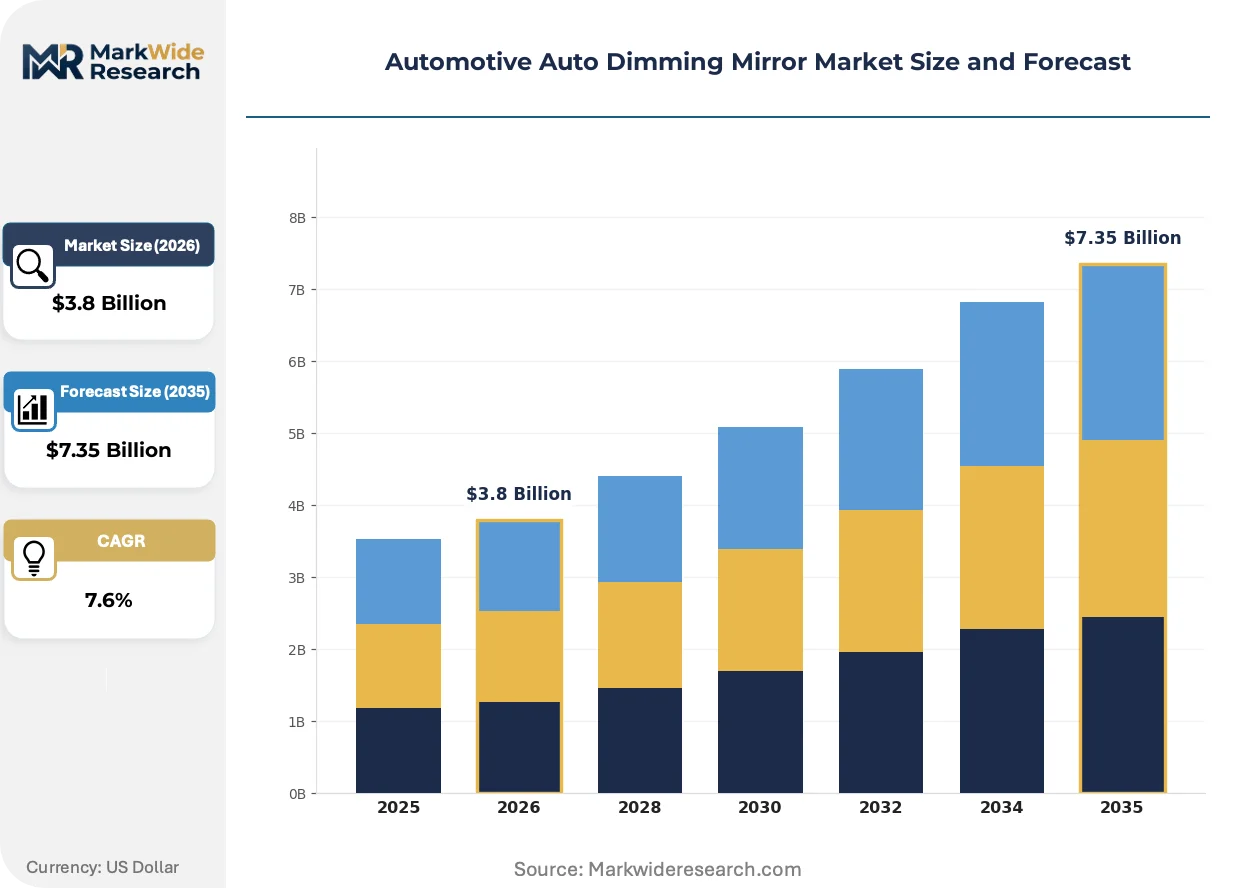
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Mirrors, Exterior Mirrors, Smart Mirrors, Rearview Mirrors Technology: Electrochromatic, Photochromatic, Manual Dimming, Adaptive Dimming End User: OEMs, Aftermarket Providers, Automotive Manufacturers, Fleet Operators Distribution Channel: Online Retail, Offline Retail, Distributors, Direct Sales |
| Companies Covered | Gentex Corporation, Magna International Inc., Ficosa International S.A., Samvardhana Motherson Group, Murakami Corporation, SL Corporation, Honda Lock Mfg. Co. Ltd., FLABEG Automotive Glass Group GmbH, Ichikoh Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Auto Dimming Mirror Market Emerging Trajectories
Electrochromatic technology is converging with camera and display systems in ways that preserve its core glare-reduction function while accommodating regulatory experimentation with mirrorless vehicle designs. Three developments are restructuring supplier priorities and OEM procurement criteria.
Electrochromatic gel formulations are unifying with thin-film transistor backplanes to enable zone-selective dimming that responds to specific glare vectors rather than uniform darkening. German and Japanese luxury OEMs are piloting these advanced interior mirrors in flagship electric vehicle programs. This unifying architecture compresses the functional gap between conventional electrochromatic systems and full camera-monitor replacements.
Japan's Ministry of Land, Infrastructure, Transport and Tourism is accelerating camera-based mirror legalization through amended safety standards that permit display systems in specified vehicle categories. This regulatory opening pressures electrochromatic suppliers to demonstrate relevance in hybrid architectures. European and North American regulators are observing Japanese implementation outcomes before finalizing parallel frameworks.
Fleet procurement for commercial vehicles is fragmenting across direct OEM supply, tier-one distributor networks, and emerging digital aftermarket platforms. Long-haul operators in the United States are sourcing retrofit glare-reduction systems through e-commerce channels that bypass traditional service bay distribution. This channel disintermediation concentrates in owner-operator segments where vehicle customization preferences override standardized OEM specifications.
Automotive Auto Dimming Mirror Market Segmentation
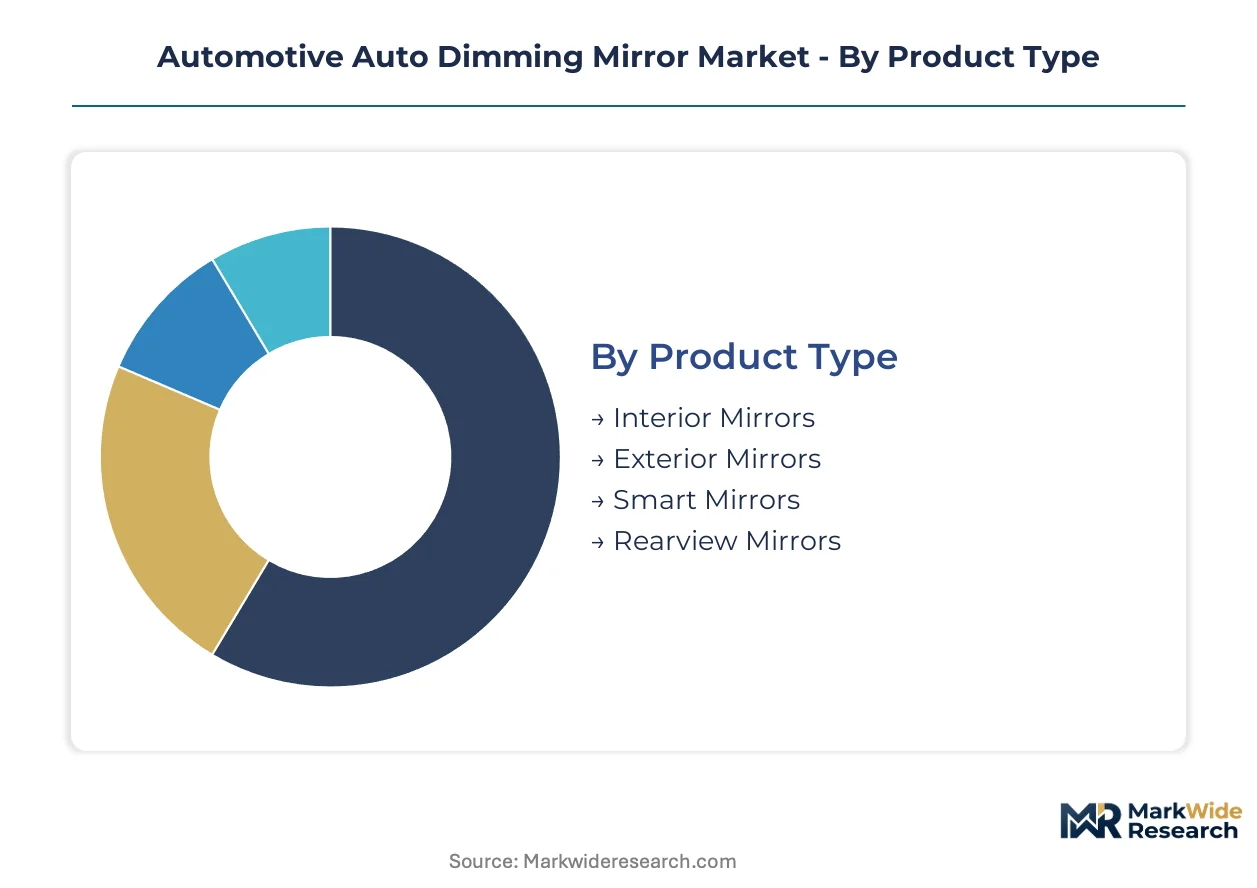
Segmentation in automotive auto dimming mirrors reveals how electrochromatic technology diffuses across vehicle price tiers and regulatory environments. Understanding these splits exposes where margin pools concentrate and where camera-monitor substitution threatens incumbent positions.
Product Type:
Volume concentrates in established interior applications while premium programs pioneer camera-integrated alternatives that compress future demand for reflective glass.
- Interior Mirrors:Electrochromatic gel layers between conductive glass substrates deliver automatic glare reduction through forward-facing sensors. OEM fitment dominates in German and Japanese premium passenger vehicles where NHTSA mandates sustain baseline demand.
- Smart Mirrors:Camera-monitor systems displace conventional reflective surfaces entirely, overlaying digital feeds with electrochromatic backup dimming in hybrid architectures. Japanese regulatory approvals for display-based visibility accelerate pilot programs among luxury electric vehicle platforms.
- Exterior Mirrors:Integration complexity and weatherproofing requirements constrain adoption to flagship vehicle programs.
- Rearview Mirrors:Manual-dimming variants persist in cost-sensitive economy segments where procurement prioritizes unit cost over safety content.
Today's leader: Interior Mirrors. Tomorrow's challenger: Smart Mirrors.
Technology:
Cost tier stratification separates certified electrochromatic systems from commodity manual alternatives, with adaptive variants bridging performance gaps in mid-market applications.
- Electrochromatic:Established reliability across conductive coating chemistries sustains dominant OEM supply positions. ECE R46 compliance requirements in Europe protect incumbent manufacturers with certified gel-layer formulations.
- Manual Dimming:Mechanical tab mechanisms serve economy vehicle segments and legacy fleet retrofits where feature content minimization drives procurement.
- Photochromatic:Light-sensitive materials respond to ambient conditions without electronic control modules.
- Adaptive Dimming:Sensor-integrated systems adjust darkening intensity based on glare vector analysis.
Certification barriers favor Electrochromatic dominance. Price compression elevates Manual Dimming resilience in emerging markets.
End User:
Customer type determines specification stringency, with direct OEM supply demanding full regulatory compliance while aftermarket channels tolerate retrofit adaptation complexity.
- OEMs:Integrated electronics manufacturing requirements and parallel NHTSA-ECE R46 certification timelines constrain supplier qualification. North American and German vehicle platforms specify electrochromatic interior mirrors as standard equipment in mid-tier trims and above.
- Fleet Operators:Long-haul trucking segments in the United States source glare-reduction upgrades through digital aftermarket platforms that bypass traditional service bay distribution. Owner-operator customization preferences override standardized specifications.
- Automotive Manufacturers:Battery-electric platform launches bundle advanced mirror electronics with compass and telematics displays.
- Aftermarket Providers:E-commerce channel growth concentrates retrofit demand among vehicle customization enthusiasts.
OEMs command specification authority. Fleet Operators represent the steepest expansion trajectory outside captive supply chains.
Distribution Channel:
Supply concentration in direct OEM relationships contrasts with channel fragmentation as commercial vehicle procurement migrates toward digital platforms.
- Direct Sales:Tier-one supplier contracts with German, Japanese, and United States OEMs lock in multi-year electrochromatic mirror supply agreements with embedded electronics integration.
- Online Retail:Digital platforms capture fleet operator and owner-operator retrofit demand for glare-reduction systems, disintermediating traditional service bay networks.
- Offline Retail:Brick-and-mortar automotive service centers handle warranty replacements and collision repair.
- Distributors:Regional inventory pooling supports just-in-time delivery to assembly plants.
Direct Sales anchor revenue stability. Online Retail gains share fastest in aftermarket fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochromatic engineering talent clusters in Michigan, Stuttgart, and Aichi Prefecture anchor mirror technology development. German and Japanese OEM integration programs concentrate specification authority in these manufacturing corridors. NHTSA, ECE R46, and Japan MLIT compliance timelines diverge across regulatory jurisdictions.
United States
NHTSA Federal Motor Vehicle Safety Standards mandate automatic dimming in specified vehicle categories, sustaining baseline electrochromatic demand. Michigan's automotive corridor hosts tier-one supplier engineering centers that lock in multi-year OEM contracts. Detroit-area manufacturing clusters concentrate interior mirror assembly for North American vehicle platforms.
Germany
ECE R46 compliance requirements protect incumbent manufacturers with certified gel-layer formulations against non-compliant entrants. Baden-Württemberg's precision electronics ecosystem supports conductive coating refinement for premium OEM programs. Stuttgart-based engineering teams pilot zone-selective dimming systems for flagship electric vehicle launches.
Japan
MLIT amended safety standards now permit camera-based mirror systems in specified categories, accelerating regulatory experimentation. Aichi Prefecture's Toyota-supplier network maintains electrochromatic interior mirror dominance through established reliability records. Nagoya-area manufacturing facilities supply both domestic OEMs and export programs to Southeast Asian markets.
India
Bureau of Indian Standards proposals for enhanced visibility requirements create compliance-driven entry windows for electrochromatic suppliers. Tamil Nadu's automotive belt attracts tier-one component manufacturing as domestic OEMs upgrade feature content. Chennai-based assembly plants increasingly specify automatic dimming for mid-tier passenger vehicle trims.
South Korea
Battery-electric platform launches from Hyundai and Kia bundle advanced mirror electronics with integrated telematics displays. Gyeonggi Province's supplier parks host electrochromatic module production for both domestic fitment and China export. Seoul Capital Area engineering centers develop hybrid smart-mirror architectures combining physical and camera-based visibility.
Automotive Auto Dimming Mirror Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the electrochromatic mirror value chain. The supplier base concentrates around three strategic tiers: integrated electronics manufacturers controlling full mirror assembly, specialized gel-layer chemistry houses supplying conductive substrates, and camera-system integrators hedging into hybrid architectures. Dominant competitive moves include backward integration into indium tin oxide coating capacity and strategic partnerships with tier-one distributors serving fleet aftermarket channels.
Within the integrated electronics tier, Gentex Corporation and Magna International exemplify divergent approaches to OEM supply chain positioning. Ficosa International S.A. occupies a specialist position at the convergence of traditional dimming and camera-monitor development. Japanese manufacturers including Murakami Corporation and Ichikoh Industries, Ltd. anchor the Asia-Pacific supply base through long-standing relationships with domestic vehicle programs. Samvardhana Motherson Group represents the emerging market fabrication archetype with expanding presence in Indian and European automotive corridors.
| Leading Market Players |
|---|
| Gentex Corporation |
| Magna International Inc. |
| Ficosa International S.A. |
| Samvardhana Motherson Group |
| Murakami Corporation |
| SL Corporation |
| Honda Lock Mfg. Co. Ltd. |
| FLABEG Automotive Glass Group GmbH |
| Ichikoh Industries, Ltd. |
| Others |
Supply Flow & Price Mechanics
Indium tin oxide spot pricing volatility cascades through electrochromatic mirror manufacturing into three-tier pricing structure across premium, standard, and economy levels. Conductive coating cost swings compress margins for mid-tier suppliers while German and Japanese OEMs lock in long-term offtake agreements that insulate flagship programs from raw material turbulence.
Pricing Analysis
Bundled electronics integration versus unbundled commodity glass separates pricing tiers in electrochromatic mirror procurement. OEM direct contracts command premium positioning through embedded compass and telematics displays, while aftermarket channels compete on unit cost with stripped-down manual-dimming alternatives. Price differentiation hinges on ECE R46 certification grade and volume scale commitments. Cost compression in economy segments intensifies because Indian and Southeast Asian OEMs prioritize procurement minimization over safety feature content. Fleet operators show highest price sensitivity; German luxury platforms least.
Supply Chain Analysis
India's phased manufacturing program and domestic-content mandates for automotive electronics are reshaping sourcing patterns for mirror assembly operations. Indium refining concentrates in China, South Korea, and Japan; electrochromatic gel formulation clusters in Michigan and Stuttgart. Mirror manufacturers draw from conductive glass substrates, sensor modules, and CAN bus integration hardware. Single-source vulnerability in indium tin oxide coating capacity exposes tier-one suppliers to geographic supply risk. Distribution runs through tier-one supplier contracts with just-in-time delivery to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automotive auto dimming mirrors rests on zone-selective dimming technology commanding premium positioning in battery-electric platforms. Gel-layer chemistry optimization and sensor integration density drive cost-down trajectories that protect incumbent profitability.
For Market Incumbents: Hedge core interior mirror revenue by accelerating hybrid smart-mirror development that preserves electrochromatic dimming alongside camera feeds. Camera-monitor substitution in Japanese luxury segments threatens reflective glass obsolescence; backward integration into indium tin oxide coating capacity secures input cost control against supply concentration risk. For New Entrants and Emerging Players: Bureau of Indian Standards visibility requirements in India opens a window for electrochromatic suppliers as domestic OEMs upgrade mid-tier trim specifications. Target commercial vehicle fleet retrofits through digital aftermarket platforms bypassing traditional service bay networks. Pursue certification-first entry strategy with parallel NHTSA and ECE R46 testing to qualify for German and North American OEM supply. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized gel-layer chemistry houses possessing certified conductive substrate formulations and established MLIT approval records. Long-term viability centers on electrochromatic relevance in hybrid architectures through the camera-monitor transition period. Watch Japanese regulatory outcomes for display-based mirror legalization as inflection indicator for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Zone-Selective Dimming Development | Pilot programs with Stuttgart-based engineering teams differentiate flagship electric vehicle mirror specifications. |
| Indium Tin Oxide Backward Integration | Captive coating capacity insulates margin structures from Chinese refining supply volatility. |
| Hybrid Smart-Mirror Architecture | Camera-electrochromatic convergence preserves core dimming function against display substitution threat. |
| India Regulatory Certification Investment | BIS compliance pathway unlocks Chennai-based assembly plant integration for domestic OEM programs. |
| Fleet Aftermarket Channel Partnership | Digital platform alliances capture long-haul trucking retrofit demand outside captive OEM supply chains. |
Methodological Framework
Direct dialogue with tier-one supplier procurement officers, OEM platform engineers, aftermarket distributors, and electrochromatic gel-layer chemists grounded qualitative assessment. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standards filings, ECE R46 certification databases, Japan MLIT regulatory amendments, vehicle production data from IHS Markit, and SEC disclosures from listed mirror suppliers. Bottom-up and top-down triangulation reconciled segment-level volume estimates with aggregate market sizing.
Bottom-up modeling built from vehicle production forecasts by platform, content-per-vehicle assumptions by trim tier, and electrochromatic penetration rates across OEM portfolios. Top-down analysis cross-checked against aggregate automotive electronics spending patterns and mirror-specific procurement data. Segmentation dimensions spanned product type, technology certification grade, vehicle class, propulsion architecture, and regional regulatory cluster. CAGRs derived from fitted growth curves anchored to disclosed supplier revenue trajectories and announced OEM platform launches across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under divergent camera-monitor legalization timelines and indium supply disruption scenarios. Forecasts reflect assumptions about regulatory harmonization pace and electrochromatic technology persistence in hybrid architectures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Global Automotive Carpeting Market
Automotive Interior & Exterior
Rear-View Mirror Market
Automotive Interior & Exterior
Automotive in-Vehicle Air Purifier Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Automotive Cowl Screen Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
India Automotive Door Seals Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market