
 Global Fleet Maintenance Software Market | 2026-2036
Global Fleet Maintenance Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fleet Maintenance Software Market Foresight
ISO 55000 certification for asset management is unwinding competitive barriers in fleet maintenance software, forcing vendors to demonstrate structured lifecycle management capabilities. Geotab leverages its native telematics platform to anchor maintenance alerts within real-time vehicle diagnostics. Samsara competes through edge-computing architectures that process sensor data before cloud transmission. Verizon Connect sustains its position via channel control across North American dealer networks.
Global Fleet Maintenance Software comprises digital platforms that schedule, track, and analyze vehicle servicing through integration with OBD-II ports, GPS modules, and ERP systems, primarily serving operators seeking to minimize unplanned downtime and extend asset lifecycles. Cloud-based deployment leads among mid-market buyers seeking lower capital commitment, while edge computing segments show the fastest expansion as latency-sensitive diagnostics migrate toward vehicle-side processing. Compliance tracking applications command premium pricing due to the complexity of multi-jurisdiction regulatory reporting.
FAA airworthiness directives and EPA emissions standards in the United States, alongside EU Green Deal reporting requirements enforced by national transport regulators, are mandating auditable maintenance documentation and accelerating replacement of paper-based logs. The EU AI Act will soon classify predictive maintenance algorithms by risk tier, altering how software vendors validate automated fault detection. Stakeholders must monitor whether emerging cybersecurity standards for connected vehicles become a prerequisite for fleet software procurement.
Market Dynamics
Predictive maintenance algorithms are compressing the traditional reactive service model, forcing fleet operators to restructure technician workflows and parts inventory around probability-based intervention schedules rather than fixed mileage intervals.
Growth Catalysts
- EU Green Deal emissions reporting:Mandatory digitization of maintenance records for commercial fleets operating across Germany, France, and the Netherlands creates immediate software procurement pressure.
- Telematics-OBD-II convergence:Real-time engine diagnostics streaming through cellular modules enables condition-based servicing that extends powertrain lifecycles.
- Third-party logistics consolidation:Large freight carriers in India and Brazil are centralizing maintenance operations across dispersed vehicle pools, requiring unified SaaS platforms.
Market Restraints
- Semiconductor supply concentration:Persistent shortages of automotive-grade microcontrollers from Taiwan-based foundries delay telematics hardware deployments.
- Interoperability friction:Proprietary data protocols from incumbent vehicle manufacturers lock maintenance data within walled gardens.
- Technician skill scarcity:Shortages of technicians trained in both mechanical systems and software diagnostics constrain implementation velocity.
Strategic Opportunities
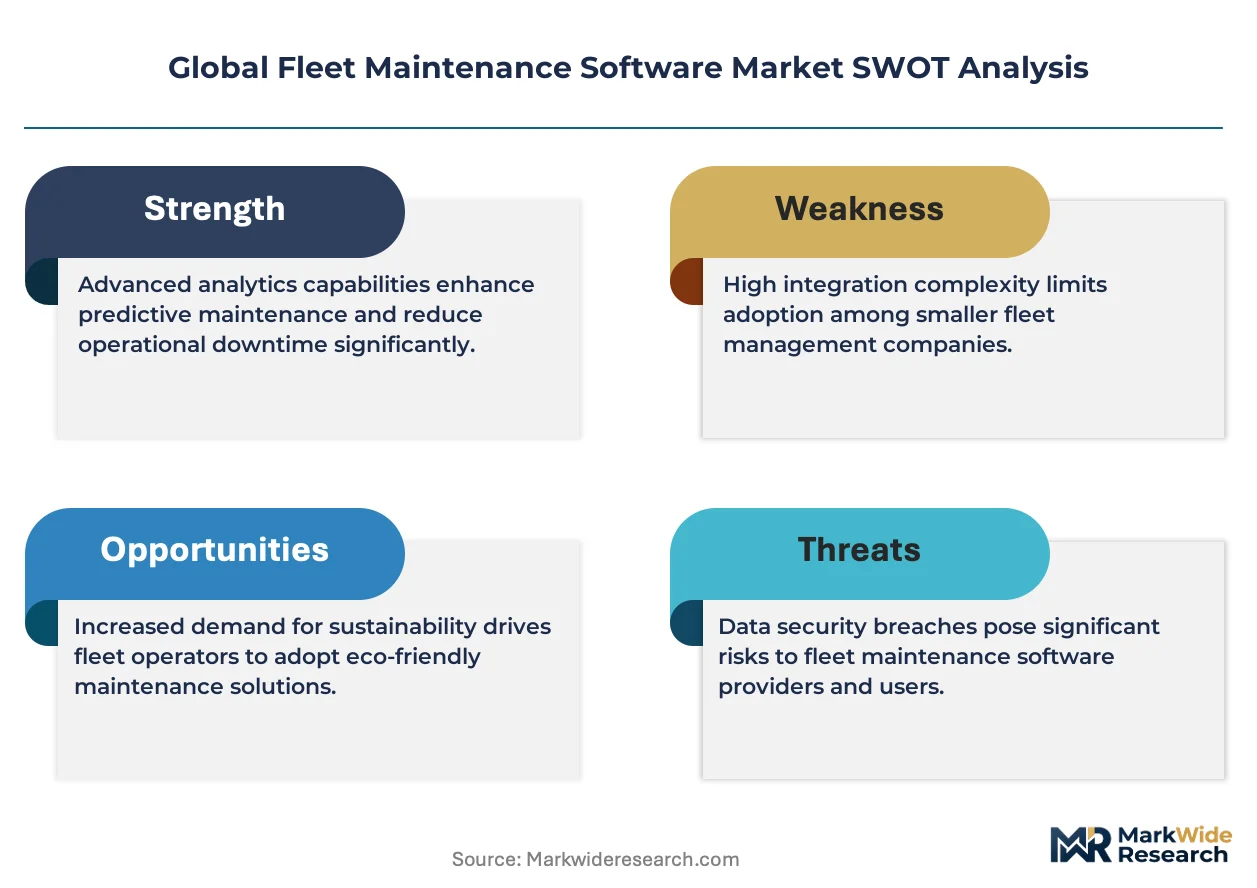
- EU AI Act algorithm validation:Early compliance with risk-tier classification for predictive fault detection creates differentiation among European vendors.
- Edge-to-cloud architecture convergence:Pairing vehicle-side inference with centralized fleet analytics opens new pricing tiers for latency-sensitive diagnostics.
- Indonesia's archipelago logistics:Maritime-dependent freight networks lack maintenance infrastructure, creating whitespace for remote diagnostics platforms.
Industry Challenges
- ISO 55000 certification timelines:Asset management standard compliance requires 12-18 month documentation overhauls that strain implementation resources.
- ERP integration complexity:Synchronizing maintenance modules with legacy SAP and Oracle deployments demands specialized middleware development.
- Cybersecurity standard fragmentation:Emerging connected vehicle security frameworks from NHTSA and UN ECE lack harmonization, complicating multi-jurisdiction deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fleet Maintenance Software Market |
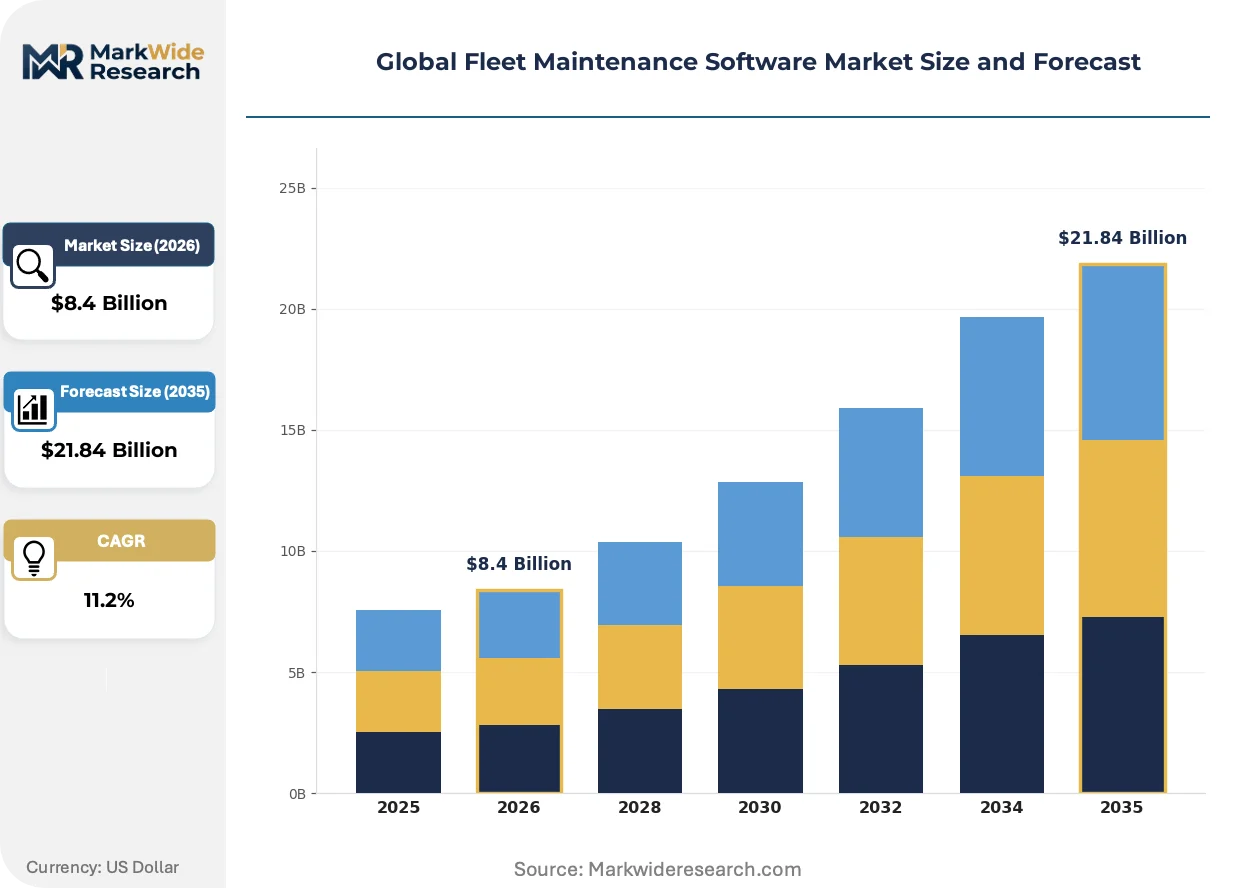
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $21.84 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing Application: Scheduling, Diagnostics, Inventory Management, Compliance Tracking, Reporting End User Industry: Logistics Providers, Public Transport Operators, Delivery Services, Construction Firms License Type: Subscription, Perpetual, Freemium, Pay-Per-Use, Enterprise |
| Companies Covered | Verizon Connect, OxMaint, RTA Fleet360, Lytx, Motive, Fleetio, Geotab, Teletrac Navman, Samsara, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fleet Maintenance Software Market Shifts & Advancements
Edge computing architectures are redistributing diagnostic intelligence from centralized servers toward vehicle-mounted processors, altering latency requirements and hardware procurement patterns across commercial fleet operations.
Digital twin technology is decomposing the traditional physical inspection cycle by creating virtual replicas of engine, transmission, and brake systems that simulate degradation under actual load profiles. Heavy-duty trucking operators in Germany and the United States are deploying these models to compress maintenance windows from quarterly to event-triggered interventions. The technology is decomposing established service revenue streams tied to scheduled shop visits.
The EU AI Act's risk-based classification system is mandating algorithmic transparency documentation for predictive maintenance systems deployed in passenger transport fleets. Vendors must now maintain audit trails for fault detection logic and retraining protocols. European operators of municipal bus networks face the steepest compliance burden, with France's national transport regulator already requiring pre-deployment validation.
Subscription-based pricing for maintenance software is displacing perpetual license models among mid-market fleet operators seeking to align costs with vehicle utilization. Equipment leasing companies in the United Kingdom and Australia are bundling software access into monthly per-vehicle rates. This shift is most pronounced in refrigerated transport, where temperature-sensitive cargo demands continuous monitoring uptime guarantees.
Global Fleet Maintenance Software Market Segmentation
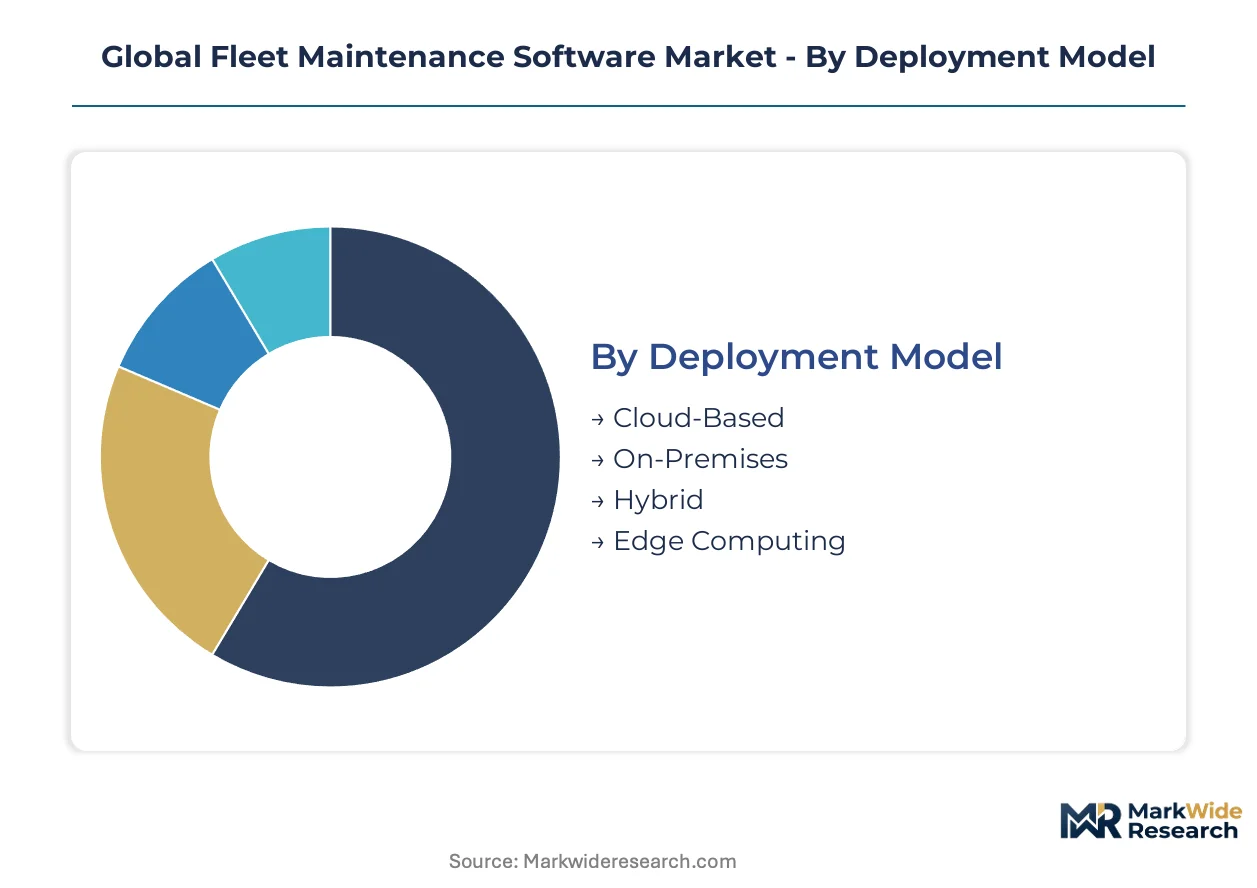
Fleet maintenance software segments diverge sharply between capital-intensive buyers favoring perpetual control and utilization-driven operators seeking variable cost structures. Deployment architecture and licensing flexibility determine vendor selection across logistics hubs in Germany, freight corridors in India, and municipal fleets in France.
Deployment Model:
Cloud-based solutions dominate domestic mid-market procurement in Germany and the Netherlands, while edge computing deployments concentrate in export-oriented long-haul trucking across Baltic freight corridors.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server infrastructure for fleet operators with under 500 vehicles. German logistics providers in the Rhine-Ruhr cluster favor this model to satisfy EU Green Deal documentation mandates without IT overhead.
- On-Premises:Single-tenant installations behind operator firewalls serve defense contractors and airport ground fleets with air-gapped security requirements. French military transport divisions mandate this architecture for classified vehicle movements.
- Hybrid:Split architectures keep sensitive compliance data local while pushing analytics to cloud instances. Dutch refrigerated transport operators deploy this model to balance temperature-data sovereignty with centralized fleet optimization.
- Edge Computing:Vehicle-mounted processors execute inference for latency-critical fault detection. Indian long-haul operators traversing cellular dead zones between Mumbai and Delhi rely on this architecture for uninterrupted diagnostics.
Cloud-based holds the largest share; momentum sits with edge computing.
Application:
Diagnostic modules command premium pricing due to sensor integration complexity, while compliance tracking accelerates fastest under regulatory pressure from EU transport authorities.
- Scheduling:Calendar-based service interval automation integrates with ERP systems for parts procurement. Brazilian third-party logistics consolidators use this module to synchronize maintenance across dispersed regional depots.
- Diagnostics:Real-time OBD-II streaming with predictive fault classification requires telematics hardware integration. German commercial vehicle operators deploy this capability to extend powertrain lifecycles under KBA inspection protocols.
- Inventory Management:Parts availability tracking links warehouse stock to vehicle location and pending service orders. Australian mining fleet operators in Western Australia leverage this function for remote site resupply.
- Compliance Tracking:Automated generation of auditable maintenance logs for regulator submission. French municipal bus networks face the steepest implementation burden under pre-deployment validation rules from the national transport regulator.
- Reporting:Customizable dashboards aggregating cost-per-mile, downtime frequency, and technician productivity. UK equipment leasing companies bundle standardized reports into monthly per-vehicle service agreements.
Diagnostics generates the highest revenue per deployment; compliance tracking is climbing the fastest.
End User Industry:
Logistics providers drive volume through centralized procurement, while public transport operators impose the most stringent certification requirements under passenger safety mandates.
- Logistics Providers:Freight carriers with heterogeneous vehicle pools require unified platforms across owned and contracted assets. Indian conglomerates consolidating regional trucking operations deploy SaaS solutions to replace fragmented paper systems.
- Public Transport Operators:Municipal bus and rail fleets face ISO 55000 asset management certification timelines of 12-18 months. German Verkehrsverbünde coordinate maintenance across multi-operator regional networks.
- Delivery Services:Last-mile operators with high vehicle turnover prioritize rapid onboarding and mobile-first technician interfaces. Brazilian e-commerce fulfillment networks in São Paulo adopt subscription pricing to match seasonal demand fluctuation.
- Construction Firms:Heavy equipment maintenance for off-highway vehicles demands integration with manufacturer-specific diagnostic protocols. Australian civil contractors in Queensland track excavator and grader servicing through specialized modules.
Logistics providers command the largest installed base; delivery services are gaining share fastest.
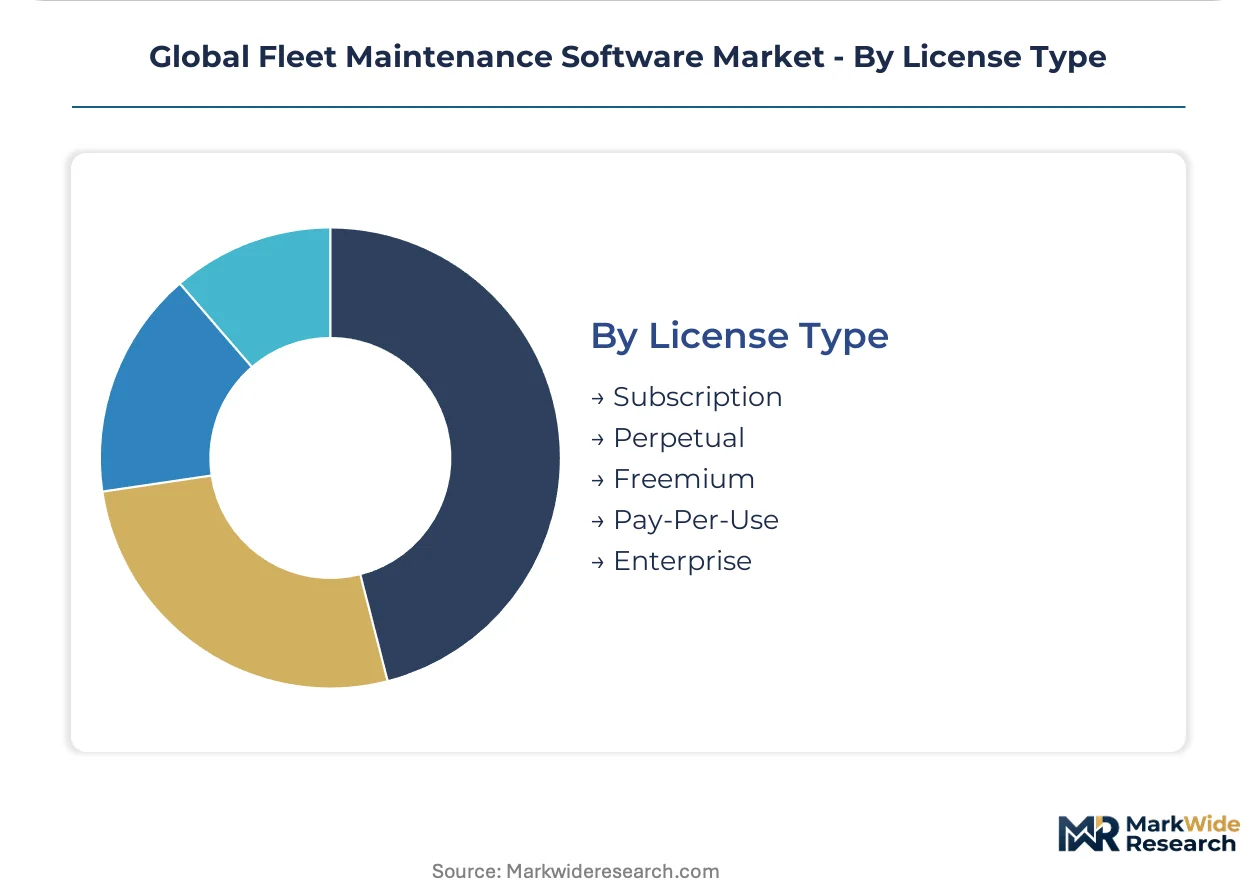
License Type:
Subscription models displace perpetual licenses among mid-market buyers seeking cost alignment with vehicle utilization, while enterprise agreements concentrate in multinational fleet operators.
- Subscription:Monthly or annual per-vehicle pricing with automatic feature updates. UK refrigerated transport operators favor this structure for continuous monitoring uptime guarantees tied to temperature-sensitive cargo.
- Perpetual:One-time license purchase with separate maintenance contracts for version support. French defense and security fleets prefer this model for budget predictability across multi-year procurement cycles.
- Freemium:Basic functionality at no cost with tiered unlocks for advanced analytics. Small Dutch owner-operator fleets trial compliance modules before scaling to paid diagnostics tiers.
- Pay-Per-Use:Variable billing tied to actual diagnostic queries or report generations. Indian seasonal agricultural logistics operators deploy this model for harvest-period fleet surges.
- Enterprise:Custom-negotiated agreements with dedicated support and API access for ERP integration. German automotive manufacturers extending software to dealer network maintenance operations require this licensing tier.
Subscription holds the dominant position; enterprise licensing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal emissions reporting mandates are accelerating software procurement across Germany, France, and the Netherlands. KBA inspection protocols in Germany and France's national transport regulator pre-deployment validation rules are forcing digitization of maintenance logs. Logistics clusters in the Rhine-Ruhr region, Paris Basin, and Randstad are consolidating fragmented systems into unified SaaS platforms.
Germany
Commercial vehicle telematics integration runs deepest here, with freight operators deploying predictive maintenance to extend powertrain lifecycles. KBA mandates auditable documentation for all commercial fleets under federal motor vehicle inspection protocols. The Rhine-Ruhr logistics corridor concentrates procurement among third-party logistics providers replacing paper-based service records.
United States
FAA airworthiness directives and EPA emissions standards mandate structured maintenance documentation for aviation and heavy-duty trucking fleets. NHTSA cybersecurity frameworks for connected vehicles are emerging as procurement prerequisites for federal contractors. Dallas-Fort Worth and Chicago freight hubs drive adoption among long-haul operators seeking condition-based servicing.
France
Municipal bus networks face the steepest EU AI Act compliance burden, with France's national transport regulator requiring pre-deployment algorithm validation. Verkehrsverbünde-style regional coordination across multi-operator networks demands standardized maintenance platforms. The Paris Basin concentrates demand among public transport operators pursuing ISO 55000 asset management certification.
India
Large freight carriers are centralizing maintenance operations across dispersed vehicle pools, requiring unified SaaS platforms to replace fragmented regional systems. The country's central transport authority is digitizing commercial vehicle fitness certification processes. The Mumbai-Delhi freight corridor drives edge computing deployments where cellular dead zones interrupt cloud connectivity.
United Kingdom
Equipment leasing companies are bundling software access into monthly per-vehicle rates, shifting procurement toward subscription models. The Driver and Vehicle Standards Agency is tightening audit requirements for commercial fleet maintenance records. Refrigerated transport operators in the Midlands seek continuous monitoring uptime guarantees tied to temperature-sensitive cargo.
Global Fleet Maintenance Software Market Competitive Landscape
Player mix skews toward telematics-native platforms and cloud-first SaaS specialists, with incumbent automotive hardware vendors occupying a secondary tier. The structure concentrates around three archetypes: integrated telematics providers leveraging native vehicle data streams, pure-play software vendors competing on deployment flexibility, and ERP-anchored suites targeting enterprise procurement cycles. Dominant competitive moves include channel control across dealer networks and edge-to-cloud architecture convergence for latency-sensitive diagnostics.
Among telematics-native platforms, Geotab anchors the real-time diagnostics tier, while Samsara occupies a position within edge-computing architectures. Verizon Connect exemplifies channel-control strategies across North American distribution networks. These three represent divergent bets on where diagnostic intelligence should reside—vehicle-mounted, cloud-centralized, or hybrid.
| Leading Market Players |
|---|
| Verizon Connect |
| OxMaint |
| RTA Fleet360 |
| Lytx |
| Motive |
| Fleetio |
| Geotab |
| Teletrac Navman |
| Samsara |
| Others |
Supply & Pricing Matrix
Edge computing hardware substitution for cloud-dependent telematics modules is redrawing procurement geography from centralized data centers toward Taiwanese semiconductor foundries and German automotive electronics suppliers, simultaneously inflating upfront hardware costs while compressing recurring SaaS margins.
Pricing Analysis
Certification level creates the primary spread between compliance-tracking premiums and basic scheduling tiers. Three-tier pricing structure across premium, standard, and economy levels aligns with ISO 55000 asset management validation, EU AI Act algorithmic transparency documentation, and raw telematics data feeds. Cost compression in mid-market cloud subscriptions intensifies because logistics providers consolidate vendor relationships across dispersed fleets. Small owner-operators exhibit acute price sensitivity, while German automotive manufacturers extending software to dealer networks tolerate premium enterprise licensing for API access and ERP integration.
Supply Chain Analysis
Port congestion along Asia-Europe container routes elevates inbound logistics costs for vehicle-mounted telematics hardware sourced from contract manufacturers in Taiwan, South Korea, and Vietnam. Semiconductor fabrication for automotive-grade microcontrollers draws from Taiwan-based foundries, German sensor specialists, and Japanese memory suppliers. Single-source vulnerability concentrates in Taiwan's 28nm automotive microcontroller capacity. Distribution runs through North American dealer networks controlled by incumbent telematics providers and direct SaaS sales to European logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in fleet maintenance software rests on EU Green Deal emissions reporting mandates forcing digitization among operators still reliant on paper-based service logs.
For Market Incumbents: Shield installed base relationships through channel control across dealer networks and preemptive ISO 55000 certification investment. Consolidate position by acquiring edge computing specialists before algorithm validation requirements harden under EU AI Act enforcement. Defensive moves must neutralize pure-play SaaS vendors competing on deployment flexibility. For New Entrants and Emerging Players: Differentiate on EU AI Act pre-compliance documentation and algorithmic audit trail capabilities. Target Indonesian archipelago logistics operators lacking maintenance infrastructure for maritime-dependent freight networks. Penetrate Indian long-haul corridors traversing cellular dead zones through vehicle-side inference architectures. Go-to-market leverage rests on pay-per-use pricing aligned with seasonal agricultural harvest surges. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed telematics platforms seeking exit liquidity before architecture convergence toward edge-to-cloud hybrid models. Five-to-ten year viability hinges on regulatory compliance moats deepening beyond commodity diagnostic features. Acquisition targets cluster among edge computing hardware-software integrators with validated automotive microcontroller supply relationships. Watch for NHTSA cybersecurity framework harmonization with UN ECE standards as procurement prerequisite inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Architecture Convergence | Pairs vehicle-side inference with centralized fleet analytics for latency-sensitive diagnostics across Indian and German corridors. |
| EU AI Act Pre-Compliance Investment | Creates algorithmic transparency documentation moat before France's national transport regulator mandates pre-deployment validation. |
| Dealer Network Channel Control | Secures captive distribution for maintenance software bundling with North American commercial vehicle sales. |
| ISO 55000 Certification Acceleration | Unlocks enterprise procurement cycles among German Verkehrsverbünde coordinating multi-operator regional networks. |
| Indonesian Maritime Logistics Platform Launch | Addresses whitespace in remote diagnostics for archipelago-dependent freight networks lacking maintenance infrastructure. |
Research Methodology
Desk research of regulatory filings from KBA, EPA, and France's national transport regulator preceded structured interviews with fleet operations directors, telematics platform engineers, automotive procurement leads, and ERP integration specialists. Secondary validation drew from EU Green Deal implementation guidance, FAA airworthiness directive documentation, SEC filings of listed logistics providers, and commercial vehicle registration databases. Bottom-up sizing of deployment models and application modules triangulated against top-down expenditure estimates from national transport authority digitization budgets.
Variance decomposition across deployment architecture, license type, and end-user industry segments shaped analytical framework construction over the projection horizon. Modeled dimensions spanned cloud versus edge computing uptake, subscription versus perpetual license mix, and logistics provider versus public transport operator penetration. CAGRs derived from segment-level adoption curves weighted by regulatory enforcement timelines and telematics hardware availability. Industry-specific inputs included EU AI Act risk-tier classification implementation pace and semiconductor foundry capacity allocation to automotive-grade microcontrollers.
Decision-makers should treat outputs as directional under assumptions of sustained EU emissions reporting enforcement and gradual NHTSA cybersecurity framework adoption; material deviation would warrant model refresh. Forecasts reflect documented base cases without contingency for Taiwan semiconductor supply disruption or abrupt algorithmic validation requirement acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market