
 Wind Shield Washer Market | 2026-2036
Wind Shield Washer Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Shield Washer Market Analytics
ISO 22241 AdBlue certification is bifurcating the supplier landscape for windshield washer systems, separating qualified tier-one suppliers from unvalidated competitors. Robert Bosch GmbH leverages its captive sensor-washer integration to dominate OEM contracts across European passenger vehicle programs. Continental AG anchors its position through backward integration into pump motor manufacturing, reducing supplier dependency for heated washer modules. HELLA GmbH & Co. KGaA differentiates via specialized nozzle design expertise that supports adaptive spray pattern technologies for advanced driver assistance systems.
Wind shield washer systems comprise fluid reservoirs, delivery pumps, spray nozzles, and wiper blade assemblies engineered to clear optical obstructions from vehicle windscreens; heated variants incorporate PTC heating elements rated for sub-zero activation thresholds to prevent fluid line freezing in arctic operating conditions. Conventional washers still occupy the largest volume share in aftermarket channels, though biodegradable washers are gaining fastest in regulatory-sensitive European markets where REACH compliance adds formulation cost. Heated washers concentrate margin pools at OEM level, where thermal management integration with battery electric vehicle architectures commands premium positioning.
The US EPA regulates volatile organic compound content in washer fluid formulations under Clean Air Act provisions, while the EU REACH framework restricts methanol concentrations and mandates biodegradability thresholds for consumer-facing products. Germany's KBA enforces type-approval standards that cascade into supplier qualification requirements across the European supply base. Stakeholders must monitor evolving chemical restriction schedules and thermal integration specifications as electrification reshapes vehicle front-end thermal management architectures.
Market Dynamics
Electric vehicle thermal management integration is compressing development cycles for heated washer systems, forcing suppliers to synchronize pump electronics with battery thermal loops rather than treating washers as standalone accessories.
Growth Catalysts
- EU F-Gas Regulation:Methane-based propellant bans are accelerating reformulation investments toward biodegradable surfactant bases that qualify for REACH-compliant supply chains.
- ADAS optical clarity mandates:Camera and lidar sensor housings now require precision spray patterning, expanding nozzle specification complexity for tier-one contracts.
- Germany's OEM supplier density:Stuttgart and Munich corridor concentration enables same-day prototype iteration cycles that compress qualification timelines for heated module suppliers.
Market Restraints
- Propylene glycol cost volatility:Feedstock price swings tied to petrochemical refining capacity constrain margin stability for fluid formulators serving aftermarket channels.
- PTC heater element supply concentration:Ceramic heating component fabrication clusters in East Asian foundries create single-source vulnerability for European heated washer module assemblers.
- Sub-zero activation threshold limitations:Current PTC technology cannot reliably activate below minus forty degrees Celsius without auxiliary battery drain penalties.
Strategic Opportunities
- Nordic aftermarket penetration:Norway and Finland vehicle fleets exhibit underpenetrated heated washer retrofit rates despite statutory winter equipment requirements.
- Sensor-washer convergence:Integration of spray nozzles with camera cleaning jets creates bundled specification opportunities for ADAS-equipped vehicle platforms.
- France ANSM biodegradability incentives:National eco-labeling schemes reward fluid formulators exceeding minimum OECD test thresholds, creating premium positioning for compliant suppliers.
Industry Challenges
- ISO 22241 certification timelines:AdBlue-adjacent fluid qualification protocols extend validation cycles by eight to fourteen months for new market entrants.
- Legacy reservoir tooling incompatibility:Existing injection molds for ICE-era fluid tanks require capital-intensive redesign to accommodate BEV thermal management routing.
- Cross-functional thermal engineering talent scarcity:Battery-electric vehicle programs demand washer specialists fluent in both fluid dynamics and high-voltage safety architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Shield Washer Market |
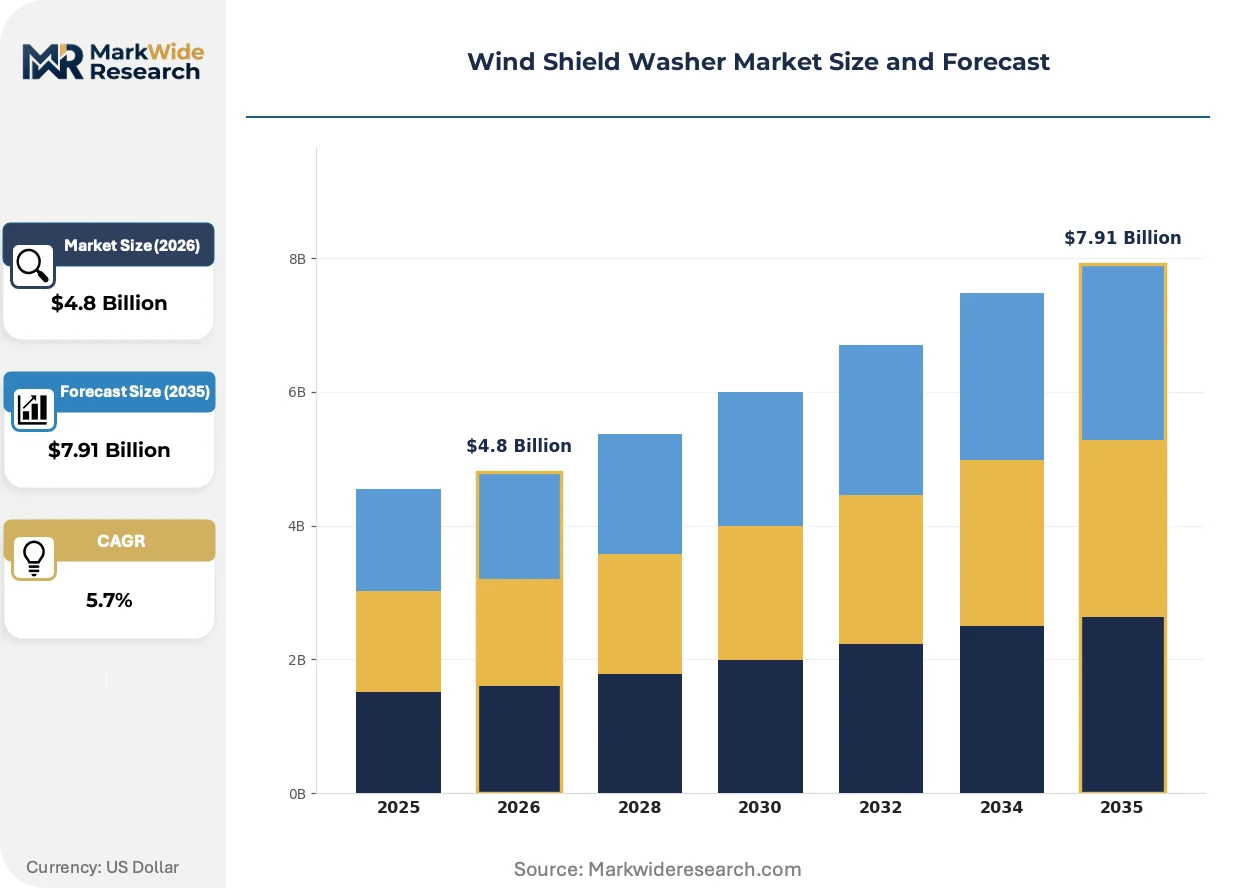
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Washers, Heated Washers, Concentrated Washers, Biodegradable Washers Distribution Channel: Online Retailers, Auto Parts Stores, Service Stations, Wholesale Distributors End User: Individual Consumers, Automotive Manufacturers, Fleet Operators, Repair Shops Packaging Type: Jerry Cans, Bottles, Tetra Packs, Pouches |
| Companies Covered | DENSO Corporation, Continental AG, HELLA GmbH & Co. KGaA, Robert Bosch GmbH, Mitsuba Corp., Valeo, Trico Products Corporation, 3M, ACDelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Shield Washer Market Evolving Landscape
Electrification is dissolving the boundary between windshield washing and vehicle thermal management, converting peripheral components into integrated subsystems governed by battery thermal logic rather than accessory switching.
Adaptive multi-jet nozzle arrays with piezoelectric actuation are supplanting fixed-spray mechanical nozzles in premium vehicle programs. OEM thermal management teams specify these units for electric platforms where precise fluid delivery minimizes waste and extends range. The technology is compressing supplier margins on conventional nozzle categories while opening specification slots for mechatronics-capable tier ones.
REACH Article 57 substance restriction schedules are forcing methanol concentration reductions in consumer-facing washer fluids across EU member states. Formulators are pivoting toward ethanol-isopropanol blends with enhanced surfactant packages to maintain freeze protection. Germany's KBA type-approval cascade transmits these requirements into supplier qualification protocols that now span thermal performance and chemical composition.
Fleet procurement departments are consolidating washer fluid sourcing through direct manufacturer contracts rather than distributor intermediaries. Large logistics operators with centralized maintenance depots negotiate bulk concentrate formulations that technicians dilute on-site. This pattern is most visible in German commercial vehicle segments where total cost of ownership reporting drives specification standardization across multi-brand fleets.
Wind Shield Washer Market Segmentation
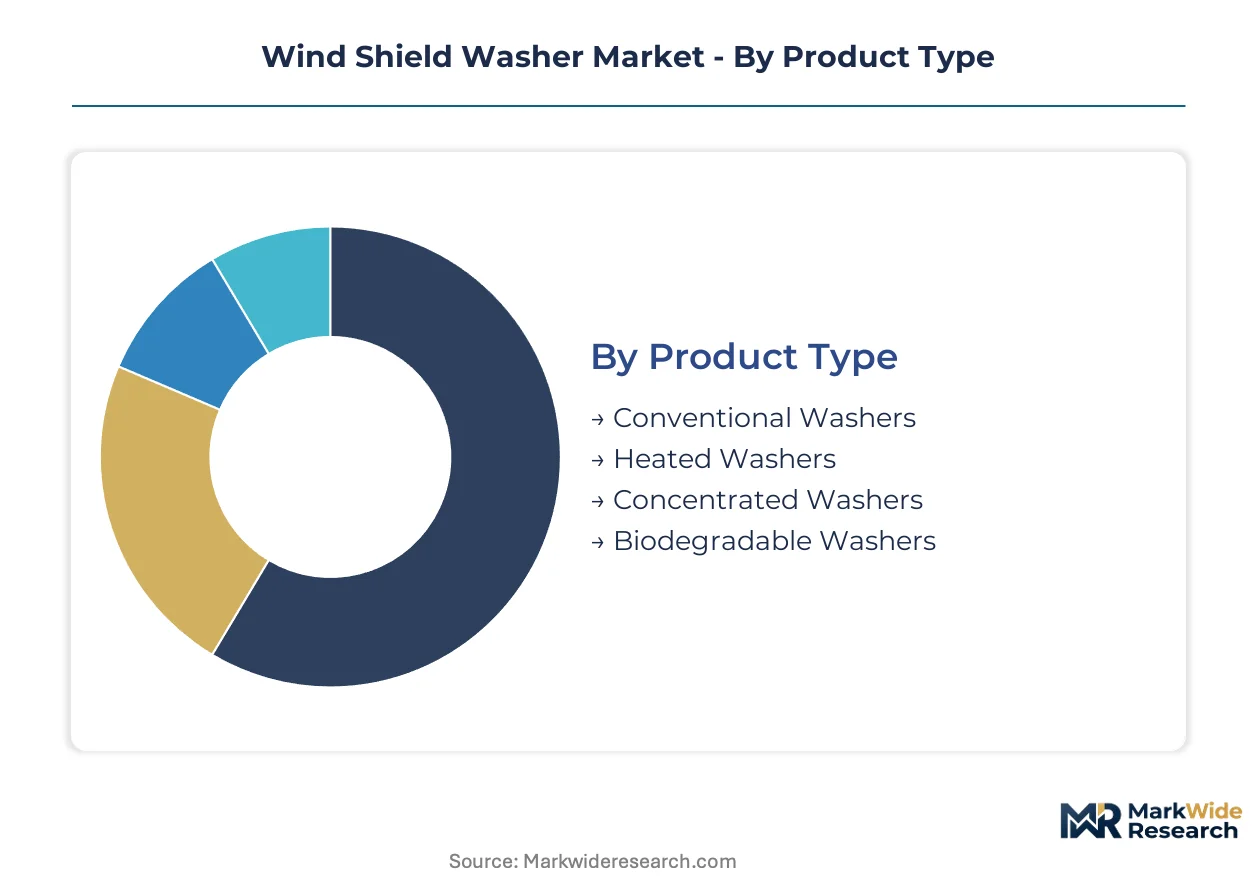
Segmentation in the wind shield washer market reveals how electrification and regulatory chemistry are splitting procurement patterns. OEM thermal integration requirements now diverge sharply from aftermarket price sensitivity, creating distinct specification lanes.
Product Type:
Substitution pressure from electrification and REACH compliance is fragmenting product categories fastest in this dimension, with legacy formulations facing regulatory displacement.
- Conventional Washers:Methanol-based formulations dominate aftermarket volume through established cold-weather performance. Fleet procurement in Germany continues specifying these for commercial vehicle pools despite gradual regulatory pressure.
- Heated Washers:PTC element integration with battery thermal loops defines this category. Stuttgart OEM programs specify these modules for electric platforms where sub-zero reliability cannot depend on fluid chemistry alone.
- Concentrated Washers:Bulk dilution protocols reduce transport costs for centralized maintenance depots. Logistics operators in France negotiate direct manufacturer contracts for concentrate supply.
- Biodegradable Washers:Ethanol-isopropanol blends with enhanced surfactants satisfy OECD biodegradability thresholds. ANSM eco-labeling in France rewards formulators exceeding minimum compliance.
Conventional washers retain volume leadership; biodegradable variants hold the steepest expansion curve.
Distribution Channel:
Channel structure reflects the split between emergency consumer purchase patterns and planned fleet procurement with consolidated specification authority.
- Online Retailers:Concentrate formulations and seasonal bulk purchases concentrate here. German consumers favor platform comparison for REACH-compliant fluid verification.
- Auto Parts Stores:Immediate-need replacement drives foot traffic for conventional washer fluids. Store networks in Nordic markets stock heated system components seasonally.
- Service Stations:Impulse purchase placement captures individual motorists. France's highway service network integrates biodegradability labeling into shelf positioning.
- Wholesale Distributors:Fleet and repair shop volume flows through this channel. German commercial vehicle segments leverage distributor consolidation for total cost of ownership standardization.
Wholesale distributors handle the largest transaction volumes; online retailers are expanding most quickly in concentrate categories.
End User:
User type determines whether procurement prioritizes thermal integration complexity or per-liter cost minimization.
- Individual Consumers:Price-sensitive purchase with seasonal concentration in cold-climate regions. French retail channels target this segment with ANSM-labeled premium biodegradables.
- Automotive Manufacturers:Heated washer module integration with ADAS sensor cleaning dominates OEM specifications. Munich and Stuttgart engineering teams synchronize pump electronics with battery thermal loops.
- Fleet Operators:Centralized maintenance depots enable bulk concentrate procurement with on-site dilution. German logistics operators standardize specifications across multi-brand commercial vehicle pools.
- Repair Shops:Aftermarket replacement demand with inventory breadth requirements. Nordic shops retrofit heated systems for statutory winter equipment compliance.
Automotive manufacturers command the highest specification complexity; fleet operators are consolidating procurement fastest through direct contracts.
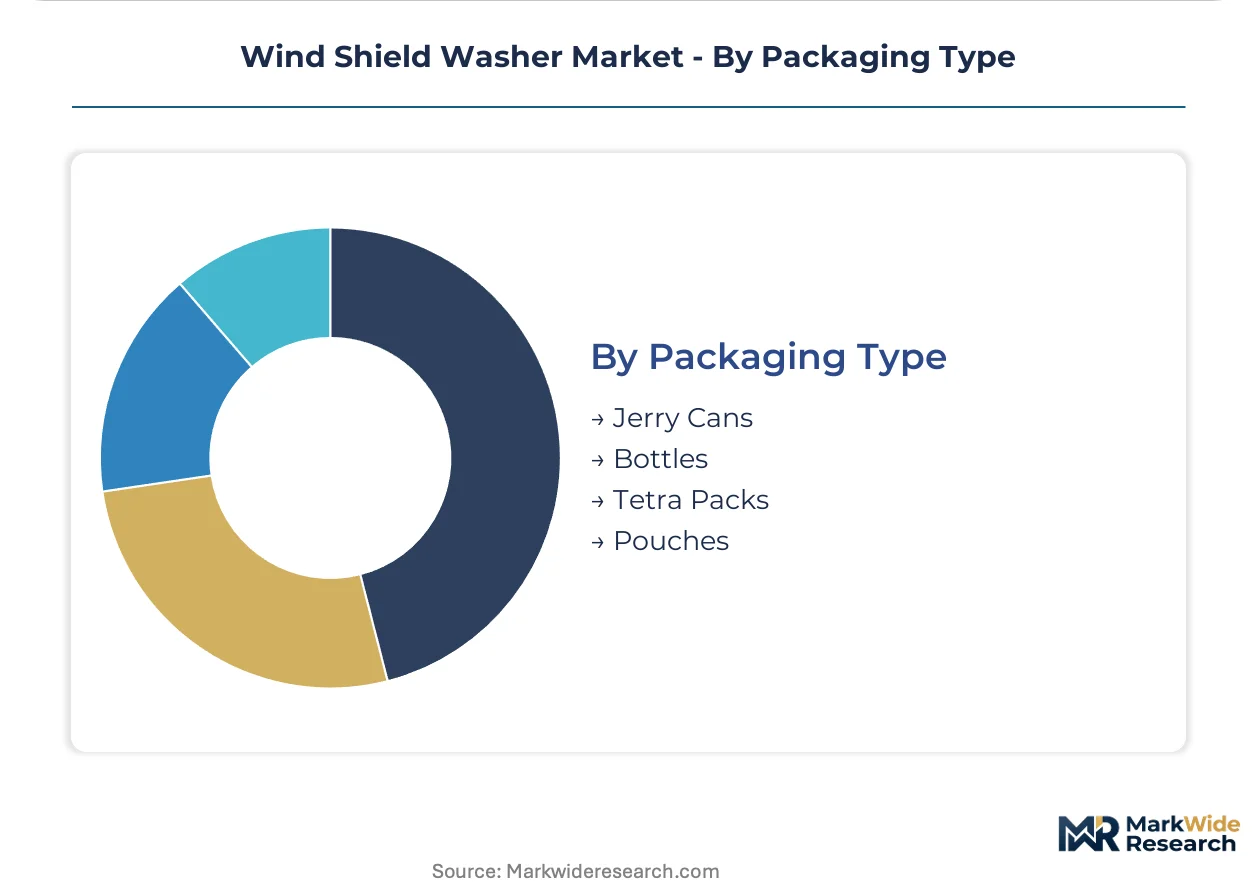
Packaging Type:
Packaging selection tracks the divergence between bulk fleet logistics and retail consumer convenience.
- Jerry Cans:Fleet and commercial workshop bulk storage with concentrate dilution protocols. German logistics depots specify UN-certified containers for transport compliance.
- Bottles:Standard retail format for individual consumer purchase. French supermarkets integrate biodegradability certification into shelf-facing decisions.
- Tetra Packs:Lightweight alternative reducing transport emissions for concentrate formulations. Environmental positioning targets regulatory-sensitive Nordic markets.
- Pouches:Single-use emergency formats for glovebox storage. Service station impulse placement in Germany captures motorist convenience demand.
Jerry cans retain fleet dominance; tetra packs are gaining share fastest in carbon-conscious supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Basel Rhine corridor moves concentrated washer fluid formulations from Dutch chemical ports to Stuttgart and Munich assembly plants, underwriting Europe's densest automotive supplier network.
Germany
Stuttgart and Munich OEM engineering teams specify heated washer modules for electric platforms requiring battery thermal loop synchronization. KBA type-approval standards cascade into supplier qualification protocols that now span chemical composition and thermal performance. Baden-Württemberg's supplier cluster enables same-day prototype iteration cycles for heated system validation.
France
ANSM eco-labeling rewards fluid formulators exceeding OECD biodegradability thresholds, creating premium positioning for compliant suppliers. REACH Article 57 substance restrictions force methanol concentration reductions in consumer-facing formulations. Île-de-France logistics operators negotiate direct manufacturer contracts for bulk concentrate supply to centralized maintenance depots.
United States
EPA Clean Air Act provisions regulate volatile organic compound content in washer fluid formulations across aftermarket channels. California's Air Resources Board imposes additional state-level formulation constraints that exceed federal baselines. Detroit Three thermal engineering teams integrate heated washer electronics with battery management systems for electric truck platforms.
China
MIIT new energy vehicle mandates accelerate heated washer module adoption as domestic OEMs expand electric platform output. GB standards for automotive fluids incorporate biodegradability testing protocols aligned with OECD methodologies. Yangtze River Delta chemical processors supply surfactant bases to both domestic formulators and European exporters.
Japan
METI carbon neutrality roadmaps pressure fluid formulators toward bio-based surfactant packages with reduced petrochemical dependency. JIS standards for automotive washer systems specify precision spray pattern tolerances that support ADAS optical clarity requirements. Kanto region suppliers concentrate nozzle manufacturing for premium vehicle programs across Asia-Pacific.
Wind Shield Washer Market Competitive Landscape
Listed leaders compete with private specialists across thermal integration capability, with publicly traded tier-one suppliers commanding OEM contracts while family-owned component houses dominate aftermarket channels. The supplier base concentrates around three strategic archetypes: integrated thermal system houses, specialized nozzle designers, and fluid formulators with chemical backward integration. Capacity expansion and strategic partnerships represent the dominant competitive moves, as heated module suppliers align with battery thermal management specialists.
Within the integrated thermal system tier, Robert Bosch GmbH and Continental AG exemplify archetypes combining pump electronics with vehicle thermal loop expertise, while HELLA GmbH & Co. KGaA occupies a position among specialized component designers. These German entities anchor European supply relationships through proximity to Stuttgart and Munich engineering centers.
| Leading Market Players |
|---|
| DENSO Corporation |
| Continental AG |
| HELLA GmbH & Co. KGaA |
| Robert Bosch GmbH |
| Mitsuba Corp. |
| Valeo |
| Trico Products Corporation |
| 3M |
| ACDelco |
| Others |
Value Network & Pricing Analysis
Forty-five-day inventory cycles for PTC heater elements expose European module assemblers to East Asian foundry pricing power, compressing margins when ceramic substrate costs spike. This lead-time vulnerability concentrates procurement leverage among suppliers with captive heating element production or long-term offtake agreements with Yangtze River Delta fabricators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs heated washer module procurement, with ADAS-integrated sensor-washer bundles commanding certification premiums against commodity reservoir-pump assemblies. Price differentiation centers on ISO 22241 qualification status and thermal integration complexity, with OEM direct contracts showing lowest sensitivity while aftermarket distributors face intense cost compression from propylene glycol feedstock volatility. Pricing pressure stems from REACH compliance investments in biodegradable surfactant reformulation, forcing margin trade-offs between regulatory adherence and volume retention.
Supply Chain Analysis
Strait of Malacca transit routes underpin surfactant base logistics from Yangtze River Delta chemical processors to European formulators, creating chokepoint exposure for just-in-time fluid production. Supply concentrates in China for ceramic heating components, Germany for precision nozzle machining, and the Netherlands for Rotterdam-port chemical blending operations. Raw material dependencies span propylene glycol from petrochemical refineries, ethanol-isopropanol blends from biofuel processors, and PTC ceramics from specialized foundries. Single-source vulnerability in East Asian heating element fabrication threatens module assembly continuity. Distribution runs through wholesale distributors for fleet volume, with direct manufacturer contracts gaining share among logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform proliferation positions heated washer systems at early-cycle expansion, with battery thermal loop integration mandates driving specification upgrades across Stuttgart and Munich engineering centers.
For Market Incumbents: Shield OEM relationships by accelerating backward integration into pump motor manufacturing and securing multi-year PTC element offtake agreements with Yangtze River Delta suppliers. Invest in ISO 22241 certification maintenance to defend against unvalidated competitors exploiting shortened qualification timelines. Priority levers include sensor-washer convergence R&D and Baden-Württemberg prototype iteration capacity expansion.
For New Entrants and Emerging Players: Lead with biodegradable formulation specialization targeting France ANSM eco-labeling incentives and Nordic aftermarket retrofit gaps in Norway and Finland. White-space targets concentrate in fleet concentrate supply contracts and ADAS-adjacent precision nozzle segments underserved by integrated thermal houses. Go-to-market angle emphasizes REACH-compliant chemistry credentials against methanol-based incumbents facing regulatory displacement.
For Investors and Strategic Acquirers: Long-term, this sits as a thermal integration consolidation play because electrification dissolves standalone accessory boundaries and rewards subsystem convergence capability. Acquisition target archetype: mechatronics-capable nozzle designers with ADAS spray patterning expertise and existing OEM qualification relationships. Signal to watch is battery-electric vehicle thermal management team staffing ratios at Stuttgart and Munich engineering centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Motor Manufacturing | Continental AG's captive motor production reduces supplier dependency for heated washer module assembly. |
| ISO 22241 Certification Investment | AdBlue-adjacent qualification separates tier-one suppliers from unvalidated competitors in OEM procurement. |
| Sensor-Washer Convergence Development | Integration of spray nozzles with camera cleaning jets captures ADAS-equipped platform specifications. |
| Biodegradable Formulation Pivot | Ethanol-isopropanol blends with enhanced surfactants satisfy France ANSM eco-labeling thresholds. |
| East Asian PTC Element Offtake Agreement | Long-term ceramic heating component contracts mitigate single-source vulnerability for European assemblers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, vehicle production databases, and regulatory filing repositories including ECHA REACH registrations and KBA type-approval records. Primary interviews engaged OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, fluid formulator R&D directors, and fleet maintenance managers across Germany, France, and the United States. Bottom-up volume estimates from component shipment analysis triangulate against top-down market sizing from automotive production forecasts and content-per-vehicle assumptions.
Segmentation dimensions modeled span product type, distribution channel, end user category, and packaging format, with additional granularity on thermal integration tier and biodegradability certification status. Value projections across the analysis window apply CAGRs derived from historical price trajectory analysis and forward-looking OEM specification roadmaps. Industry-specific inputs include battery-electric vehicle thermal management architecture evolution and REACH Article 57 substance restriction implementation schedules.
Forecasts assume regulatory continuity in EU F-Gas Regulation, REACH compliance timelines, and EPA Clean Air Act enforcement; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Fluid Couplings Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Clutch Pedal Kit Market
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Car Rack Market
Automotive Parts
Automotive Remanufactured Parts Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Indonesia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Asia Pacific Automotive Parts Die Casting Market
Automotive Parts
Global Automotive Dynamic Chassis Control System Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Closure Market