
 Automotive Engine Connecting Rods Market | 2026-2036
Automotive Engine Connecting Rods Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engine Connecting Rods Market Analysis
Mexico's automotive corridor is reconfiguring connecting rod supply chains as OEMs localize engine component sourcing. Mahle GmbH leverages its forged steel expertise to anchor European OEM programs with integrated piston-rod modules. JD Norman Industries sustains high-volume cast rod production across Midwestern US powertrain plants. Linamar Corporation competes through electromechanical rod assembly automation that reduces labor content per unit.
An automotive engine connecting rod is a rigid mechanical link that transmits reciprocating motion from the piston to the crankshaft, typically manufactured from microalloyed steel forgings or powder metal with hardness ratings exceeding 30 HRC to withstand cyclic tensile-compressive loads exceeding 50 MPa. Its primary function is converting linear piston force into rotational torque with minimal mass penalty to optimize engine balance and fuel efficiency. Forged rods dominate OEM volume for high-load diesel and turbocharged gasoline engines where fatigue resistance commands premium positioning, while cast rods retain cost-driven share in naturally aspirated commuter vehicle segments. Billet and titanium offerings occupy thin margin pools in motorsport and specialty aftermarket channels where unit economics tolerate material premiums.
EPA tailpipe rules and Euro 7 standards from the European Commission are forcing rod manufacturers to certify surface finish tolerances that reduce friction losses in downsized engines. China's MIIT fuel consumption mandates and India's BIS automotive steel standards create divergent compliance pathways across major supply corridors. Stakeholders must monitor how OEM electrification timelines redistribute capital between ICE rod capacity and hybrid-specific connecting rod architectures.
Market Dynamics
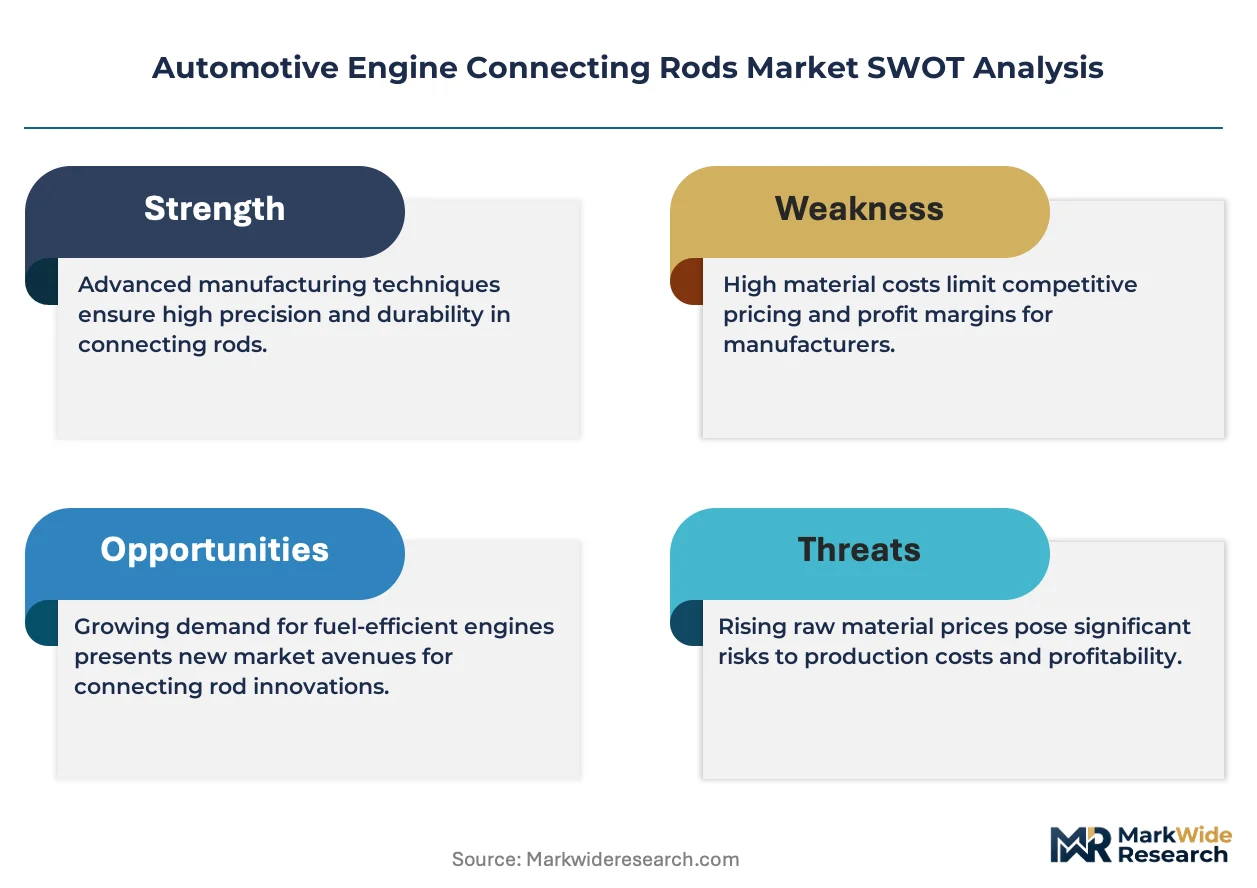
Connecting rod manufacturers face a structural squeeze between ICE downsizing mandates and hybrid powertrain diversification, forcing parallel investments in forged steel durability for turbocharged engines and powder-forged variants for range-extender architectures.
Growth Catalysts
- Euro 7 friction-loss mandates:EPA Tier 3 and European Commission tailpipe rules compel OEMs to specify surface-finish tolerances that reduce parasitic drag in downsized engines.
- China Yangtze River Delta cluster concentration:Engine foundries in this automotive corridor serve domestic EV-to-hybrid transitions, sustaining rod demand through powertrain architecture shifts.
- Powder-forged steel innovation:Near-net-shape forming from German and Japanese process licensors cuts machining waste while maintaining fatigue resistance above 50 MPa cyclic loads.
Market Restraints
- Scrap steel price volatility:Microalloyed steel billets constitute 60-70% of forged rod input costs, exposing margins to commodity swings.
- Single-source forging press concentration:Large-tonnage mechanical and hydraulic presses cluster in Germany, Japan, and select Chinese provinces, creating geographic supply risk.
- Titanium substitution ceiling:Motorsport and specialty aftermarket segments absorb limited titanium rod volume due to unit economics, capping premium material penetration.
Strategic Opportunities
- India BIS automotive steel compliance:Domestic certification requirements for high-strength steels create captive demand for localized forged rod capacity.
- Hybrid-specific rod architectures:Range-extender engines operate at fixed RPM setpoints, enabling optimized connecting rod designs with reduced mass tolerance bands.
- Integrated piston-rod modules:Powertrain assemblers seek pre-balanced rotating assemblies that compress final engine line labor content.
Industry Challenges
- Dual metallurgy workforce scarcity:Forging engineers skilled in both conventional steel and powder metal sintering command premium compensation in Midwestern US and European industrial zones.
- Euro 7 certification timeline compression:Surface finish and fatigue testing protocols require 18-24 month validation cycles that outpace model-year development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engine Connecting Rods Market |
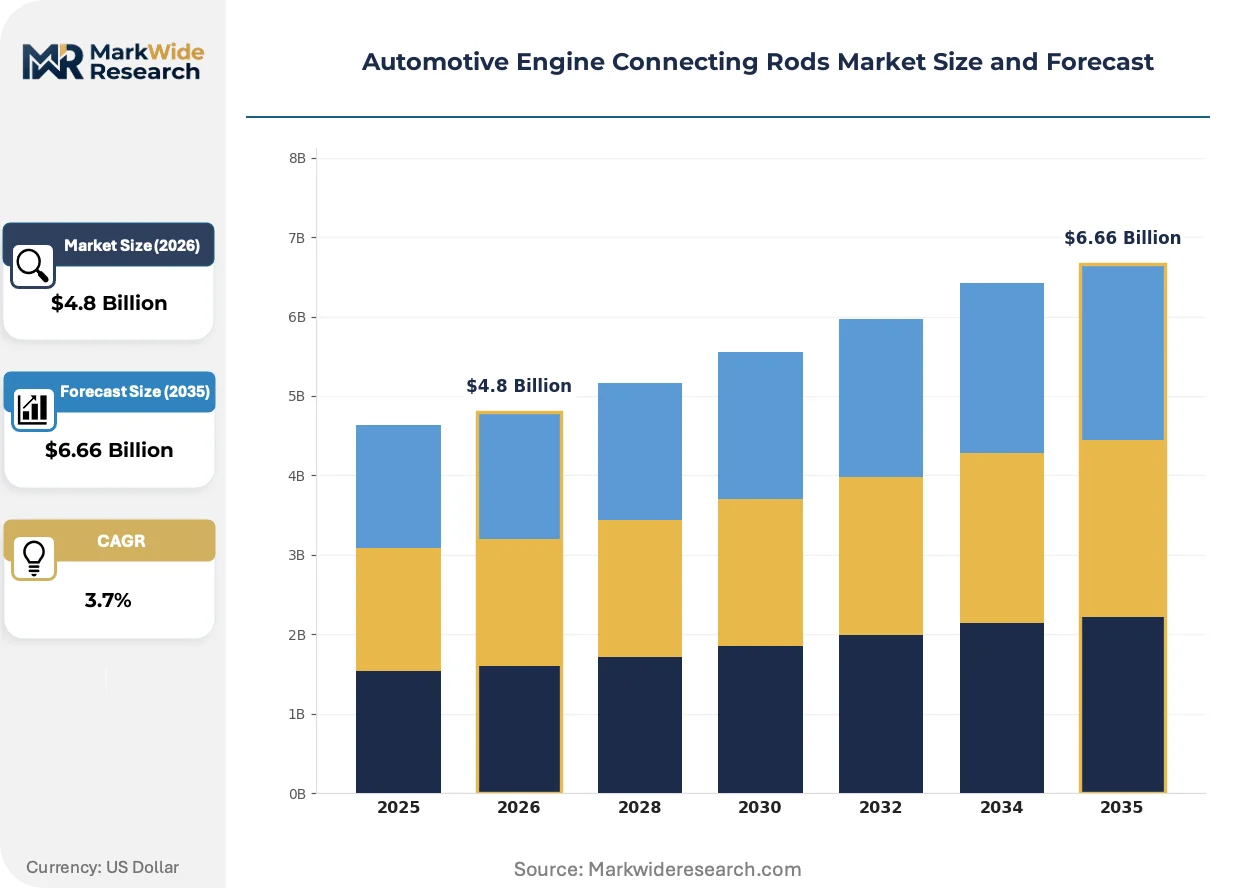
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forged, Cast, Billet, Riveted Material: Steel, Aluminum, Titanium, Composite End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Hydraulic, Mechanical, Electromechanical, Pneumatic |
| Companies Covered | Mahle GmbH, JD Norman Industries, Albon Engineering & Manufacturing Plc, Linamar Corporation, CP-Carrillo, Wiseco, Pauter Machine, Tianrun Crankshaft, MGP Connecting Rods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engine Connecting Rods Market Emerging Trajectories
Powder metallurgy advances and regulatory friction-reduction mandates are compressing traditional manufacturing paradigms while hybrid powertrain diversification creates parallel specification tracks for connecting rod suppliers.
Continuous-sinter powder-forged steel rods achieve 95% theoretical density through controlled atmosphere sintering followed by closed-die forging, delivering fatigue strength parity with conventional forgings at 15-20% lower finished mass. Light commercial vehicle OEMs in Germany and Japan have adopted these rods for turbocharged gasoline engines since 2022. The technology is rendering obsolete single-piece machined billets in mid-displacement passenger car applications where weight reduction commands procurement priority.
EPA Tier 3 evaporative emissions standards and Euro 7 particulate limits force rod manufacturers to certify surface roughness below 0.4 micrometers Ra on crankshaft and piston pin bores, specifications previously reserved for racing components. This industrial consequence extends finishing cycle times and capital equipment requirements. High-volume passenger car programs in the US and EU face the steepest compliance cost absorption, with some OEMs shifting specification authority to Tier-1 forging houses.
Fleet operators and powertrain assemblers increasingly specify outcome-based supplier contracts tied to warranty claim rates rather than unit price, compressing traditional spot-market purchasing. Tier-1 forging houses in China's Jiangsu province and Mexico's Bajío corridor now carry inventory risk for OEM just-in-sequence assembly lines. This procurement model change is most visible in North American light truck programs where vertical integration into captive forging capacity has accelerated since 2020.
Automotive Engine Connecting Rods Market Segmentation
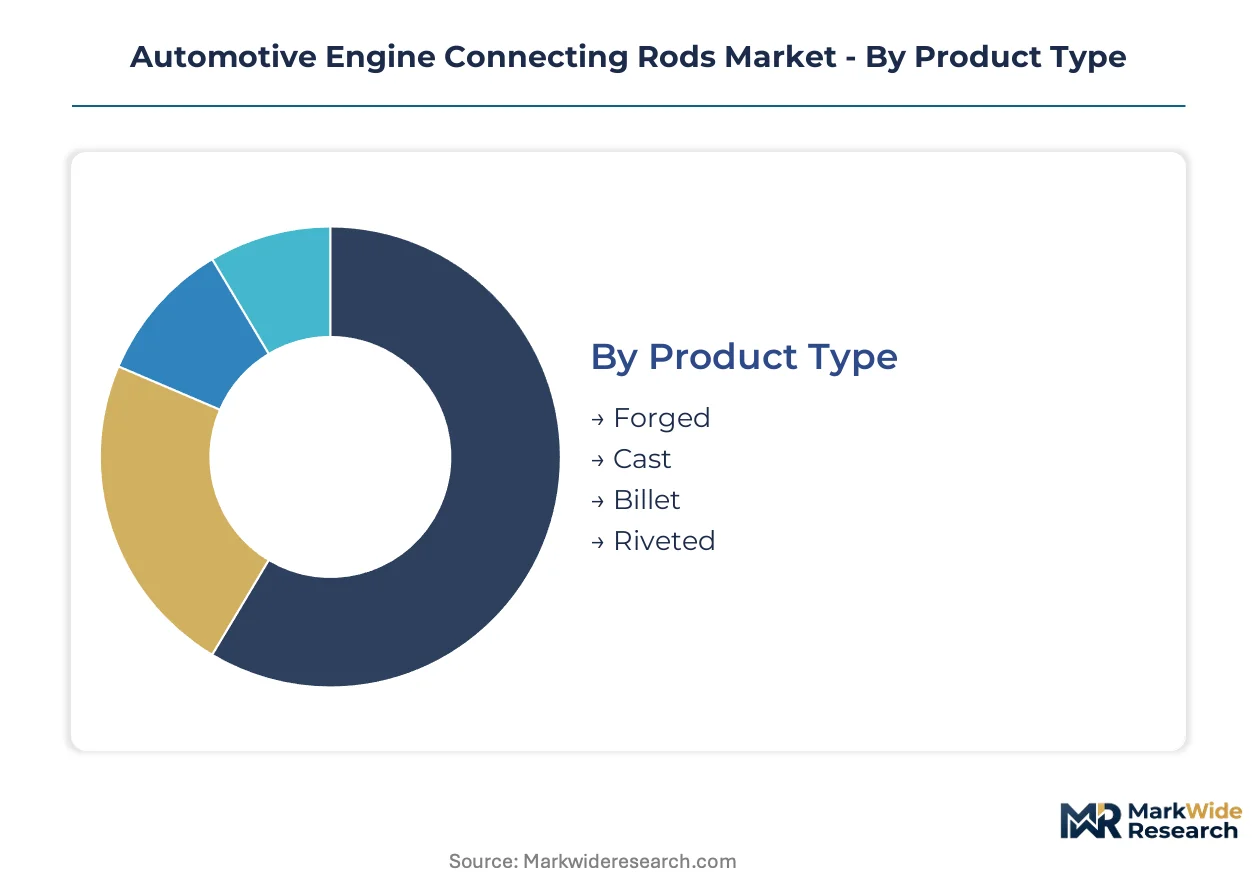
Connecting rod procurement patterns diverge sharply across powertrain architectures and supply chain tiers, with OEM specifications for hybrid durability clashing against aftermarket cost sensitivity. Segment boundaries are blurring as powder-forged steel bridges forged and cast economics.
Product Type:
Forged and cast rods anchor opposite ends of the load spectrum, with billet and riveted variants serving narrow performance niches where standardization fails.
- Forged:Microalloyed steel forgings exceed 30 HRC hardness ratings to withstand cyclic tensile-compressive loads above 50 MPa in turbocharged gasoline and diesel engines. German and Japanese OEM programs specify these rods for Euro 7 compliance, where fatigue resistance commands procurement priority over unit cost.
- Cast:Gray iron and ductile iron castings retain cost-driven share in naturally aspirated commuter vehicles where production scale outweighs performance margins. China's Yangtze River Delta engine foundries sustain cast rod volume through domestic hybrid transitions that preserve naturally aspirated range-extender architectures.
- Billet:CNC-machined from solid steel stock for motorsport and specialty builds where batch sizes preclude forging die investment.
- Riveted:Two-piece assemblies with separate cap and rod body joined by high-strength fasteners, specified for select heavy-duty diesel rebuild markets.
Established volume favors forged rods in OEM turbocharged programs; emerging adoption favors cast derivatives in cost-optimized hybrid range-extenders.
Material:
Steel dominates mass production while aluminum and titanium occupy weight-critical niches constrained by fatigue limits and unit economics.
- Steel:Microalloyed grades with vanadium and niobium additions constitute 60-70% of forged rod input costs, with powder-forged variants achieving 95% theoretical density through controlled atmosphere sintering. EPA Tier 3 and Euro 7 surface finish mandates below 0.4 micrometers Ra extend finishing cycle times for steel rod crankshaft bores.
- Aluminum:Hypereutectic alloys reduce reciprocating mass in high-RPM gasoline engines where piston acceleration limits dominate durability concerns. Japanese OEMs specify aluminum rods for fixed-RPM range-extender setpoints where reduced mass tolerance bands optimize engine balance.
- Titanium:Ti-6Al-4V alloys serve motorsport and specialty aftermarket channels where unit economics tolerate material premiums for 40% mass reduction versus steel.
- Composite:Carbon fiber-reinforced polymer experimental rods remain pre-commercial for production powertrains, limited by thermal expansion mismatch with steel crankshafts.
Steel maintains procurement dominance across displacement categories; aluminum is climbing the fastest in hybrid-specific fixed-RPM architectures.
End User:
Outcome-based contracting is compressing traditional spot-market purchasing across assembler and supplier tiers.
- OEMs:Light commercial vehicle manufacturers in Germany and Japan specify integrated piston-rod modules that compress final engine line labor content. Warranty claim rate clauses now override unit price in supplier contract structures.
- Aftermarket Providers:Independent distributors serve rebuild markets with reverse-engineered specifications, absorbing inventory risk for aging naturally aspirated commuter vehicle fleets.
- Tier-1 Suppliers:Forging houses in China's Jiangsu province and Mexico's Bajío corridor carry just-in-sequence inventory risk for North American light truck programs.
- Vehicle Assemblers:Powertrain integration specialists seek pre-balanced rotating assemblies from captive forging capacity accelerated since 2020.
OEM direct procurement favors forged rod durability guarantees; Tier-1 intermediaries are gaining share fastest in localized supply corridor configurations.
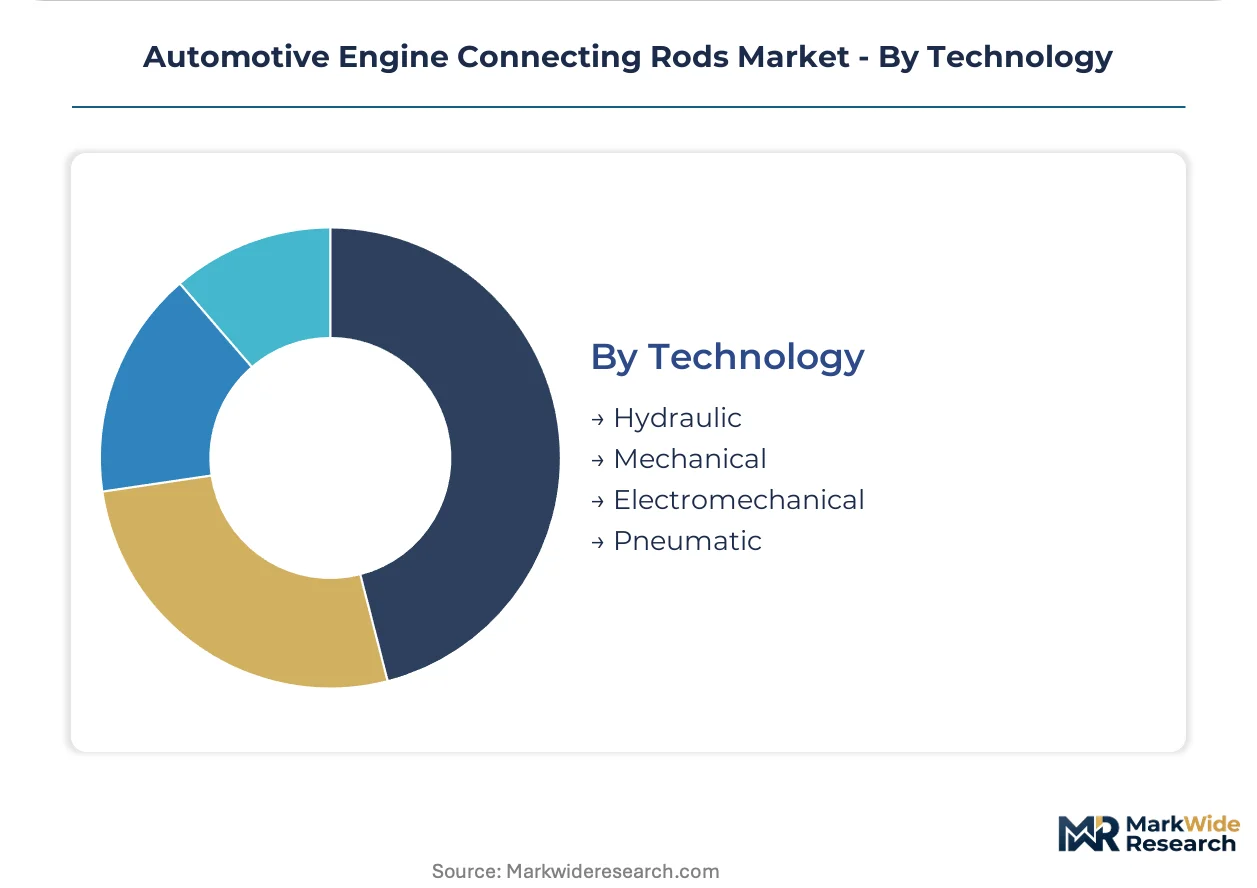
Technology:
Rod manufacturing equipment selection tracks forging complexity, surface finish mandates, and automation labor substitution.
- Hydraulic:Large-tonnage presses enable closed-die forging of powder-forged steel rods with near-net-shape forming that cuts machining waste. Geographic concentration in Germany, Japan, and select Chinese provinces creates supply risk.
- Mechanical:High-speed crank presses dominate high-volume forged rod production for mid-displacement passenger car programs where cycle time economics prevail.
- Electromechanical:Servo-driven press controls enable precise stroke profiling for complex I-beam sections, with Linamar Corporation competing through assembly automation that reduces labor content per unit.
- Pneumatic:Limited to secondary operations and fixture clamping in rod finishing lines, not primary forming.
Hydraulic systems retain dominance in powder-forged steel adoption; electromechanical controls are expanding most quickly in precision surface finish compliance for Euro 7 certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys connecting rods predominantly in hybrid range-extender architectures, while Germany and Japan concentrate procurement on high-load turbocharged gasoline and diesel engines. The United States splits demand between light commercial vehicle durability specifications and cost-optimized cast rod segments for commuter fleets.
China
Engine foundries in the Yangtze River Delta automotive cluster serve domestic EV-to-hybrid transitions, sustaining rod demand through powertrain architecture shifts. MIIT fuel consumption mandates force OEMs to optimize reciprocating mass in downsized engines. Jiangsu province forging houses carry just-in-sequence inventory risk for localized assembly operations.
Germany
Light commercial vehicle OEMs specify integrated piston-rod modules that compress final engine line labor content. Euro 7 standards from the European Commission compel surface-finish tolerances below 0.4 micrometers Ra on crankshaft bores. Powder-forged steel innovations from German process licensors achieve 95% theoretical density through controlled atmosphere sintering.
United States
Midwestern powertrain plants sustain high-volume cast rod production for naturally aspirated commuter vehicle segments. EPA Tier 3 tailpipe rules mandate friction-loss reductions that extend finishing cycle times and capital equipment requirements. Mexico's Bajío corridor reconfigures supply chains as OEMs localize engine component sourcing for North American light truck programs.
Japan
Japanese OEMs specify aluminum rods for fixed-RPM range-extender setpoints where reduced mass tolerance bands optimize engine balance. METI industrial policy supports powder metallurgy advances in automotive steel applications. Closed-die forging expertise clusters around Nagoya and Osaka industrial zones serving turbocharged gasoline engine programs.
India
Domestic certification requirements under BIS automotive steel standards create captive demand for localized forged rod capacity. Engine manufacturers serving the commuter vehicle segment prioritize cost-optimized cast rod architectures. Tamil Nadu and Maharashtra automotive corridors attract Tier-1 forging investments to serve hybrid powertrain diversification.
Automotive Engine Connecting Rods Market Vendor Landscape
Capability concentration sits with European and Japanese forging specialists; scale advantage sits with North American and Chinese volume producers. The vendor base separates into three strategic archetypes: integrated powertrain module suppliers, high-volume forged rod specialists, and precision electromechanical automation providers. Dominant competitive moves include backward integration into captive steel billet supply and technology licensing agreements for powder-forged steel processes.
Within the integrated module tier, Mahle GmbH and Linamar Corporation occupy positions defined by electromechanical assembly automation and pre-balanced rotating assembly expertise. JD Norman Industries exemplifies the high-volume forged rod specialist archetype sustaining production across Midwestern US powertrain plants. These three companies represent distinct competitive vectors: European forging heritage, North American scale economics, and precision manufacturing automation respectively.
| Leading Market Players |
|---|
| Mahle GmbH |
| JD Norman Industries |
| Albon Engineering & Manufacturing Plc |
| Linamar Corporation |
| CP-Carrillo |
| Wiseco |
| Pauter Machine |
| Tianrun Crankshaft |
| MGP Connecting Rods |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Germany's large-tonnage forging press fleet constrains powder-forged steel rod availability, compressing supplier pricing power while forcing OEMs into multi-year offtake commitments to secure capacity slots. This utilization squeeze propagates through the value chain as Tier-1 houses in China's Jiangsu province and Mexico's Bajío corridor absorb inventory risk to maintain just-in-sequence delivery guarantees.
Pricing Analysis
Long-term offtake contracts dominate procurement for high-load forged rods, with OEMs locking capacity three to five years ahead to hedge against press scarcity. Price differentiation hinges on fatigue certification grade and surface finish tolerance compliance below 0.4 micrometers Ra for Euro 7 engines. Cost compression in cast rod segments intensifies as China's Yangtze River Delta foundries compete on scale for hybrid range-extender programs. Aftermarket rebuild providers exhibit highest price sensitivity, while German light commercial vehicle OEMs prioritize warranty-backed performance guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts microalloyed steel billet flows that feed Midwestern powertrain plants. Supply concentrates in Germany, Japan, and select Chinese provinces for large-tonnage hydraulic and mechanical forging presses. Raw material dependencies center on vanadium-niobium microalloyed grades, scrap steel pricing, and powder metal sintering feedstocks. Single-source vulnerability persists for 10,000-ton-plus closed-die forging capacity. Distribution runs through Tier-1 forging houses carrying just-in-sequence inventory for OEM assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized forging engineering talent capable of spanning conventional steel and powder metal sintering disciplines has become the constraining asset, with Midwestern US and European industrial zones commanding premium compensation for dual-metallurgy expertise.
For Market Incumbents: Pre-empt powder-forged steel capacity constraints by securing exclusive licensing agreements with German and Japanese process licensors before competitors lock up technology access. Anchor European OEM programs with integrated piston-rod modules that compress final engine line labor content, raising switching costs. Defend against emerging electromechanical automation specialists by accelerating in-house production of pre-balanced rotating assemblies. For New Entrants and Emerging Players: India's Tamil Nadu and Maharashtra automotive corridors present underpenetrated white-space for localized forged rod capacity serving BIS automotive steel compliance mandates. Target hybrid-specific rod architectures with reduced mass tolerance bands optimized for fixed-RPM range-extender setpoints. Enter through outcome-based supplier contracts tied to warranty claim rates rather than competing on spot-market unit pricing. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap forging specialists with captive powder metallurgy expertise and established OEM qualification pathways. Long-term viability across the analysis window hinges on positioning for hybrid powertrain diversification rather than pure ICE volume exposure. Monitor EPA Tier 3 and Euro 7 certification timeline compression as the inflection signal for supplier consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Powder-Metallurgy Licensing Agreement | Secures near-net-shape forming technology from German and Japanese process licensors to cut machining waste. |
| Integrated Piston-Rod Module Development | Compresses final engine line labor content for Mahle GmbH and Linamar Corporation OEM programs. |
| Electromechanical Assembly Automation | Reduces labor content per unit through servo-driven press controls and precision stroke profiling. |
| Regional Forging Capacity Expansion | Addresses undercapacity in large-tonnage press fleets serving Euro 7 and EPA Tier 3 certification demands. |
| Outcome-Based Supplier Contracting | Shifts procurement from spot-market pricing to warranty claim rate guarantees with Tier-1 forging houses. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and powertrain integration specialists; and secondary validation through vehicle production databases, IHS Markit registration data, SEC filings from publicly traded forging houses, and customs records for microalloyed steel billet trade flows. Bottom-up triangulation across regional production clusters and top-down reconciliation against powertrain architecture forecasts anchored volume estimates.
Forecast inputs considered propulsion architecture splits, content per vehicle variations between turbocharged and naturally aspirated engines, and regional regulatory compliance timelines across the projection horizon. Segmentation dimensions modeled include product type, material grade, end-user tier, and technology platform. CAGRs were derived from regression analysis of historical capacity utilization, OEM procurement patterns, and powertrain mix projections. Industry-specific inputs incorporated Euro 7 surface finish mandate adoption curves and MIIT fuel consumption mandate enforcement intensity.
Practitioners should monitor scrap steel price volatility, single-source forging press concentration risk, and OEM electrification timeline acceleration for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Automotive Buffers Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
Automotive Braking Component Market
Automotive Components
Argentina Automotive Electric Actuators Market
Automotive Components
Automotive Resonator Market
Automotive Components
Automotive Backing Plate Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Japan Automotive Sunroof Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Iran Automotive Lubricants Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Automotive Pedals Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
Automotive Rear End Module Market