
 Automotive Weigh in Motion Market | 2026-2036
Automotive Weigh in Motion Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Weigh in Motion Market Analysis
The gap between precision piezoelectric installations and basic load-cell deployments is repositioning how transport authorities allocate capital across enforcement networks. Kistler Group leverages its quartz sensor heritage to dominate high-speed weighing corridors in Europe. TE Connectivity sustains manufacturing scale across North American tolling infrastructure. International Road Dynamics anchors provincial highway contracts in Canada through integrated data platforms.
Automotive weigh-in-motion systems measure axle loads and gross vehicle weights at highway speeds using embedded road sensors, quartz piezoelectric strips, or bending-plate load cells with accuracy thresholds typically within five to ten percent of static scale readings. These systems enable real-time weight enforcement without interrupting traffic flow. Piezoelectric technology leads permanent installations due to durability under heavy freight volumes, while load-cell configurations retain share in lower-speed checkpoint applications. The logistics end-user segment shows the fastest procurement expansion as private fleet operators adopt onboard integration for route compliance.
The U.S. Federal Highway Administration coordinates with state DOTs to mandate Commercial Vehicle Information Systems and Networks compliance, while the EU Weigh-in-Motion Directive sets enforcement accuracy thresholds that filter non-compliant vendors from public tenders. Germany's KBA enforces type-approval standards that shape sensor calibration protocols across member states. Stakeholders must monitor how pending U.S. infrastructure appropriations and EU Green Deal freight efficiency targets recalibrate enforcement technology specifications before next procurement cycles.
Market Dynamics
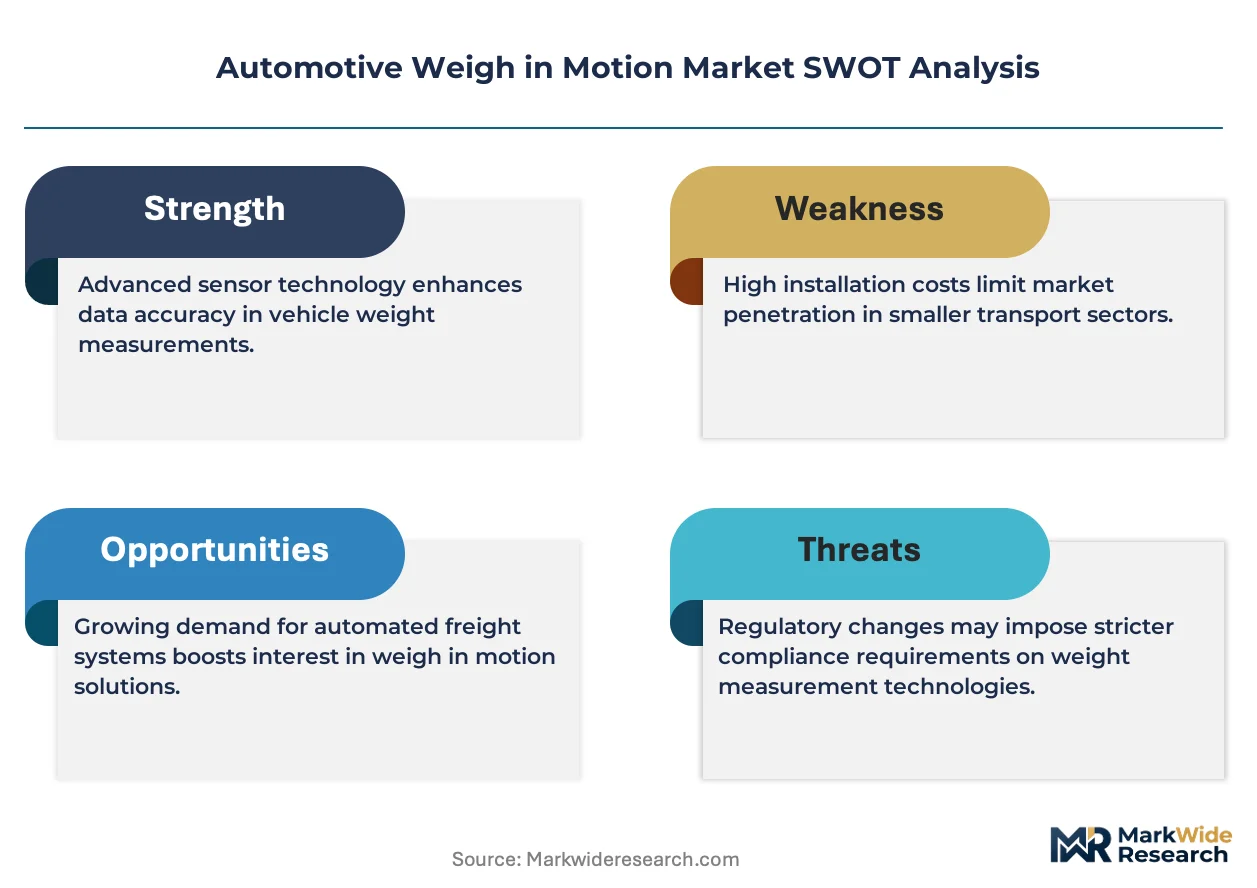
The EU Weigh-in-Motion Directive's accuracy mandates are compressing vendor margins while forcing sensor manufacturers toward quartz piezoelectric investments. State DOT procurement cycles in the U.S. and Germany's KBA type-approval protocols are synchronizing enforcement technology specifications across two continents.
Growth Catalysts
- EU Directive Enforcement Thresholds:The updated Weigh-in-Motion Directive mandates broader roadside deployment across member states. Transport authorities in Germany and France are accelerating permanent installation tenders.
- Highway Tolling Automation:North American tolling authorities are expanding automated enforcement programs. Real-time weight verification reduces manual checkpoint staffing costs.
- Logistics Fleet Integration:Private fleet operators are adopting onboard weigh-in-motion integration for route compliance. E-commerce freight volumes are driving continuous monitoring adoption.
Market Restraints
- Quartz Sensor Supply Concentration:High-purity quartz crystal supply concentrates among specialized German and Swiss suppliers. Geopolitical friction threatens calibration-grade material availability.
- Installation Cost Structure:Permanent embedded road sensor installation requires lane closure and civil works. Municipal budget constraints delay multi-lane highway deployments.
- Accuracy-versus-Speed Tradeoff:Basic load-cell configurations cannot achieve the five-percent accuracy threshold at highway speeds. Low-cost alternatives face exclusion from enforcement-grade tenders.
Strategic Opportunities
- Provincial Highway Networks:Canadian provincial DOTs are consolidating integrated data platforms. International Road Dynamics has established anchor contracts that competitors can challenge.
- EU Green Deal Freight Efficiency:The EU Green Deal's freight efficiency targets are recalibrating enforcement specifications. Carbon-accounting integration creates new sensor data monetization paths.
- Machine Vision Convergence:Camera-based vehicle classification is converging with piezoelectric weight data. Combined enforcement systems reduce false-positive rates for overloaded vehicle detection.
Industry Challenges
- Calibration Technician Scarcity:Certified sensor calibration specialists are concentrated among legacy vendors. New market entrants face twelve-to-eighteen-month workforce development timelines.
- Legacy System Integration:State DOTs require backward compatibility with existing Commercial Vehicle Information Systems and Networks infrastructure. Multi-protocol data exchange adds integration complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Weigh in Motion Market |
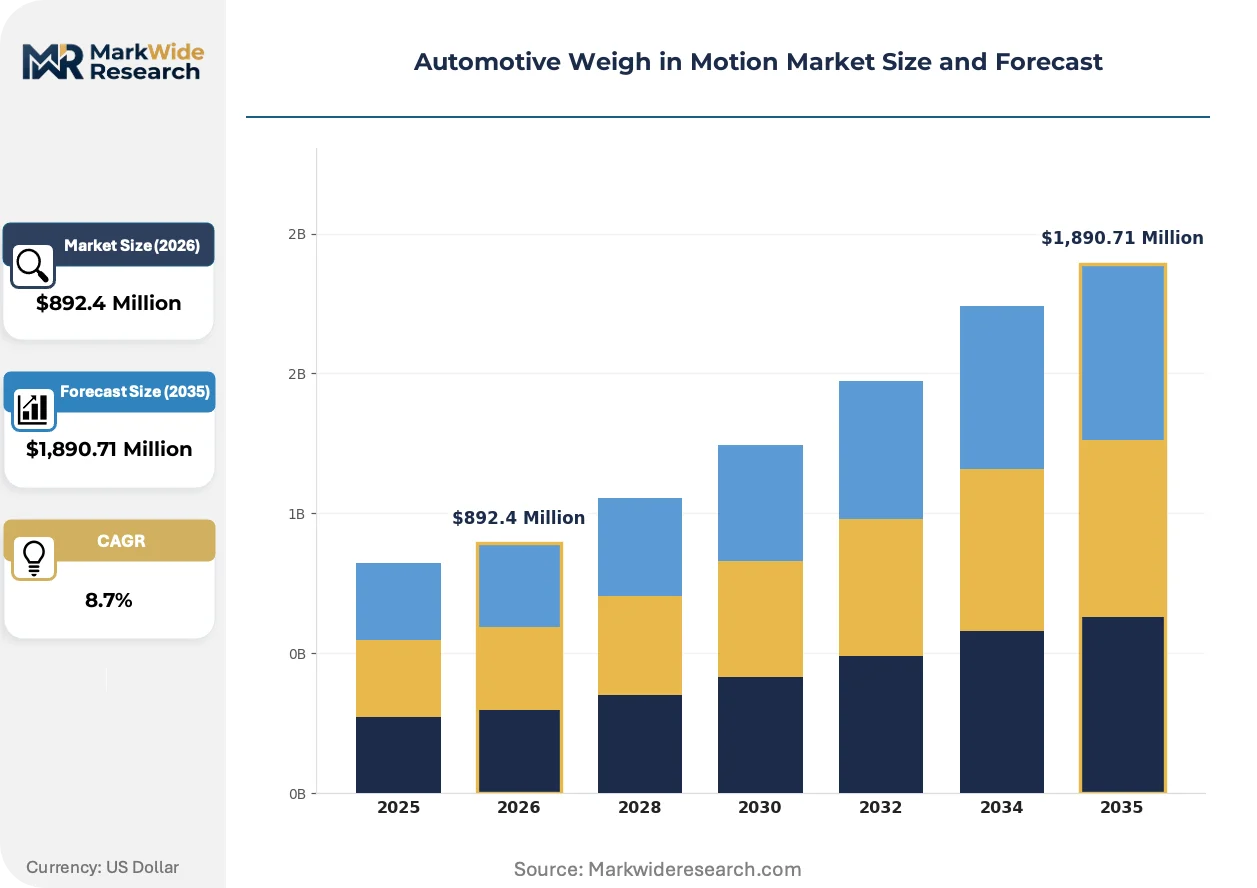
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,890.71 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electromagnetic, Piezoelectric, Load Cell, Optical End User: Transport Authorities, Logistics Companies, Municipalities, Fleet Operators Installation Type: Permanent, Portable, Mobile, Hybrid Application: Traffic Monitoring, Toll Collection, Weight Compliance, Freight Management |
| Companies Covered | Kistler Group, TE Connectivity, International Road Dynamics, SWARCO, Q-Free ASA, Kapsch TrafficCom, Siemens, Avery Weigh-Tronix, Sensys Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Weigh in Motion Market Emerging Trajectories
Quartz piezoelectric sensor technology is compressing the performance gap between high-speed enforcement and static scale precision. Regulatory mandates are synchronizing accuracy thresholds across North American and European procurement cycles.
Multi-layer quartz piezoelectric sensor arrays are integrating with temperature-compensated signal processing for year-round calibration stability. German autobahn operators are deploying these configurations at 120-kilometer-per-hour enforcement corridors. The technology is integrating axle-load data with real-time pavement stress monitoring, enabling predictive maintenance scheduling that reduces sensor replacement frequency.
The EU Weigh-in-Motion Directive's updated accuracy thresholds are filtering non-compliant vendors from public tenders. Germany's KBA enforces type-approval standards that shape sensor calibration protocols across member states. Equipment suppliers must maintain dual certification tracks for EU and U.S. Federal Highway Administration compliance, compressing product development cycles and raising R&D overhead.
Fleet operators are unbundling after-sales service contracts from initial hardware procurement. Large logistics end-users are demanding outcome-based calibration guarantees rather than scheduled maintenance intervals. This behavioral shift is most visible in U.S. interstate corridor contracts, where penalty clauses for accuracy drift are replacing traditional warranty terms.
Automotive Weigh in Motion Market Segmentation
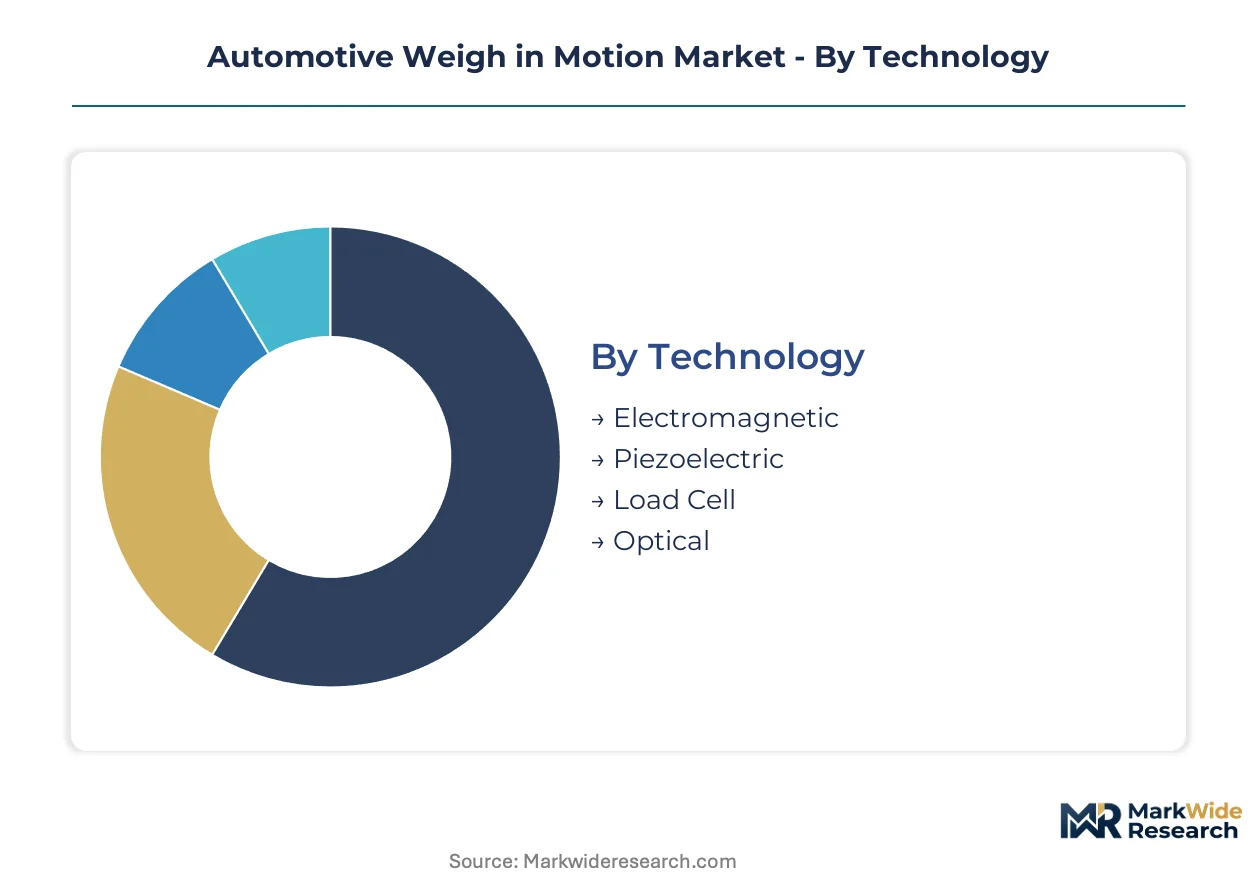
Segmentation in the automotive weigh-in-motion market reveals how capital allocation, regulatory mandates, and operational requirements fragment procurement patterns across transport authorities and commercial fleets. Technology choices and installation permanence determine lifecycle costs and compliance capabilities.
Technology:
Capital intensity varies sharply across sensor technologies, with quartz piezoelectric configurations demanding the highest upfront investment for calibration-grade precision.
- Piezoelectric:Quartz crystal strips embedded in road surfaces generate electrical signals proportional to axle loads, achieving enforcement-grade accuracy thresholds. German autobahn operators and French transport authorities concentrate procurement in this segment, driven by EU Weigh-in-Motion Directive mandates for five-percent accuracy at highway speeds.
- Load Cell:Strain-gauge bending plates measure deflection under vehicle weight, offering lower per-unit costs but reduced precision above 80 kilometers per hour. State DOTs in the U.S. deploy these at lower-speed checkpoint corridors where civil works budgets constrain permanent installation scope.
- Electromagnetic:Inductive loop systems detect vehicle presence and estimate mass through magnetic field distortion. The technology serves supplementary classification roles in integrated enforcement networks.
- Optical:Machine vision and laser profiling capture dimensional data for volume-based weight estimation. Emerging deployments combine optical classification with piezoelectric verification to reduce false-positive enforcement actions.
Piezoelectric installations absorb the bulk of installed capacity in enforcement-grade corridors; optical configurations are expanding most quickly through convergence with camera-based vehicle identification systems.
End User:
Procurement authority and operational control determine how accuracy requirements and budget cycles shape demand concentration across public and private entities.
- Transport Authorities:Federal and state highway agencies deploy permanent roadside installations for automated weight enforcement. U.S. state DOTs synchronize procurement with Federal Highway Administration infrastructure appropriations cycles.
- Logistics Companies:E-commerce freight operators adopt onboard integration for route compliance and axle-load optimization. Continuous monitoring prevents overweight penalties at destination facilities.
- Fleet Operators:Private trucking companies install portable verification systems at distribution centers. Driver behavior analytics link weight data to fuel consumption patterns.
- Municipalities:Local road departments deploy lower-cost portable units for seasonal enforcement campaigns. Budget constraints limit permanent embedded sensor commitments.
Transport authorities command the largest share of capital expenditure; logistics companies are climbing the fastest as fleet-scale digitization accelerates.
Installation Type:
Permanence of civil works investment determines maintenance obligations, calibration frequency, and operational flexibility across enforcement scenarios.
- Permanent:Embedded road sensors with dedicated data acquisition infrastructure require lane closure and asphalt cutting. German KBA type-approval standards govern calibration protocols for these installations.
- Portable:Surface-mounted sensor plates deploy temporarily across multiple locations. Canadian provincial DOTs consolidate these into integrated data platforms for flexible enforcement scheduling.
- Mobile:Vehicle-mounted enforcement units patrol corridors without fixed infrastructure. Municipal budget constraints drive adoption where permanent installation is politically unfeasible.
- Hybrid:Combinations of fixed and portable elements adapt to variable traffic patterns. Toll plaza operators deploy these for peak-period capacity expansion.
Permanent installations anchor enforcement network backbone capacity; portable systems are gaining share fastest through modular procurement frameworks.
Application:
Functional purpose shapes accuracy requirements, data integration depth, and revenue model structures across enforcement and commercial use cases.
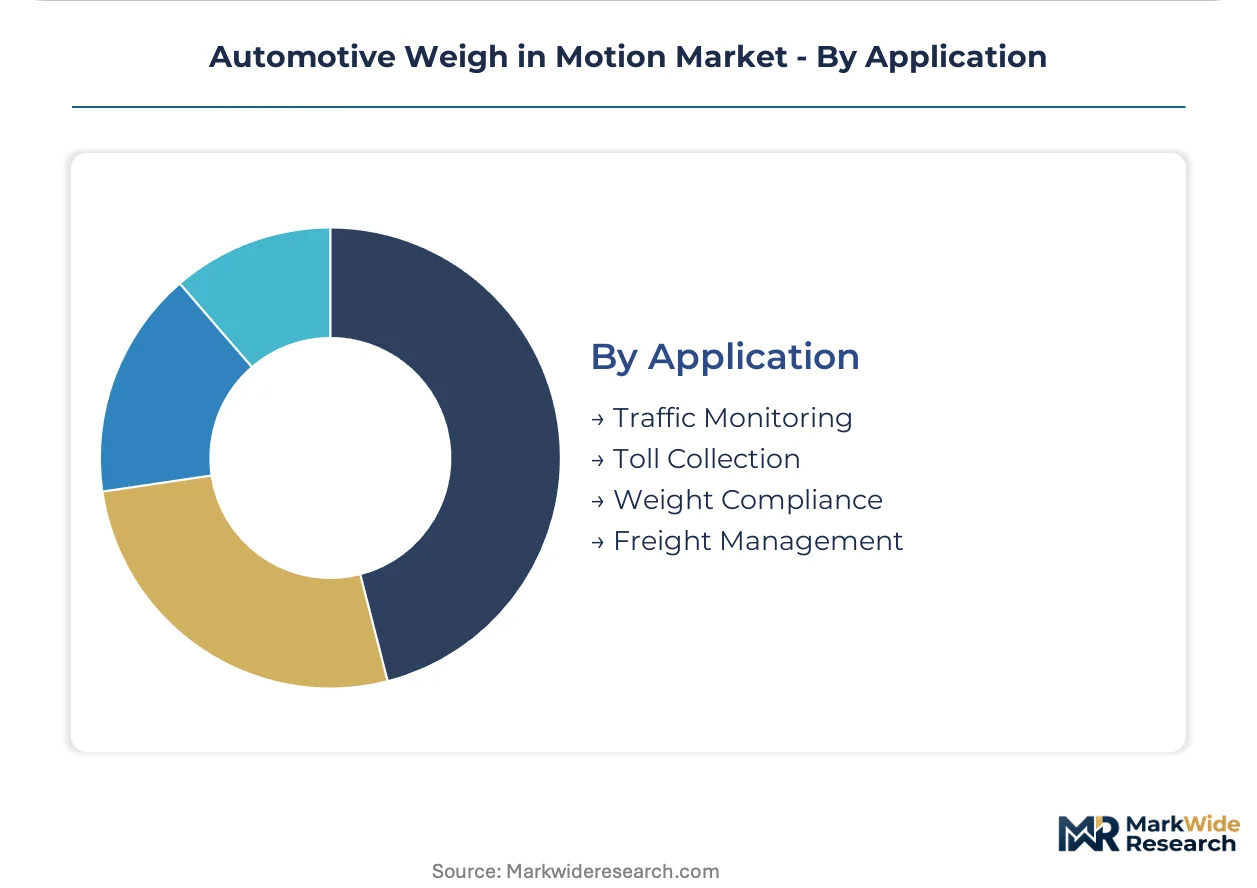
- Weight Compliance:Automated overweight vehicle detection triggers enforcement actions without traffic interruption. EU member states expand roadside deployment under updated Directive mandates.
- Toll Collection:Axle-weight data informs distance-based or mass-distance charging schemes. North American tolling authorities integrate weight verification into automated payment systems.
- Traffic Monitoring:Vehicle classification and flow measurement support congestion management. Piezoelectric arrays feed real-time traffic control centers.
- Freight Management:Continuous load monitoring optimizes cargo distribution and prevents axle overload. Private fleet operators demand outcome-based calibration guarantees for these deployments.
Weight compliance applications dominate public procurement volume; freight management is expanding most steeply through logistics operator digitization initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European sensor manufacturing for automotive weigh-in-motion systems, with the Rhine-Main corridor and Munich technology clusters supporting precision instrumentation supply chains.
United States
State DOT procurement cycles concentrate demand along the I-95 and I-10 freight corridors. The Federal Highway Administration coordinates Commercial Vehicle Information Systems and Networks compliance mandates. Texas DOT and California Caltrans anchor multi-state deployment frameworks for automated weight enforcement.
Germany
Autobahn network upgrades drive permanent piezoelectric installations at 120-kilometer-per-hour enforcement zones. The KBA enforces type-approval standards that shape sensor calibration protocols across EU member states. Bavarian sensor manufacturers cluster around Munich precision engineering corridors.
Canada
Provincial highway contracts consolidate integrated data platforms for flexible enforcement scheduling. Transport Canada aligns with provincial DOTs on interprovincial freight monitoring standards. International Road Dynamics anchors contracts across Ontario and British Columbia highway networks.
France
Transport authorities accelerate permanent installation tenders under updated EU Weigh-in-Motion Directive mandates. The country's national transport regulator enforces roadside deployment timelines for overweight vehicle detection. Lyon and Paris orbital highways concentrate enforcement infrastructure investment.
China
Expressway operators deploy bending-plate systems at toll plaza checkpoints for mass-distance charging schemes. The Ministry of Transport mandates axle-load monitoring across national trunk highway networks. Yangtze River Delta logistics corridors concentrate fleet-scale digitization initiatives.
Automotive Weigh in Motion Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across sensor fabrication and systems integration tiers. The market structure consolidates around precision sensor specialists and diversified traffic infrastructure conglomerates. Three archetypes dominate: quartz sensor heritage houses, diversified electronics manufacturers, and integrated traffic management platforms. Competitive moves center on dual-certification track maintenance for EU and U.S. compliance, plus outcome-based service contract unbundling from hardware procurement.
Within the precision sensor tier, Kistler Group and TE Connectivity exemplify divergent geographic anchoring strategies. Kistler Group represents European quartz heritage specialization, while TE Connectivity occupies a position as a diversified connectivity and sensor conglomerate with North American manufacturing scale. International Road Dynamics anchors Canadian provincial platform integration, sitting within the integrated systems archetype rather than pure component supply.
| Leading Market Players |
|---|
| Kistler Group |
| TE Connectivity |
| International Road Dynamics |
| SWARCO |
| Q-Free ASA |
| Kapsch TrafficCom |
| Siemens |
| Avery Weigh-Tronix |
| Sensys Networks |
| Others |
Supply Flow & Price Mechanics
Certified sensor calibration specialists concentrated in southern Germany and the Swiss Alps command wage premiums that compress margins at the precision tier while widening spreads against basic load-cell alternatives. Labor-cost differentials between these heritage manufacturing clusters and emerging assembly locations in eastern Europe directly shape three-tier pricing stratification across enforcement-grade, commercial-grade, and municipal-grade procurement bands.
Pricing Analysis
Outcome-based calibration guarantees now anchor value-based pricing for permanent roadside installations, with transport authorities paying for verified accuracy uptime rather than scheduled maintenance intervals. Price differentiation rests on KBA type-approval certification and dual EU-U.S. compliance tracks, with fully certified configurations commanding substantial premiums over single-market alternatives. Cost compression in the municipal portable segment is intensifying because budget-constrained local road departments prioritize lowest first-cost procurement over lifecycle accuracy guarantees. Logistics fleet operators show least price sensitivity, accepting penalty-clause structures that transfer accuracy-drift risk to vendors.
Supply Chain Analysis
KBA and FHWA certification gating restricts qualified sensor fabrication to established precision engineering corridors in Germany, Switzerland, and select U.S. manufacturing zones. High-purity quartz crystal supply draws from specialized German and Swiss suppliers, with signal processing electronics sourcing from Taiwanese semiconductor foundries. Single-source vulnerability concentrates in calibration-grade quartz substrate supply, where geopolitical friction threatens material availability. Distribution runs through systems integrators who bundle sensor hardware with civil works contracting and long-term service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors capable of maintaining dual-certification compliance tracks, with EU Weigh-in-Motion Directive accuracy mandates forcing undercapitalized competitors from public tender participation.
For Market Incumbents: Cement dominance in German autobahn and U.S. I-95 corridor deployments by capturing scarce certified calibration technician capacity through apprenticeship pipeline investments. Acquire portable systems specialists in Canada and France to preempt modular procurement frameworks that threaten permanent installation revenue streams. Dual-certification maintenance represents the critical defensive lever against emerging Asian sensor manufacturers.
For New Entrants and Emerging Players: Cloud-based calibration-as-a-service platforms offer a direct-channel route to bypass incumbent service contract bundling. Target municipal portable enforcement campaigns in eastern European member states where EU Directive compliance deadlines outpace local vendor qualification. White-space exists in machine vision convergence systems that combine camera-based classification with piezoelectric verification for reduced false-positive detection.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated traffic management platforms given EU Green Deal freight efficiency targets mandating carbon-accounting sensor data integration. Long-term viability favors vendors with captive quartz sensor fabrication and established KBA type-approval protocols. Monitor U.S. infrastructure appropriation passage as inflection indicator for state DOT procurement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Track Investment | Maintains eligibility for EU and U.S. Federal Highway Administration procurement cycles simultaneously. |
| Quartz Sensor Fabrication Scale-Up | Captures scarce high-purity crystal supply and reduces dependency on German-Swiss substrate vendors. |
| Machine Vision Convergence Development | Combines piezoelectric weight data with camera-based vehicle classification for enforcement accuracy. |
| Outcome-Based Service Contract Unbundling | Aligns vendor compensation with calibration uptime guarantees rather than scheduled maintenance. |
| Provincial Platform Integration Acquisition | Consolidates Canadian and French flexible enforcement scheduling into integrated data architectures. |
Methodological Framework
Independent corroboration across state DOT procurement officers, KBA certification auditors, and logistics fleet operations managers underwrites the qualitative findings. Primary interviews with sensor calibration specialists, civil works contractors, and tolling authority technology directors combined with secondary validation from Federal Highway Administration appropriations documentation, EU Directive implementation timelines, and provincial highway contract databases. Bottom-up installation unit economics and top-down enforcement infrastructure spending triangulate market sizing.
Comparable-period anchoring to historical EU Directive adoption waves and U.S. infrastructure investment cycles structured the forecast window across the analysis window. Segmentation dimensions modeled include sensor technology tier, installation permanence type, end-user procurement authority, and regional regulatory compliance cluster. CAGRs derived from deployment pipeline analysis and replacement cycle timing, with freight volume growth and enforcement automation penetration as industry-specific demand inputs.
The model holds under sustained EU Directive enforcement and stable federal infrastructure appropriation levels; deviation in quartz supply availability or KBA certification timeline acceleration would shift vendor competitive positioning. Forecasts reflect documented assumptions regarding procurement cycle synchronization and certification capacity expansion. A model refresh is warranted upon material change in EU Green Deal freight efficiency target implementation or U.S. state DOT multi-year capital plan revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Vehicle Crash Testing System Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market
Automotive Testing and Simulation
Wheel Alignment Equipment Market
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Electric Vehicle Test Bench Market
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
Automotive Driving Simulators Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market