
 Automotive Door Stabilizer Market | 2026-2036
Automotive Door Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Door Stabilizer Market Outlook
NHTSA side-impact protocols is hardening the cost-of-entry calculus for door stabilizer suppliers serving North American OEM programs. Aisin Seiki Co., Ltd leverages its integrated powertrain-to-chassis engineering footprint to sustain competitive positioning in hydraulic stabilization modules. Faurecia anchors its presence through vertical control over seating and door system integration, while Magna International Inc competes on manufacturing scale across multiple premium vehicle platforms.
Automotive door stabilizers are structural or semi-active components engineered to minimize lateral deflection, vibration, and intrusion during dynamic loading, typically fabricated from high-tensile steel alloys, aluminum extrusions, or polymer-composite hybrids with specified yield strengths exceeding 500 MPa. Their primary industrial purpose is to maintain door panel geometric integrity under crash pulses while enabling smooth operational kinematics across temperature extremes. Hydraulic stabilizers dominate current OEM fitment volumes owing to proven durability in high-cycle environments, whereas magnetic stabilizers represent the fastest-expanding technology segment as automakers pursue mass reduction targets without sacrificing stiffness. Active stabilization systems command concentrated margin pools due to embedded sensor arrays and real-time control firmware.
Federal Motor Vehicle Safety Standards in the United States, ECE R95 regulations administered by European type-approval authorities, and China's GB standards for passenger vehicle side-impact protection collectively shape product certification requirements and material selection protocols across major supply corridors. Suppliers must synchronize design validation with divergent homologation timelines, particularly where active systems interface with vehicle network architectures. Stakeholders should monitor how software-defined vehicle platforms redefine the boundary between mechanical stabilization and centralized chassis control.
Market Dynamics
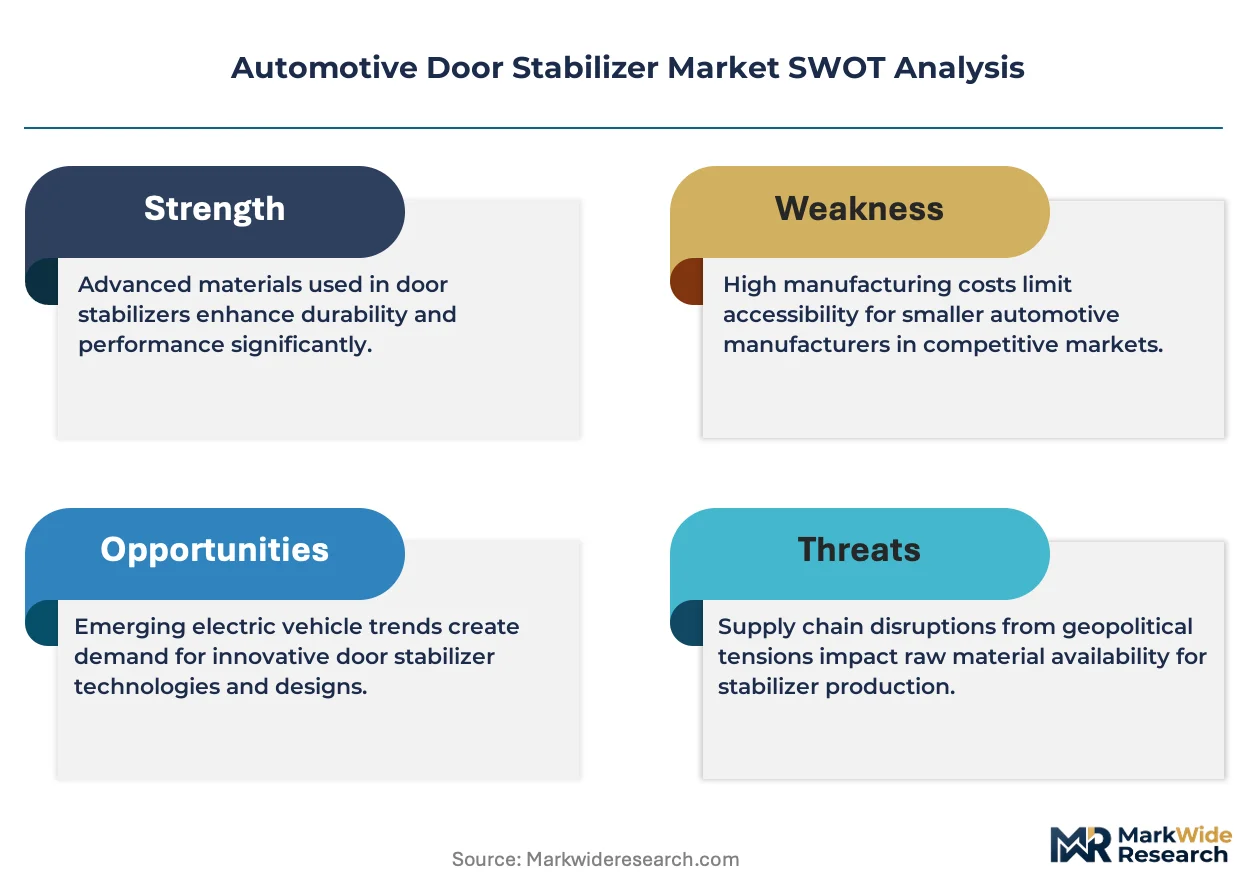
Magnetic stabilization architectures are compressing traditional hydraulic module lifecycles as OEMs chase mass reduction targets without sacrificing side-impact stiffness thresholds mandated by evolving crash protocols.
Growth Catalysts
- Side-Impact Mandates:NHTSA protocols in the United States and ECE R95 in Europe are compelling door reinforcement redesigns that favor advanced stabilizer integration.
- Electric Vehicle Platforms:Battery-electric architectures prioritize weight reduction, accelerating specification of aluminum-composite hybrid stabilizers over conventional steel assemblies.
- German Premium Manufacturing:Stuttgart and Munich engineering centers are embedding active stabilization with real-time sensor feedback into next-generation vehicle platforms.
Market Restraints
- High-Tensile Steel Volatility:Yield-strength-grade alloy pricing swings compress margin predictability for stamped reinforcement suppliers.
- Active System Validation Burden:Embedded firmware and sensor arrays extend homologation timelines, delaying program revenue recognition.
- Hydraulic Module Durability:Proven high-cycle performance of legacy hydraulic stabilizers creates specification inertia among risk-averse procurement teams.
Strategic Opportunities
- Software-Defined Vehicle Convergence:Centralized chassis control architectures create openings for stabilizer systems with CAN-FD and Ethernet connectivity.
- China GB Standard Alignment:Passenger vehicle side-impact protection mandates under national GB frameworks favor suppliers with localized testing capabilities.
- Polymer-Composite Hybridization:Glass-fiber-reinforced polymer cores with aluminum face sheets enable 30-40% mass reduction in premium door modules.
Industry Challenges
- Multi-Homologation Synchronization:Divergent NHTSA, ECE, and GB validation timelines strain engineering bandwidth and program management resources.
- Cross-Domain Integration Complexity:Active stabilizer firmware must interface with legacy body control modules lacking standardized API architectures.
- Thermal Management Expertise Scarcity:Temperature-extreme operational requirements demand material scientists familiar with polymer creep behavior across -40°C to 85°C ranges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Door Stabilizer Market |
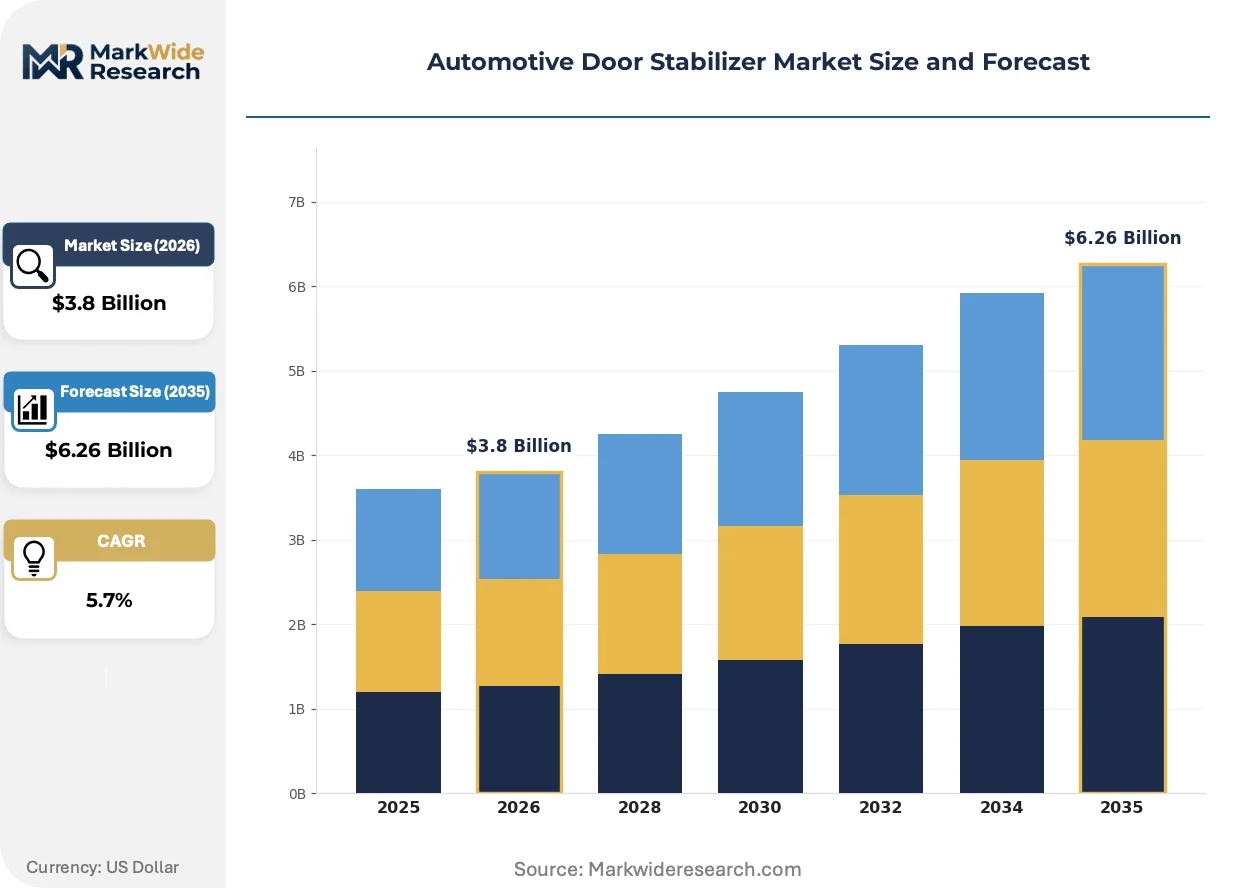
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Stabilizers, Pneumatic Stabilizers, Mechanical Stabilizers, Magnetic Stabilizers Application: OEMs, Aftermarket, Replacement, Custom Builds End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Technology: Active Stabilization, Passive Stabilization, Smart Sensors, Control Systems |
| Companies Covered | Aisin Seiki Co., Ltd, Faurecia, Magna International Inc, Valeo SA, ZF Friedrichshafen AG, Continental AG, Denso Corporation, Schaeffler AG, Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Door Stabilizer Market Strategic Shifts
Door stabilization engineering is bifurcating along passive-structural and active-intelligent pathways, with material science and embedded electronics converging to redefine performance benchmarks.
Magnetic stabilizer technology is modularizing around rare-earth actuator arrays that deliver variable stiffness on demand. Luxury electric vehicle programs in Germany and California are specifying these systems for flagship sedans launching in 2026-2027. The technology is modularizing supplier relationships, enabling tier-two specialists to deliver complete subassemblies rather than raw components to door system integrators.
ECE R95 revisions administered by European type-approval authorities are tightening intrusion velocity thresholds for side-pole impacts. This regulatory compression is forcing redesign of B-pillar-to-door load paths and accelerating adoption of multi-material stabilizer configurations. Premium OEMs with engineering centers in Germany and Sweden are responding with predictive simulation workflows that front-load crash validation.
Fleet procurement of standardized door architectures is consolidating specification power at commercial vehicle divisions of major OEMs. Long-haul truck and van manufacturers are pushing for stabilizer modules with identical mounting interfaces across multiple cab variants, displacing bespoke door engineering for individual nameplates. This pattern is most visible in North American heavy-duty truck manufacturing, where platform commonality reduces service part complexity.
Automotive Door Stabilizer Market Segmentation
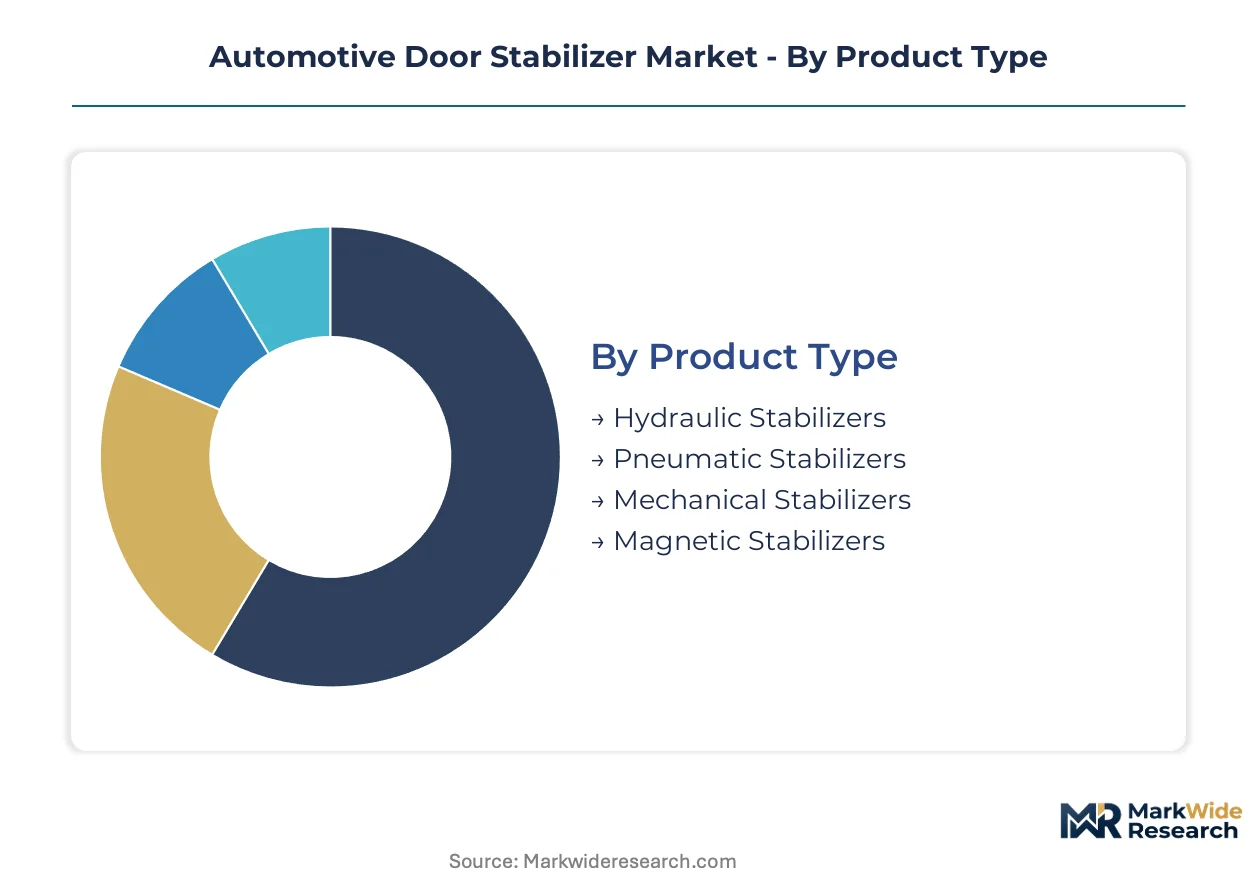
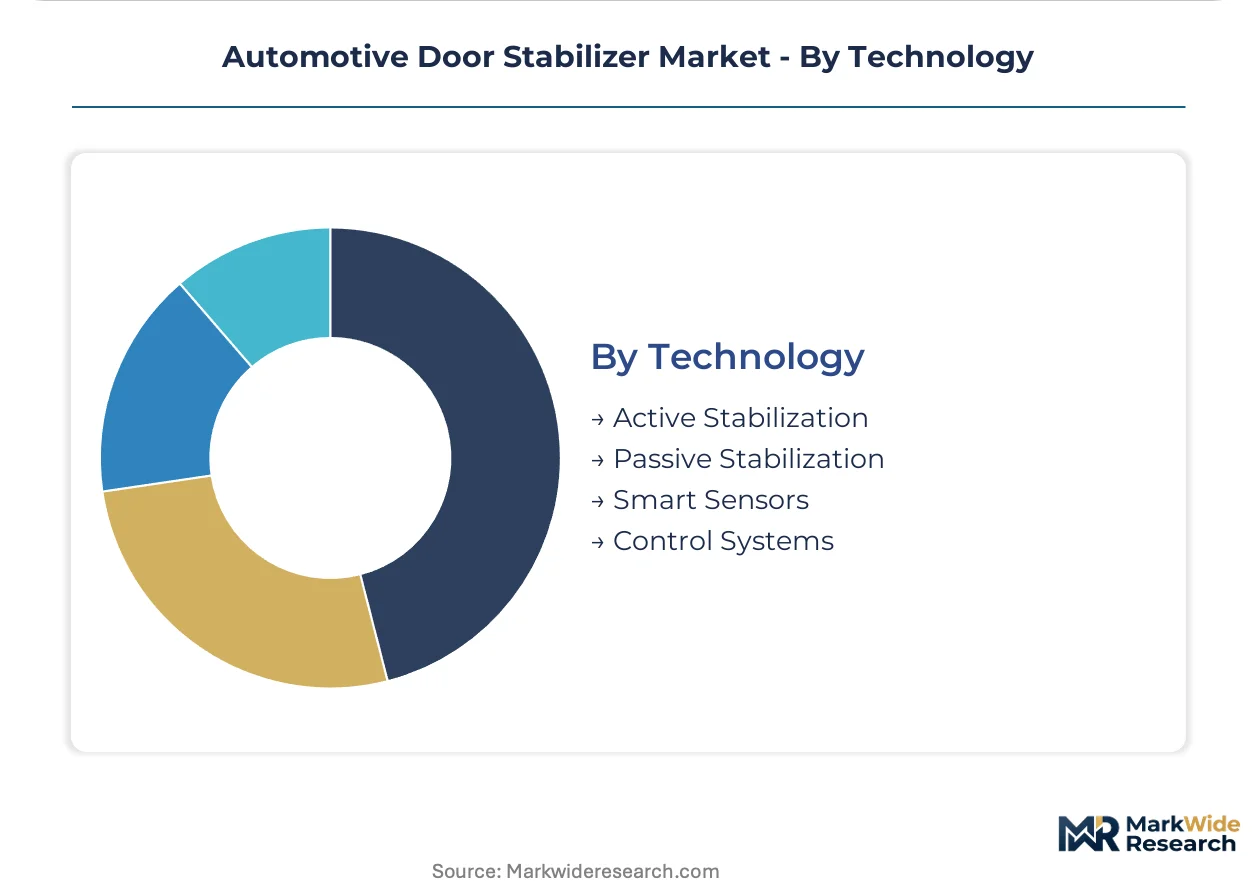
Door stabilizer procurement patterns diverge sharply between high-volume platforms and premium architectures, with material selection and control intelligence serving as the primary sorting mechanisms. Suppliers must calibrate production footprints across these divides to capture margin pools concentrated in active stabilization modules.
Product Type:
Hydraulic modules dominate current fitment volumes while magnetic architectures command expanding specification in mass-sensitive platforms.
- Hydraulic Stabilizers:Sealed fluid-damper assemblies fabricated from cast aluminum housings with nitrile seals deliver proven durability across temperature extremes. Fleet procurement teams at North American commercial vehicle divisions specify these modules for standardized cab architectures prioritizing service-interval predictability.
- Magnetic Stabilizers:Rare-earth actuator arrays enable variable stiffness modulation through electromagnetic field adjustment. German premium OEMs embed these systems in flagship electric sedans where mass reduction targets intersect with side-impact stiffness mandates.
- Pneumatic Stabilizers:Compressed-air damping chambers serve specialized commercial vehicle applications requiring rapid stiffness adjustment.
- Mechanical Stabilizers:Coil-spring and torsion-bar assemblies persist in economy passenger vehicle segments where procurement prioritizes unit cost over adaptive performance.
Mature deployment sits with hydraulic stabilizers. Newer deployment is concentrated in magnetic stabilizers.
Application:
Specification authority concentrates at OEM engineering centers for new platform development, while aftermarket channels capture replacement cycles and customization demand.
- OEMs:Original equipment programs require synchronisation with vehicle platform timelines and network architecture integration. Active stabilizer firmware must validate against body control module interfaces during prototype phases.
- Aftermarket:Independent distributors serve collision repair and upgrade segments with retrofit-compatible modules. Channel fragmentation across regional parts networks complicates inventory planning.
- Replacement:Service part demand correlates with vehicle age distribution and regional fleet turnover rates.
- Custom Builds:Low-volume specialty manufacturers specify bespoke stabilizer geometries for modified suspension architectures.
Revenue concentration favors OEM programs. Margin expansion is steepest in custom builds.
End User:
Vehicle electrification is redistributing demand across passenger and commercial segments, with battery mass dictating material selection protocols.
- Electric Vehicles:Aluminum-composite hybrid stabilizers address mass-compensation requirements imposed by battery pack weight. NHTSA side-impact protocols drive specification of multi-material reinforcement in California-engineered platforms.
- Luxury Vehicles:Active stabilization with real-time sensor feedback commands concentrated engineering investment at Stuttgart and Munich development centers.
- Passenger Vehicles:High-volume compact and mid-size segments standardize on hydraulic modules with stamped steel reinforcement.
- Commercial Vehicles:Long-haul truck manufacturers push for common mounting interfaces across cab variants to reduce service complexity.
Specification leadership resides with luxury vehicles. Volume scaling runs through passenger vehicles.
Technology:
The boundary between mechanical stabilization and chassis control electronics is dissolving as software-defined vehicle architectures mature.
- Active Stabilization:Real-time stiffness adjustment via embedded actuators and control firmware. These systems interface with centralized chassis computers through CAN-FD and Ethernet protocols.
- Smart Sensors:Accelerometer and strain-gauge arrays feed predictive algorithms for impact anticipation. Integration complexity extends validation timelines for suppliers lacking embedded systems expertise.
- Passive Stabilization:Fixed-geometry reinforcement without electronic control dominates cost-sensitive production tiers.
- Control Systems:Software modules governing stabilizer response curves require cybersecurity certification under emerging vehicle network standards.
Technology maturation centers on passive stabilization. Capability investment is concentrating in active stabilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in northern Mexico and India's automotive corridors concentrate contract manufacturing for door stabilizer subassemblies. Stuttgart engineering centers anchor specification authority for active stabilization systems. Detroit-area technical centers coordinate NHTSA compliance validation for North American OEM programs.
United States
NHTSA side-impact protocols drive specification of multi-material reinforcement architectures across Michigan and Ohio manufacturing clusters. Federal Motor Vehicle Safety Standard 214 mandates intrusion velocity thresholds that compress design cycles for Detroit-based Tier-1 suppliers. Ann Arbor technical centers validate active stabilizer firmware against body control module interfaces for premium electric vehicle platforms.
Germany
ECE R95 revisions tighten side-pole impact requirements, forcing B-pillar-to-door load path redesigns at Stuttgart and Munich engineering centers. KBA type-approval timelines extend validation cycles for embedded sensor arrays in active stabilization modules. Bavarian premium OEMs integrate magnetic actuator systems with real-time chassis control for flagship electric sedans launching 2026-2027.
China
GB standards for passenger vehicle side-impact protection mandate localized testing capabilities for aluminum-composite hybrid stabilizers. MIIT new energy vehicle subsidies accelerate specification of mass-reduced door modules across Yangtze River Delta manufacturing corridors. Shanghai engineering centers synchronize multi-material validation with divergent export homologation timelines for European and North American programs.
Japan
METI carbon neutrality roadmaps pressure suppliers to displace high-tensile steel with polymer-composite hybrids in door reinforcement architectures. Nagoya-area manufacturing clusters specialize in hydraulic module production for high-cycle commercial vehicle applications. JIS standards for automotive structural components shape material selection protocols for stamped reinforcement suppliers serving ASEAN export markets.
India
PLI scheme incentives for advanced automotive components attract magnetic stabilizer assembly investments into Tamil Nadu and Gujarat manufacturing zones. BIS certification requirements for side-impact protection create entry barriers for imported subassemblies lacking localized crash-test validation. Pune engineering centers adapt European active stabilization architectures for cost-optimized compact vehicle platforms.
Automotive Door Stabilizer Market Competitive Environment
German producers anchor the premium-tier specification vector; Japanese and North American specialists hold volume manufacturing positions. The vendor base organizes around three strategic archetypes: integrated chassis-system suppliers with powertrain-to-body engineering footprints, door-module integrators with seating and interior control, and rare-earth actuator specialists delivering complete magnetic subassemblies. Dominant competitive moves include backward integration into aluminum extrusion and polymer-composite core manufacturing, plus technology licensing agreements for CAN-FD interface firmware.
Within the integrated-system tier, Aisin Seiki Co., Ltd and ZF Friedrichshafen AG represent engineering breadth spanning powertrain, chassis, and body electronics. Faurecia exemplifies the door-module integrator archetype through vertical control over seating and closure systems. Among North American scale manufacturers, Magna International Inc occupies a position across multiple premium vehicle platforms. Specialists in magnetic stabilization technology include Schaeffler AG, which anchors rare-earth actuator development for variable-stiffness applications.
| Leading Market Players |
|---|
| Aisin Seiki Co., Ltd |
| Faurecia |
| Magna International Inc |
| Valeo SA |
| ZF Friedrichshafen AG |
| Continental AG |
| Denso Corporation |
| Schaeffler AG |
| Bosch GmbH |
| Others |
Value Chain & Pricing Dynamics
Active-passive technology bifurcation separates magnetic stabilizer premiums from hydraulic module commoditization, with certification-grade differentiation manifesting in both procurement pricing and supplier consolidation patterns across German premium and North American fleet channels.
Pricing Analysis
Lead-time premiums attach to magnetic stabilizer modules with embedded sensor arrays and KBA-validated firmware, while spot inventory discounts flow through hydraulic assemblies serving standardized commercial vehicle cab architectures. Three-tier pricing structure across premium, standard, and economy levels sorts by certification complexity, with NHTSA-compliant active systems commanding procurement premiums and economy hydraulic units facing cost compression from high-tensile steel alloy volatility. Fleet procurement teams at North American OEMs exhibit highest price sensitivity, whereas Stuttgart engineering centers prioritize performance validation over unit economics.
Supply Chain Analysis
Remanufacturing flows for hydraulic stabilizer cores concentrate in northern Mexico contract manufacturing zones, with refurbished cast aluminum housings re-entering aftermarket channels through independent distributors. Production gravity centers on Germany, China, and Japan, with rare-earth actuator arrays for magnetic systems drawing from Chinese processing facilities and Japanese magnet fabrication. Single-source vulnerability sits with neodymium supply concentration, while distribution runs through Tier 1 door module integrators with captive seating and closure system control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with backward integration into aluminum extrusion and polymer-composite core manufacturing representing the decisive upstream lever separating margin leaders from component assemblers.
For Market Incumbents: Anticipate magnetic stabilizer specification acceleration by securing captive rare-earth actuator supply through long-term offtake agreements with Chinese processors. Defensive consolidation of hydraulic module service part networks in North American commercial vehicle channels protects against aftermarket disintermediation. Prioritize firmware cybersecurity certification under emerging vehicle network standards to maintain OEM program access.
For New Entrants and Emerging Players: Sensor-integrated active stabilization firmware offers the most penetrable wedge for specialist entrants lacking legacy hydraulic manufacturing scale. White-space concentration sits with CAN-FD interface modules serving software-defined vehicle platforms at California and Shanghai engineering centers. Go-to-market execution should anchor on technology licensing agreements with established door system integrators rather than direct OEM confrontation.
For Investors and Strategic Acquirers: Re-rating potential sits with rare-earth actuator specialists given ECE R95 revision timelines accelerating magnetic stabilizer adoption. Long-term viability favors suppliers with demonstrated multi-homologation synchronization capabilities across NHTSA, KBA, and MIIT validation frameworks. Monitor GB standard alignment announcements from Yangtze River Delta manufacturing corridors as inflection signals for China market entry valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Rare-Earth Actuator Supply Agreement | Captive neodymium sourcing from Chinese processors insulates magnetic stabilizer margins against commodity volatility. |
| Software-Defined Vehicle Firmware Investment | Cybersecurity-certified CAN-FD interfaces unlock centralized chassis control architectures at Stuttgart engineering centers. |
| Multi-Material Hybridization Scale-Up | Glass-fiber-reinforced polymer core production enables 30-40% mass reduction for electric vehicle door modules. |
| Regional Homologation Laboratory Expansion | Localized crash-test validation accelerates GB standard compliance for Yangtze River Delta manufacturing programs. |
| Aftermarket Service Part Network Consolidation | Inventory control over hydraulic module refurbishment flows captures fleet procurement spend in North American commercial vehicle channels. |
Study Parameters
Independent corroboration across Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork combined structured interviews with hydraulic module plant managers in Nagoya-area manufacturing clusters and magnetic stabilizer firmware developers at Bavarian engineering centers. Secondary validation drew from NHTSA FMVSS 214 docket filings, ECE R95 revision documentation, MIIT new energy vehicle subsidy disclosures, and vehicle production databases. Bottom-up segment sizing triangulated against top-down OEM platform content analysis.
Comparable-period anchoring aligned the projection horizon against historical fitment rate trajectories across hydraulic, magnetic, and active stabilization technologies. The analytical framework modeled segmentation across propulsion architecture, vehicle class, content per vehicle, and regional production cluster dimensions. CAGRs derived from technology substitution curves weighted by regulatory compliance timelines and battery-electric platform launch densities. Forecast inputs incorporated rare-earth price volatility scenarios and multi-homologation validation cycle distributions.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to side-pole impact protocols and breakthrough polymer creep resistance discoveries outside -40°C to 85°C operational ranges. Forecasts reflect assumptions regarding ECE R95 implementation consistency and NHTSA enforcement posture continuity. Practitioners should monitor MIIT subsidy recalibration announcements and KBA type-approval backlog indicators for early signals of demand inflection or supply constraint.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Auto Glass Encapsulation Market
Automotive Interior & Exterior
Global Automotive Windows and Exterior Sealing Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Automotive Center Stack Display Market