
 Global Automotive Window Power Sunshade Market | 2026-2036
Global Automotive Window Power Sunshade Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Window Power Sunshade Market Analysis
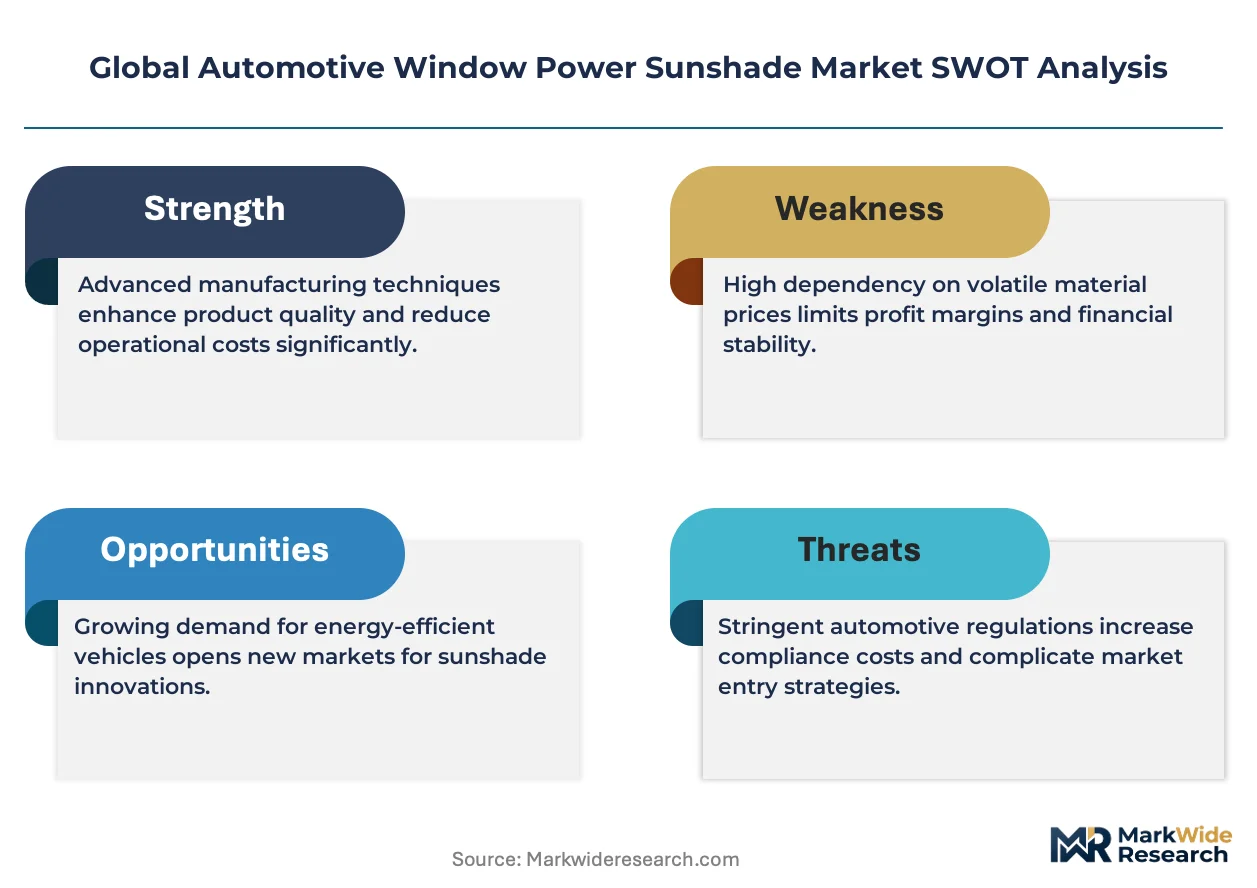
The EU F-Gas Regulation is broadening the cost-of-entry calculus for suppliers serving European OEM thermal management programs. BOS GmbH and Co. KG leverages deep integration into German premium vehicle supply chains. Webasto SE sustains technology leadership in roof and glazing comfort systems. Ashimori Industry Co. Ltd. anchors Asian manufacturing scale for power-operated shade mechanisms.
Automotive window power sunshades are electromechanically actuated screening devices, typically integrating DC motors, polymer-composite fabric substrates, and CAN-bus control modules to modulate solar heat gain and cabin luminosity. These systems reduce HVAC load and protect interior surfaces from ultraviolet degradation. Power sunshades lead product type adoption as OEMs phase out manual variants, while factory-installed configurations command margin concentration over retro-fitted alternatives. Polyester material formulations dominate cost-optimized segments, though fabric composites sustain premium positioning through acoustic damping properties.
The EPA's vehicle efficiency testing protocols in the United States, China's MIIT passenger vehicle energy consumption standards, and Japan's METI automotive component quality certifications collectively shape motorization requirements and electromagnetic compatibility benchmarks. REACH compliance in Europe restricts certain phthalate plasticizers in PVC shade substrates, redirecting material selection toward thermoplastic elastomer alternatives. Stakeholders must monitor evolving thermal efficiency test cycles across multiple regulatory jurisdictions to anticipate specification changes before platform lock-in.
Market Dynamics
Factory-installed power sunshade penetration is displacing manual alternatives as OEMs integrate thermal management into vehicle efficiency compliance frameworks. The EU Green Deal's cabin efficiency mandates and China's MIIT energy consumption standards are accelerating motorization requirements across premium electric vehicle platforms.
Growth Catalysts
- EU Green Deal thermal mandates:Cabin efficiency targets under the European Commission's climate framework are compelling OEMs to specify motorized sunshades as standard equipment in luxury and mid-tier segments.
- Yangtze River Delta clustering:Concentrated automotive manufacturing in China's Jiangsu and Zhejiang provinces is generating localized demand for integrated glazing comfort systems.
- Polymer-composite fabric advances:Acoustic-damping substrate technologies are extending power sunshade adoption into premium electric vehicle cabins where NVH performance is critical.
Market Restraints
- DC motor cost volatility:Rare earth magnet price fluctuations and semiconductor shortages for CAN-bus control modules are compressing supplier margins.
- German supply chain concentration:Premium OEM dependency on specialized electromechanical actuator suppliers in Baden-Württemberg creates single-source vulnerability.
- REACH substrate restrictions:ECHA phthalate limitations on PVC shade materials are forcing costly reformulation toward thermoplastic elastomer alternatives.
Strategic Opportunities
- India PLI scheme alignment:Component manufacturing incentives under India's automotive production-linked incentive program are attracting power sunshade assembly investment.
- Retrofit channel expansion:Independent service networks and certified installer programs are opening aftermarket revenue streams beyond factory-fit configurations.
- Smart glass convergence:Integration with electrochromic glazing and vehicle thermal management AI is creating bundled system opportunities.
Industry Challenges
- EMC certification timelines:Japan's METI electromagnetic compatibility testing protocols and EPA vehicle efficiency validation cycles are extending product qualification periods.
- Legacy platform integration:CAN-bus architecture mismatches between newer power sunshade modules and older vehicle electrical systems are complicating retrofit installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Window Power Sunshade Market |
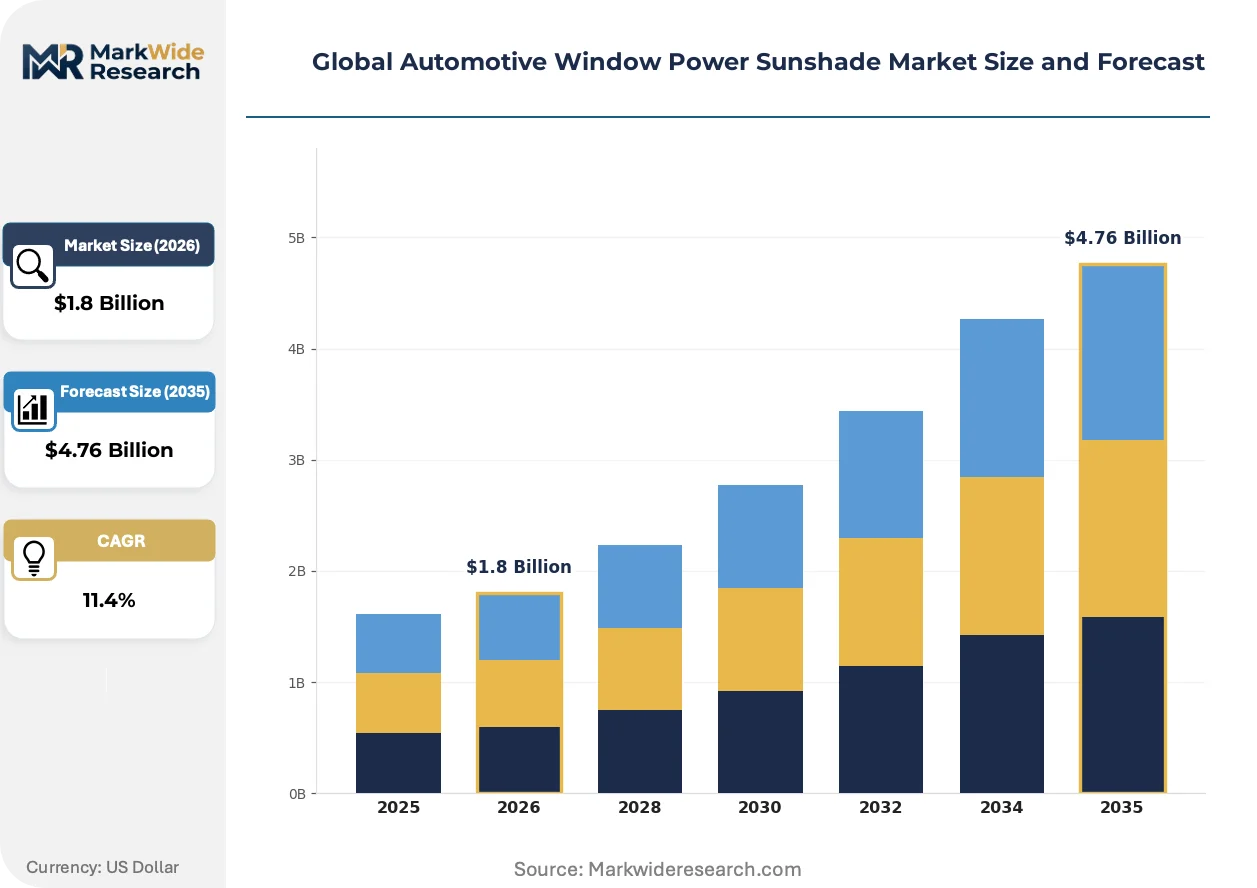
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Sunshades, Power Sunshades, Retractable Sunshades, Fixed Sunshades Material: Fabric, Polyester, PVC, Metal End User: OEMs, Aftermarket Buyers, Vehicle Assemblers, Tier-1 Suppliers Installation Type: Integrated, Retro-fitted, Factory-installed, Modular |
| Companies Covered | BOS GmbH and Co. KG, Ashimori Industry Co. Ltd., Inalfa Roof Systems Group B.V., Eclipse SunShades, CIE Automotive SA, Webasto SE, Macauto Industrial Co. Ltd., Vaccess India Pvt. Ltd., Inteva Products LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Window Power Sunshade Market Emerging Trajectories
Electromechanical shade systems are converging with intelligent vehicle thermal management architectures. Material science advances and regulatory test cycle evolution are reshaping specification requirements across OEM supply chains.
Smart fabric substrates with embedded photovoltaic sensing layers are expanding into premium electric vehicle glazing systems. German luxury OEMs are specifying these materials for panoramic roof applications where real-time solar load modulation reduces HVAC energy draw. The technology is expanding into mid-tier platforms as thermoplastic elastomer formulations achieve cost parity with conventional polyester weaves.
China's MIIT passenger vehicle energy consumption standards are tightening thermal efficiency test procedures. The regulation now captures cabin solar heat gain in official efficiency ratings, compelling domestic OEMs to motorize rear and side window shading. Domestic manufacturers in the Yangtze River Delta are responding with localized DC motor and control module sourcing.
Fleet procurement models for luxury electric vehicle subscriptions are altering shade system specification patterns. Corporate mobility providers in Germany are demanding standardized thermal comfort packages across vehicle classes, compressing variant complexity for suppliers. This concentration is most visible in Munich and Stuttgart corporate fleet procurement where bundled glazing specifications now dominate individual option selection.
Global Automotive Window Power Sunshade Market Segmentation
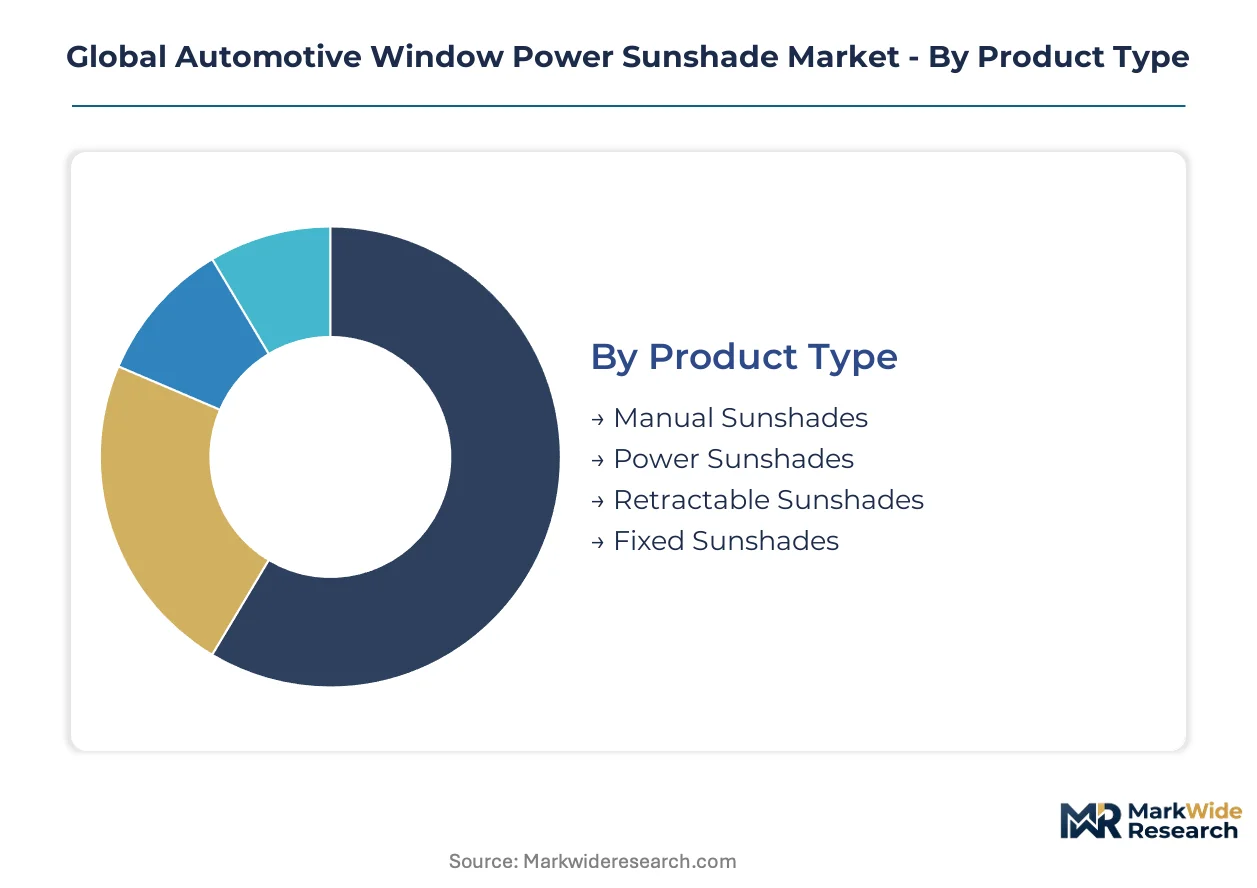
Segmentation reveals how factory-installed motorization is displacing manual alternatives across OEM supply chains. Material selection and installation architecture determine margin capture and regulatory compliance pathways for suppliers.
Product Type:
Upgrade cycles from manual to powered systems are accelerating as thermal efficiency mandates harden across major automotive markets.
- Power Sunshades:Electromechanically actuated systems integrate DC motors, polymer-composite fabrics, and CAN-bus control modules to modulate solar heat gain. Demand concentrates in Germany's luxury electric vehicle fleets where EU Green Deal cabin efficiency targets compel OEM specification as standard equipment.
- Manual Sunshades:Hand-operated mechanical systems with spring-tensioned roller mechanisms and polyester mesh substrates. OEMs in China's Yangtze River Delta are phasing these out fastest as MIIT energy consumption standards now capture cabin solar load in official vehicle ratings.
- Retractable Sunshades:Collapsible screening systems deploying along guide rails for panoramic roof applications.
- Fixed Sunshades:Static-mounted screening elements bonded directly to glazing assemblies.
Volume placements concentrate in Power Sunshades; the faster expansion belongs to Retractable Sunshades.
Material:
Cost tiers separate acoustic-damping premium substrates from mass-market polymer weaves.
- Fabric:Woven textile substrates incorporating thermoplastic elastomer formulations to meet REACH phthalate restrictions. German premium OEMs specify these for NVH-critical electric vehicle cabins where acoustic damping properties justify material cost premiums.
- Polyester:Cost-optimized synthetic fiber weaves dominating high-volume production. China's domestic manufacturers in Jiangsu and Zhejiang provinces source these for localized DC motor integration programs serving MIIT-compliant vehicle platforms.
- PVC:Legacy vinyl substrates facing ECHA-driven reformulation pressure.
- Metal:Perforated aluminum or steel mesh for structural load-bearing applications.
Polyester commands current volume leadership; Fabric composites are climbing the fastest.
End User:
Customer type determines specification authority and margin capture timing.
- OEMs:Original equipment manufacturers integrating sunshades at vehicle platform design stage. Thermal management bundling with electrochromic glazing and AI-driven HVAC systems is reshaping procurement specifications across German and Chinese premium vehicle programs.
- Aftermarket Buyers:Independent vehicle owners and fleet operators purchasing through certified installer networks. Retrofit channel expansion in India's automotive PLI scheme corridors is attracting power sunshade assembly investment for localized supply.
- Vehicle Assemblers:Contract manufacturing facilities executing final vehicle integration.
- Tier-1 Suppliers:Specialized electromechanical component manufacturers feeding OEM assembly lines.
Factory-fit volumes dominate OEM relationships; aftermarket channels are gaining share fastest.
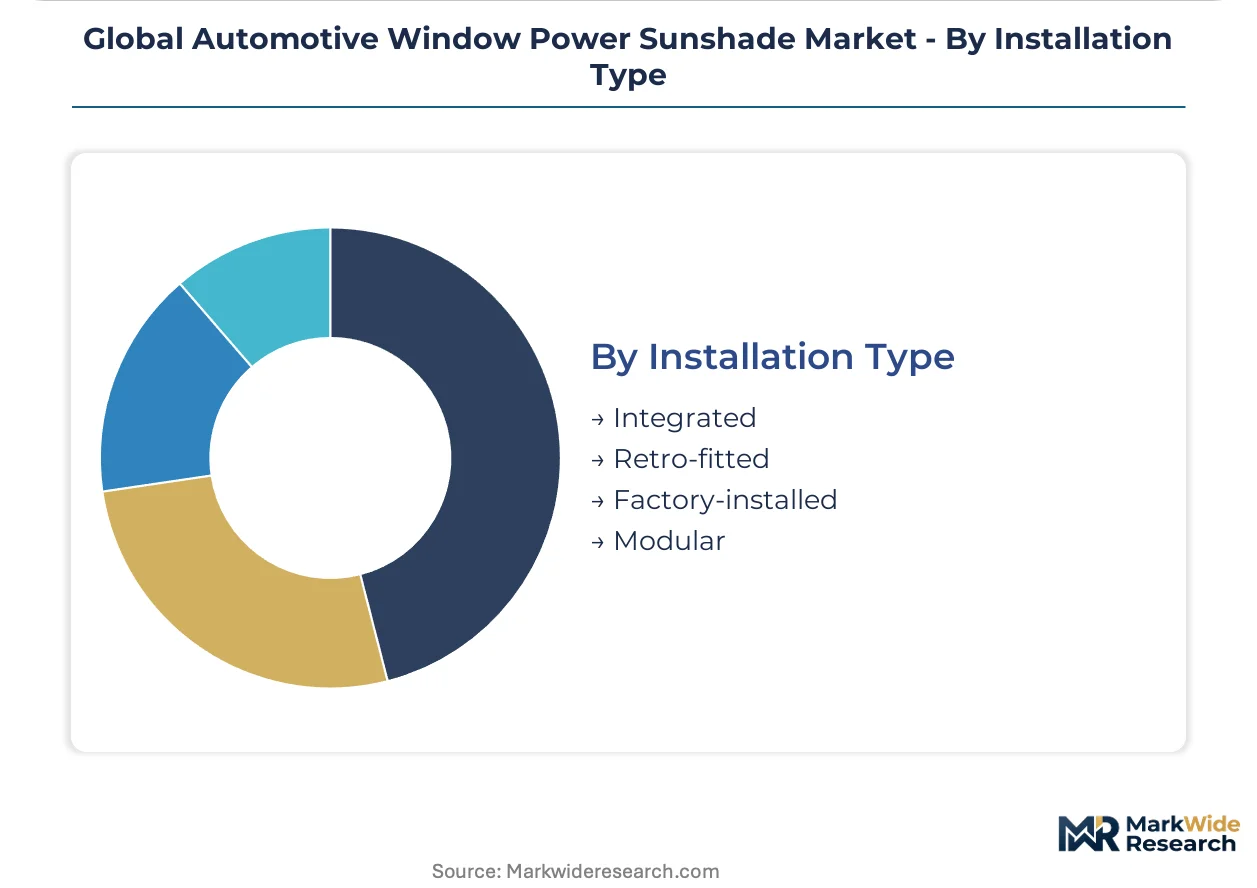
Installation Type:
Integration depth determines electromagnetic compatibility burden and qualification timeline.
- Factory-installed:Systems specified at vehicle platform conception with embedded CAN-bus architecture. EPA vehicle efficiency testing protocols and Japan's METI electromagnetic compatibility benchmarks extend qualification periods but lock in multi-year supply agreements.
- Integrated:Glazing-system-embedded configurations where shade mechanisms merge with window regulator assemblies.
- Retro-fitted:Post-production installations through independent service networks. CAN-bus architecture mismatches with older vehicle electrical systems complicate deployment despite growing certified installer programs.
- Modular:Self-contained units enabling field replacement without glazing disassembly.
Factory-installed configurations hold volume concentration; integrated systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones are concentrating power sunshade manufacturing investment. German automotive clusters leverage EU Green Deal compliance frameworks. India's PLI corridors attract assembly localization for cost-optimized supply.
Germany
Luxury electric vehicle fleets in Munich and Stuttgart drive factory-installed power sunshade specification. EU Green Deal cabin thermal efficiency mandates compel OEMs to motorize rear and side window shading as standard equipment. Baden-Württemberg's electromechanical actuator suppliers anchor specialized component sourcing for premium glazing systems.
China
Domestic OEMs in Jiangsu and Zhejiang provinces accelerate motorization to meet MIIT energy consumption standards. The regulation now captures cabin solar heat gain in official vehicle efficiency ratings. Yangtze River Delta automotive clusters generate localized demand for DC motor and control module integration.
United States
EPA vehicle efficiency testing protocols shape thermal management bundling across Detroit and Southern California design centers. Corporate fleet procurement models alter shade system specification patterns toward standardized comfort packages. Texas and Michigan assembly corridors integrate power sunshades into platform efficiency compliance frameworks.
India
Automotive PLI scheme incentives attract power sunshade assembly investment in Maharashtra and Gujarat corridors. Domestic manufacturers respond to localized thermal efficiency requirements through certified installer network expansion. Tamil Nadu vehicle assembly clusters source cost-optimized polyester substrates for mid-tier platform integration.
Japan
METI electromagnetic compatibility testing protocols extend product qualification timelines for electromechanical shade systems. Premium electric vehicle cabins in Kanto and Kansai regions demand acoustic-damping fabric composites. Nagoya-area glazing suppliers integrate CAN-bus control modules into thermal management architectures.
Global Automotive Window Power Sunshade Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across factory-installed and aftermarket channels. The vendor base spans electromechanical component fabricators, glazing system integrators, and regional assembly specialists. Three strategic archetypes dominate: German premium-tier system integrators, Asian manufacturing-scale producers, and India-focused cost-optimized assemblers. Competitive moves concentrate on backward integration into DC motor sourcing and strategic partnerships with electrochromic glazing developers.
Among Germany-based system integrators, BOS GmbH and Co. KG and Webasto SE occupy positions anchoring premium OEM supply chains. Ashimori Industry Co. Ltd. exemplifies Asian manufacturing-scale specialization in power-operated shade mechanisms. These three represent the archetype spectrum from European premium integration to Asian volume production.
| Leading Market Players |
|---|
| BOS GmbH and Co. KG |
| Ashimori Industry Co. Ltd. |
| Inalfa Roof Systems Group B.V. |
| Eclipse SunShades |
| CIE Automotive SA |
| Webasto SE |
| Macauto Industrial Co. Ltd. |
| Vaccess India Pvt. Ltd. |
| Inteva Products LLC |
| Others |
Supply Flow & Price Mechanics
German luxury OEM procurement concentration anchors contract-based long-term offtake as the dominant pricing model across factory-installed power sunshade supply chains. Thermal management bundling with electrochromic glazing and AI-driven HVAC systems compresses variant complexity while sustaining premium capture for acoustic-damping fabric composites.
Pricing Analysis
Short lead-time premiums for MIIT-compliant DC motor and control module sourcing separate urgent procurement from standard-cycle contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with polyester substrates facing cost compression from rare earth magnet price fluctuations. OEM platform engineers show lowest price sensitivity for REACH-compliant thermoplastic elastomer formulations, while aftermarket distributors in India's PLI corridors exhibit highest sensitivity to landed cost fluctuations.
Supply Chain Analysis
Japan's METI electromagnetic compatibility certification and EPA vehicle efficiency validation gate supplier qualification timelines, extending product acceptance periods. Manufacturing concentrates in Germany's Baden-Württemberg electromechanical cluster, China's Yangtze River Delta automotive corridor, and Japan's Nagoya-area glazing supplier networks. The supply chain draws from rare earth magnet feedstocks, semiconductor components for CAN-bus modules, and polymer-composite fabric substrates. Single-source vulnerability in specialized actuator sourcing creates structural risk. Distribution runs through Tier 1 supplier integration into OEM platform engineering channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power sunshade supply remains constrained by qualified DC motor and electromagnetic compatibility certification capacity, propping pricing for certified suppliers against uncertified competitors.
For Market Incumbents: Anchor multi-year supply agreements with German luxury OEMs through captive control module production in Baden-Württemberg. Deepen backward integration into rare earth magnet sourcing to defend margins against semiconductor shortage recurrence. Prioritize REACH-compliant thermoplastic elastomer substrate qualification to preempt PVC reformulation disruption. For New Entrants and Emerging Players: Smart fabric substrates with embedded photovoltaic sensing layers offer technology-first wedge into premium electric vehicle panoramic roof applications. Target India's Maharashtra and Gujarat PLI corridors for cost-optimized polyester substrate assembly serving domestic OEM thermal efficiency requirements. Pursue certified installer network partnerships as the primary go-to-market channel for retrofit channel expansion. For Investors and Strategic Acquirers: The window for entry favors Asian manufacturing-scale specialists with established Yangtze River Delta production footprints and MIIT certification pathways. Long-term viability hinges on electrochromic glazing convergence and vehicle thermal management AI integration capability. Watch for MIIT energy consumption standard tightening as the inflection signal for accelerated motorization mandates across China's domestic OEM platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into DC Motor Sourcing | Captive rare earth magnet supply secures margin stability against commodity volatility in German premium supply chains. |
| Smart Fabric Substrate Development | Photovoltaic sensing layer integration unlocks bundled system opportunities with electrochromic glazing developers. |
| India PLI Corridor Manufacturing Footprint | Localized assembly in Maharashtra and Gujarat reduces landed cost for cost-optimized polyester substrate programs. |
| REACH-Compliant Material Reformulation | Thermoplastic elastomer qualification preempts ECHA phthalate restriction enforcement across European OEM specifications. |
| Certified Installer Network Expansion | Retrofit channel control captures aftermarket revenue streams beyond factory-fit configurations in India's emerging vehicle parc. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distribution channel heads, and electromagnetic compatibility testing laboratory directors. Bottom-up vehicle production database triangulation with top-down thermal management system content modeling validated segmentation outputs across the projection horizon.
Granularity-level modeling captured power sunshade adoption by vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from fitted growth curves applied to platform-level motorization penetration assumptions, with MIIT energy consumption standard evolution and EU Green Deal cabin efficiency mandate timelines as key forecast inputs.
Several conditions sit outside the modeled scope, including speculative electrochromic glazing cost curves and unannounced OEM platform cancellations. Forecasts reflect documented assumptions about regulatory enforcement timing and rare earth magnet supply stabilization. A model refresh is warranted upon material change in MIIT thermal efficiency test cycle implementation or ECHA REACH substrate restriction expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Automotive Fridge Market
Automotive Interior & Exterior
United States Car Bumper Guard Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Automotive Cups and Glass Holder Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Global Automotive Anti Vibration Mounting Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Car Organizer Market