
 Global Automotive Mirror Replacement System Market | 2026-2036
Global Automotive Mirror Replacement System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Mirror Replacement System Market Intelligence
Market Context
Polycarbonate substrate usage is shifting from glass in mirror replacement systems as weight-reduction mandates tighten across vehicle platforms. Gentex Corporation leverages its electrochromic intellectual property to sustain premium positioning in auto-dimming architectures. Magna International anchors North American supply through integrated module assembly and direct OEM relationships. Samvardhana Motherson Reflectec dominates cost-optimized power mirror segments across European and Asian vehicle programs.
Technical Definition and Segment Structure
Automotive mirror replacement systems comprise electromechanical and electrochromic assemblies that adjust field of view, reduce glare, or integrate blind-spot monitoring through embedded sensors and heating elements. These units serve the primary commercial purpose of maintaining regulatory visibility compliance while supporting advanced driver-assistance functionality. Auto-dimming mirrors command the dominant margin pool due to electrochromic gel chemistry and proprietary control circuitry, while sensor-based configurations represent the fastest-growing technology segment as camera fusion requirements expand. Aftermarket suppliers occupy a structurally fragmented channel where price competition intensifies against OEM-captive distribution.
Regulatory Framework and Outlook
NHTSA visibility standards, UNECE Regulation 46, and EU General Safety Regulation collectively determine mirror replacement system design, testing protocols, and market access conditions across major vehicle-producing jurisdictions. Camera-monitor system exemptions under evolving UNECE frameworks are reshaping product roadmaps and R&D allocation for traditional mirror suppliers. Stakeholders must monitor regulatory divergence between camera-permissive European frameworks and more restrictive North American interpretations when allocating platform development resources.
Market Dynamics
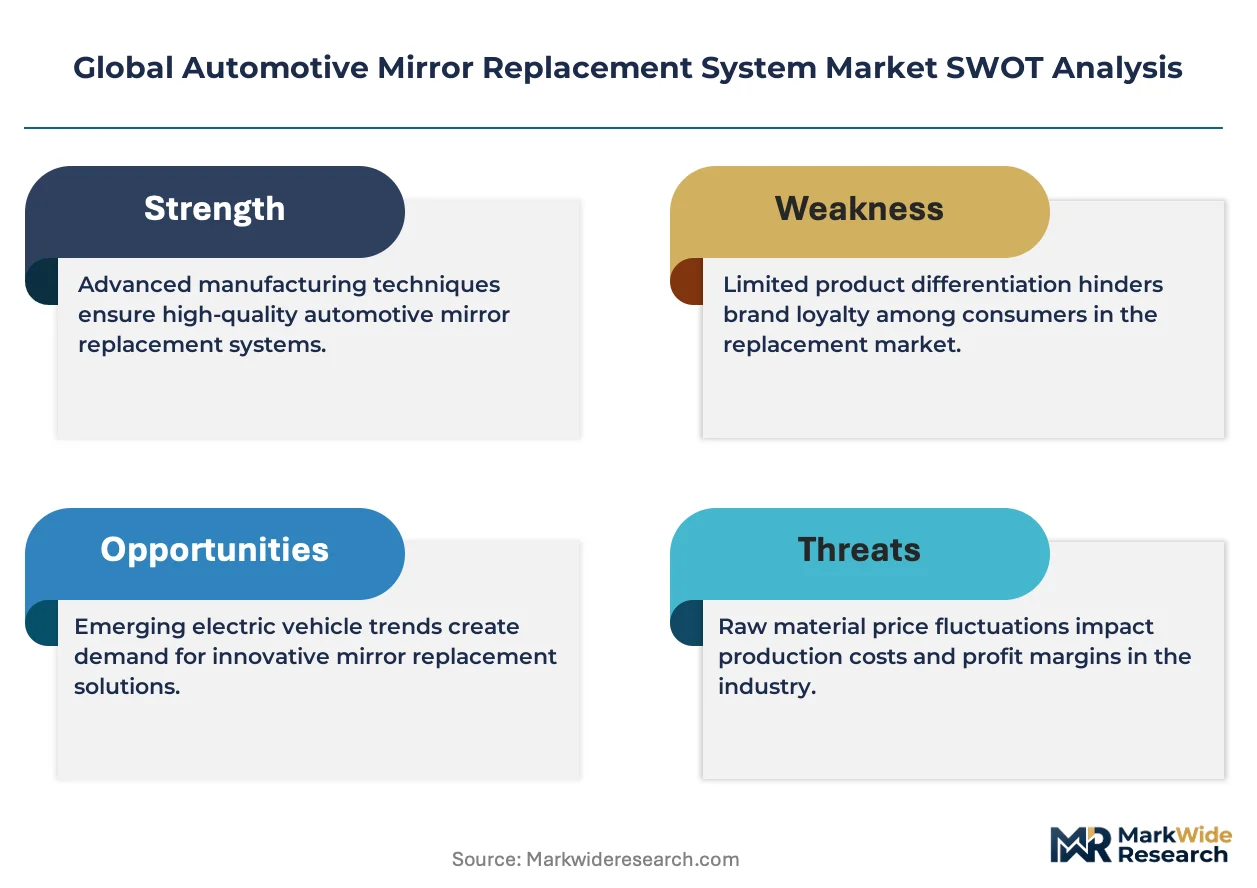
Camera-monitor system exemptions under evolving UNECE frameworks are compressing development timelines for traditional mirror suppliers while fragmenting R&D allocation across electrochromic and digital display architectures.
Growth Catalysts
- EU General Safety Regulation:Mandates for expanded blind-spot visibility zones are accelerating sensor integration into mirror modules across European vehicle platforms.
- Polycarbonate substrate adoption:Weight-reduction requirements in electric vehicle programs are displacing glass substrates in exterior mirror housings and interior assemblies.
- China's NEV production concentration:Premium passenger vehicle output in Chinese manufacturing clusters is pulling auto-dimming module procurement from global tier-one suppliers.
Market Restraints
- Electrochromic gel supply concentration:Proprietary chemistry control by a limited supplier base in North America creates input cost volatility for auto-dimming architectures.
- NHTSA visibility standard friction:Restrictive interpretations of camera-monitor system compliance are delaying product roadmaps for digital mirror replacements in the United States.
- Glass-to-plastic conversion limits:Optical clarity degradation in polycarbonate substrates constrains application in high-precision exterior mirror segments.
Strategic Opportunities
- Aftermarket retrofit channel:Sensor-based mirror upgrade kits for legacy vehicle fleets represent underpenetrated revenue pools in Germany and United States service networks.
- Camera fusion convergence:Integration of blind-spot monitoring with surround-view systems is unifying control electronics into single-module architectures.
- India PLI scheme extension:Automotive component manufacturing incentives are attracting power mirror assembly investment for export-oriented supply.
Industry Challenges
- Electrochromic process engineering talent:Scarce expertise in gel chemistry and thin-film deposition is constraining production scale-up for premium auto-dimming lines.
- UNECE R46 certification timelines:Extended homologation cycles for camera-monitor variants are compressing product launch windows against platform deadlines.
- Legacy vehicle electrical architecture integration:Backward compatibility requirements for CAN bus protocols are complicating sensor-based mirror deployment in model-year transition programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Mirror Replacement System Market |
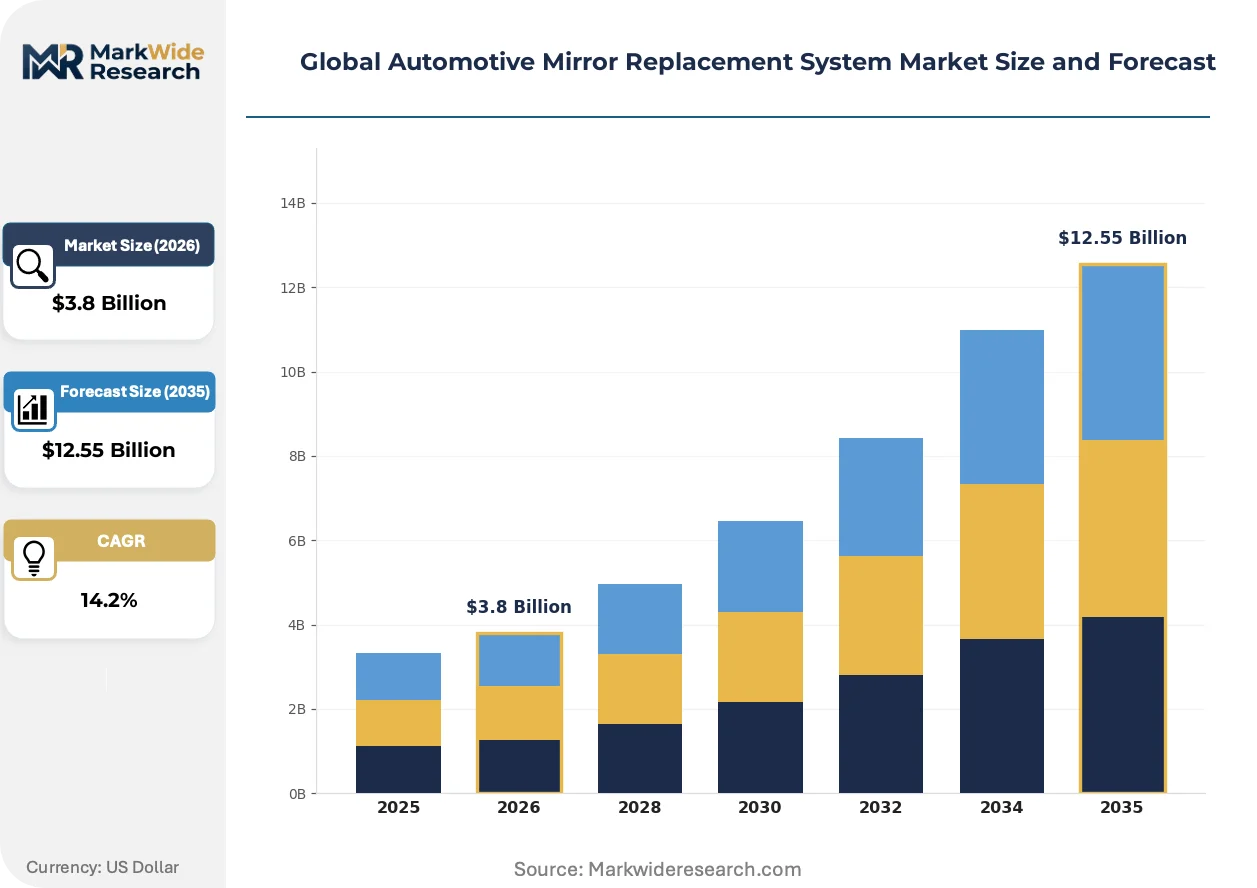
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Mirrors, Power Mirrors, Heated Mirrors, Auto-Dimming Mirrors, Blind Spot Detection Mirrors Technology: Electromechanical, Electrochromic, OLED, Sensor-Based, Thermoelectric Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Off-Road Vehicles, Specialty Vehicles End User: OEMs, Aftermarket Suppliers, Repair Shops, Vehicle Assemblers |
| Companies Covered | Gentex Corporation, Magna International Inc., Ficosa International SA, Samvardhana Motherson Reflectec, Murakami Corporation, SL Corporation, MEKRA Lang, Ichikoh Industries, SMR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Mirror Replacement System Market Strategic Shifts & Innovations
Digital display technologies are converging with traditional mirror functions, creating hybrid architectures that satisfy regulatory visibility mandates while enabling advanced driver-assistance feature integration.
Electrochromic auto-dimming technology is unifying glare reduction with embedded LED indicator and homelink functionality in single-glass assemblies. Luxury and premium OEM programs in Germany and United States are standardizing these consolidated modules at accelerated refresh cycles. This integration is compressing the addressable market for discrete component suppliers while elevating barrier-to-entry for new electrochromic entrants.
UNECE Regulation 46 amendments are permitting camera-monitor system exemptions for rearward visibility in European type approvals. Mirror suppliers are reallocating engineering resources toward display and image-processing competencies alongside traditional glass and housing expertise. The regulatory divergence between camera-permissive European frameworks and restrictive NHTSA interpretations is forcing dual-track development strategies.
Fleet operators and leasing companies are compressing replacement cycles for damaged mirror assemblies through consolidated procurement contracts with tier-one module suppliers. Direct OEM-captive distribution is displacing fragmented aftermarket channels for sensor-integrated configurations in commercial vehicle segments. This concentration is most visible in United States long-haul trucking and German premium passenger leasing programs.
Global Automotive Mirror Replacement System Market Segmentation
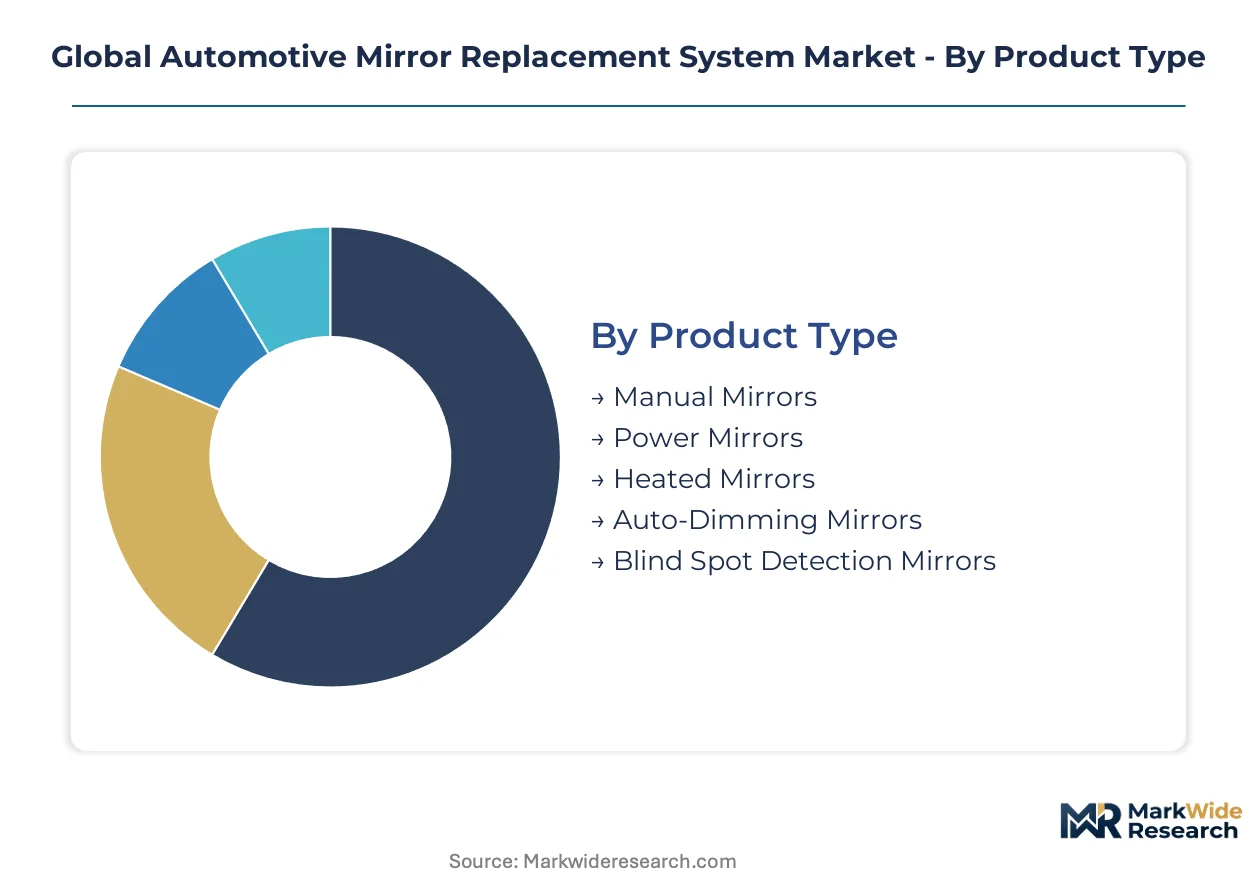
Mirror replacement cycles vary sharply across vehicle categories and technology tiers, creating distinct procurement patterns for OEMs and aftermarket channels. Upgrade trajectories from manual to sensor-integrated modules are compressing replacement intervals in premium passenger segments while extending them in commercial fleets.
Product Type:
Replacement-cycle timing differs substantially across mirror categories, with technology sophistication dictating both failure modes and upgrade incentives.
- Auto-Dimming Mirrors:Electrochromic gel assemblies with proprietary control circuitry command extended replacement intervals due to sealed construction and minimal moving parts. Demand concentrates in German and United States premium passenger programs where glare reduction is standard equipment, though gel chemistry supply constraints create procurement volatility.
- Blind Spot Detection Mirrors:Integrated radar or ultrasonic sensor modules with LED warning indicators represent the steepest upgrade trajectory as NHTSA and UNECE visibility mandates tighten. Procurement accelerates in Chinese NEV manufacturing clusters where camera fusion requirements are standardizing across mid-tier vehicle platforms.
- Power Mirrors:Electromechanical actuator assemblies with position memory functionality serve cost-optimized vehicle programs across European and Asian markets.
- Heated Mirrors:Resistive element configurations for defrosting and demisting address cold-climate aftermarket demand in Canada and Nordic countries.
- Manual Mirrors:Basic mechanical adjustment mechanisms persist in entry-level two-wheeler and emerging market vehicle segments where cost minimization dominates procurement.
Auto-Dimming Mirrors sit at the top of the volume ranking, with Blind Spot Detection Mirrors climbing the fastest.
Technology:
Cost tier stratification separates mature electromechanical platforms from emerging digital architectures, with R&D allocation shifting toward sensor fusion and display integration.
- Sensor-Based:Multi-modal detection systems combining radar, camera, and ultrasonic inputs for surround-view functionality are unifying control electronics into single-module designs. Demand is accelerating in United States and German premium OEM programs where ADAS feature bundling is standardizing replacement specifications.
- Electrochromic:Thin-film gel deposition technology with automatic light-sensing circuitry sustains premium positioning through proprietary chemistry control. Production concentrates in North American supplier facilities where process engineering expertise constrains scale-up for new market entrants.
- Electromechanical:Motor-driven positioning systems with manual override capability serve volume vehicle platforms across cost-sensitive segments.
- OLED:Digital display substrates for camera-monitor system implementations are gaining regulatory traction under evolving UNECE frameworks.
- Thermoelectric:Solid-state heating and cooling elements for climate-controlled mirror surfaces address niche luxury applications.
Electromechanical configurations retain the broadest installed base, while Sensor-Based architectures are expanding most quickly.
Application:
Customer type and vehicle duty cycle determine replacement frequency, with commercial fleet operators pursuing consolidated procurement contracts distinct from individual owner behaviors.
- Passenger Vehicles:Private owner replacement cycles average 7-10 years for damage-related events, though technology upgrade incentives compress this interval in premium segments. Procurement concentrates in Chinese, German, and United States manufacturing clusters where auto-dimming and sensor-based modules are standardizing.
- Commercial Vehicles:Fleet operators and leasing companies are consolidating mirror assembly procurement through direct tier-one contracts, displacing fragmented aftermarket channels. United States long-haul trucking and German logistics fleets are standardizing sensor-integrated configurations with compressed replacement cycles for damage-prone exterior units.
- Two-Wheelers:Manual mirror assemblies dominate cost-optimized production across Indian and Southeast Asian markets.
- Off-Road Vehicles:Vibration-resistant housing designs with reinforced mounting points address construction and agricultural equipment requirements.
- Specialty Vehicles:Custom mirror configurations for emergency services and military applications require specialized homologation pathways.
Passenger Vehicles command the largest replacement volume, with Commercial Vehicles gaining share fastest through fleet consolidation.
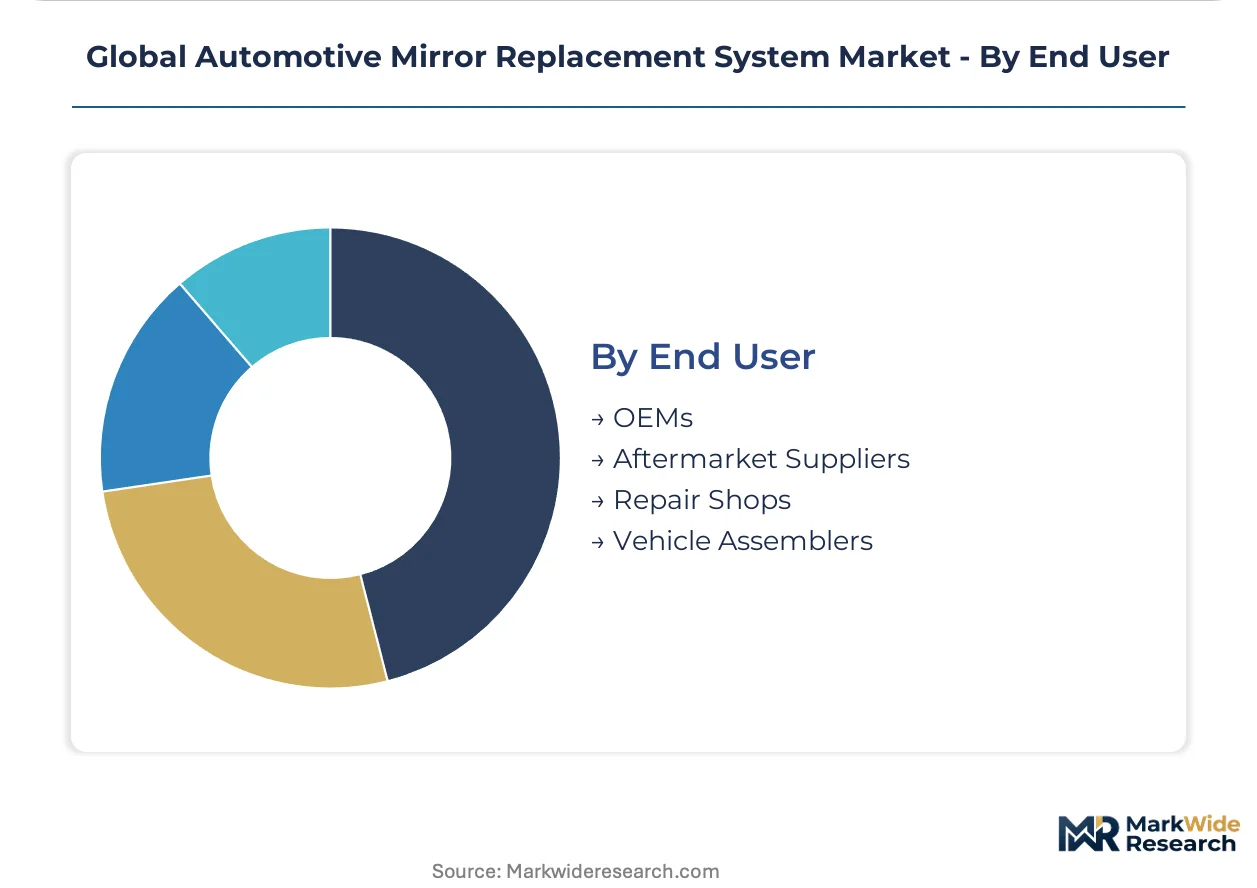
End User:
Supply concentration varies sharply between OEM-captive distribution and fragmented aftermarket channels, with margin structures reflecting channel control intensity.
- OEMs:Direct procurement relationships with integrated module suppliers anchor North American and European supply, with specification control residing in platform engineering teams. Auto-dimming and sensor-based configurations are standardizing at accelerated refresh cycles in German and United States premium programs.
- Aftermarket Suppliers:Fragmented distribution networks serve legacy vehicle fleets with price-competitive manual and power mirror assemblies, though sensor-based upgrade kits represent underpenetrated revenue pools in Germany and United States service networks.
- Repair Shops:Independent service providers source through distributor intermediaries with limited technical support for integrated electronic modules.
- Vehicle Assemblers:Contract manufacturing arrangements for emerging market production leverage localized power mirror assembly under India's PLI scheme incentives.
OEMs dominate procurement value, with Aftermarket Suppliers climbing fastest through sensor-based upgrade penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta manufacturing corridor concentrates the world's densest assembly capacity for sensor-integrated mirror modules, pulling procurement volumes from European and North American tier-one suppliers as NEV platform launches accelerate.
China
Premium passenger vehicle output in Shanghai and Jiangsu provinces is standardizing auto-dimming and blind-spot detection modules across mid-tier electric vehicle platforms. MIIT's GB standards for intelligent vehicle components are mandating expanded visibility zones in new type approvals. Suzhou and Ningbo industrial clusters host concentrated mirror module assembly operations serving domestic OEMs and export programs.
Germany
Luxury OEM engineering centers in Munich and Stuttgart are consolidating electrochromic and sensor-based specifications at accelerated refresh cycles. KBA enforcement of EU General Safety Regulation blind-spot mandates is driving technology upgrade penetration across vehicle fleets. Baden-Württemberg's supplier corridor anchors European module development for camera-monitor system transitions.
United States
Detroit Three platform engineering teams are standardizing auto-dimming architectures across light truck and premium passenger segments despite NHTSA's restrictive camera-monitor system interpretations. NHTSA visibility standard friction is delaying digital mirror replacements while sustaining demand for electrochromic assemblies. Michigan and Ohio manufacturing belts concentrate North American module assembly capacity.
Japan
Keiretsu supply relationships in Aichi and Kanagawa prefectures are integrating mirror modules with surround-view camera systems for domestic OEM export programs. METI's automotive technology roadmaps are supporting electrochromic process development for next-generation glare reduction. Nagoya industrial zone maintains specialized thin-film deposition expertise for premium auto-dimming production.
India
Power mirror assembly investment is accelerating under PLI scheme incentives for export-oriented component manufacturing. BIS certification requirements for automotive electronics are elevating quality thresholds for domestic and export-bound production. Tamil Nadu and Gujarat automotive corridors are attracting tier-one supplier facility establishment for regional supply.
Global Automotive Mirror Replacement System Market Key Industry Players
Global majors compete with regional champions across technology tiers and geographic account control, producing a stratified structure where proprietary electrochromic chemistry and integrated sensor fusion capabilities separate premium positioning from cost-optimized supply. Consolidation concentrates around North American and European headquarters locations, while Asian manufacturing scale sustains volume competition. Three archetypes dominate: integrated module suppliers with direct OEM relationships, electrochromic chemistry specialists with sealed intellectual property, and regional power mirror fabricators serving cost-sensitive vehicle programs. Competitive moves center on backward integration into gel chemistry production and strategic partnerships for camera fusion software.
Among North American headquartered suppliers, Gentex Corporation exemplifies the electrochromic specialist archetype through its proprietary control circuitry positioning, while Magna International Inc. represents integrated module assembly with direct OEM account anchoring. Samvardhana Motherson Reflectec occupies the regional scale fabricator tier across European and Asian cost-optimized segments. These three company structures illustrate the competitive spectrum from chemistry-controlled premium positioning through vertically integrated module supply to geographically distributed volume manufacturing.
| Leading Market Players |
|---|
| Gentex Corporation |
| Magna International Inc. |
| Ficosa International SA |
| Samvardhana Motherson Reflectec |
| Murakami Corporation |
| SL Corporation |
| MEKRA Lang |
| Ichikoh Industries |
| SMR |
| Others |
Cost & Logistics Intelligence
EU General Safety Regulation blind-spot mandates gate qualified supply for premium-tier mirror modules, restricting electrochromic gel sourcing to North American chemistry specialists while OEM procurement contracts enforce volume-scaled pricing tiers that exclude fragmented aftermarket channels.
Pricing Analysis
Input-cost pass-through from proprietary electrochromic gel chemistry drives pricing stratification across premium, standard, and economy tiers. Certification under UNECE R46 and NHTSA visibility standards separates validated OEM supply from uncertified aftermarket alternatives. Cost compression in power mirror segments intensifies as polycarbonate substrate adoption displaces glass in volume vehicle programs. Fleet operators and leasing companies exhibit lowest price sensitivity due to consolidated procurement contracts, while independent repair shops face acute margin pressure from distributor intermediaries.
Supply Chain Analysis
Electrochromic gel supply rests on concentrated North American specialty chemistry producers, constraining scale-up for new auto-dimming entrants. Mirror module assembly draws from polycarbonate resin feedstocks in Germany and China, with sensor fusion electronics sourcing from South Korean and Japanese semiconductor fabricators. Single-source vulnerability in thin-film deposition equipment creates procurement risk for premium mirror lines. Distribution runs through direct OEM-captive channels for sensor-integrated configurations, while fragmented distributor networks serve legacy aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where UNECE camera-monitor exemptions in Europe contrast with NHTSA restrictive interpretations, creating dual-track R&D cost differentials that favor European-bound product development.
For Market Incumbents: Cement electrochromic chemistry control through captive gel production investment in North American facilities, defending against sensor-based substitution threats from camera-monitor architectures. Expand module assembly capacity in China's Yangtze River Delta to capture NEV platform procurement pull from domestic OEMs. For New Entrants and Emerging Players: Launch via aftermarket sensor-based upgrade kits targeting legacy vehicle fleets in Germany and United States service networks, exploiting underpenetrated revenue pools outside OEM-captive distribution. Prioritize blind-spot detection mirror penetration in Chinese mid-tier electric vehicle platforms where camera fusion standardization accelerates replacement demand. For Investors and Strategic Acquirers: Roll-up economics work for regional power mirror fabricators because fragmented aftermarket channels lack technical support infrastructure for integrated electronic modules. Long-term viability hinges on backward integration into gel chemistry or forward integration into camera fusion software. Watch NHTSA camera-monitor rulemaking as the critical inflection signal for digital mirror replacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrochromic Gel Production | Captive chemistry supply secures margin control against proprietary North American supplier concentration. |
| Camera Fusion Software Partnership | Integration with surround-view systems unifies control electronics into single-module architectures for German premium OEMs. |
| China NEV Platform Standardization | Direct OEM relationships in Shanghai and Jiangsu manufacturing clusters anchor sensor-integrated module procurement. |
| Aftermarket Sensor Upgrade Kit Launch | Service network penetration in United States and Germany exploits fragmented legacy fleet replacement demand. |
| UNECE R46 Certification Investment | European type approval acceleration enables camera-monitor system exemptions ahead of restrictive NHTSA timelines. |
Research Approach
Direct dialogue with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers grounded qualitative findings, validated against vehicle production databases, IHS Markit registration data, customs trade records, and SEC filings from listed automotive component suppliers. Bottom-up and top-down triangulation reconciled segment-level volume estimates with aggregate market sizing.
The analytical lens combined bottom-up content-per-vehicle modeling with top-down OEM procurement contract analysis across the projection horizon. Segmentation dimensions included vehicle class, propulsion architecture, mirror technology tier, and regional production cluster. CAGRs derived from fitted growth curves applied to technology adoption S-cycles, with electric vehicle penetration rates and regulatory mandate enforcement timelines as automotive-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NHTSA camera-monitor rulemaking reversals or electrochromic gel supply disruptions. Forecasts reflect documented assumptions regarding UNECE R46 amendment timelines and Chinese NEV production concentration. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Steering Column Locks Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market
Automotive Safety and Security Systems
Automotive Inspection Tunnels Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Automotive Brake System Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market